

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Projects Worldwide Anti-Radiation Clothing Market to Expand at a 7.03% CAGR During 2026–2032

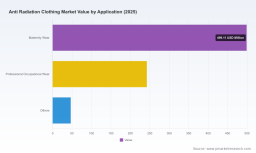
Worldwide Anti-Radiation Clothing Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases an executive briefing drawn from our forthcoming Worldwide Anti-Radiation Clothing Market report (base year: 2025; historical: 2020–2025; forecast: 2026–2032). The global market has expanded from roughly USD 585 million in 2020 to about USD 789 million in 2025 and is forecast to continue growing to an estimated USD 1,266 million by 2032, reflecting a compound annual growth rate of 7.03% over the 2026–2032 forecast window. For executives planning investment, product strategy, or procurement in 2026, these macro trajectories and the practical frameworks we provide are immediately actionable — while the full report contains the granular segmentation tables and decision-grade datasets that support tactical execution.
Bifurcated Covered Stent Market
Why this report matters for 2026
-
Transition point for buyers and suppliers: 2026 is the inflection year where material innovation, regulatory scrutiny, and diversified end‑use demand converge to change procurement and product roadmaps. Our report translates that convergence into discrete, time‑bound actions for R&D, sourcing, and marketing teams.
Worldwide Flip Chip CSP Market -
Investment calibration: with the market growing at a mid‑single-digit CAGR into the early 2030s, capital allocation decisions must balance steady recurring demand (medical and occupational protective apparel) against episodic, higher‑value opportunities (specialty suits for aerospace and emergency response). We show how to size those bets without exposing sensitive client-level data in this briefing.
Worldwide Lip Makeup Market -
Regulation and certification as market enablers: standards and device classifications will determine market access and procurement cycles; alignment with these frameworks is a prerequisite for growth in regulated channels.
Key market dynamics and growth drivers
-
Persistent medical demand and evolving occupational use-cases: healthcare imaging and interventional suites remain steady anchors. Parallel growth is driven by new professional use‑cases where targeted attenuation and lighter garments are required for extended wear.
-
Material-led product differentiation: the shift from traditional lead to lead‑free composites (tungsten, bismuth, antimony blends) is reshaping product performance and user acceptance. These alternatives can reduce garment weight substantially — typically in the 30–50% range versus equivalent lead products — enabling new form factors and new channels.
-
Standards and regulatory gating: internationally recognized standards (e.g., IEC 61331‑1) and device classifications (such as FDA’s treatment of radiation-attenuating garments) continue to be both market levers and barriers; compliance accelerates institutional purchasing while absence of certification constrains access to large buyers.
-
Moderate market concentration: leading players capture a meaningful share of the market, but the industry retains multiple viable niches. Measured concentration metrics indicate room for both consolidation plays and specialist entrants that focus on specific use‑cases or materials.
-
Risk and safety messaging: public health guidance confirming there is no clothing that provides complete protection against all forms of ionizing radiation increases demand for solution‑specific messaging and validated performance claims rather than generic protection claims.
What the full report contains — practical, executable content
PW Consulting’s full market study is designed as a working tool for management teams. Highlights include:
-
Market sizing and forward-looking scenario models: comprehensive base and scenario forecasts (2026–2032) with sensitivity analyses that stress-test demand across regulatory outcomes, raw material price shocks, and adoption curves.
-
Go‑to‑market playbooks: channel strategies for medical, occupational, and specialist aerospace/emergency response buyers; distributor partner profiles; sample procurement RFIs and commercial contracting templates.
-
Technology and material roadmaps: patent landscaping, supplier capability matrices, and a materials cost‑performance dashboard to help product teams prioritize composites and fiber technologies.
-
Regulatory and standards matrix: mapping of global certification requirements, clinical validation protocols, and routes to market for medical device classification versus general protective apparel.
-
Competitive and M&A intelligence: vendor scorecards, capability gaps, strategic fit analyses, and an acquisition target shortlist for buyers seeking inorganic growth.
-
Supply chain resilience playbook: contingency planning for scarce raw materials, logistics stress testing, supplier hedging strategies, and contract clauses to link price and performance.
-
Operational checklists: product validation protocols, testing labs checklist (including IEC-compliant test criteria), and quality management KPIs tailored to protective apparel manufacturing.
Competitive landscape — what leading vendors signal for strategy
The market’s competitive set combines specialist innovators with established medical‑supply manufacturers. A few illustrative company profiles and recent developments are instructive for strategy:
-
StemRad (Israel): a technology‑led innovator focused on selective shielding in high‑risk applications. Their validated AstroRad vest and first‑responder 360 Gamma suit demonstrate how mission‑grade performance claims combined with external validation (e.g., aerospace program certifications) can create premium product lines and open non‑traditional channels.
-
Radiation Protection Products (U.S.): an established medical apparel manufacturer that recently refreshed its product portfolio with lighter, more flexible lead‑free aprons. This kind of iterative product innovation suggests a path for incumbents to defend share through material swaps and ergonomics rather than only price competition.
-
Barrier Technologies (U.S.): a specialist in lightweight designs (Zero‑Gravity portfolio) that uses trade‑show visibility to accelerate adoption among clinicians — a reminder that targeted engagement at professional conferences remains a high‑ROI demand generation tactic.
-
Infab Corporation, MarShield, Ray‑Bar Engineering: these firms represent breadth across medical and industrial shielding, custom composites, and barrier solutions. Their presence underscores fragmentation in product form factors and the opportunity for vertically integrated players to capture higher margins via custom material compounds and contract manufacturing.
Recent proof points — product certifications and new launches — indicate two actionable themes: (1) certification and third‑party validation materially improve procurement momentum in institutional channels; and (2) ergonomics and weight reduction drive adoption among frontline users. Both themes should inform product roadmaps and commercial messaging in 2026.
Strategic implications and recommended priorities for 2026
We recommend a four‑pillar approach for firms planning strategic moves next year:
-
Invest selectively in materials and ergonomics. Prioritize R&D that targets a 30–50% perceived weight improvement via lead‑free composites while maintaining IEC‑level attenuation across target energy bands. Build a prototype and validation timeline that aligns with procurement cycles of major hospital systems and emergency services.
-
Certify early and tell the story. Plan for IEC and, where applicable, medical device registrations. Certification accelerates access to regulated channels and supports premium pricing. Use third‑party validation in all sales collateral for institutional buyers.
-
Design channel plays by buyer archetype. Separate strategies for medical imaging departments, occupational safety buyers, and specialty aerospace/emergency customers. For each archetype, articulate total cost of ownership, training requirements, and lifecycle replacement metrics.
-
Securitize supply chains. Given the reliance on specialized composite inputs and the potential for raw material price volatility, build supplier redundancy, long‑lead inventory buffering, and contractual hedges. Our supplier map and price sensitivity models in the full report make these decisions executable.
KPIs and near‑term signals to monitor in 2026
-
Certification milestones achieved (IEC and applicable national device registrations).
-
Adoption velocity in institutional tenders and number of hospitals/clinics transacting on new lead‑free SKUs.
-
Material cost trends for tungsten/bismuth/antimony blends and announced capacity expansions by composite producers.
-
Competitor product launches and trade‑show visibility (e.g., major radiology conferences) as leading indicators of commercial focus.
Concluding assessment
The anti‑radiation clothing market is no longer a static, commodity domain. It is evolving into a differentiated landscape where materials science, regulatory alignment, and channel strategy determine winners. With the market projected to expand meaningfully from its 2025 base toward the early 2030s and with moderate concentration among leading suppliers, 2026 will reward firms that couple validated product advances with disciplined go‑to‑market execution.
PW Consulting’s full report synthesizes the granular data, validated supplier and buyer intelligence, and tactical playbooks required to execute those moves. This briefing offers the strategic contours — the full dataset, segmentation tables, vendor scorecards, and executable templates are available in the complete study for teams that need to convert insight into 2026 operational plans.
For detailed analysis of this topic, please visit the official page: Worldwide Anti Radiation Clothing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com