

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: CMO Services Market Set to Expand at a 13.5% CAGR (2026–2032), New Report Finds
By pmarketresearch, 2026-08-18
CMO Services Market 2026: A Strategic Preview — Why This Report Will Shape Your 2026 Decisions
Executive summary
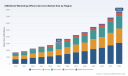
As organizations recalibrate growth playbooks in an AI-accelerated, outcome-driven era, PW Consulting’s new CMO Services Market report (base year 2025) delivers a tactical intelligence package designed for executive decision-makers. The global CMO services market has evolved from roughly USD 1.70 billion in 2020 to USD 3.20 billion in 2025, and our modelling projects expansion at a compound annual growth rate (CAGR) of 13.5% through the 2026–2032 forecast window. By 2026 the market crosses into the mid‑billion range and, under our baseline scenario, approaches USD 7.76 billion by 2032. That trajectory reflects structural changes in talent sourcing, technology adoption and buyer economics — all core considerations for CMOs, procurement leads and private equity sponsors evaluating go‑to‑market investments in 2026.
Carbon Neutral Carpet Tile Market
Why this matters for 2026 strategy
-
Talent arbitrage is now strategic. The accelerating adoption of fractional and interim senior marketing leadership allows organizations to access C‑suite capabilities without the fixed-cost burden of full‑time hires. Our market modelling shows this shift materially influences marketing operating models and long‑term cost baselines.
Three Piece Flanged Ball Valve Market -
AI is everywhere, but maturity is rare. Approximately three quarters of marketing organizations report some level of AI adoption, yet only a sliver have mature, repeatable implementations. That creates a strategic opening for advisory and fractional leaders who can translate AI capabilities into measurable revenue impact.
3D Braiding Machine Market -
Buyers demand outcome-linked engagements. Cost comparisons and performance benchmarks in our study indicate that firms using fractional CMO models often outpace peers in topline growth, reshaping how boards and PE sponsors evaluate marketing spend as a growth lever rather than a pure cost center.
What the report contains — operational, decision‑grade assets
The research is explicit in converting market insight into practitioner tools. Readers will find:
- Executive brief and 18‑month decision calendar for CMOs and procurement teams to prioritize hires, vendor pilot windows and budget reallocation.
- Scenario modelling (base, accelerated, and downside) driven by macro adoption curves and technology maturation timelines — including sensitivity to AI enablement and macroeconomic variability.
- Vendor selection framework and scorecard: objective criteria for assessing fractional CMO firms and integrated advisory partners across capabilities, delivery model, pricing transparency, regulatory competence and measurable KPIs.
- Commercial frameworks: modular contracting templates, outcome‑based pricing playbooks, and a practitioner’s guide to blending retained advisory with performance incentives.
- Implementation blueprints: 90/180/360‑day activation plans mapped to capability gaps (demand generation, product‑marketing alignment, PLG/SLG integration, and marketing operations modernization).
- AI adoption roadmap for marketing leaders: use cases prioritized by revenue impact, implementation complexity and data readiness, plus a vendor short‑list and governance checklist.
- Performance measurement pack: KPI scorecards and simple ROI models that translate marketing inputs into revenue outcomes and cashflow impact for CFO discussions.
- Case studies and anonymized benchmarks drawn from client engagements and market signals to illustrate typical uplift curves and risks.
Market dynamics: what our analysis reveals
-
Structural growth is robust. The overall market nearly doubled between 2020 and 2025 and, at a projected CAGR of 13.5% across 2026–2032, the services market will remain a high‑growth segment of the marketing ecosystem. Growth is being driven by three converging forces: the commoditization of tactical marketing execution, increased C‑suite comfort with flexible leadership models, and the monetization of AI‑enabled capabilities.
-
Fractional leadership is maturing. Public data and platform signals show rapid adoption of fractional leadership constructs — profiles referencing fractional roles have exploded over recent years — and organizations are increasingly treating fractional CMOs as strategic partners rather than stopgaps. Firms that institutionalize these relationships — through clear KPIs and contractual design — capture disproportionate value.
-
Performance delta matters. Our synthesis of sector studies and client datasets indicates materially stronger growth for companies that leverage experienced fractional CMOs and strategic advisory partners. This phenomenon is reinforcing buyer willingness to shift budget from headcount to flexible specialist engagements.
-
Competitive intensity remains low at the top. Market concentration metrics show a fragmented vendor base: the top three and top five providers account for relatively modest shares of total market activity, creating both opportunity and vendor selection risk for buyers seeking scale, specialization or regulatory depth.
Competitive landscape — key players and strategic moves
The vendor environment combines established fractional leadership specialists with newer growth engineering and AI‑first boutiques. Our report provides a comparable analysis of leading firms, highlighting positioning, sector focus and capability differentials. Selected strategic observations include:
-
Chief Outsiders: A broad fractional CMO platform with deep penetration of mid‑market and PE‑backed portfolios. Recent executive additions signal sharpened focus on AI‑enabled marketing transformation and sector diversification into healthcare and infrastructure — moves that read as deliberate steps to expand capability depth and enterprise credibility.
-
CMOx: A process‑oriented provider emphasizing repeatable frameworks for marketing function development and scalable growth. Their methodology appeals to organizations seeking to industrialize marketing practices rather than episodic advisory.
-
Kalungi: B2B SaaS specialists with strong playbooks around positioning and T2D3 growth mechanics — attractive to scaling software vendors that need GTM rigor and product‑led/ sales‑led integration.
-
NoGood and other growth engineering shops: Distinctive for high‑velocity experimentation and analytics‑first approaches, often the choice for growth teams prioritizing rapid hypothesis testing and optimization.
-
W‑2 embedded models and compliance‑focused firms: Several providers offer embedded leadership and compliance expertise for regulated industries, which is an important consideration for healthcare and financial services buyers.
Recent vendor developments — including targeted hires and service expansions — underscore a market in active consolidation by capability rather than price. Buyers should treat executive additions and service launches as leading indicators of vendor intent: are they deepening domain expertise, scaling delivery capacity, or simply broadening market messaging?
Practical implications and recommended actions for 2026
-
Prioritize outcome‑linked pilots. Run short, measurable engagements (90–180 days) with clear revenue or funnel KPIs. Use the report’s pilot template to set success thresholds and de‑risk longer commitments.
-
Design a blended operating model. Mix embedded leadership, fractional expertise and specialist execution partners to balance continuity and speed. The report’s org design scenarios provide prescriptive role definitions and handoff matrices.
-
Invest in AI governance before scale. With broad AI adoption but low maturity, companies that establish data, model and measurement guardrails now will capture disproportionate advantage when mature use cases emerge.
-
Use the vendor scorecard. Evaluate providers not just on CVs but on demonstrable playbooks, commercial alignment (risk‑reward split) and measurable ramp timelines. Our scorecard weights those dimensions for buyers across enterprise, PE and SME contexts.
-
Measure marketing as a growth lever. Translate marketing plans into cashflow outcomes; use the report’s ROI templates to make the case to treasury and the board.
How to use this release — the “trailer” approach
This bulletin demonstrates the depth and practical orientation of the full PW Consulting report while preserving proprietary segment tables, detailed vendor revenue splits and cell‑level forecasts — these are intentionally omitted here to protect analytical rigor and to ensure buyers access the complete dataset on our platform. The full report contains the benchmarking datasets, vendor scorecards, contracting templates and forecast scenarios that senior leaders need to operationalize the conclusions summarized above.
Next steps
-
Download the executive summary and access a sample scorecard on our report page (link in the official release). For procurement teams and CMOs planning 2026 budgets, schedule a ninety‑minute briefing with a PW Consulting lead analyst to walk through scenario implications for your organization.
-
For boards and PE sponsors: request the “board pack” variant of the report — a condensed, decision‑focused bundle that aligns marketing investments to valuation drivers and exit timing considerations.
PW Consulting’s CMO Services Market report is built for leaders who must make fast, defensible choices in 2026. It combines market foresight with practitioner playbooks — enough to act with confidence, and intentionally calibrated to direct decision‑makers to the full intelligence set available on our site.
For detailed analysis of this topic, please visit the official page: CMO(Chief Marketing Officer) Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ocean Recycled Yarn Market Poised to Grow at 13.24% CAGR, Reaching USD 1,773.04 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide Ocean Recycled Yarn Market — Strategic Preview and 2026 Decision Roadmap
PW Consulting’s latest market study on the Worldwide Ocean Recycled Yarn Market delivers a compact, decision-focused briefing for corporate leaders preparing strategic moves in 2026. This preview summarizes the report’s high‑confidence macro view, explains why ocean‑recycled yarns now merit executive attention, and maps practical actions procurement, R&D, and sustainability teams should prioritize this year. To preserve the commercial value of our granular intelligence, detailed segment tables, regional shares, and application-level unit economics are reserved for subscribers; this release is written as a high‑signal “trailer” to demonstrate the report’s analytic rigor and operational utility.
Outdoor Fixed Screen Market
Market trajectory and what it means for 2026 planning
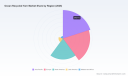
The ocean recycled yarn market has transitioned from niche sustainability experiment to a clearly scaling industrial segment. Our model, calibrated against 2020–2025 audited observations, shows total market revenue expanding from roughly USD 412 million in 2020 to USD 742.5 million in 2025. Looking forward, the market is projected to grow at a compound annual growth rate (CAGR) of 13.24% across 2026–2032, reaching approximately USD 1.77 billion by 2032.
MV Cables and Accessories Market
These figures indicate more than symbolic momentum — they signal structural demand growth driven by regulatory pressure, supply‑chain traceability needs, and brand‑level sustainability commitments. For 2026, that means companies cannot treat ocean‑recycled yarns as purely experimental procurement items. Instead, they should adopt a three‑track approach concurrently: secure traceable feedstock agreements, validate performance equivalence through targeted testing, and define near‑term pricing and marketing strategies that reflect the product’s traceability premium.
Gamete Processing Media Market
Why 2026 is a pivotal year
- Regulatory inflection points are accelerating demand: Emerging mandatory recycled‑content rules in major jurisdictions are creating measurable procurement requirements for downstream brands. These rules amplify the commercial value of traceable recycled inputs and increase buyer urgency in 2026.
- Supply‑side sophistication is improving: Leading producers and material platforms have moved beyond pilot projects into demonstrated commercial pathways for ocean‑bound feedstocks. These developments reduce technical execution risk for early adopters who move to formalize supplier relationships in 2026.
- Market concentration offers both risk and opportunity: The market demonstrates moderate concentration among leading suppliers; the top three and top five producers account for meaningful but not overwhelming shares, leaving space for partnerships, co‑development, and second‑tier entrants.
Key dynamics shaping supplier and buyer strategy
- Feedstock realities and cost dynamics: Recycled PET and recycled nylon feedstocks for ocean‑recycled yarns remain price‑sensitive and regionally variable. Certified ocean‑bound and traceable streams command a premium for provenance and environmental additionality; procurement teams must budget for those premiums while leveraging forward contracts and aggregated demand to stabilize costs.
- Traceability and certification as a commercial filter: Materials carrying recognized certifications (Global Recycled Standard, Ocean‑Bound certification frameworks, and independently auditable chain‑of‑custody systems) are rapidly becoming table stakes for brand buyers. Verification quality—not just label—will determine which suppliers gain scale in 2026.
- Regulatory and trade headwinds: New policy measures and tariff adjustments are increasing total landed cost in certain corridors. Companies with global supply chains should model alternative sourcing and localized conversion footprints to mitigate trade exposure.
- Performance parity and application limits: Technical advances have closed many performance gaps for apparel and soft‑goods applications, but buyers should still expect differentiated product readiness across technical performance categories (e.g., high‑tenacity industrial yarns vs. fashion filament yarns). Targeted validation programs are required before large rollouts.
Competitive landscape — who is setting the market’s tempo
Our report profiles the active commercial ecosystem that is shaping market standards and supply capacities. Several vertically integrated material manufacturers and technology platforms are particularly influential in 2026:
- Manufacturers converting ocean‑bound plastics into commercial yarns (both polyester and regenerated nylon) are leveraging integrated branding and B2B distribution channels to secure premium placements with apparel and technical customers.
- Specialist platform players and marketplaces focused on traceable ocean‑bound plastics have become transaction hubs, enabling smaller yarn converters and fabric mills to access certified feedstock without building their own procurement networks.
- Several pioneers have announced or implemented pilot and demonstration facilities to address specific technical challenges—separation of blended fibers, scalable regeneration of nylon from nets, and modular traceability systems—indicating that industrialization risk is reducing but still present for complex blends.
Notable recent corporate developments captured in our timeline include sustainability target updates from global players; pilot‑scale demonstration plants aimed at recycling nylon blends; and industry exhibitions where manufacturers showcased next‑generation ocean‑recycled portfolios. These events underline the shift from proof‑of‑concept to industrial scaling and brand engagement.
Practical report content: what PW Consulting delivers
The full report is designed as an operational toolkit for 2026 decision cycles. Key deliverables include:
- A validated market model with historical audit and forward projections through 2032, allowing scenario testing under alternative price and regulatory paths.
- A risk matrix and supplier heat map that ranks commercial suppliers by traceability integrity, capacity ramp plans, technology readiness, and margin expectations—presented to enable rapid supplier selection and negotiation checklists.
- Commercial playbooks for procurement, product development, and sustainability teams: ready‑to‑use contract language for marine‑sourced feedstock premiums, benchmarking protocols for performance parity testing, and communication frameworks to translate provenance into brand stories without greenwash exposure.
- Regulatory impact assessments that model the near‑term effects of recycled‑content mandates and trade measures on feedstock flows, and recommend adaptive sourcing strategies per jurisdictional risk profile.
- Capex and Opex scenarios for in‑house vs. outsourced conversion strategies, including a decision tree that identifies when integration into upstream feedstock collection or downstream value capture becomes financially attractive.
How executives should use this analysis in 2026
We recommend a four‑step 2026 action agenda for executives who want to move from exploratory pilots to measurable business outcomes:
- Secure traceable feedstock capacity: Enter minimum‑volume commitment discussions with certified suppliers or marketplaces now to lock in availability and negotiate premium offsets via multi‑year contracts.
- Run targeted validation pilots: Allocate prioritized engineering resources to performance testing in two critical SKUs that represent your highest volume and margin sensitivity. Use our standard test template to accelerate procurement acceptance.
- Hedge against price and trade volatility: Build a simple forward procurement and localized conversion rubric into your sourcing strategy. Use blended sourcing (bottle rPET + certified ocean‑bound where needed) to moderate cost while preserving claim authenticity.
- Institutionalize traceability and comms discipline: Prepare proof‑packets and audit trails for each launched product line. Marketing and legal teams must align on verifiable claims to avoid reputational risk as regulatory scrutiny increases.
Why PW Consulting’s dataset matters for 2026
Our projection methodology triangulates multiple inputs: supplier capacity disclosures, audited sales data, trade flows, pricing windows, certification volumes, and a curated timeline of supplier‑level developments. That allows the report to deliver not only a directional market forecast — anchored by a 13.24% CAGR into 2032 and a total market trajectory that reaches roughly USD 1.77 billion by 2032 — but also actionable levers that materially affect procurement efficacy and product roadmaps in the coming 12 months.
Importantly, while the market is growing rapidly, ocean‑sourced streams still represent a differentiated and scarce subset of recycled feedstock; their commercialization is contingent on traceability systems, technological advances in blend separation, and the ability of brands to internalize premiums. Our report quantifies these constraints and proposes commercially viable pathways for overcoming them.
Next steps — how to access the full dataset and tailored advisory
This announcement is a high‑value preview intended to guide immediate 2026 planning. The detailed segment breakdowns (regional shares, application‑level volumes, unit economics, and supplier‑level market shares), downloadable model, and custom advisory options are available in the full PW Consulting report and through our enterprise advisory engagements. For teams looking to accelerate decision cycles in 2026, we offer fast‑track briefings and bespoke scenario runs that incorporate company‑specific demand forecasts and contract terms.
To request the full report, model files, or to schedule a strategy workshop, please contact PW Consulting. Early engagement in 2026 will materially improve bargaining posture with suppliers, reduce technical adoption risk, and convert sustainability commitments into defensible commercial advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Ocean Recycled Yarn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Elastomeric Polyurethane Roof Coatings Market to Grow at a 6.8% CAGR, Reaching USD 1,625.15 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide Elastomeric Polyurethane Roof Coating Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study, "Worldwide Elastomeric Polyurethane Roof Coating Market (Base Year 2025) — Strategic Outlook 2026–2032," translates complex market dynamics into operationally useful guidance for procurement leaders, product strategists, investors, and corporate development teams preparing decisions in 2026. The market is no longer just about formulation science or price-per-gallon: it is an intersecting story of raw‑material supply swings, regulatory shifts, and consolidation dynamics that will materially shape margin, specification and sourcing choices over the next planning cycle.
Mobile Solar Container Market
High‑level trajectory: the numbers that matter
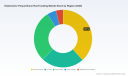
Our study tracks the market through a six‑year historical series and delivers a 2026‑2032 forecast. The global elastomeric polyurethane roof coating market grew steadily in the 2020–2025 period and is estimated at roughly USD 1.025 billion in the base year (2025). Our forecast points to continued expansion in 2026 and beyond, supported by a compound annual growth rate (CAGR) of 6.8% through 2032, with the market approaching the mid‑to‑high‑USD‑millions range by the end of the forecast window. Market concentration is meaningful but not prohibitive: the three largest players account for a little under two fifths of value, while the top five capture a little over half—conditions that favour both scale players and well‑positioned niche innovators.
Electric Energy Metering Cubicle Market
Why this report is a strategic asset for 2026 planning
- Translate macro trends into procurement playbooks: understand how near‑term raw‑material momentum and policy moves translate into contract terms, hedging targets and working capital needs.
- Prioritise R&D and portfolio investment: determine whether to favour single‑component moisture‑cure systems, two‑component systems, or hybrid approaches given evolving site conditions, specification trends, and lifecycle cost drivers.
- Fine‑tune commercial strategy: use a defensible, scenario‑based view of demand to redesign pricing ladders, rebate programs, distributor margins and warranty constructs for 2026 launches.
- Identify M&A and collaboration windows: map attractive target profiles and realistic valuation bands under multiple raw‑material and regulatory scenarios.
Core dynamics shaping 2026 decisions
Three interlocking dynamics will dominate tactical and strategic choices in 2026:
Zinc-Oxygen Air Battery Market
- Raw material volatility and supplier posture. The feedstock cycle has shown material movement recently — with significant short‑term downward correction in MDI pricing followed by upstream manufacturers signalling price countermeasures. Buyers need active cost‑model sensitivity to MDI/TDI and polyol moves rather than relying on static assumptions.
- Trade policy and regional supply risk. Escalating trade measures on certain feedstocks and ongoing antidumping reviews create a two‑track sourcing landscape: onshore/balanced inventories versus opportunistic import sourcing as duties and trade remedies evolve.
- Regulatory and specification pressure. Environmental policy is shifting product selection and application methods. Phasedowns and import restrictions on certain blowing agents and HFC‑containing formulations are already influencing specification language and will increasingly be reflected in procurement tenders and public‑sector RFPs.
Competitive landscape — what we observed and why it matters
Our competitive review synthesises company positioning, recent product and specification activity, channel footprints and formulation distinctions across a broad set of incumbents and specialists. Key takeaways:
- Global formulators with system offerings (e.g., Sika Corporation). These organisations compete on integrated system claims (membrane + coating + warranties), channel depth, and spec‑level visibility. They are favoured in large commercial projects that prioritise single‑source responsibility.
- Regional specialists and formulators (e.g., Polycoat Products, Inland Coatings, UPI, Tremco). These firms win on application depth, nimble reformulation, and contractor relationships. Recent updates to product specifications and package sizes signal tactical moves to capture restoration and retrofit workstreams where logistics and labour efficiency matter.
- Technology and niche players. Companies that emphasize low‑odor, low‑VOC, UV‑stable aliphatic topcoats, and moisture‑curing single‑component systems retain technical differentiation that can be monetised through premium specs or reduced installation risk.
- Emerging suppliers from lower‑cost production bases. They are penetrating certain channels, especially where price‑for‑performance acceptance thresholds are lower. Trade measures and quality assurance expectations will determine how quickly such entrants scale in developed markets.
Notable, actionable signals in the competitive set: Inland Coatings’ specification releases and package size updates in 2025 reflect a deliberate push to standardise restoration workflows and logistics efficiency — an example of how product packaging and spec language can be deployed as competitive levers without material formulation changes.
What the full report contains — practical tools for execution
PW Consulting’s report is designed as a practitioner’s toolkit. Key deliverables include:
- Interactive market model (2020–2032) with scenario toggles for MDI/TDI price swings, tariff outcomes and regulatory milestones so finance and procurement can quantify upside and downside exposure.
- Actionable supplier scorecards that map capability (formulation range, claim substantiation, warranty, spec references), logistic footprint, and counterparty risk.
- Application‑level playbooks (commercial, residential retrofit, industrial) with recommended product choices, installation productivity benchmarks, and lifecycle cost comparisons tailored to common roofing substrates.
- Regulatory compliance checklist and suggested contract provisions to mitigate phasedown and import restriction risks for both suppliers and buyers.
- Deal playbook for M&A and partnerships that includes valuation diagnostics, earn‑out structures keyed to material price normalization, and buyer integration risks.
- Procurement templates and RFP language that operationalise product‑level performance clauses, acceptable substitute rules and audit rights.
As a preview, we present market direction and the aforementioned tools; detailed subsegment tables (type-by-application-by-region), granular price curves, and the full supplier benchmarking matrices are reserved for the complete report and interactive dashboards available on the PW Consulting portal.
Practical use cases — how executives should apply these insights in 2026
- Chief Procurement Officers: Use the scenario model to size working capital needs under alternate tariff and feedstock outcomes, and to set forward‑buy thresholds for critical polyols and isocyanates.
- Head of Product/R&D: Prioritise development of low‑VOC moisture‑cure systems and aliphatic topcoats where specification tailwinds intersect with lower installation risk—validate via field pilots that include life‑cycle cost inputs from our model.
- Commercial Leaders: Rework distributor contracts to reflect differentiated technical services and installation training; target warranty and specification sweet spots where competitors are weaker.
- Corporate Development / PE Investors: Use the competitive concentration metrics and supplier scorecards to identify consolidation targets or partnership candidates whose value unlock depends primarily on distribution scale or specification access.
Risk scenarios and early warning indicators
The report includes three scenario tracks to frame 2026 choices: (1) supply oversupply and price softening, (2) policy‑driven supply tightness with elevated duties, and (3) technology‑led specification shifts towards low‑emission systems. Each track is associated with early warning indicators we monitor monthly — including spot spreads for key isocyanates, trade remedy filings, and major public‑sector specification updates — enabling rapid course correction.
Next steps — how to convert insight into advantage
For leaders who need to convert this analysis into 90‑day actions and 18‑month programs, the recommended next steps are:
- Acquire the full report and interactive model to run organisation‑specific scenarios against your raw material exposure and mix of single‑ vs two‑component sales.
- Commission a focused procurement stress‑test to translate scenario outcomes into supplier contracting and inventory strategies.
- Initiate pilot projects for priority product variants identified by our go‑to‑market scorecards, capturing both performance and installer time‑and‑motion data.
- Use the supplier scorecards to update approved vendor lists and refine warranty and acceptance criteria in upcoming bids.
PW Consulting’s Worldwide Elastomeric Polyurethane Roof Coating Market report is built to inform the key tradeoffs executives face in 2026: speed to market versus specification integrity, short‑term cost savings versus long‑term warranty risk, and domestic resilience versus import opportunism. For the complete data tables, supplier matrices and interactive scenario model that underpin these recommendations, please visit the PW Consulting report page to access the full deliverable and schedule a briefing with our industry specialists.
For detailed analysis of this topic, please visit the official page: Worldwide Elastomeric Polyurethane Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Customer Churn Software Market Set to Expand at a 20% CAGR
By pmarketresearch, 2026-08-18
Customer Churn Software Market — Strategic Preview for 2026 Decision-Makers
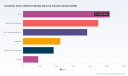
PW Consulting’s latest market study on Customer Churn Software offers a forward-looking strategic toolkit for executives planning investments, procurement, and operating-model shifts in 2026. Anchored on a 2025 base year and projecting through 2032, the study quantifies a rapidly expanding market driven by AI-led prediction, automation of customer success workflows, and tighter regulatory scrutiny. Our headline finding: the market is growing at a compound annual growth rate (CAGR) of 20.0% from the 2020–2025 historical period into the 2026–2032 forecast window, producing a material expansion in vendor opportunity and buyer choice across segments.
Garbage Truck Dispatch System Market
Why this report matters for 2026 strategy
-
Capital allocation: With the market already crossing the billion-dollar threshold in the mid-2020s and accelerating into the late 2020s, boards and CFOs must re-evaluate tech budgets and ROI horizons for subscription and retention technology. This study translates market momentum into realistic procurement timelines and investment break-evens tailored to enterprise and mid-market buying cycles.
Power Electronics for Data Centers Market -
Vendor selection complexity: AI-driven modules, no-code predictive tools, and embedded CX workflows have multiplied vendor capabilities—and the risk of feature overlap and integration debt. Our vendor assessment framework helps buyers prioritize capability clusters that map to measurable churn KPIs rather than product buzzwords.
Double Speed Wire Rope Electric Hoist Market -
Operational redesign: Automation and AI agents are shifting costs from human time to cloud compute. The report quantifies this shift and provides scenario-based financial models so leaders can stress-test headcount vs. compute trade-offs for 12–36 month horizons.
-
Regulatory and cost shocks: Emerging state privacy laws and increased GDPR enforcement are already affecting data usage strategies for churn analytics. Meanwhile, cloud hosting cost dynamics—such as recently introduced IPv4 charges—are creating new variable cost lines that materially affect SaaS economics for retention platforms. We translate these externalities into actionable mitigation options.
Market sizing and trajectory (high-level)
Using a consistent methodology across the 2020–2025 historical period and a scenario-based forecast through 2032, the study provides a year-by-year market sizing sequence that demonstrates both the momentum already achieved and the expected continuation of high growth. The 20% CAGR reflects accelerating adoption of AI-based predictive modules, broader acceptance of cloud-native deployments, and an expanding set of use cases from subscription-native businesses to traditional verticals adopting customer success disciplines.
For procurement and finance teams, this trajectory means shorter technology refresh cycles, more frequent feature-driven vendor churn, and a heightened premium on integration architecture and vendor lock-in avoidance. The report offers templates to quantify total addressable opportunity (TAM), serviceable addressable market (SAM), and realistic obtainable market (SOM) for corporate planning, without presuming a one-size-fits-all position.
What’s inside the report — practical deliverables
-
Executive Playbook: A prioritized, enterprise-grade decision checklist that links business objectives (reduce gross churn, improve net revenue retention, lower servicing cost) to measurable deployment paths and KPIs.
-
Vendor Evaluation Matrix: Multi-dimensional comparisons across capability vectors (predictive accuracy, explainability, automation maturity, integration depth, data governance and privacy controls, cost transparency). The matrix ranks vendors by fit for archetypal buyer personas.
-
Implementation Playbooks: Step-by-step blueprints for pilot-to-scale deployments, including data ingestion patterns, model governance, change-management checkpoints, and playbook-trigger mappings for common churn drivers.
-
Financial Models & TCO Calculator: Interactive templates to model acquisition cost reductions, retention lift, and the compute vs. headcount sensitivity given the current trend of shifting labor costs to cloud compute.
-
Regulatory Impact Map: Scenario planning for privacy and compliance risk that aligns U.S. state-level privacy shifts and European enforcement trends to practical mitigations (data minimization, edge anonymization, consent orchestration).
-
Procurement & Commercial Playbook: Negotiation levers that matter in 2026—consumptive pricing, data egress terms, IP for derived models, and performance SLAs tied to retention outcomes.
-
Customizable Buyer Shortlists: Pre-built vendor shortlists for enterprise, mid-market and vertical-specific needs that accelerate RFP and PoC cycles.
Competitive landscape — who matters and why
The market is in a phase where a mix of specialized customer-success platforms, CX incumbents, and no-code AI providers each play distinct roles. Market concentration is moderate: the top-three firms account for a meaningful share but do not dominate the sector completely; the top-five increase concentration further, indicating room for both scale and nimble challengers. This competitive structure creates opportunities for strategic partnerships, bolt-on acquisitions, and niche specialization.
-
Gainsight (San Francisco) — Strengths: enterprise-grade customer success platform with deep lifecycle analytics, AI-powered churn prediction, and strong adoption among large Customer Success organizations. Strategic posture: platform extensibility and enterprise governance, suited to customers prioritizing scale and integration with existing CRM and analytics stacks.
-
ChurnZero (Washington, D.C.) — Strengths: subscription-business focus with real-time risk alerts, engagement scoring, and recent investment in AI agents. Recent move: announced a 2026 leadership summit and Q4 product updates that further embed AI-assisted workflows—signaling continued emphasis on community and practitioner enablement.
-
Zendesk (San Francisco) — Strengths: CX and support workflow integration with churn prediction embedded into service operations. Strategic advantage: ability to operationalize retention insights within support channels and omnichannel customer interactions.
-
Totango (Redwood City) — Strengths: journey-driven customer success for SaaS, with predictive revenue intelligence and an emphasis on modular deployments to reduce time-to-value for recurring-revenue businesses.
-
Pecan AI (New York; global operations) — Strengths: no-code predictive analytics focused on automated churn modeling. Recent move: launched a Predictive AI Agent that translates business questions into production-grade churn models without a full data science bench—an offering that shortens model-to-action cycles for non-technical teams.
-
Vitally (Brooklyn) — Strengths: data unification and automation aimed at B2B SaaS teams, combining health scoring and actionable playbooks for smaller CS functions seeking rapid adoption.
Recent industry movements and implications
-
Product momentum: January 2026 releases and product updates from vendors like ChurnZero and Pecan AI underscore the race to productize AI agents and pre-built predictive workflows. For buyers, this means PoCs can be executed faster—but buyers must insist on explainability and governance for any agent-driven recommendation.
-
Benchmarking and accountability: External reports (e.g., the 2026 B2B Retention Report) are creating standardized retention benchmarks; vendors and customers will increasingly use these benchmarks to anchor commercial SLAs and to quantify the contribution of churn software to NRR (Net Revenue Retention).
-
Cloud cost dynamics: Newly surfaced hosting costs—such as IPv4-related charges—are producing a non-trivial 8–12% uplift on cloud bills for SaaS deployments that rely on multiple public IPs. Our cloud-cost sensitivity analysis shows that these line items can materially change unit economics and vendor TCO comparisons.
-
Regulatory pressure: A wave of state-level privacy statutes and increased GDPR enforcement (with breach notifications up ~22% year-over-year) is elevating compliance as a core procurement criterion. The report provides an actionable compliance checklist that facilities can apply during RFPs and due diligence.
-
Labor-to-compute shift: Adoption of AI agents is reducing routine CS administrative work, shifting spend from human FTEs to compute and platform fees. The report includes scenarios to help HR and Finance teams rebalance roles around higher-value retention activities.
Strategic recommendations for 2026
-
Adopt an outcomes-first procurement approach: define the retention metrics you will pay for (e.g., incremental NRR lift per quarter) rather than feature checklists. Tie pilot success criteria to those outcomes.
-
Insist on model governance and explainability: AI agents increase velocity but introduce model risk. Include minimum explainability and monitoring clauses in contracts.
-
Stress-test TCO for hidden line items: include cloud cost sensitivity (e.g., IPv4 charges), data egress, and incremental compute for model retraining as part of procurement models.
-
Design for composability: select vendors that provide API-first integrations and clear data contracts to avoid lock-in and to enable best-of-breed orchestration.
-
Plan workforce transitions: redeploy CS resources to proactive retention and expansion motions while automating low-value administrative tasks.
-
Build privacy-by-design into data pipelines: treat emerging state privacy requirements and European enforcement as a design constraint, not a checklist add-on.
How to use this preview
This article is a strategic preview intended to convey the report’s utility for 2026 planning. PW Consulting’s full Customer Churn Software Market Report contains the complete year-by-year market sizing series, detailed vendor profiles and scoring, granular segmentation by deployment model, organization size, vertical and region, and downloadable financial models and procurement templates. To preserve the report’s commercial value and to prevent misuse of market detail in public summaries, we have intentionally withheld the granular segment-level splits and tactical vendor scoring from this preview.
If your investment committee, procurement team, or customer-success leadership requires an accelerated decision package, our practice offers tailored briefings, vendor shortlists matched to your environment, and hands-on implementation advisory to compress the evaluation and PoC cycle from months to weeks.
Contact PW Consulting to arrange a briefing or to license the full report and the editable TCO/ROI models that support 2026 budget cycles and multi-year roadmaps.
For detailed analysis of this topic, please visit the official page: Customer Churn Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 5‑Bromo‑2,4‑Dichloropyrimidine Market Hits USD 142.5 Million in 2025, Poised for Further Growth
By pmarketresearch, 2026-08-18
Worldwide 5-Bromo-2,4-dichloropyrimidine Market — Strategic Insights for 2026 Decision-Making
Executive summary
As pharmaceutical and fine-chemical supply chains stabilize post‑pandemic, 5‑Bromo‑2,4‑dichloropyrimidine is re‑emerging from a niche intermediate to a strategically important commodity for drug synthesis, process R&D, and specialty agrochemical routes. Our updated market model values the addressable market at approximately USD 142.5 Million in 2025, with an anticipated near‑term uplift into 2026 and a compound annual growth rate (CAGR) of 6.31% across the 2026–2032 forecast window. By 2032 the market scenario we model reaches the low hundreds of millions of USD, driven by incremental demand from pharmaceutical APIs, ongoing laboratory synthesis needs, and modest growth in agrochemical intermediates.
Worldwide Massage Therapy Software Market
Why this report matters for 2026 corporate strategy
-
Procurement and supply continuity: Buyers who lock in strategy before mid‑2026 will avoid the next wave of spot‑market volatility caused by feedstock price swings and transport reclassification costs.
Worldwide Sink & Drain Unblocker Market -
Portfolio prioritization for API projects: For companies scaling trisubstituted‑pyrimidine chemistries (for example, certain CDK inhibitors), clarity on available purity grades, supplier capabilities, and lead times changes go/no‑go choices for late‑stage process development.
Die Sinking Electrical Discharge Machine Market -
Regulatory and logistics planning: The material’s transport classification and inventory regulatory status have direct implications for warehousing, international shipping, and total landed cost—factors that materially affect margin on high‑value synthesis runs.
-
M&A and partnerships: Moderate market concentration and differentiated capability across suppliers create clear opportunities for bolt‑on acquisitions and capacity partnerships that accelerate market share without large greenfield investments.
What PW Consulting’s report delivers (practical, transaction‑ready outputs)
-
Demand forecast model (interactive Excel) with base year 2025, detailed annual forecasts to 2032 and sensitivity scenarios driven by API pipelines, lab‑scale research spend, and agrochemical launches.
-
Supplier landscape and capability mapping: granular supplier scorecards covering capacity, purity grades, product form (powder vs liquid), quality systems, geographic footprint, and customer concentration metrics.
-
Pricing and margin analytics: componentized cost curves, landed‑cost calculators, and a proprietary volatility index that traces raw material drivers back to chlorination chemistry and pyrimidine intermediate inputs.
-
Regulatory & logistics playbook: implications of transport classification, TSCA listing, and EU regulatory posture—practical checklists for procurement, warehousing, and cross‑border shipments.
-
M&A and commercial playbook: target lists, value creation levers for bolt‑ons, integration checklists, and an M&A valuation template calibrated to this specialty chemical space.
-
Risk matrix and mitigation strategies: supplier failure scenarios, price‑shock playbooks, and recommendations for contract structures (caps, indexation, minimum off‑take, and dedicated tolling).
Market dynamics and near‑term risks
The market is influenced by a distinct set of structural and episodic drivers. Structurally, demand is tied to the pace of pharmaceutical synthesis and laboratory R&D activity; episodically, logistics classification changes and raw material price shocks create sharp cost and availability effects.
-
Transport & safety classification: Recent supplier documentation reinforces a corrosive solid classification under UN transport regimes. This elevates packaging, handling, and freight complexity—and increases the premium for suppliers that can offer compliant, low‑risk logistics solutions.
-
Regulatory status: The substance is listed under the U.S. TSCA inventory, with no current Annex XIV or Annex XVII restrictions under EU REACH identified in public supplier documentation. Still, regional regulatory scrutiny on intermediates in pharmaceutical supply chains remains a monitoring item for 2026.
-
Input price volatility: Key upstream inputs for 2,4‑dichloropyrimidine synthesis have experienced high intra‑quarter volatility—documented swings exceeding 40% quarter‑to‑quarter in recent periods. These swings propagate to spot pricing and put a premium on procurement strategies that include hedging or fixed‑price hedges with approved suppliers.
-
Commercial availability trends: Industrial‑scale listings and updated commercial product pages from established suppliers show active supply at 98–99% assay in both powder and liquid forms. Buyers should treat advertised availability as baseline and validate lead times through direct commercial engagement.
Competitive landscape: practical read for 2026 sourcing and partnership decisions
The supplier ecosystem is a mix of specialized lab‑grade vendors, regional manufacturers with export capability, and large global distributors. The market shows moderate concentration: the top three suppliers account for a meaningful share of revenue, and the top five collectively approach the majority of the market—an important signal for procurement and M&A strategists evaluating bargaining power and consolidation opportunities.
-
Specialist manufacturers in India and China (examples include integrated producers offering 98% assay powder and larger firms supplying 99%+ liquid intermediates) compete on scale and cost for industrial intermediates, and on price‑performance for pharma intermediate volumes.
-
Global laboratory suppliers and distributors (including established European and US brand names) dominate the small‑scale, high‑service channel—serving R&D customers with high‑purity grades, fast delivery and regulatory documentation.
-
Newer commercial listings from industrial players demonstrate incremental capacity for ton‑scale supply; these entrants change the negotiating dynamics and underline the need to verify quality consistency across batches for scale‑up programs.
Representative supplier profiles covered in the report include manufacturers and distributors spanning India, China, Japan, Europe and the US—each profiled for production footprint, assay grades offered, application focus (pharmaceutical synthesis, laboratory research, agrochemical synthesis), and recent commercial developments. The report also synthesizes public SDS and listing updates to highlight practical implications for procurement and compliance teams.
Actionable recommendations for 2026 (prioritized)
-
Secure dual sourcing with complementary partners: pair a cost‑competitive regional manufacturer for volume with a high‑service global distributor for critical R&D and expedited needs.
-
Negotiate price collars and indexation clauses: incorporate feedstock indexation tied to chlorination agent and pyrimidine derivative price indices to mitigate the risk from raw material spikes.
-
Invest selectively in qualification: for process scale‑up, allocate budget to qualify at least two suppliers per major purity grade to avoid single‑source exposure.
-
Prioritize suppliers with compliant logistics: pick partners that provide validated packaging and documentation for corrosive classification to lower landed‑cost uncertainty and reduce customs hold‑ups.
-
Earmark M&A targets: look for small, well‑qualified manufacturers with excess capacity or differentiated purification capability as high‑return bolt‑on targets to capture margin uplift.
-
Embed scenario planning into sourcing governance: run downside stress tests that assume sharp feedstock spikes and 30‑ to 60‑day shipping delays—adjust inventory policy accordingly.
How to use this report in your 2026 operating plan
The PW Consulting market package is built for immediate operationalization. Procurement teams can deploy the included supplier scorecards to update approved‑vendor lists; process development groups can use the purity and form comparisons to refine route selection; corporate development teams can run the M&A valuation templates against live targets; and regulatory or EHS groups can adopt the logistics playbook for compliant handling. Importantly, granular segmentation tables (by region, application and purity grade), price decks, and the detailed supplier contact appendices are intentionally restricted to the full report to preserve commercially sensitive datasets—this ensures readers who need transaction‑grade detail will access the primary source.
Closing — why act now
2026 will be defined by firms that convert visibility into operational advantage. With moderate concentration among incumbent suppliers, heightened input volatility, and transport/regulatory considerations creating tangible cost and timing impacts, companies that adopt the report’s recommended procurement, qualification and M&A measures in H1–H2 2026 will realize outsized risk reduction and margin protection. PW Consulting’s Worldwide 5‑Bromo‑2,4‑dichloropyrimidine Market report combines a defensible financial forecast, on‑the‑ground supplier intelligence, and transaction‑ready tools designed to inform those decisions.
For a full breakdown of regional and application segmentation, detailed price decks, supplier scorecards, and the downloadable forecast model, access the complete report on our website or contact our industry desk to schedule a briefing with one of our senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide 5-Bromo-2,4-dichloropyrimidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dried Lemon Market to Reach USD 504.63 Million by 2032, Growing at a 6.8% CAGR
By pmarketresearch, 2026-08-18
Worldwide Dried Lemon Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market brief on the Worldwide Dried Lemon Market distills the strategic intelligence senior leaders need as they finalize 2026 plans. Built from a systematic review of industry reporting, primary interviews, trade flows and price indices, the study synthesizes historical performance (2020–2025), sets an explicit base year of 2025, and delivers a seven‑year forecast through 2032. The market is projected to grow at a compound annual growth rate (CAGR) of 6.8% across the forecast window, reflecting resilient demand for dehydrated citrus ingredients across food, beverage, nutraceutical and specialty applications. This preview highlights the report’s practical value while deliberately withholding certain proprietary subsegment tables to encourage use of our full data package.
Disposable Suture Grasper Closure Device Market
Why this report matters for 2026 planning
-
Timing: 2026 is a pivot year—post‑pandemic reconfiguration of supply chains meets structural changes in ingredient sourcing and sustainability expectations. Executives who update sourcing, pricing and product roadmaps now will capture margin and share benefits as market dynamics normalize.
Worldwide Psychiatry EMR Software Market -
Scale and trajectory: The dried lemon market expanded materially through 2020–2025 and was valued at USD 318.4 Million in the 2025 base year. Our forecast shows continued expansion, with the market approaching a mid‑hundreds million USD opportunity by the end of the 2032 horizon—supporting investment cases for capacity, premiumization and downstream processing.
Internet Intelligent Elderly Care Service Platform Market -
Competitive context: The market remains fragmented (CR3 ≈ 18.5%; CR5 ≈ 28.3%), leaving meaningful space for differentiated offers, regional champions and scale consolidation—especially for players that can secure stable raw material access and deliver validated sustainability credentials.
Market trajectory at a glance
After an uneven recovery through 2020–2024, the dried lemon market posted renewed momentum in 2025. Our forecasted CAGR of 6.8% from 2026–2032 integrates price and supply shocks observed in late 2025 and early 2026, as well as growth drivers tied to convenience foods, beverage innovation, and nutraceutical formulation. While headline growth is attractive, the path to value requires targeted execution across sourcing, product differentiation and route‑to‑market strategies.
Supply‑side dynamics and near‑term risks
-
Raw material pressure: Multiple indicators point to constrained fresh lemon supply in the 2025/26 marketing year, including a projected global decline in fresh lemon and lime production. Parallel price signals—such as the uptick in U.S. Producer Price Index for farm lemons into early 2026 and elevated EU wholesale quotes—create immediate margin pressure for processors and exporters.
-
Processing and classification: International trade classification (e.g., HS code 0814.00 covering citrus fruit peel) continues to shape cross‑border movements and duty planning. Firms that optimize product specifications to minimize classification ambiguity will reduce friction and duty leakage in export markets.
-
Sustainability and traceability: Leading processors are accelerating investments in renewable energy and circular waste streams. Recent corporate disclosures demonstrate an industry shift from compliance to differentiation—producers that can document lifecycle emissions, water footprint and regenerative sourcing will command premium access to brands seeking verified inputs.
Demand drivers shaping product strategy
-
Formulation and convenience: Food and beverage manufacturers continue to favor stable, shelf‑ready citrus ingredients for flavoring, garnish and functional fortification. Innovations in powderization and volatile retention expand the addressable market for dried citrus beyond traditional uses.
-
Health and nutraceuticals: Renewed interest in vitamin C, botanical actives and gut‑friendly formulations supports higher value applications of dried lemon derivatives in supplements and functional beverages.
-
Premiumization of culinary and beverage segments: Co‑branded and artisanal product lines seek unique provenance claims (e.g., varietal, terroir, organic), which create differentiated pricing lanes for processors that can segregate and certify supply.
Competitive landscape — players to watch
The market’s fragmentation creates room for both global ingredient specialists and regional processors to capture niche leadership. Our review highlights a mix of integrated growers, dehydrators and ingredient conglomerates whose strategic moves will influence supply, pricing and innovation in 2026.
-
Lemon Concentrate S.L. (Spain) — A specialist in dehydrated peel and citrus inputs for industrial food processing, the company’s European footprint and focus on sauces and marinades position it as a key supplier to large food manufacturers.
-
Citrusvil (Argentina) — Vertically integrated from orchard to processing, Citrusvil’s sustainability initiative continues to support its global distribution model. Their emphasis on renewable processing aligns with rising buyer requirements for documented ESG performance.
-
Citromax (Argentina) — A producer focused on organic lemons and long‑term sustainable production, Citromax is strategically positioned to serve premium and certified organic channels.
-
Sunkist Growers & Dole (USA) — As major cooperatives and global fruit companies, these organizations provide scale and branded trust; their focus on quality dehydrated variants helps anchor mainstream foodservice and retail supply.
-
NutraDry (Australia), Van Drunen Farms, Limoneira (USA), Kerry Group (Ireland) — These firms represent the spectrum from specialist dehydrators to ingredient technologists, each contributing to innovation in powder forms, flavor systems and formulated ingredients.
-
EIC for Export (Egypt) — A notable bulk exporter with product relevance for spice, tea and specialty food processing markets—highlighting the continuing role of regional exporters in global spice and beverage value chains.
Recent developments reinforce these dynamics: Citrusvil’s sustainability announcements in early 2026, USDA FAS signals about organic peel expansion in the EU, and corporate financial disclosures from growers such as Limoneira collectively underscore how production, certification and forward guidance will shape 2026 sourcing and capacity decisions.
Strategic playbook for 2026
Based on the combination of market growth, price volatility and fragmented competition, PW Consulting recommends a set of prioritized actions for suppliers, brand owners and investors preparing 2026 budgets.
-
Hedge raw material exposure: Implement layered procurement contracts that combine fixed volumes, indexed pricing clauses and spot coverage. Scenario test cost pass‑through models for customers and incorporate margin protection in commercial agreements.
-
Segment selectively, without overextending: Pursue product variants that align with top‑line demand (e.g., premiumized powder formats for beverages, certified organic peel) but avoid broad SKU proliferation. Use pilot customers to validate premium claims before scaling.
-
Operationalize sustainability: Prioritize investments with rapid payback that also strengthen commercial positioning—solarization of drying facilities, water‑recycling, and traceability platforms. Account for these in R&D and capital plans as they increasingly unlock procurement preferences among large buyers.
-
Commercial partnerships and co‑development: Engage downstream beverage, flavor and nutraceutical partners in shared‑risk product development to accelerate adoption and secure long‑term off‑take agreements.
-
M&A and consolidation lens: Given low aggregate concentration, strategic acquisitions—particularly of regional processors with strong orchard linkages—remain an efficient route to secure feedstock and achieve scale synergies.
-
Regulatory and customs optimization: Audit classification and packing strategies to reduce trade friction tied to HS classifications and origin rules; small changes in product specs can materially affect landed costs in key export markets.
What the full PW Consulting report delivers
Our comprehensive report includes:
-
Methodology, data sources and a transparent model covering historical performance and forecast scenarios through 2032.
-
Proprietary demand‑side driver mapping and an assessment of growth vectors by form, application and channel (note: granular subsegment tables and region‑application grids are reserved for the full report and interactive dashboard).
-
Supply chain risk heatmaps, supplier scorecards and an actionable supplier segmentation framework that buyers and processors can use to prioritize partnerships.
-
Condensed M&A playbook and valuation benchmarks tailored for investors considering roll‑up and vertical integration strategies.
-
Commercial templates, KPIs and a 12‑month implementation checklist to convert strategy into execution.
How to use this intelligence in boardroom decisions
For 2026 planning cycles, treat this brief as the executive narrative and our full report as the tactical manual. Use the headline metrics—market scale, trajectory and concentration—to set investment envelopes. Then apply the procurement, sustainability and commercial playbooks to stress‑test budgets and prioritize capital allocation. Where uncertainty is highest (raw material availability and short‑term price swings), build contingency lines into operating plans rather than relying on single‑sourced assumptions.
Closing note — why PW Consulting
PW Consulting combines primary industry access with a pragmatic, implementation‑focused approach. Our dried lemon market study is designed to inform strategic choices without overwhelming stakeholders with raw tables; full subsegment analytics and the interactive forecast model are available through our client portal for executives who want the complete data set and executable templates.
Contact PW Consulting to arrange a briefing with our lead analyst team and obtain access to the full report and downloadable model—tailored workshops for procurement, R&D and M&A teams are available on request.
For detailed analysis of this topic, please visit the official page: Worldwide Dried Lemon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Educational & Training Software Market Poised for Rapid Expansion — 15.12% CAGR Forecast Through 2032
By pmarketresearch, 2026-08-18
Educational and Training Software Market — Strategic Imperatives for 2026
PW Consulting’s latest market research on the Educational and Training Software Market provides a sharply actionable, executive-grade playbook for 2026 decision-makers. Anchored in five years of historical analysis (2020–2025) and a multi-scenario forecast through 2032, the report translates rapid market expansion, technology disruption, and evolving regulation into clear, prioritized choices for vendors, enterprise buyers, and investors.
Predictive Behavioral Analytics Softwares Market
Why 2026 is a Pivotal Year
The sector’s structural momentum is unambiguous. Between 2020 and 2025 the global market more than doubled, reflecting widespread digitalization across K‑12, higher education and corporate learning. By our base year (2025) the market has reached a scale that makes platform selection, content strategy, and AI governance strategic rather than purely tactical concerns. Looking forward, our forecast shows a sustained compound annual growth rate (CAGR) of 15.12% for the 2026–2032 period, with the market roughly trebling over the forecast horizon under the baseline scenario.
Pharma Grade Conjugated Linoleic Acid Market
For leaders planning budgets and M&A in 2026, this combination of scale and growth shifts the calculus: investments in interoperability, data governance, and AI-enabled learning pathways offer outsized returns relative to incremental content spend. Conversely, lagging on standards and compliance will create asymmetric downside as regulatory scrutiny tightens.
Oil Property Monitor Market
What PW Consulting’s Report Delivers
- Actionable market sizing and scenarios: A validated historical series to 2025 and three forward-looking scenarios through 2032 that quantify upside risk and downside contingencies for planning cycles and board discussions.
- Decision frameworks: Vendor selection matrices, ROI triangulation tools, and procurement scorecards tailored to distinct buyer personas (e.g., national education ministries, universities, enterprise L&D functions).
- Technology adoption blueprints: Roadmaps for migrating to cloud-native platforms, integrating generative AI capabilities, adopting standards-based assessment engines, and operationalizing data privacy controls.
- Go‑to‑market playbooks: GTM frameworks for vendors seeking to prioritize product investments, channel partnerships, and pricing models in 2026, with sample KPIs and churn-minimization tactics.
- Vendor and competitive heatmaps: Tactical profiles and capability assessments of the sector’s leading providers—highlighting differentiation vectors without disclosing proprietary benchmarking scores in this release.
- Compliance and risk mitigation modules: Practical checklists to align AI-enhanced offerings with emerging regulatory regimes, including high-risk AI classifications and data-protection expectations.
Key Strategic Insights for 2026 Decision-Making
- Prioritize composable architectures: Buyers should favor platforms that support modular integration—LMS, assessment engines, content repositories, and analytics services—because the pace of innovation (especially in AI) will make monolithic solutions brittle. The economics of switching costs and incremental functionality strongly favor composability in vendor evaluations.
- Invest early in AI governance and explainability: With generative AI now embedded in product roadmaps and national initiatives promoting AI literacy, organizations must build governance controls around pedagogical validity, bias mitigation, and auditability. Our practical templates enable procurement teams to score AI features on safety and pedagogical alignment.
- Turn compliance into a competitive asset: The regulatory environment — including guidance and enforcement in 2026 from supranational and national bodies — will redefine procurement criteria. Vendors that bake in compliance and transparent model governance will unlock larger public-sector contracts and partnerships.
- Measure learning impact, not just engagement: As customers demand demonstrable outcomes, focus metrics should shift from time-on-platform to competency attainment, transfer-to-job outcomes, and longitudinal ROI. The report’s outcome-mapping methodology helps buyers construct defensible business cases.
- Consolidation opportunity, but with an innovation premium: Market concentration remains moderate; the three- and five-firm concentration ratios indicate room for scale plays as well as specialist vertical winners. Strategic M&A that preserves product differentiation while accelerating cloud and AI capabilities will be rewarded.
Competitive Landscape: Who’s Moving and Why It Matters
The market’s leading commercial players are executing a mix of platform expansion, vertical specialization, and AI-led product innovation. Our qualitative analysis of incumbents and fast-scaling challengers reveals distinct strategic postures:
- Platform aggregators and marketplace players (e.g., Coursera): These providers are leveraging university and corporate partnerships to broaden credentialing, micro-credential pathways, and degree-completion offerings. Their competitive strengths lie in content breadth, brand association with top-tier institutions, and marketplace economics that scale well with demand.
- Consumer-first education apps (e.g., Duolingo): With engagement-driven product design and gamified learning loops, consumer apps are moving into adjacent categories (math, coding, soft skills) and proving the viability of learning-as-a-service models that can be adapted for corporate skilling.
- LMS incumbents (e.g., Instructure, Anthology/Blackboard): These firms maintain footholds in institutional procurement cycles. Their near-term challenge and opportunity is integrating AI-assistive tooling while modernizing architectures to support cloud-native deployment and seamless analytics.
- Corporate content specialists (e.g., Skillsoft, Pluralsight): Focused on professional reskilling and technical skill development, these vendors are competing on content depth, skill-path curation, and integration with enterprise HR systems and skill taxonomies.
- Cloud and platform titans (e.g., Microsoft, Google): Their strategic advantage is ecosystem integration—productivity suites, identity and device management, and increasingly, AI developer tooling. Recent 2026 initiatives from major cloud providers underscore the move to embed learning tools directly into daily workflows.
Recent developments—such as new AI-powered educator tools from major cloud providers, product innovations that automate personalized learning journeys, and national upskilling initiatives—validate our thesis that the race in 2026 is as much about platform ecosystem control as it is about content quality.
Regulatory and Macro Drivers to Watch
- AI-specific regulation: Emerging frameworks classify particular AI applications in education as higher risk and impose requirements for transparency, human oversight, and performance documentation. These regimes will meaningfully affect vendor roadmaps and procurement specifications in 2026.
- Public upskilling initiatives: Governments are rolling out AI-literacy and workforce development programs that create large-volume, low-margin demand — attractive for platform players that can deliver scalable, auditable outcomes.
- Standards and interoperability momentum: There is growing adoption of technical and data standards to enable credential portability and learning record stores; organizations that align early will reduce integration costs and accelerate cross-institution collaboration.
How PW Consulting Recommends Organizations Act in 2026
- For buyers: Run short, focused pilot programs that test composable integrations and learning-outcome metrics before committing to enterprise-wide deployments. Use the report’s procurement scorecards to compare vendors on governance, interoperability, and measurable outcomes rather than headline features.
- For vendors: Prioritize modular API-first designs, invest in robust AI safety and explainability features, and pursue partnerships that extend credentialing pathways into bona fide career outcomes. Consider disciplined bolt-on acquisitions that accelerate AI content creation or assessment automation.
- For investors: Target companies with defensible channels into public education and enterprise HR systems, clear paths to margin expansion via cloud economics, and demonstrable KPIs on learning-to-job transfer.
What We’re Not Releasing Here (and Why)
To preserve utility for procurement and investment workflows, the full report contains granular segmentation by deployment model, sector, region and product type, alongside vendor benchmarking scores and proprietary revenue splits. This release intentionally showcases strategic conclusions and practical tools while withholding the detailed subsegment tables and exact vendor metrics that organizations rely on for procurement or M&A diligence. That level of granularity is available in the full report and supporting data package.
Next Steps for Executives
PW Consulting’s report is designed to be immediately operationalizable in 2026 planning cycles. Clients can license the full dataset and toolkit for use in procurement RFPs, M&A diligence, and enterprise L&D strategy workshops. For executives preparing 2026 budgets, our recommendation is to reallocate a portion of content spend toward platform modernization, AI governance, and measurable outcome pilots—steps that the full report quantifies and prioritizes by expected ROI.
To explore the complete dataset, vendor profiles, and buy/sell playbooks, please consult the full PW Consulting publication and supporting tools on our website. Our analysts are available for tailored briefings and scenario workshops to translate the research into an actionable 90‑day roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Educational and Training Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modified Phenolic Resins Market Poised to Grow at a 5.29% CAGR, 2025 Insight Forecasts
By pmarketresearch, 2026-08-18
Modified Phenolic Resins Market: Strategic Imperatives for 2026 — PW Consulting Insights
As global manufacturers recalibrate for a new phase of industrial demand, Modified Phenolic Resins are re‑emerging as a strategic material class for adhesives, inks, coatings, friction materials and foundry applications. PW Consulting’s latest market model shows a steady expansion trajectory: the global market that stood below USD 1.6 billion in 2020 has approached the USD 2.0 billion mark by the 2025 base year, and our forecast projects continued growth at a compound annual growth rate (CAGR) of roughly 5.3% through 2032. For decision‑makers planning capex, sourcing and product strategy in 2026, that growth—coupled with shifting feedstock dynamics and an accelerating sustainability agenda—creates a narrow window of competitive opportunity.
Calcium Titanate for Ceramic Capacitors Market
Why 2026 is a Strategic Inflection Point
-
Supply‑side geometry is changing. Phenolic resins historically ride on the economics of phenol and downstream thermoset demand; between 2020 and 2025 we observed volatile but manageable swings in overall market value. With phenol prices moderating in 2025 and forecast ranges for 2026 dependent on benzene fundamentals, procurement teams must balance short‑term cost relief with medium‑term supply risk.
Separation and Purification Media Market -
Decarbonization and biomass substitution are now operational realities. Leading producers are commercializing lignin‑modified and other bio‑derived modifiers—reducing lifecycle carbon footprints while preserving performance attributes. These launches are not niche PR; they are influencing procurement specs and OEM sourcing decisions in plywood, friction applications and selected industrial end‑uses.
Self-curing Acrylic Resin Market -
Market structure favors focused differentiation. The industry’s concentration metrics indicate that top players command meaningful share without creating an impenetrable oligopoly—leaving room for specialized suppliers, toll manufacturers and regional champions to exploit niches or vertically integrate. This fragmentation underlines the strategic value of focused product and channel plays over blanket scale expansion.
-
Regulatory and customer requirements—especially on emissions and formaldehyde—are tightening selectively across jurisdictions. Manufacturers that can demonstrate lower emissions and certified biomass content are gaining preferential access to specification lists in construction and wood products sectors.
What the Report Delivers — Practical, Actionable Intelligence
We designed the Modified Phenolic Resins Market report as an operational toolkit for executives and technical leaders, not a static desk reference. Key deliverables include:
-
A robust market forecast model (2026–2032) with scenario branches covering demand‑led, supply‑shock and decarbonization accelerations—built to be re‑run with client‑specific inputs.
-
Supply‑chain stress tests and raw‑material sensitivity analyses that translate phenol, benzene and propylene movements into P&L and working capital impacts for typical resin portfolios.
-
Go‑to‑market blueprints for premium and commodity segments, including channel economics for tolling versus direct manufacture, and recommended KPIs for integration.
-
Commercial playbooks for low‑emissions product launches, including regulatory alignment, certification roadmaps and pricing levers that preserve margin while enabling volume adoption.
-
M&A / partnership screening—rapid assessment templates to identify bolt‑on assets, local tollers or biomass feedstock partners that deliver near‑term revenue accretion and long‑term resilience.
Competitive Landscape: Reading the Leaders
Our competitive analysis synthesizes corporate strategy, product portfolios and recent initiatives to reveal where incumbents are placing their bets. Several archetypes emerge:
-
Heritage formulators with sustainability R&D: Companies such as Sumitomo Bakelite and Prefere Resins are leveraging deep resin know‑how to commercialize lignin and other biomass‑modified grades. These players are moving beyond pilot announcements to industrialized offerings—an important signal that biomass substitution is migrating into mainstream procurement conversations.
-
Specialty, high‑performance-focused formulators: Hexion, DIC and SI Group continue to concentrate on electronics, aerospace and automotive niches that demand strict thermal, dielectric or mechanical performance. Their engineering sophistication enables higher ASPs and lower exposure to commodity cyclicality.
-
Toll manufacturers and regional champions: Plastics Engineering Company (PLENCO), Capital Resin Corporation and several agile players in Asia (including Polyols & Polymers) provide configurable supply models and multiple delivery formats—pastilles, powders, liquids—that large OEMs use to de‑risk manufacturing and shorten qualification cycles.
-
Integrated industrial suppliers: Producers with wood‑product, insulation or construction affiliations (e.g., Georgia‑Pacific Chemicals, Kolon Industries) use backward or forward integration to lock demand and optimize resin formulations for specific downstream processes.
Recent commercial moves underscore these dynamics. Notably, a major Japanese manufacturer commercialized a resol‑type lignin‑modified product in late 2024, marketing demonstrable lifecycle carbon benefits and certification credentials. That launch crystallizes two trends—first, that biomass substitution can be introduced without compromising key performance attributes; second, that credible third‑party certification amplifies commercial uptake by risk‑averse specification owners.
Raw Materials & Cost Dynamics to Watch in 2026
-
Phenol price trajectory. After peaking in earlier cycles, phenol softened through 2025. Market intelligence shows phenol moving from roughly USD 1.05/kg to the low‑USD 0.9x/kg band by 2025, with 2026 consensus reflecting a range driven by benzene fundamentals and recovery in adjacent polymer sectors. Procurement teams should plan for mid‑cycle volatility and embed dynamic price triggers into long‑term contracts.
-
Benzene and propylene linkage. Upstream feedstock swings—especially benzene and propylene—remain primary drivers of phenolic resin production cost. Regional cost differentials will persist, and North‑Asia sourcing economics warrant focused analysis for companies operating global supply footprints.
-
Biomass feedstock economics. Lignin and CNSL pathways are maturing but have distinct supply profiles and processing costs compared with petrochemical feedstocks. Early movers should quantify not only raw material costs but also processing CAPEX and certification timelines when modeling total cost of ownership.
Strategic Playbook for 2026: Five Actions for Executives
-
Operationalize feedstock diversification. Convert pilot bio‑formulations into commercial lines where upstream partnerships and certification can be secured. Prioritize feedstock trials that minimally disrupt existing cure and process windows to accelerate customer qualification.
-
Adopt scenario‑based procurement. Move from static long‑term contracts to blended strategies that combine fixed‑price volumes, indexed volumes and rolling call‑offs. Use the report’s sensitivity model to quantify how phenol swings map to EBITDA and to set hedging thresholds.
-
Differentiate through formulation services. For resin producers, offer application engineering and co‑development as a bundled service—this raises switching costs and shifts competition from price to value.
-
Fast‑track regulatory compliance as a commercial lever. Achieving demonstrated reductions in VOCs and formaldehyde, and securing biomass credentials, creates privileged access to spec lists in wood paneling, plywood and OEM parts specifications.
-
Execute selective M&A and toll partnerships. Identify regional tollers or specialty formulators that can be integrated quickly to capture demand in high‑growth subsegments without heavy CAPEX outlay.
Where PW Consulting Adds Value
PW Consulting’s report is designed for executives who need to act in 2026. Beyond the headline forecast and qualitative context, our deliverables include downloadable financial models, supplier heatmaps, qualification roadmaps for bio‑modified grades, and M&A playbooks tailored to different corporate archetypes (integrator, specialist, toll partner). We also package an interactive workshop that applies the model to a client’s portfolio, yielding a prioritized, executable roadmap with quantified ROI and implementation timelines.
We intentionally preserve granular segmentation tables and company‑level financials for the full report: this article follows a “trailer” principle—demonstrating methodological depth and strategic implications while directing commercial audiences to the complete data set for transaction‑grade decision‑making.
Next Steps
For procurement leads, product managers and corporate strategists, 2026 will be a year to convert optionality into differentiated capability. If you are planning raw‑material commitments, product launches, or inorganic moves in the resin space, access to segmented forecasts, supplier scorecards and our sensitivity engine is essential. Contact PW Consulting to license the full Modified Phenolic Resins Market report and schedule a tailored strategy session to convert the forecast into an executable action plan.
For detailed analysis of this topic, please visit the official page: Modified Phenolic Resins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com