

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 5‑Bromo‑2,4‑Dichloropyrimidine Market Hits USD 142.5 Million in 2025, Poised for Further Growth

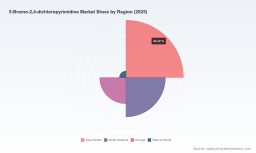
Worldwide 5-Bromo-2,4-dichloropyrimidine Market — Strategic Insights for 2026 Decision-Making
Executive summary
As pharmaceutical and fine-chemical supply chains stabilize post‑pandemic, 5‑Bromo‑2,4‑dichloropyrimidine is re‑emerging from a niche intermediate to a strategically important commodity for drug synthesis, process R&D, and specialty agrochemical routes. Our updated market model values the addressable market at approximately USD 142.5 Million in 2025, with an anticipated near‑term uplift into 2026 and a compound annual growth rate (CAGR) of 6.31% across the 2026–2032 forecast window. By 2032 the market scenario we model reaches the low hundreds of millions of USD, driven by incremental demand from pharmaceutical APIs, ongoing laboratory synthesis needs, and modest growth in agrochemical intermediates.
Worldwide Massage Therapy Software Market
Why this report matters for 2026 corporate strategy
-
Procurement and supply continuity: Buyers who lock in strategy before mid‑2026 will avoid the next wave of spot‑market volatility caused by feedstock price swings and transport reclassification costs.
Worldwide Sink & Drain Unblocker Market -
Portfolio prioritization for API projects: For companies scaling trisubstituted‑pyrimidine chemistries (for example, certain CDK inhibitors), clarity on available purity grades, supplier capabilities, and lead times changes go/no‑go choices for late‑stage process development.
Die Sinking Electrical Discharge Machine Market -
Regulatory and logistics planning: The material’s transport classification and inventory regulatory status have direct implications for warehousing, international shipping, and total landed cost—factors that materially affect margin on high‑value synthesis runs.
-
M&A and partnerships: Moderate market concentration and differentiated capability across suppliers create clear opportunities for bolt‑on acquisitions and capacity partnerships that accelerate market share without large greenfield investments.
What PW Consulting’s report delivers (practical, transaction‑ready outputs)
-
Demand forecast model (interactive Excel) with base year 2025, detailed annual forecasts to 2032 and sensitivity scenarios driven by API pipelines, lab‑scale research spend, and agrochemical launches.
-
Supplier landscape and capability mapping: granular supplier scorecards covering capacity, purity grades, product form (powder vs liquid), quality systems, geographic footprint, and customer concentration metrics.
-
Pricing and margin analytics: componentized cost curves, landed‑cost calculators, and a proprietary volatility index that traces raw material drivers back to chlorination chemistry and pyrimidine intermediate inputs.
-
Regulatory & logistics playbook: implications of transport classification, TSCA listing, and EU regulatory posture—practical checklists for procurement, warehousing, and cross‑border shipments.
-
M&A and commercial playbook: target lists, value creation levers for bolt‑ons, integration checklists, and an M&A valuation template calibrated to this specialty chemical space.
-
Risk matrix and mitigation strategies: supplier failure scenarios, price‑shock playbooks, and recommendations for contract structures (caps, indexation, minimum off‑take, and dedicated tolling).
Market dynamics and near‑term risks
The market is influenced by a distinct set of structural and episodic drivers. Structurally, demand is tied to the pace of pharmaceutical synthesis and laboratory R&D activity; episodically, logistics classification changes and raw material price shocks create sharp cost and availability effects.
-
Transport & safety classification: Recent supplier documentation reinforces a corrosive solid classification under UN transport regimes. This elevates packaging, handling, and freight complexity—and increases the premium for suppliers that can offer compliant, low‑risk logistics solutions.
-
Regulatory status: The substance is listed under the U.S. TSCA inventory, with no current Annex XIV or Annex XVII restrictions under EU REACH identified in public supplier documentation. Still, regional regulatory scrutiny on intermediates in pharmaceutical supply chains remains a monitoring item for 2026.
-
Input price volatility: Key upstream inputs for 2,4‑dichloropyrimidine synthesis have experienced high intra‑quarter volatility—documented swings exceeding 40% quarter‑to‑quarter in recent periods. These swings propagate to spot pricing and put a premium on procurement strategies that include hedging or fixed‑price hedges with approved suppliers.
-
Commercial availability trends: Industrial‑scale listings and updated commercial product pages from established suppliers show active supply at 98–99% assay in both powder and liquid forms. Buyers should treat advertised availability as baseline and validate lead times through direct commercial engagement.
Competitive landscape: practical read for 2026 sourcing and partnership decisions
The supplier ecosystem is a mix of specialized lab‑grade vendors, regional manufacturers with export capability, and large global distributors. The market shows moderate concentration: the top three suppliers account for a meaningful share of revenue, and the top five collectively approach the majority of the market—an important signal for procurement and M&A strategists evaluating bargaining power and consolidation opportunities.
-
Specialist manufacturers in India and China (examples include integrated producers offering 98% assay powder and larger firms supplying 99%+ liquid intermediates) compete on scale and cost for industrial intermediates, and on price‑performance for pharma intermediate volumes.
-
Global laboratory suppliers and distributors (including established European and US brand names) dominate the small‑scale, high‑service channel—serving R&D customers with high‑purity grades, fast delivery and regulatory documentation.
-
Newer commercial listings from industrial players demonstrate incremental capacity for ton‑scale supply; these entrants change the negotiating dynamics and underline the need to verify quality consistency across batches for scale‑up programs.
Representative supplier profiles covered in the report include manufacturers and distributors spanning India, China, Japan, Europe and the US—each profiled for production footprint, assay grades offered, application focus (pharmaceutical synthesis, laboratory research, agrochemical synthesis), and recent commercial developments. The report also synthesizes public SDS and listing updates to highlight practical implications for procurement and compliance teams.
Actionable recommendations for 2026 (prioritized)
-
Secure dual sourcing with complementary partners: pair a cost‑competitive regional manufacturer for volume with a high‑service global distributor for critical R&D and expedited needs.
-
Negotiate price collars and indexation clauses: incorporate feedstock indexation tied to chlorination agent and pyrimidine derivative price indices to mitigate the risk from raw material spikes.
-
Invest selectively in qualification: for process scale‑up, allocate budget to qualify at least two suppliers per major purity grade to avoid single‑source exposure.
-
Prioritize suppliers with compliant logistics: pick partners that provide validated packaging and documentation for corrosive classification to lower landed‑cost uncertainty and reduce customs hold‑ups.
-
Earmark M&A targets: look for small, well‑qualified manufacturers with excess capacity or differentiated purification capability as high‑return bolt‑on targets to capture margin uplift.
-
Embed scenario planning into sourcing governance: run downside stress tests that assume sharp feedstock spikes and 30‑ to 60‑day shipping delays—adjust inventory policy accordingly.
How to use this report in your 2026 operating plan
The PW Consulting market package is built for immediate operationalization. Procurement teams can deploy the included supplier scorecards to update approved‑vendor lists; process development groups can use the purity and form comparisons to refine route selection; corporate development teams can run the M&A valuation templates against live targets; and regulatory or EHS groups can adopt the logistics playbook for compliant handling. Importantly, granular segmentation tables (by region, application and purity grade), price decks, and the detailed supplier contact appendices are intentionally restricted to the full report to preserve commercially sensitive datasets—this ensures readers who need transaction‑grade detail will access the primary source.
Closing — why act now
2026 will be defined by firms that convert visibility into operational advantage. With moderate concentration among incumbent suppliers, heightened input volatility, and transport/regulatory considerations creating tangible cost and timing impacts, companies that adopt the report’s recommended procurement, qualification and M&A measures in H1–H2 2026 will realize outsized risk reduction and margin protection. PW Consulting’s Worldwide 5‑Bromo‑2,4‑dichloropyrimidine Market report combines a defensible financial forecast, on‑the‑ground supplier intelligence, and transaction‑ready tools designed to inform those decisions.
For a full breakdown of regional and application segmentation, detailed price decks, supplier scorecards, and the downloadable forecast model, access the complete report on our website or contact our industry desk to schedule a briefing with one of our senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide 5-Bromo-2,4-dichloropyrimidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com