

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Customer Churn Software Market Set to Expand at a 20% CAGR

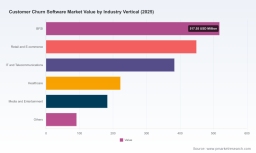
Customer Churn Software Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on Customer Churn Software offers a forward-looking strategic toolkit for executives planning investments, procurement, and operating-model shifts in 2026. Anchored on a 2025 base year and projecting through 2032, the study quantifies a rapidly expanding market driven by AI-led prediction, automation of customer success workflows, and tighter regulatory scrutiny. Our headline finding: the market is growing at a compound annual growth rate (CAGR) of 20.0% from the 2020–2025 historical period into the 2026–2032 forecast window, producing a material expansion in vendor opportunity and buyer choice across segments.
Garbage Truck Dispatch System Market
Why this report matters for 2026 strategy
-
Capital allocation: With the market already crossing the billion-dollar threshold in the mid-2020s and accelerating into the late 2020s, boards and CFOs must re-evaluate tech budgets and ROI horizons for subscription and retention technology. This study translates market momentum into realistic procurement timelines and investment break-evens tailored to enterprise and mid-market buying cycles.
Power Electronics for Data Centers Market -
Vendor selection complexity: AI-driven modules, no-code predictive tools, and embedded CX workflows have multiplied vendor capabilities—and the risk of feature overlap and integration debt. Our vendor assessment framework helps buyers prioritize capability clusters that map to measurable churn KPIs rather than product buzzwords.
Double Speed Wire Rope Electric Hoist Market -
Operational redesign: Automation and AI agents are shifting costs from human time to cloud compute. The report quantifies this shift and provides scenario-based financial models so leaders can stress-test headcount vs. compute trade-offs for 12–36 month horizons.
-
Regulatory and cost shocks: Emerging state privacy laws and increased GDPR enforcement are already affecting data usage strategies for churn analytics. Meanwhile, cloud hosting cost dynamics—such as recently introduced IPv4 charges—are creating new variable cost lines that materially affect SaaS economics for retention platforms. We translate these externalities into actionable mitigation options.
Market sizing and trajectory (high-level)
Using a consistent methodology across the 2020–2025 historical period and a scenario-based forecast through 2032, the study provides a year-by-year market sizing sequence that demonstrates both the momentum already achieved and the expected continuation of high growth. The 20% CAGR reflects accelerating adoption of AI-based predictive modules, broader acceptance of cloud-native deployments, and an expanding set of use cases from subscription-native businesses to traditional verticals adopting customer success disciplines.
For procurement and finance teams, this trajectory means shorter technology refresh cycles, more frequent feature-driven vendor churn, and a heightened premium on integration architecture and vendor lock-in avoidance. The report offers templates to quantify total addressable opportunity (TAM), serviceable addressable market (SAM), and realistic obtainable market (SOM) for corporate planning, without presuming a one-size-fits-all position.
What’s inside the report — practical deliverables
-
Executive Playbook: A prioritized, enterprise-grade decision checklist that links business objectives (reduce gross churn, improve net revenue retention, lower servicing cost) to measurable deployment paths and KPIs.
-
Vendor Evaluation Matrix: Multi-dimensional comparisons across capability vectors (predictive accuracy, explainability, automation maturity, integration depth, data governance and privacy controls, cost transparency). The matrix ranks vendors by fit for archetypal buyer personas.
-
Implementation Playbooks: Step-by-step blueprints for pilot-to-scale deployments, including data ingestion patterns, model governance, change-management checkpoints, and playbook-trigger mappings for common churn drivers.
-
Financial Models & TCO Calculator: Interactive templates to model acquisition cost reductions, retention lift, and the compute vs. headcount sensitivity given the current trend of shifting labor costs to cloud compute.
-
Regulatory Impact Map: Scenario planning for privacy and compliance risk that aligns U.S. state-level privacy shifts and European enforcement trends to practical mitigations (data minimization, edge anonymization, consent orchestration).
-
Procurement & Commercial Playbook: Negotiation levers that matter in 2026—consumptive pricing, data egress terms, IP for derived models, and performance SLAs tied to retention outcomes.
-
Customizable Buyer Shortlists: Pre-built vendor shortlists for enterprise, mid-market and vertical-specific needs that accelerate RFP and PoC cycles.
Competitive landscape — who matters and why
The market is in a phase where a mix of specialized customer-success platforms, CX incumbents, and no-code AI providers each play distinct roles. Market concentration is moderate: the top-three firms account for a meaningful share but do not dominate the sector completely; the top-five increase concentration further, indicating room for both scale and nimble challengers. This competitive structure creates opportunities for strategic partnerships, bolt-on acquisitions, and niche specialization.
-
Gainsight (San Francisco) — Strengths: enterprise-grade customer success platform with deep lifecycle analytics, AI-powered churn prediction, and strong adoption among large Customer Success organizations. Strategic posture: platform extensibility and enterprise governance, suited to customers prioritizing scale and integration with existing CRM and analytics stacks.
-
ChurnZero (Washington, D.C.) — Strengths: subscription-business focus with real-time risk alerts, engagement scoring, and recent investment in AI agents. Recent move: announced a 2026 leadership summit and Q4 product updates that further embed AI-assisted workflows—signaling continued emphasis on community and practitioner enablement.
-
Zendesk (San Francisco) — Strengths: CX and support workflow integration with churn prediction embedded into service operations. Strategic advantage: ability to operationalize retention insights within support channels and omnichannel customer interactions.
-
Totango (Redwood City) — Strengths: journey-driven customer success for SaaS, with predictive revenue intelligence and an emphasis on modular deployments to reduce time-to-value for recurring-revenue businesses.
-
Pecan AI (New York; global operations) — Strengths: no-code predictive analytics focused on automated churn modeling. Recent move: launched a Predictive AI Agent that translates business questions into production-grade churn models without a full data science bench—an offering that shortens model-to-action cycles for non-technical teams.
-
Vitally (Brooklyn) — Strengths: data unification and automation aimed at B2B SaaS teams, combining health scoring and actionable playbooks for smaller CS functions seeking rapid adoption.
Recent industry movements and implications
-
Product momentum: January 2026 releases and product updates from vendors like ChurnZero and Pecan AI underscore the race to productize AI agents and pre-built predictive workflows. For buyers, this means PoCs can be executed faster—but buyers must insist on explainability and governance for any agent-driven recommendation.
-
Benchmarking and accountability: External reports (e.g., the 2026 B2B Retention Report) are creating standardized retention benchmarks; vendors and customers will increasingly use these benchmarks to anchor commercial SLAs and to quantify the contribution of churn software to NRR (Net Revenue Retention).
-
Cloud cost dynamics: Newly surfaced hosting costs—such as IPv4-related charges—are producing a non-trivial 8–12% uplift on cloud bills for SaaS deployments that rely on multiple public IPs. Our cloud-cost sensitivity analysis shows that these line items can materially change unit economics and vendor TCO comparisons.
-
Regulatory pressure: A wave of state-level privacy statutes and increased GDPR enforcement (with breach notifications up ~22% year-over-year) is elevating compliance as a core procurement criterion. The report provides an actionable compliance checklist that facilities can apply during RFPs and due diligence.
-
Labor-to-compute shift: Adoption of AI agents is reducing routine CS administrative work, shifting spend from human FTEs to compute and platform fees. The report includes scenarios to help HR and Finance teams rebalance roles around higher-value retention activities.
Strategic recommendations for 2026
-
Adopt an outcomes-first procurement approach: define the retention metrics you will pay for (e.g., incremental NRR lift per quarter) rather than feature checklists. Tie pilot success criteria to those outcomes.
-
Insist on model governance and explainability: AI agents increase velocity but introduce model risk. Include minimum explainability and monitoring clauses in contracts.
-
Stress-test TCO for hidden line items: include cloud cost sensitivity (e.g., IPv4 charges), data egress, and incremental compute for model retraining as part of procurement models.
-
Design for composability: select vendors that provide API-first integrations and clear data contracts to avoid lock-in and to enable best-of-breed orchestration.
-
Plan workforce transitions: redeploy CS resources to proactive retention and expansion motions while automating low-value administrative tasks.
-
Build privacy-by-design into data pipelines: treat emerging state privacy requirements and European enforcement as a design constraint, not a checklist add-on.
How to use this preview
This article is a strategic preview intended to convey the report’s utility for 2026 planning. PW Consulting’s full Customer Churn Software Market Report contains the complete year-by-year market sizing series, detailed vendor profiles and scoring, granular segmentation by deployment model, organization size, vertical and region, and downloadable financial models and procurement templates. To preserve the report’s commercial value and to prevent misuse of market detail in public summaries, we have intentionally withheld the granular segment-level splits and tactical vendor scoring from this preview.
If your investment committee, procurement team, or customer-success leadership requires an accelerated decision package, our practice offers tailored briefings, vendor shortlists matched to your environment, and hands-on implementation advisory to compress the evaluation and PoC cycle from months to weeks.
Contact PW Consulting to arrange a briefing or to license the full report and the editable TCO/ROI models that support 2026 budget cycles and multi-year roadmaps.
For detailed analysis of this topic, please visit the official page: Customer Churn Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com