

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Educational & Training Software Market Poised for Rapid Expansion — 15.12% CAGR Forecast Through 2032

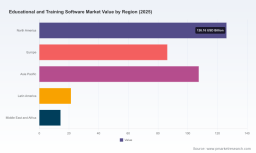
Educational and Training Software Market — Strategic Imperatives for 2026
PW Consulting’s latest market research on the Educational and Training Software Market provides a sharply actionable, executive-grade playbook for 2026 decision-makers. Anchored in five years of historical analysis (2020–2025) and a multi-scenario forecast through 2032, the report translates rapid market expansion, technology disruption, and evolving regulation into clear, prioritized choices for vendors, enterprise buyers, and investors.
Predictive Behavioral Analytics Softwares Market
Why 2026 is a Pivotal Year
The sector’s structural momentum is unambiguous. Between 2020 and 2025 the global market more than doubled, reflecting widespread digitalization across K‑12, higher education and corporate learning. By our base year (2025) the market has reached a scale that makes platform selection, content strategy, and AI governance strategic rather than purely tactical concerns. Looking forward, our forecast shows a sustained compound annual growth rate (CAGR) of 15.12% for the 2026–2032 period, with the market roughly trebling over the forecast horizon under the baseline scenario.
Pharma Grade Conjugated Linoleic Acid Market
For leaders planning budgets and M&A in 2026, this combination of scale and growth shifts the calculus: investments in interoperability, data governance, and AI-enabled learning pathways offer outsized returns relative to incremental content spend. Conversely, lagging on standards and compliance will create asymmetric downside as regulatory scrutiny tightens.
Oil Property Monitor Market
What PW Consulting’s Report Delivers
- Actionable market sizing and scenarios: A validated historical series to 2025 and three forward-looking scenarios through 2032 that quantify upside risk and downside contingencies for planning cycles and board discussions.
- Decision frameworks: Vendor selection matrices, ROI triangulation tools, and procurement scorecards tailored to distinct buyer personas (e.g., national education ministries, universities, enterprise L&D functions).
- Technology adoption blueprints: Roadmaps for migrating to cloud-native platforms, integrating generative AI capabilities, adopting standards-based assessment engines, and operationalizing data privacy controls.
- Go‑to‑market playbooks: GTM frameworks for vendors seeking to prioritize product investments, channel partnerships, and pricing models in 2026, with sample KPIs and churn-minimization tactics.
- Vendor and competitive heatmaps: Tactical profiles and capability assessments of the sector’s leading providers—highlighting differentiation vectors without disclosing proprietary benchmarking scores in this release.
- Compliance and risk mitigation modules: Practical checklists to align AI-enhanced offerings with emerging regulatory regimes, including high-risk AI classifications and data-protection expectations.
Key Strategic Insights for 2026 Decision-Making
- Prioritize composable architectures: Buyers should favor platforms that support modular integration—LMS, assessment engines, content repositories, and analytics services—because the pace of innovation (especially in AI) will make monolithic solutions brittle. The economics of switching costs and incremental functionality strongly favor composability in vendor evaluations.
- Invest early in AI governance and explainability: With generative AI now embedded in product roadmaps and national initiatives promoting AI literacy, organizations must build governance controls around pedagogical validity, bias mitigation, and auditability. Our practical templates enable procurement teams to score AI features on safety and pedagogical alignment.
- Turn compliance into a competitive asset: The regulatory environment — including guidance and enforcement in 2026 from supranational and national bodies — will redefine procurement criteria. Vendors that bake in compliance and transparent model governance will unlock larger public-sector contracts and partnerships.
- Measure learning impact, not just engagement: As customers demand demonstrable outcomes, focus metrics should shift from time-on-platform to competency attainment, transfer-to-job outcomes, and longitudinal ROI. The report’s outcome-mapping methodology helps buyers construct defensible business cases.
- Consolidation opportunity, but with an innovation premium: Market concentration remains moderate; the three- and five-firm concentration ratios indicate room for scale plays as well as specialist vertical winners. Strategic M&A that preserves product differentiation while accelerating cloud and AI capabilities will be rewarded.
Competitive Landscape: Who’s Moving and Why It Matters
The market’s leading commercial players are executing a mix of platform expansion, vertical specialization, and AI-led product innovation. Our qualitative analysis of incumbents and fast-scaling challengers reveals distinct strategic postures:
- Platform aggregators and marketplace players (e.g., Coursera): These providers are leveraging university and corporate partnerships to broaden credentialing, micro-credential pathways, and degree-completion offerings. Their competitive strengths lie in content breadth, brand association with top-tier institutions, and marketplace economics that scale well with demand.
- Consumer-first education apps (e.g., Duolingo): With engagement-driven product design and gamified learning loops, consumer apps are moving into adjacent categories (math, coding, soft skills) and proving the viability of learning-as-a-service models that can be adapted for corporate skilling.
- LMS incumbents (e.g., Instructure, Anthology/Blackboard): These firms maintain footholds in institutional procurement cycles. Their near-term challenge and opportunity is integrating AI-assistive tooling while modernizing architectures to support cloud-native deployment and seamless analytics.
- Corporate content specialists (e.g., Skillsoft, Pluralsight): Focused on professional reskilling and technical skill development, these vendors are competing on content depth, skill-path curation, and integration with enterprise HR systems and skill taxonomies.
- Cloud and platform titans (e.g., Microsoft, Google): Their strategic advantage is ecosystem integration—productivity suites, identity and device management, and increasingly, AI developer tooling. Recent 2026 initiatives from major cloud providers underscore the move to embed learning tools directly into daily workflows.
Recent developments—such as new AI-powered educator tools from major cloud providers, product innovations that automate personalized learning journeys, and national upskilling initiatives—validate our thesis that the race in 2026 is as much about platform ecosystem control as it is about content quality.
Regulatory and Macro Drivers to Watch
- AI-specific regulation: Emerging frameworks classify particular AI applications in education as higher risk and impose requirements for transparency, human oversight, and performance documentation. These regimes will meaningfully affect vendor roadmaps and procurement specifications in 2026.
- Public upskilling initiatives: Governments are rolling out AI-literacy and workforce development programs that create large-volume, low-margin demand — attractive for platform players that can deliver scalable, auditable outcomes.
- Standards and interoperability momentum: There is growing adoption of technical and data standards to enable credential portability and learning record stores; organizations that align early will reduce integration costs and accelerate cross-institution collaboration.
How PW Consulting Recommends Organizations Act in 2026
- For buyers: Run short, focused pilot programs that test composable integrations and learning-outcome metrics before committing to enterprise-wide deployments. Use the report’s procurement scorecards to compare vendors on governance, interoperability, and measurable outcomes rather than headline features.
- For vendors: Prioritize modular API-first designs, invest in robust AI safety and explainability features, and pursue partnerships that extend credentialing pathways into bona fide career outcomes. Consider disciplined bolt-on acquisitions that accelerate AI content creation or assessment automation.
- For investors: Target companies with defensible channels into public education and enterprise HR systems, clear paths to margin expansion via cloud economics, and demonstrable KPIs on learning-to-job transfer.
What We’re Not Releasing Here (and Why)
To preserve utility for procurement and investment workflows, the full report contains granular segmentation by deployment model, sector, region and product type, alongside vendor benchmarking scores and proprietary revenue splits. This release intentionally showcases strategic conclusions and practical tools while withholding the detailed subsegment tables and exact vendor metrics that organizations rely on for procurement or M&A diligence. That level of granularity is available in the full report and supporting data package.
Next Steps for Executives
PW Consulting’s report is designed to be immediately operationalizable in 2026 planning cycles. Clients can license the full dataset and toolkit for use in procurement RFPs, M&A diligence, and enterprise L&D strategy workshops. For executives preparing 2026 budgets, our recommendation is to reallocate a portion of content spend toward platform modernization, AI governance, and measurable outcome pilots—steps that the full report quantifies and prioritizes by expected ROI.
To explore the complete dataset, vendor profiles, and buy/sell playbooks, please consult the full PW Consulting publication and supporting tools on our website. Our analysts are available for tailored briefings and scenario workshops to translate the research into an actionable 90‑day roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Educational and Training Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com