

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CMO Services Market Set to Expand at a 13.5% CAGR (2026–2032), New Report Finds

CMO Services Market 2026: A Strategic Preview — Why This Report Will Shape Your 2026 Decisions
Executive summary
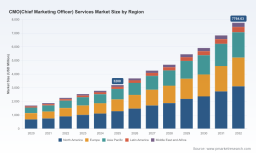
As organizations recalibrate growth playbooks in an AI-accelerated, outcome-driven era, PW Consulting’s new CMO Services Market report (base year 2025) delivers a tactical intelligence package designed for executive decision-makers. The global CMO services market has evolved from roughly USD 1.70 billion in 2020 to USD 3.20 billion in 2025, and our modelling projects expansion at a compound annual growth rate (CAGR) of 13.5% through the 2026–2032 forecast window. By 2026 the market crosses into the mid‑billion range and, under our baseline scenario, approaches USD 7.76 billion by 2032. That trajectory reflects structural changes in talent sourcing, technology adoption and buyer economics — all core considerations for CMOs, procurement leads and private equity sponsors evaluating go‑to‑market investments in 2026.
Carbon Neutral Carpet Tile Market
Why this matters for 2026 strategy
-
Talent arbitrage is now strategic. The accelerating adoption of fractional and interim senior marketing leadership allows organizations to access C‑suite capabilities without the fixed-cost burden of full‑time hires. Our market modelling shows this shift materially influences marketing operating models and long‑term cost baselines.
Three Piece Flanged Ball Valve Market -
AI is everywhere, but maturity is rare. Approximately three quarters of marketing organizations report some level of AI adoption, yet only a sliver have mature, repeatable implementations. That creates a strategic opening for advisory and fractional leaders who can translate AI capabilities into measurable revenue impact.
3D Braiding Machine Market -
Buyers demand outcome-linked engagements. Cost comparisons and performance benchmarks in our study indicate that firms using fractional CMO models often outpace peers in topline growth, reshaping how boards and PE sponsors evaluate marketing spend as a growth lever rather than a pure cost center.
What the report contains — operational, decision‑grade assets
The research is explicit in converting market insight into practitioner tools. Readers will find:
- Executive brief and 18‑month decision calendar for CMOs and procurement teams to prioritize hires, vendor pilot windows and budget reallocation.
- Scenario modelling (base, accelerated, and downside) driven by macro adoption curves and technology maturation timelines — including sensitivity to AI enablement and macroeconomic variability.
- Vendor selection framework and scorecard: objective criteria for assessing fractional CMO firms and integrated advisory partners across capabilities, delivery model, pricing transparency, regulatory competence and measurable KPIs.
- Commercial frameworks: modular contracting templates, outcome‑based pricing playbooks, and a practitioner’s guide to blending retained advisory with performance incentives.
- Implementation blueprints: 90/180/360‑day activation plans mapped to capability gaps (demand generation, product‑marketing alignment, PLG/SLG integration, and marketing operations modernization).
- AI adoption roadmap for marketing leaders: use cases prioritized by revenue impact, implementation complexity and data readiness, plus a vendor short‑list and governance checklist.
- Performance measurement pack: KPI scorecards and simple ROI models that translate marketing inputs into revenue outcomes and cashflow impact for CFO discussions.
- Case studies and anonymized benchmarks drawn from client engagements and market signals to illustrate typical uplift curves and risks.
Market dynamics: what our analysis reveals
-
Structural growth is robust. The overall market nearly doubled between 2020 and 2025 and, at a projected CAGR of 13.5% across 2026–2032, the services market will remain a high‑growth segment of the marketing ecosystem. Growth is being driven by three converging forces: the commoditization of tactical marketing execution, increased C‑suite comfort with flexible leadership models, and the monetization of AI‑enabled capabilities.
-
Fractional leadership is maturing. Public data and platform signals show rapid adoption of fractional leadership constructs — profiles referencing fractional roles have exploded over recent years — and organizations are increasingly treating fractional CMOs as strategic partners rather than stopgaps. Firms that institutionalize these relationships — through clear KPIs and contractual design — capture disproportionate value.
-
Performance delta matters. Our synthesis of sector studies and client datasets indicates materially stronger growth for companies that leverage experienced fractional CMOs and strategic advisory partners. This phenomenon is reinforcing buyer willingness to shift budget from headcount to flexible specialist engagements.
-
Competitive intensity remains low at the top. Market concentration metrics show a fragmented vendor base: the top three and top five providers account for relatively modest shares of total market activity, creating both opportunity and vendor selection risk for buyers seeking scale, specialization or regulatory depth.
Competitive landscape — key players and strategic moves
The vendor environment combines established fractional leadership specialists with newer growth engineering and AI‑first boutiques. Our report provides a comparable analysis of leading firms, highlighting positioning, sector focus and capability differentials. Selected strategic observations include:
-
Chief Outsiders: A broad fractional CMO platform with deep penetration of mid‑market and PE‑backed portfolios. Recent executive additions signal sharpened focus on AI‑enabled marketing transformation and sector diversification into healthcare and infrastructure — moves that read as deliberate steps to expand capability depth and enterprise credibility.
-
CMOx: A process‑oriented provider emphasizing repeatable frameworks for marketing function development and scalable growth. Their methodology appeals to organizations seeking to industrialize marketing practices rather than episodic advisory.
-
Kalungi: B2B SaaS specialists with strong playbooks around positioning and T2D3 growth mechanics — attractive to scaling software vendors that need GTM rigor and product‑led/ sales‑led integration.
-
NoGood and other growth engineering shops: Distinctive for high‑velocity experimentation and analytics‑first approaches, often the choice for growth teams prioritizing rapid hypothesis testing and optimization.
-
W‑2 embedded models and compliance‑focused firms: Several providers offer embedded leadership and compliance expertise for regulated industries, which is an important consideration for healthcare and financial services buyers.
Recent vendor developments — including targeted hires and service expansions — underscore a market in active consolidation by capability rather than price. Buyers should treat executive additions and service launches as leading indicators of vendor intent: are they deepening domain expertise, scaling delivery capacity, or simply broadening market messaging?
Practical implications and recommended actions for 2026
-
Prioritize outcome‑linked pilots. Run short, measurable engagements (90–180 days) with clear revenue or funnel KPIs. Use the report’s pilot template to set success thresholds and de‑risk longer commitments.
-
Design a blended operating model. Mix embedded leadership, fractional expertise and specialist execution partners to balance continuity and speed. The report’s org design scenarios provide prescriptive role definitions and handoff matrices.
-
Invest in AI governance before scale. With broad AI adoption but low maturity, companies that establish data, model and measurement guardrails now will capture disproportionate advantage when mature use cases emerge.
-
Use the vendor scorecard. Evaluate providers not just on CVs but on demonstrable playbooks, commercial alignment (risk‑reward split) and measurable ramp timelines. Our scorecard weights those dimensions for buyers across enterprise, PE and SME contexts.
-
Measure marketing as a growth lever. Translate marketing plans into cashflow outcomes; use the report’s ROI templates to make the case to treasury and the board.
How to use this release — the “trailer” approach
This bulletin demonstrates the depth and practical orientation of the full PW Consulting report while preserving proprietary segment tables, detailed vendor revenue splits and cell‑level forecasts — these are intentionally omitted here to protect analytical rigor and to ensure buyers access the complete dataset on our platform. The full report contains the benchmarking datasets, vendor scorecards, contracting templates and forecast scenarios that senior leaders need to operationalize the conclusions summarized above.
Next steps
-
Download the executive summary and access a sample scorecard on our report page (link in the official release). For procurement teams and CMOs planning 2026 budgets, schedule a ninety‑minute briefing with a PW Consulting lead analyst to walk through scenario implications for your organization.
-
For boards and PE sponsors: request the “board pack” variant of the report — a condensed, decision‑focused bundle that aligns marketing investments to valuation drivers and exit timing considerations.
PW Consulting’s CMO Services Market report is built for leaders who must make fast, defensible choices in 2026. It combines market foresight with practitioner playbooks — enough to act with confidence, and intentionally calibrated to direct decision‑makers to the full intelligence set available on our site.
For detailed analysis of this topic, please visit the official page: CMO(Chief Marketing Officer) Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com