

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Modified Phenolic Resins Market Poised to Grow at a 5.29% CAGR, 2025 Insight Forecasts

Modified Phenolic Resins Market: Strategic Imperatives for 2026 — PW Consulting Insights
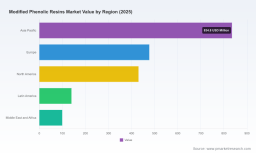
As global manufacturers recalibrate for a new phase of industrial demand, Modified Phenolic Resins are re‑emerging as a strategic material class for adhesives, inks, coatings, friction materials and foundry applications. PW Consulting’s latest market model shows a steady expansion trajectory: the global market that stood below USD 1.6 billion in 2020 has approached the USD 2.0 billion mark by the 2025 base year, and our forecast projects continued growth at a compound annual growth rate (CAGR) of roughly 5.3% through 2032. For decision‑makers planning capex, sourcing and product strategy in 2026, that growth—coupled with shifting feedstock dynamics and an accelerating sustainability agenda—creates a narrow window of competitive opportunity.
Calcium Titanate for Ceramic Capacitors Market
Why 2026 is a Strategic Inflection Point
-
Supply‑side geometry is changing. Phenolic resins historically ride on the economics of phenol and downstream thermoset demand; between 2020 and 2025 we observed volatile but manageable swings in overall market value. With phenol prices moderating in 2025 and forecast ranges for 2026 dependent on benzene fundamentals, procurement teams must balance short‑term cost relief with medium‑term supply risk.
Separation and Purification Media Market -
Decarbonization and biomass substitution are now operational realities. Leading producers are commercializing lignin‑modified and other bio‑derived modifiers—reducing lifecycle carbon footprints while preserving performance attributes. These launches are not niche PR; they are influencing procurement specs and OEM sourcing decisions in plywood, friction applications and selected industrial end‑uses.
Self-curing Acrylic Resin Market -
Market structure favors focused differentiation. The industry’s concentration metrics indicate that top players command meaningful share without creating an impenetrable oligopoly—leaving room for specialized suppliers, toll manufacturers and regional champions to exploit niches or vertically integrate. This fragmentation underlines the strategic value of focused product and channel plays over blanket scale expansion.
-
Regulatory and customer requirements—especially on emissions and formaldehyde—are tightening selectively across jurisdictions. Manufacturers that can demonstrate lower emissions and certified biomass content are gaining preferential access to specification lists in construction and wood products sectors.
What the Report Delivers — Practical, Actionable Intelligence
We designed the Modified Phenolic Resins Market report as an operational toolkit for executives and technical leaders, not a static desk reference. Key deliverables include:
-
A robust market forecast model (2026–2032) with scenario branches covering demand‑led, supply‑shock and decarbonization accelerations—built to be re‑run with client‑specific inputs.
-
Supply‑chain stress tests and raw‑material sensitivity analyses that translate phenol, benzene and propylene movements into P&L and working capital impacts for typical resin portfolios.
-
Go‑to‑market blueprints for premium and commodity segments, including channel economics for tolling versus direct manufacture, and recommended KPIs for integration.
-
Commercial playbooks for low‑emissions product launches, including regulatory alignment, certification roadmaps and pricing levers that preserve margin while enabling volume adoption.
-
M&A / partnership screening—rapid assessment templates to identify bolt‑on assets, local tollers or biomass feedstock partners that deliver near‑term revenue accretion and long‑term resilience.
Competitive Landscape: Reading the Leaders
Our competitive analysis synthesizes corporate strategy, product portfolios and recent initiatives to reveal where incumbents are placing their bets. Several archetypes emerge:
-
Heritage formulators with sustainability R&D: Companies such as Sumitomo Bakelite and Prefere Resins are leveraging deep resin know‑how to commercialize lignin and other biomass‑modified grades. These players are moving beyond pilot announcements to industrialized offerings—an important signal that biomass substitution is migrating into mainstream procurement conversations.
-
Specialty, high‑performance-focused formulators: Hexion, DIC and SI Group continue to concentrate on electronics, aerospace and automotive niches that demand strict thermal, dielectric or mechanical performance. Their engineering sophistication enables higher ASPs and lower exposure to commodity cyclicality.
-
Toll manufacturers and regional champions: Plastics Engineering Company (PLENCO), Capital Resin Corporation and several agile players in Asia (including Polyols & Polymers) provide configurable supply models and multiple delivery formats—pastilles, powders, liquids—that large OEMs use to de‑risk manufacturing and shorten qualification cycles.
-
Integrated industrial suppliers: Producers with wood‑product, insulation or construction affiliations (e.g., Georgia‑Pacific Chemicals, Kolon Industries) use backward or forward integration to lock demand and optimize resin formulations for specific downstream processes.
Recent commercial moves underscore these dynamics. Notably, a major Japanese manufacturer commercialized a resol‑type lignin‑modified product in late 2024, marketing demonstrable lifecycle carbon benefits and certification credentials. That launch crystallizes two trends—first, that biomass substitution can be introduced without compromising key performance attributes; second, that credible third‑party certification amplifies commercial uptake by risk‑averse specification owners.
Raw Materials & Cost Dynamics to Watch in 2026
-
Phenol price trajectory. After peaking in earlier cycles, phenol softened through 2025. Market intelligence shows phenol moving from roughly USD 1.05/kg to the low‑USD 0.9x/kg band by 2025, with 2026 consensus reflecting a range driven by benzene fundamentals and recovery in adjacent polymer sectors. Procurement teams should plan for mid‑cycle volatility and embed dynamic price triggers into long‑term contracts.
-
Benzene and propylene linkage. Upstream feedstock swings—especially benzene and propylene—remain primary drivers of phenolic resin production cost. Regional cost differentials will persist, and North‑Asia sourcing economics warrant focused analysis for companies operating global supply footprints.
-
Biomass feedstock economics. Lignin and CNSL pathways are maturing but have distinct supply profiles and processing costs compared with petrochemical feedstocks. Early movers should quantify not only raw material costs but also processing CAPEX and certification timelines when modeling total cost of ownership.
Strategic Playbook for 2026: Five Actions for Executives
-
Operationalize feedstock diversification. Convert pilot bio‑formulations into commercial lines where upstream partnerships and certification can be secured. Prioritize feedstock trials that minimally disrupt existing cure and process windows to accelerate customer qualification.
-
Adopt scenario‑based procurement. Move from static long‑term contracts to blended strategies that combine fixed‑price volumes, indexed volumes and rolling call‑offs. Use the report’s sensitivity model to quantify how phenol swings map to EBITDA and to set hedging thresholds.
-
Differentiate through formulation services. For resin producers, offer application engineering and co‑development as a bundled service—this raises switching costs and shifts competition from price to value.
-
Fast‑track regulatory compliance as a commercial lever. Achieving demonstrated reductions in VOCs and formaldehyde, and securing biomass credentials, creates privileged access to spec lists in wood paneling, plywood and OEM parts specifications.
-
Execute selective M&A and toll partnerships. Identify regional tollers or specialty formulators that can be integrated quickly to capture demand in high‑growth subsegments without heavy CAPEX outlay.
Where PW Consulting Adds Value
PW Consulting’s report is designed for executives who need to act in 2026. Beyond the headline forecast and qualitative context, our deliverables include downloadable financial models, supplier heatmaps, qualification roadmaps for bio‑modified grades, and M&A playbooks tailored to different corporate archetypes (integrator, specialist, toll partner). We also package an interactive workshop that applies the model to a client’s portfolio, yielding a prioritized, executable roadmap with quantified ROI and implementation timelines.
We intentionally preserve granular segmentation tables and company‑level financials for the full report: this article follows a “trailer” principle—demonstrating methodological depth and strategic implications while directing commercial audiences to the complete data set for transaction‑grade decision‑making.
Next Steps
For procurement leads, product managers and corporate strategists, 2026 will be a year to convert optionality into differentiated capability. If you are planning raw‑material commitments, product launches, or inorganic moves in the resin space, access to segmented forecasts, supplier scorecards and our sensitivity engine is essential. Contact PW Consulting to license the full Modified Phenolic Resins Market report and schedule a tailored strategy session to convert the forecast into an executable action plan.
For detailed analysis of this topic, please visit the official page: Modified Phenolic Resins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com