

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Elastomeric Polyurethane Roof Coatings Market to Grow at a 6.8% CAGR, Reaching USD 1,625.15 Million by 2032

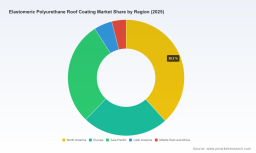
Worldwide Elastomeric Polyurethane Roof Coating Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study, "Worldwide Elastomeric Polyurethane Roof Coating Market (Base Year 2025) — Strategic Outlook 2026–2032," translates complex market dynamics into operationally useful guidance for procurement leaders, product strategists, investors, and corporate development teams preparing decisions in 2026. The market is no longer just about formulation science or price-per-gallon: it is an intersecting story of raw‑material supply swings, regulatory shifts, and consolidation dynamics that will materially shape margin, specification and sourcing choices over the next planning cycle.
Mobile Solar Container Market
High‑level trajectory: the numbers that matter
Our study tracks the market through a six‑year historical series and delivers a 2026‑2032 forecast. The global elastomeric polyurethane roof coating market grew steadily in the 2020–2025 period and is estimated at roughly USD 1.025 billion in the base year (2025). Our forecast points to continued expansion in 2026 and beyond, supported by a compound annual growth rate (CAGR) of 6.8% through 2032, with the market approaching the mid‑to‑high‑USD‑millions range by the end of the forecast window. Market concentration is meaningful but not prohibitive: the three largest players account for a little under two fifths of value, while the top five capture a little over half—conditions that favour both scale players and well‑positioned niche innovators.
Electric Energy Metering Cubicle Market
Why this report is a strategic asset for 2026 planning
- Translate macro trends into procurement playbooks: understand how near‑term raw‑material momentum and policy moves translate into contract terms, hedging targets and working capital needs.
- Prioritise R&D and portfolio investment: determine whether to favour single‑component moisture‑cure systems, two‑component systems, or hybrid approaches given evolving site conditions, specification trends, and lifecycle cost drivers.
- Fine‑tune commercial strategy: use a defensible, scenario‑based view of demand to redesign pricing ladders, rebate programs, distributor margins and warranty constructs for 2026 launches.
- Identify M&A and collaboration windows: map attractive target profiles and realistic valuation bands under multiple raw‑material and regulatory scenarios.
Core dynamics shaping 2026 decisions
Three interlocking dynamics will dominate tactical and strategic choices in 2026:
Zinc-Oxygen Air Battery Market
- Raw material volatility and supplier posture. The feedstock cycle has shown material movement recently — with significant short‑term downward correction in MDI pricing followed by upstream manufacturers signalling price countermeasures. Buyers need active cost‑model sensitivity to MDI/TDI and polyol moves rather than relying on static assumptions.
- Trade policy and regional supply risk. Escalating trade measures on certain feedstocks and ongoing antidumping reviews create a two‑track sourcing landscape: onshore/balanced inventories versus opportunistic import sourcing as duties and trade remedies evolve.
- Regulatory and specification pressure. Environmental policy is shifting product selection and application methods. Phasedowns and import restrictions on certain blowing agents and HFC‑containing formulations are already influencing specification language and will increasingly be reflected in procurement tenders and public‑sector RFPs.
Competitive landscape — what we observed and why it matters
Our competitive review synthesises company positioning, recent product and specification activity, channel footprints and formulation distinctions across a broad set of incumbents and specialists. Key takeaways:
- Global formulators with system offerings (e.g., Sika Corporation). These organisations compete on integrated system claims (membrane + coating + warranties), channel depth, and spec‑level visibility. They are favoured in large commercial projects that prioritise single‑source responsibility.
- Regional specialists and formulators (e.g., Polycoat Products, Inland Coatings, UPI, Tremco). These firms win on application depth, nimble reformulation, and contractor relationships. Recent updates to product specifications and package sizes signal tactical moves to capture restoration and retrofit workstreams where logistics and labour efficiency matter.
- Technology and niche players. Companies that emphasize low‑odor, low‑VOC, UV‑stable aliphatic topcoats, and moisture‑curing single‑component systems retain technical differentiation that can be monetised through premium specs or reduced installation risk.
- Emerging suppliers from lower‑cost production bases. They are penetrating certain channels, especially where price‑for‑performance acceptance thresholds are lower. Trade measures and quality assurance expectations will determine how quickly such entrants scale in developed markets.
Notable, actionable signals in the competitive set: Inland Coatings’ specification releases and package size updates in 2025 reflect a deliberate push to standardise restoration workflows and logistics efficiency — an example of how product packaging and spec language can be deployed as competitive levers without material formulation changes.
What the full report contains — practical tools for execution
PW Consulting’s report is designed as a practitioner’s toolkit. Key deliverables include:
- Interactive market model (2020–2032) with scenario toggles for MDI/TDI price swings, tariff outcomes and regulatory milestones so finance and procurement can quantify upside and downside exposure.
- Actionable supplier scorecards that map capability (formulation range, claim substantiation, warranty, spec references), logistic footprint, and counterparty risk.
- Application‑level playbooks (commercial, residential retrofit, industrial) with recommended product choices, installation productivity benchmarks, and lifecycle cost comparisons tailored to common roofing substrates.
- Regulatory compliance checklist and suggested contract provisions to mitigate phasedown and import restriction risks for both suppliers and buyers.
- Deal playbook for M&A and partnerships that includes valuation diagnostics, earn‑out structures keyed to material price normalization, and buyer integration risks.
- Procurement templates and RFP language that operationalise product‑level performance clauses, acceptable substitute rules and audit rights.
As a preview, we present market direction and the aforementioned tools; detailed subsegment tables (type-by-application-by-region), granular price curves, and the full supplier benchmarking matrices are reserved for the complete report and interactive dashboards available on the PW Consulting portal.
Practical use cases — how executives should apply these insights in 2026
- Chief Procurement Officers: Use the scenario model to size working capital needs under alternate tariff and feedstock outcomes, and to set forward‑buy thresholds for critical polyols and isocyanates.
- Head of Product/R&D: Prioritise development of low‑VOC moisture‑cure systems and aliphatic topcoats where specification tailwinds intersect with lower installation risk—validate via field pilots that include life‑cycle cost inputs from our model.
- Commercial Leaders: Rework distributor contracts to reflect differentiated technical services and installation training; target warranty and specification sweet spots where competitors are weaker.
- Corporate Development / PE Investors: Use the competitive concentration metrics and supplier scorecards to identify consolidation targets or partnership candidates whose value unlock depends primarily on distribution scale or specification access.
Risk scenarios and early warning indicators
The report includes three scenario tracks to frame 2026 choices: (1) supply oversupply and price softening, (2) policy‑driven supply tightness with elevated duties, and (3) technology‑led specification shifts towards low‑emission systems. Each track is associated with early warning indicators we monitor monthly — including spot spreads for key isocyanates, trade remedy filings, and major public‑sector specification updates — enabling rapid course correction.
Next steps — how to convert insight into advantage
For leaders who need to convert this analysis into 90‑day actions and 18‑month programs, the recommended next steps are:
- Acquire the full report and interactive model to run organisation‑specific scenarios against your raw material exposure and mix of single‑ vs two‑component sales.
- Commission a focused procurement stress‑test to translate scenario outcomes into supplier contracting and inventory strategies.
- Initiate pilot projects for priority product variants identified by our go‑to‑market scorecards, capturing both performance and installer time‑and‑motion data.
- Use the supplier scorecards to update approved vendor lists and refine warranty and acceptance criteria in upcoming bids.
PW Consulting’s Worldwide Elastomeric Polyurethane Roof Coating Market report is built to inform the key tradeoffs executives face in 2026: speed to market versus specification integrity, short‑term cost savings versus long‑term warranty risk, and domestic resilience versus import opportunism. For the complete data tables, supplier matrices and interactive scenario model that underpin these recommendations, please visit the PW Consulting report page to access the full deliverable and schedule a briefing with our industry specialists.
For detailed analysis of this topic, please visit the official page: Worldwide Elastomeric Polyurethane Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com