

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Tonsil Cancer Treatment Market to Top USD 1.54 Billion by 2032, Growing at a 6.42% CAGR
By pmarketresearch, 2026-08-18
Worldwide Tonsil Cancer Treatment Market — Strategic Insights for 2026 Decision-Makers
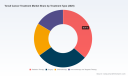
PW Consulting today releases a forward-looking industry brief that synthesizes clinical, regulatory, commercial and payer dynamics shaping the worldwide tonsil cancer treatment market. Built on a rigorous base year of 2025 and a historical series from 2020–2025, our modeling shows the market reached approximately USD 996.0 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 6.42% through 2032, exceeding USD 1.5 billion by the end of the forecast window. This release is designed as a strategic “trailer” for executives, investors and clinical leaders who must make high-consequence choices in 2026; it demonstrates the depth and utility of our analysis while reserving detailed, segment-level datapoints for the full report.
HBM Controller IP Market
Why this report matters for 2026 planning
- Convergence of clinical breakthroughs and regulatory movement. A major perioperative immunotherapy approval in 2025 has already reconfigured treatment sequencing for resectable locally advanced disease, creating near-term demand pressures and long-run shifts in standard of care.
- Moderate market concentration shapes competitive dynamics. The market shows meaningful concentration among the largest oncology players, indicating that collaboration, licensing and targeted M&A will materially change competitive positions in 2026.
- Commercial and supply-chain policy shocks require rapid strategic responses. Emerging trade and manufacturing mandates are elevating nearshoring and capacity planning to board-level priorities.
- Payer scrutiny and patent lifecycle effects will compress margins for incumbent product portfolios while elevating premium pricing for late-stage, biomarker-driven therapies.
What PW Consulting’s report delivers — practical, transaction-ready intelligence
Our report is structured to be immediately operational for teams forming 2026 budgets, clinical development plans and commercial plays. Deliverables include:
Card Grading Services Market
- Market sizing and forecast (base year 2025; forecast 2026–2032) with scenario pathways tied to regulatory timelines, clinical readouts and reimbursement changes.
- Competitive landscaping that maps incumbent portfolios and late-stage pipelines to strategic imperatives (e.g., perioperative immunotherapy adoption, ADCs in HPV-positive disease).
- Playbooks for commercialization and access: pricing sensitivity matrices, payer negotiation templates, and formulary positioning checklists tailored to oncology market dynamics.
- Go-to-manufacturing and supply-chain decision framework addressing tariff exposure, capacity ramp calendars, and cost-to-serve modeling for on-patent vs. biosimilar eras.
- Clinical and regulatory scenario models that quantify the commercial impact of accelerated approvals, biomarker-driven label expansions, and negative trial outcomes.
- M&A and partnering heatmaps identifying capability gaps (e.g., ADC manufacturing, HPV-vaccine–peripheral immunotherapy combos, companion diagnostics) prioritized by strategic fit and execution risk.
- Actionable dashboards enabling executive briefings: customizable slide decks, investor-ready executive summaries, and an interactive model for sensitivity testing.
Competitive landscape — players, strategic postures and implications
The tonsil cancer treatment ecosystem blends large diversified oncology franchises with agile biotech innovators advancing modality-shifting assets. Key dynamics we highlight in the report include:
Data Encryption Storage Market
- Incumbent immunotherapy leaders have moved from metastatic settings into perioperative treatment paradigms. One leading PD-1 agent secured regulatory approval for neoadjuvant and adjuvant use in PD-L1–selected resectable head and neck disease in mid‑2025, accelerating hospital pathway redesigns and creating opportunities for companion diagnostics and perioperative services.
- Established oncology firms continue to support their positions through combination strategies — pairing checkpoint inhibitors with cytotoxics, radiation sensitizers, or targeted antibodies. These combinations increase both clinical complexity and commercial leverage, especially in hospital-based care pathways.
- Specialty biotechs are driving modality innovation. Antibody–drug conjugates (ADCs) and vaccine‑platform immunotherapies have advanced into late-stage development with regulatory alignment meetings in 2025, presenting candidates that could materially alter the treatment mix for HPV-positive oropharyngeal and tonsil cancers.
- Diagnostic and biomarker strategies are central. PD‑L1 expression and HPV status are increasingly determinative for therapeutic selection; firms that combine therapeutic assets with validated diagnostics command premium positioning.
- Clinical and academic centers are influential catalysts. Major cancer centers that led trials supporting the latest regulatory approvals will continue to set standards of care and accelerate physician adoption — a channel effect that companies must actively engage.
Collectively, these forces contribute to a market where the top three competitors hold a meaningful share but leave substantial room for innovative entrants to capture niche and combination-driven segments.
Regulatory, reimbursement and supply-chain headwinds & catalysts
- Regulatory catalysts: The 2025 approval of perioperative immunotherapy marked the first major label evolution in several years for head and neck oncology. That pathway has lowered the barrier for subsequent label extensions and has increased the visibility of surrogate endpoints in trial design.
- Reimbursement pressure: Oncology drug spending remains strongly affected by patent lifecycles. The post-patent entry environment drives rapid price decline, while payers promote generics/biosimilars through formulary design and cost-sharing structures. Companies must model erosion timelines and construct tiered access strategies.
- Trade and manufacturing risk: New import tariff regimes effective in late 2025 create a binary economics for manufacturers: invest in domestic manufacturing to avoid punitive tariffs or accept substantially higher cost structures for international supply. This is a near-term capital allocation decision for 2026.
- Cross-border treatment availability: Novel cellular therapies and certain advanced immunotherapies are available under EU standards before U.S. approval in some cases, creating treatment tourism and differential adoption curves that affect global demand projections.
Practical takeaways for executive decision-making in 2026
- Prioritize domestic manufacturing evaluations now. For companies with global supply footprints, our cost‑benefit simulations show accelerated onshore investment can materially reduce tariff exposure and protect net pricing in the U.S. market.
- Reprofile pipelines toward biomarker-led indications. PD‑L1 and HPV stratification are central to commercial value; late‑stage assets that include companion diagnostic strategies command higher uptake and more favorable reimbursement pathways.
- Design perioperative commercialization initiatives. Hospitals and surgical oncology networks are retooling care pathways; companies that support multidisciplinary adoption — through education, pathway resources and bundled contracting — will capture share faster.
- Model multiple regulatory scenarios in deal valuations. Accelerated approvals and conditional pathways increase upside but also raise execution risk; valuation models should stress-test both positive and negative pivotal outcomes.
- For payers and health systems: prepare coverage frameworks that balance short-term costs of novel perioperative regimens against longer-term reductions in recurrence and downstream treatment intensity.
- Investors should re-evaluate portfolio exposure to on-patent revenue cliffs and prioritize assets with durable market access constructs (diagnostics, unique mechanisms, or differentiated manufacturing).
How to use this “trailer” and where to find the full intelligence
This overview is intentionally calibrated to provide executive-grade context and to spotlight where decisive 2026 actions are required. The full PW Consulting Worldwide Tonsil Cancer Treatment Market report contains granular segmentations, region- and channel-level modeling, company market shares, primary research findings, five-year scenario matrices, and downloadable financial models. We have withheld detailed segmental tables and underlying raw datapoints from this summary to preserve the analytical integrity of the full report and to ensure high‑value engagement for subscribers seeking operational datasets.
PW Consulting offers tailored executive briefings, custom modeling engagements and data licensing for corporate planning and transaction due diligence. For organizations preparing budgets, revising pipelines, or evaluating manufacturing investments in 2026, the full report and an accompanying strategy workshop provide the practical tools necessary to convert insights into executable plans.
Contact PW Consulting to schedule a briefing and to obtain access to the complete dataset, including interactive scenario models and primary research appendices.
For detailed analysis of this topic, please visit the official page: Worldwide Tonsil Cancer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Formamidinium Iodide (FAI) Market to Soar from USD 62.5 Million in 2025 to USD 360.6 Million by 2032 at a 28.42% CAGR, Fueled by Ultra‑High‑Purity Demand in Perovskite Solar Cells
By pmarketresearch, 2026-08-18
Formamidinium Iodide (FAI) Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive summary
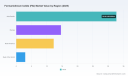
Formamidinium Iodide (FAI) has moved from niche reagent to strategic feedstock within the perovskite ecosystem. PW Consulting’s latest market study shows the FAI market expanding at a compound annual growth rate (CAGR) of 28.42% through our forecast horizon. The market has grown from an estimated USD 16.5 million in 2020 to USD 62.5 million in 2025 and — under our base-case modeling — is projected to exceed USD 360 million by 2032. For executives positioning portfolios, supply chains, and R&D roadmaps in 2026, this trajectory turns a once-tactical material purchase into a potential strategic choke point and a lever for differentiation in solar and opto-electronics value chains.
High Payload Robot Market
Why 2026 is a pivotal planning year
- Commercialization inflection: As perovskite cell efficiency and stability milestones converge with scalable manufacturing techniques, demand for high-performance precursors accelerates. Our demand model shows step-change adoption starting in 2026 as pilot lines transition to early commercial throughput.
- Cost and regulatory squeeze: High-grade FAI manufacturing requires specialized purification technology. PW Consulting’s costing analysis flags a roughly 30% increase in manufacturing expense for ultra‑high‑purity grades relative to standard grades, and regulatory classifications of certain iodine-containing precursors are adding incremental production costs where they apply (estimated +12–18% in affected jurisdictions).
- Strategic supplier selection matters: With market concentration moderate but meaningful (CR3 ≈ 42% and CR5 ≈ 58% in our coverage), buyers face realistic counterparty risk that can influence project timelines and margins. Procurement choices made in 2026 will shape access and price stability into the late 2020s.
Market trajectory and commercial implications
Our top-line numbers serve two functions: they quantify scale and they provide a framework for scenario analysis. The market’s implied growth profile — from the mid‑tens of USD million in 2020 to several hundred million by the early 2030s — reflects a combination of componentization in perovskite PV, increasing adoption in opto-electronic applications, and the premium placed on ultra‑high‑purity precursors for high-efficiency device architectures.
Acetyl L-Carnitine Powder Market
For corporate strategy, the arithmetic is clear: product roadmaps that assume low-cost, commoditized precursor supply risk margin compression as purity and regulatory demands push per‑unit costs higher. Conversely, players that secure differentiated supply sources, invest in upstream purification, or develop tolerance‑for‑impurities in device chemistry can capture disproportionate value.
Omega 3 Nutritional Supplements Market
Drivers, technical context, and regulatory overlays
- Technical advantage: FAI is the stoichiometric precursor for the formamidinium lead iodide (FAPbI3) family that exhibits a narrower bandgap (~1.48 eV) compared with methylammonium‑based perovskites (~1.57 eV). This physical property supports higher theoretical solar conversion efficiency and explains the premium placed on FAI in cell designs targeting higher-efficiency stack architectures.
- Purity economics: The performance gap narrows rapidly if impurities induce phase instabilities or trap states. Achieving ultra‑high purity necessitates additional capital equipment and process steps, which our industrial benchmarking pegs at near‑term cost premiums of roughly 30% versus standard grades. That premium is a material input into device LCOE calculations — and a strategic variable for both materials and device manufacturers.
- Regulatory risk: Evolving chemical classifications in multiple jurisdictions create a non‑trivial compliance and cost overlay. In regions where certain iodine‑containing precursors are regulated as high‑concern substances, manufacturers face permit hurdles, expanded testing, and higher operational expenses — our regional dynamics assessment estimates a 12–18% uplift in production cost where these rules apply.
Competitive landscape — who matters and why
The supplier universe spans small high‑precision specialty houses to larger firms with broad chemical portfolios. Our qualitative and comparative assessment identifies the following strategic archetypes:
- Specialist high‑purity producers: Companies that emphasize in‑house synthesis and ultralow moisture content control position themselves as partners for R&D and early commercial lines. Their strengths are process control, custom packaging for sensitive handling, and small‑batch flexibility.
- Scale‑oriented suppliers with industrial packaging: Firms offering bench‑to‑industrial supply and a diversity of packaging/quantity options are attractive to integrators moving from lab to pilot line, because they reduce the friction of volume ramping.
- Broad distributors and catalog players: These firms facilitate rapid access for research and prototyping but may lack the process improvements and documentation industrial customers require for scale‑up or regulatory compliance.
- Vertically integrated or listed manufacturers: Some manufacturers combine broader chemical portfolios and capital access, enabling investments in purification lines, regulatory programs, and supply security initiatives more readily than small specialists.
Across these archetypes, the competitive battleground centers on three axes: purity and moisture control, supply continuity and scale, and regulatory / documentation capabilities (e.g., REACH compliance, material safety data fidelity, and alternative precursor traceability). In our supplier heatmaps, each named firm is evaluated against those criteria to support buy‑side prioritization (detailed scorecards are reserved for the full report).
Key strategic moves for corporates in 2026
- Secure staged supply commitments: Negotiate two‑tier agreements that bind initial R&D volumes while enabling conditional volume increases tied to pilot‑to‑commercial milestones. Include quality‑by‑lot reporting and moisture limits as contract triggers.
- Pursue selective vertical integration or strategic partnerships: For device manufacturers with high volume targets, backward integration into precursor production — or long‑term tolling/contract manufacturing agreements — materially reduces exposure to spot volatility and regulatory shock.
- Invest in impurity tolerance R&D: Materials science options that reduce reliance on ultra‑high‑purity feedstock (e.g., compositional engineering, additive strategies, defect passivation) can convert raw material premiums into device performance resilience.
- Build regulatory and compliance playbooks: Implement region‑specific mapping of classification risk and associated cost impacts. Quantify how permitting timelines could affect project milestones and embed contingency buffers in rollout plans.
- Prioritize supplier due diligence: Beyond price, evaluate moisture control protocols, trace metal analysis, process reproducibility, and secondary sourcing options. Our report provides a due‑diligence checklist tailored to FAI procurement.
What PW Consulting’s FAI Market report delivers (practical, action‑oriented)
This release is intentionally a strategic preview. The full report equips executives with the operational tools needed to translate market insight into decisions — without disclosing the proprietary segment models that underpin our consulting work. Core deliverables include:
- Scenario‑based market modeling (base, upside, downside) with sensitivity levers for purity premiums, regulatory cost uplifts, and adoption curves for perovskite commercialization.
- Supplier scorecards and short‑list methodology: a repeatable framework to evaluate purity control, scale readiness, documentation practices, and commercial terms. (Note: full supplier rankings and detailed metrics are part of the paid deliverable.)
- Procurement playbook and template contract language: staged volume commitments, quality acceptance testing, traceability clauses, and penalty structures for non‑conforming batches.
- Regulatory impact matrix and compliance roadmap: jurisdictional mapping, likely permitting timelines, and mitigation tactics to neutralize the estimated 12–18% regional cost uplift where applicable.
- Technology readiness and R&D prioritization guide: where to invest in device chemistry vs precursor supply, and how to evaluate the ROI of internal purification capacity.
- M&A and partnership screening criteria: identifying targets for bolt‑on purification capabilities, tolling agreements, or downstream offtake paths aligned with your commercial timeline.
Competitive callouts — how leading suppliers are being positioned
Across the supplier universe, several tactical differentiators stand out. Some firms emphasize ultra‑high purity production with extremely low moisture content and small‑batch flexibility, making them natural partners for early adopters and device developers. Others combine industrial packaging and bench‑to‑industrial supply chains to facilitate volume scaling. Global distributors play the role of fast access and catalog convenience but may require supplemental QA documentation for industrial adoption. Finally, listed and larger manufacturers bring capital to expand purification capacity and support regulatory programs faster than smaller players.
How to use this preview in 2026 planning
- Use the market growth rates and the directional size forecasts here to stress‑test capital allocation and procurement budgets for pilot and early commercial projects.
- Assess whether to lock in long‑term supply now, hedge through diversified sourcing, or invest in purification capacity — guided by your exposure to device performance sensitivity to precursor purity.
- Factor regulatory cost adders into LCOE and margin models and prioritize jurisdictions where compliance pathways are clearer or faster to execute.
Next steps — obtaining the full advisory package
This preview is designed to establish the strategic contours and to prompt executive action. PW Consulting’s full Formamidinium Iodide Market report contains the proprietary segment analysis, supplier rankings, and executable templates that procurement, corporate development, and R&D teams need to act in 2026. For access to the full dataset, supplier scorecards, and tailored advisory engagements, please contact PW Consulting via our official channels to arrange delivery of the complete deliverable and optional deep‑dive workshops.
For detailed analysis of this topic, please visit the official page: Formamidinium Iodide (FAI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Houttuynia Extract Market to Reach USD 284.26 Million by 2032 at a 7.02% CAGR — Asia‑Pacific Leads with USD 102.09 Million in 2025
By pmarketresearch, 2026-08-18
Worldwide Houttuynia Extract Market: Strategic Intelligence to Shape 2026 Decisions
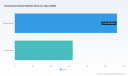
PW Consulting today publishes an executive briefing—derived from our full Worldwide Houttuynia Extract Market report (base year 2025)—designed to inform the high-stakes commercial and regulatory choices companies must make in 2026. Our macro model shows the industry expanding from an estimated USD 126.4 million in 2020 to USD 176.8 million in 2025, and we project continued growth to roughly USD 284.3 million by 2032 at a compound annual growth rate (CAGR) of 7.02%. These headline figures reflect accelerating demand across personal care, nutraceutical and specialty pharmaceutical pathways and justify renewed strategic attention from ingredient manufacturers, brand owners and investors.
Worldwide Acid and Alkali Etching Resistant Ink Market
Why this briefing matters for 2026 strategic decisions
- Actionable foresight: The market’s mid-single-digit CAGR hides pockets of asymmetric opportunity driven by extraction technology, formulation stability and certification premiumization—areas where early movers can secure sustainable margins.
- Risk-adjusted sourcing: Raw material variability and historical regulatory events mean that procurement decisions in 2026 must be assessed against botanical quality metrics, seasonal variability and manufacturing traceability.
- Commercial timing: With ingredient innovation producing new claims and stability outcomes, 2026 is a pivotal year to convert R&D into differentiated SKUs before competitive noise intensifies.
What the full report delivers (practical, executable content)
- Integrated market model: A reconciled historical series (2020–2025) and an explicit forecast (2026–2032) with scenario stress-tests for demand shocks, price movements and regulatory tightening.
- Go-to-market playbooks: Stepwise commercialization roadmaps for ingredient suppliers, contract manufacturers and brands—covering product positioning, pricing architecture, distributor selection and sample-to-shelf timelines.
- Supplier scorecards and sourcing matrix: Multi-dimensional supplier assessments (quality control, traceability, certifications, capacity, lead times) and a decision tool to align sourcing strategy to target applications.
- Technology and extraction benchmarking: Comparative analysis of powder vs. liquid extract production, ultrasonic and solvent extraction impacts on yield and bioactivity, and recommendations for capital allocation into process upgrades.
- Regulatory and safety dossier: A practical regulatory matrix addressing historical adverse event contexts, excipient considerations, label claims and country-specific acceptance pathways relevant to 2026 launches.
- Formulation & stability dossiers: Evidence-based guidance for integrating Houttuynia extracts into cosmetics, supplements and topical therapeutics—highlighting formulation strategies proven to mitigate instability and irritation risks.
- M&A and partnership playbook: Candidate profiles for bolt-on acquisitions, due-diligence checklists and valuation sensitivity analyses anchored to EBITDA and production capacity metrics.
- Commercial KPIs & negotiation templates: Benchmarks and contract clauses for minimum order quantities, quality acceptance criteria, testing protocols and price-review mechanisms tailored for 2026 supplier negotiations.
Competitive landscape — how the manufacturing base stacks up
The Houttuynia extract sector remains fragmented: top-three producers control a modest share of the market (CR3 ≈ 18.5%), and a wider top-five concentration (CR5 ≈ 24.2%) confirms significant room for consolidation. Our qualitative assessment identifies a set of active manufacturers and ingredient suppliers that represent the diversity of capabilities in the ecosystem:
Drone Inspection System Market
- Shaanxi Fairir Biotech (Shaanxi, China; https://www.fairirbiotech.com) – A specialist in customized, wholesale botanical extracts with strengths in large-batch powder supply and global distribution channels.
- Xi'an Demeter Biotech Co., Ltd. (Xi'an, China; https://www.demeterherb.com) – Noted for strict quality controls and positioning on the natural medicinal attributes of Houttuynia.
- Sinochem Nanjing (Nanjing, China; https://www.sinochem-nanjing.com) – An accredited factory that emphasizes rigorous in-process testing, appealing to customers prioritizing consistent safety and efficacy.
- The Garden of Naturalsolution Co., Ltd. (Korea) – Focused on cosmetic ingredient formats and ultrasonic extraction techniques; recent product listing activity underscores a push into higher-margin personal care channels.
- Plum Flower (USA; https://1stchineseherbs.com) – A U.S.-based provider serving brands that require domestically-sourced regulatory and supply assurances for traditional herb extracts.
Beyond these recognizable names, dozens of regional players supply commodity powder and liquid extracts. Our supplier heatmaps in the full report translate this topology into prioritized shortlists for private label, co-manufacturing and long-term strategic supply agreements.
Hand Controlled Robotic Arm Market
Scientific and regulatory dynamics shaping 2026
Two threads will define near-term technical differentiation: extraction-method-driven bioactivity and a sharpened regulatory lens. Recent scientific publications—covering the effects of extraction methods on polysaccharide structure and cosmetic formulation stability of Houttuynia essential oil—demonstrate how process variables materially change functional outcomes. Manufacturers that invest in validated extraction platforms and provide robust analytical dossiers will command premiums.
Regulatory memory remains important. Historical adverse-reaction reports tied to injectable formulations and excipient-related safety reviews have left a durable footprint on approval pathways and labeling expectations. For ingredients intended for topical or ingestible use, the 2026 regulatory playbook requires explicit documentation of excipients, allergen testing and batch-level traceability—factors our report operationalizes into checklist and sample dossier templates.
Raw-material quality: a non-linear value driver
Variability in plant metabolite profiles across geography, harvest season, and plant part creates both risk and opportunity. Differences in saccharide and flavonoid composition—documented in recent phytochemistry studies—mean sourcing decisions must be purpose-built to the target application (e.g., anti-inflammatory cosmetic claims versus nutraceutical endpoints). Our sourcing toolkit converts laboratory metrics into commercial procurement specifications so buyers can avoid costly reformulations or claim retractions downstream.
Recent market movements that matter for 2026 plays
- Product listings and ingredient updates from personal care suppliers signal intensified marketing for redness- and sensitivity-focused claims—brands should expect an uptick in supplier-led claim packages.
- Peer-reviewed studies on extraction methods and essential oil stability validate investments in ultrasonic and novel solvent systems, creating a near-term advantage for process-savvy producers.
- Continued disclosure around historical safety events stresses the need for transparent quality records; companies lacking end-to-end traceability will face longer onboarding cycles with Tier-1 customers.
Strategic recommendations for executives in 2026
- Prioritize supplier qualification with botanical intelligence: require harvest-date, plant-part and metabolite profiling as part of routine contracts.
- Invest selectively in extraction and analytical capabilities—either in-house or via partners—to convert process performance into defensible product claims.
- Lock in regulatory-ready documentation: cultivate clinical-standards-ready dossiers that anticipate stricter labeling and excipient scrutiny.
- Differentiate via formulation support: offer co-development services and stability data to brand customers rather than selling commodity material alone.
- Consider bolt-on acquisitions or long-term offtake contracts to secure feedstock and shorten time-to-market for high-value applications.
- Build a staged go-to-market plan: pilot in personal care where speed-to-shelf and marketing claims can be monetized, then scale into nutraceutical or therapeutic categories as clinical evidence accrues.
How to use this briefing and where to go next
This release is a strategic preview designed to orient 2026 planning. To preserve the tactical integrity of market participants—and to ensure the full utility of our commercial models—we have intentionally withheld granular regional and application-level segment tables from this summary. The full report contains those detailed segmentations, price-benchmark matrices, supplier scorecards and downloadable datasets that procurement, R&D and corporate development teams will use to operationalize the recommendations above.
For organizations preparing RFPs, reassessing supplier portfolios, or building 2026–27 product roadmaps, the full Worldwide Houttuynia Extract Market report from PW Consulting provides the data, playbooks and templates needed to convert insight into measurable value. Contact PW Consulting to request the full report and access the models and appendices that underpin the strategic guidance summarized here.
— PW Consulting, Strategic Intelligence & Industry Analysis
For detailed analysis of this topic, please visit the official page: Worldwide Houttuynia Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Degradable Implants Market to Expand from USD 6.85 Billion in 2025 to USD 11.93 Billion by 2032, Backed by an 8.25% CAGR
By pmarketresearch, 2026-08-18
PW Consulting Releases Strategic Brief: Degradable Implants Market — A 2026 Playbook for Market Leaders and Challengers
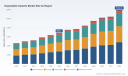
PW Consulting today publishes a strategic briefing drawn from our forthcoming Degradable Implants Market report, designed to equip executive teams with the evidence and decision frameworks they need as they allocate R&D, regulatory and commercial capital in 2026. The degradable implants market has moved from scientific promise to commercial reality: after a market value of USD 4,608.7 million in 2020, PW’s model projects continual expansion—reaching USD 6,850.5 million in 2025 and accelerating into the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 8.25%, with our 2032 projection exceeding USD 11.9 billion. For leaders preparing budgets, partnerships and regulatory dossiers for next year, this report translates high-level growth into executable options while preserving the detailed segment data behind a gated model.
Rare Earth Battery Alloys Market
Why this report matters for 2026 decision-making
- Translating growth into strategy: The macro expansion is real, but winning requires choices—material selection, clinical evidence prioritization and commercialization sequencing—that determine whether a program is accretive or dilutive to enterprise value.
- Regulatory and evidence timing: The regulatory pathway for bioresorbables is now characterized by heightened scrutiny on long-term biocompatibility and mechanical performance across degradation timelines; timing of clinical milestones materially affects market access windows and ROI.
- Supply chain and cost management: Specialized magnesium alloys and precision manufacturing materially raise component costs versus conventional implants; supply concentration in primary magnesium production adds a volatility premium that must be hedged.
- Competitive posture: The market displays a moderate concentration (CR3 ≈ 42.5%; CR5 ≈ 56.8%)—enough room for scale players to defend incumbency but also for focused innovators to create lucrative niches.
What the PW Consulting report delivers (practical outputs)
- Comprehensive market sizing and 2026–2032 forecast with bottom-up and scenario-based projections that isolate demand drivers and sensitivity to reimbursement and pricing.
- Technology and materials mapping—polymers, ceramics, magnesium alloys and emerging biological matrices—linked to manufacturing cost envelopes and scale economics.
- Regulatory and clinical roadmap: stepwise requirements (including ISO 10993 biocompatibility frameworks), recommended study designs to demonstrate mechanical equivalence through degradation, and timing templates for FDA/EMA submissions.
- Supplier and OEM intelligence: vendor scorecards, margin corridor analyses, and contract manufacturing profiles to accelerate production scale-up without compromising regulatory traceability.
- Commercial playbooks: GTM sequencing, hospital procurement strategies, value dossiers for payers and clinicians, and launch KPIs for trauma, orthopedic reconstruction and cardiovascular scaffold applications.
- Deal and investment suite: M&A heatmaps, licensing models, and joint-venture archetypes informed by CR3/CR5 concentration and technology ownership.
- Interactive financial model and data annex (gated): full segment splits, unit economics, and sensitivity levers available to subscribers and licensed users.
Competitive landscape: how incumbents and specialists are positioning
The competitive topology is bifurcating along two axes: large orthopedics/medtech incumbents leveraging commercial reach and regulatory expertise, and specialist innovators driving material-level differentiation.
Paper Coffee Filter Market
- Specialist innovators — Firms such as Bioretec Ltd and Syntellix AG have staked leadership in magnesium-based solutions and are translating clinical-first positioning into regulatory milestones. Bioretec’s RemeOs magnesium alloy portfolio earned the industry’s first FDA De Novo clearance in its class and has since accrued further regulatory momentum (including a Breakthrough Device designation for a RemeOs DrillPin and CE approvals supporting European commercialization). These regulatory achievements shorten commercial lead times for novel metallic resorbable fixation and create a reference set for competitors. Syntellix’s MAGNEZIX line similarly demonstrates how metallic degradables can scale clinically when combined with strong device-level evidence and regional certifications.
- Polymer specialists and platform owners — Companies such as Inion Oy have commercialized polymer-based, bioabsorbable plates, screws and anchors across multiple specialties and boast substantial clinical usage; their strengths lie in integrated polymer platforms and well-developed clinical adoption pathways.
- Large medtech incumbents — Major OEMs (including Medtronic, Johnson & Johnson / DePuy Synthes, Stryker, Zimmer Biomet and Smith+Nephew) are actively incubating or acquiring bioresorbable capabilities to protect franchise value and address surgeon demand for absorption-enabled workflows. These players bring scale in distribution, hospital contracting and payer engagement—critical advantages when converting clinical approvals into unit volumes.
- Cardiovascular niche players — Biotronik’s resorbable scaffold programs underscore that the cardiovascular use-case has a distinct evidence and reimbursement arc compared with orthopedics, requiring dedicated registries and HTA engagement strategies.
Regulatory, material and supply dynamics to watch in 2026
- Regulatory rigor is the new baseline: FDA and EMA expectations now routinely include long-term in vivo degradation studies and proof of mechanical equivalence across the degradation lifecycle; sponsors should budget for multi-year programs and plan staged submissions to sustain investor confidence.
- Magnesium economics and sourcing: Development of medical-grade magnesium alloys increases unit production costs—our analysis shows a meaningful premium relative to conventional materials—and primary magnesium supply is regionally concentrated. China’s dominance in upstream magnesium production drives a potential price and availability volatility that can distort margin models for manufacturers absent mitigation strategies.
- Clinical evidence and HCP adoption: Surgeon familiarity, instrumentation compatibility and real-world registries will be decisive in adoption speed, especially for pediatric and trauma applications where device removal avoidance is a clear clinical value proposition.
Strategic actions for 2026: a practical playbook
- Secure material supply and manufacturing continuity: Negotiate multi-year supply contracts with quality clauses, explore geographic diversification for critical alloys, and assess vertical integration where scale economics justify capex.
- Invest early in degradation-focused evidence: Prioritize preclinical and early clinical studies that demonstrate mechanical competence through critical healing windows—this de-risks reimbursement conversations and accelerates regulatory acceptance.
- Design commercialization pilots intelligently: Launch in clinical centers of excellence to build registry data, refine surgical technique training, and create KOL advocates before broad roll-out.
- Align pricing to differentiated value: Account for production cost differentials (notably for magnesium-based implants) and build payer dossiers that quantify savings from avoided hardware removal, reduced secondary procedures and shortened care pathways.
- Consider partnership-first approaches: For many innovators, licensing to or co-developing with a larger OEM reduces time-to-scale and leverages established sales channels while preserving upside through milestone and royalty structures.
- Model multiple scenarios: Run downside and upside scenarios tied to regulatory timelines, magnesium price shocks and hospital adoption rates; use contingent investment tranches to protect cash runway.
How PW’s intelligence accelerates your 2026 roadmap
Executives who use PW’s degradable implants intelligence gain access to a practical combination of macro forecasts, competitive scorecards and executable playbooks that reduce uncertainty at three critical decision gates: R&D prioritization, regulatory sequencing and commercialization sequencing. The report’s gated models allow clients to interrogate unit economics under custom assumptions—isolating the impact of material costs, scaling efficiencies and pricing strategies on IRR and payback.
Portable LED Light Facial Device Market
Access and next steps
This release is a strategic synopsis designed to demonstrate the report’s analytic depth while preserving the granular segment tables, regional splits and company-level scorecards that form the paywalled core. Firms planning capital allocation, M&A or partnership strategies for 2026 should engage PW Consulting for a tailored briefing and demo of the interactive forecast model.
To request a briefing, licensing terms for the interactive model, or to arrange a private strategy workshop for your leadership team, contact PW Consulting’s Life Sciences Strategy practice. Our consultants can map the outputs of this study to your product portfolio, regulatory timelines and commercial channels so you can move from insight to action in 2026 with confidence.
For detailed analysis of this topic, please visit the official page: Degradable Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Spin Electronics Market to Reach USD 2.76 Billion by 2032 at 12% CAGR — STT‑MRAM Leads with USD 604.11 Million in 2025
By pmarketresearch, 2026-08-18
Worldwide Spin Electronics Market — Strategic Outlook 2026: Navigating a 12% CAGR Landscape
Executive snapshot
As organizations set priorities for 2026, spin electronics (spintronics) is transitioning from specialist R&D to boardroom-level strategic planning. PW Consulting’s latest Worldwide Spin Electronics Market report — with a 2025 base and a 2026–2032 forecast window — synthesizes market dynamics, technology trajectories, regulatory vectors, and competitive positioning into a practical playbook for executives, investors, and product leaders. The market, which advanced from a modest industrial base in 2020 to roughly USD 1.25 billion in 2025, is projected to continue expanding at a robust compound annual growth rate of 12% through our forecast horizon, surpassing USD 2.7 billion by 2032. That macro momentum underpins a rapid maturation cycle and creates discrete windows for strategic action in 2026.
Worldwide Optical Character Recognition (OCR) Software Market
Why 2026 is an inflection year
-
Commercial validation: Following several product launches and research milestones in 2024–2026, a set of spintronic technologies is moving from laboratory proof-of-concept into qualified product families suitable for mainstream OEM adoption.
Worldwide Pro AV Solutions Market -
Standards & measurement: Metrology and standardization initiatives are reducing technical uncertainty. National and international programs are actively defining measurement protocols and testbeds, which will shorten qualification timelines for suppliers and buyers alike.
Worldwide Automobile Electric Power Steering Systems Market -
Supply chain and policy attention: Critical materials and conflict-minerals regulations are framing supplier selection and risk management strategies, making material sourcing a strategic procurement imperative rather than a sourcing footnote.
-
Concentration dynamics: The market exhibits moderate concentration — the top three and five players capture substantial shares — offering both partnership opportunities with market leaders and niches for specialized entrants.
Market trajectory and what it means for strategy
Spin electronics is demonstrating sustained volumetric growth and commercialization acceleration. After a multi-year compound expansion that lifted the market from several hundred million dollars in 2020 to approximately USD 1.25 billion in 2025, our forecast anticipates continuation of a roughly 12% CAGR through 2032. That growth trajectory has three practical implications for 2026 decision-making:
-
Timing investments: Companies deciding whether to invest in spintronic-enabled product lines or to integrate spintronic memory/sensors into existing portfolios should treat 2026 as a timing inflection — early movers can secure design-wins and influence ecosystem standards, while fast-followers should focus on interoperability and supply security.
-
Portfolio prioritization: Given the pace of technology maturation, portfolio managers must assess trade-offs between committing to single-vendor technology stacks versus modular architectures that allow substitution as component performance and supply landscapes evolve.
-
Risk-adjusted valuation: Investors and corporate development teams need updated assumptions on TAM expansion and an informed view of concentration metrics to price M&A and minority investments appropriately.
Technology roadmap: from memory to compute-in-memory
Spintronics no longer sits solely within memory research labs. It is emerging into multiple system-level roles: non-volatile embedded memory options are reshaping SoC designs; magnetoresistive sensors are finding new niches in harsh-environment and automotive applications; and novel spin-based devices are being explored for compute-in-memory and photonic-spintronic interfaces. These technology pathways carry distinct adoption profiles and integration requirements — some demand foundry partnerships and process integration, others require system-level architecture changes. PW Consulting’s report maps these pathways across a maturity axis and provides actionable gating criteria for adoption decisions, including qualification timelines, expected reliability envelopes, and integration cost breakouts.
Supply chain, materials, and regulatory vectors
Spintronic devices depend on specialty metals and complex thin-film stacks. Material risks — including availability and regulatory constraints around certain strategic metals — are material to commercial outcomes. At the same time, standardization efforts and new metrology programs are lowering technical uncertainty. Together, these forces are reshaping procurement strategies and supplier risk profiles. Our analysis translates material and policy signals into operational checklists: supplier dual-sourcing thresholds, stock strategies, material substitution pathways, and compliance roadmaps to meet evolving conflict-minerals and export-control obligations.
Competitive landscape: what to watch in 2026
The spin electronics ecosystem blends specialized pure-plays, large semiconductor incumbents, and tool and IP providers. The market concentration we observe reflects a landscape where a handful of companies exert outsized influence on technology direction, but where innovation pockets remain accessible to agile entrants and research spin-outs. Key players include niche sensor and MRAM specialists, major memory and fab incumbents, and equipment and simulation providers whose tools accelerate device design.
-
Niche specialists with commercial product lines are capitalizing on direct-fit applications where spintronic properties give clear performance and reliability advantages. These firms are often preferred partners for early adopters seeking rapid design wins and bespoke integration support.
-
Large semiconductor and system firms are investing in spintronic architectures that promise lower-power compute and tighter memory-logic integration. Their scale enables ecosystem development but also raises the bar for new entrants who must demonstrate clear differentiation or niche economics.
-
Tool, IP, and modeling providers play an outsized role in de-risking spintronic development. Atomic-scale simulation tools, process IP, and foundry relationships are frequently decisive in shortening time-to-market.
Our vendor profiles go beyond public marketing claims to evaluate product maturity, manufacturability, go-to-market motion, and partnership ecosystems. The report also includes a pragmatic M&A watchlist and partnership archetypes for strategic scaling.
Recent industry inflection points (signal highlights)
-
Patent landscape activity shows active filings across STT- and SOT-based memory architectures and field-free two-terminal devices — signaling both defensive and platform-building strategies among research institutions and startups.
-
Commercial product announcements are accelerating: advanced photo-spintronic detectors and low-power spin-memristors have been publicly demonstrated, indicating potential step-changes in data transmission speeds and AI energy efficiency.
-
High-reliability, space-grade MRAM products have reached commercialization, marking readiness for demanding aerospace and defense applications where reliability and radiation tolerance are prerequisites.
-
National metrology and international standardization programs are actively progressing, which will reduce vendor lock-in risk and shorten qualification cycles for end-users.
What PW Consulting’s report delivers to 2026 decision-makers
Our report is structured to be directly operational for teams preparing 2026 roadmaps. Highlights include:
-
A consolidated market forecast, scenario variants, and sensitivity analysis that model different adoption-speed outcomes and their P&L implications.
-
Technology maturity maps and integration playbooks that identify the practical gating criteria (test plans, reliability targets, foundry requirements) for various spintronic device classes.
-
Supply-chain risk matrices and procurement strategies tailored to regulatory realities and critical material exposures.
-
Competitive benchmarking including vendor capability matrices, partnership archetypes, and a prioritized list of potential acquisition or alliance targets.
-
Actionable scenario planning worksheets and a 12–24 month tactical plan template to help product, sourcing, and corporate development teams convert strategy into deliverables.
Practical strategic recommendations for 2026
-
Adopt a two-track engagement model: secure short-term design-wins with proven suppliers while sponsoring co-development projects with research or pre-commercial partners to retain optionality on disruptive architectures.
-
Embed material governance in sourcing: implement traceability and substitution playbooks now to avoid downstream compliance and availability shocks.
-
Invest in metrology and qualification capabilities: firms that internalize key testing competencies will reduce time-to-market and lower dependency on external test houses.
-
Recalibrate R&D portfolios to favor architectures that demonstrably lower system-level energy consumption or materially improve system reliability; prioritize integrations that mitigate the von Neumann bottleneck through compute-in-memory trials where applicable.
-
Pursue strategic partnerships with tool and simulation providers to accelerate design cycles and capture early performance advantages.
Why this report matters for boardroom conversations
Spin electronics is not merely a component market; it is an enabler of new system architectures and business models. For boards and C-suite teams that must allocate scarce capital and set multi-year R&D priorities, PW Consulting’s report translates technical detail into economic consequence. It provides the frameworks to assess whether to incubate internal capabilities, buy into existing vendors, or form strategic alliances — while quantifying upside under different adoption scenarios.
Next steps and access
This article highlights high-level findings and strategic implications. Per the “teaser” principle, detailed segment-level datasets, regional breakdowns, technology-specific forecasts, and vendor-level revenue analyses are intentionally reserved for the full report and accompanying datasets. Executives requiring the granular inputs (including downloadable spreadsheets, scenario tools, and vendor dossiers) should consult the PW Consulting report page for secure access and advisory engagements to convert insight into action in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Spin Electronics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Forensic Lab Equipment Market Poised to Expand at a 7.15% CAGR (2026–2032)
By pmarketresearch, 2026-08-18
Worldwide Forensic Lab Equipment Market — 2026 Strategic Briefing
PW Consulting’s latest market study, Worldwide Forensic Lab Equipment Market (base year 2025; forecast 2026–2032), equips executive teams with the evidence-based intelligence required to make high-stakes decisions in 2026. The market reached USD 3,088.1 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 7.15% through the 2026–2032 forecast window, approaching USD 5,007.7 Million by 2032. This briefing distills the report’s strategic value: what leaders must act on now, what to monitor, and where to direct capital and capability investments to capture growth while managing regulatory and operational risk.
Disposable Suture Grasper Closure Device Market
Why this report matters for 2026 decision cycles
-
Capital allocation: With measurable mid-single-digit to high-single-digit growth ahead, organizations must sequence capex into high-impact platforms while preserving flexibility for rapid technology shifts (e.g., next‑generation sequencing, advanced mass spectrometry and digital forensics stacks).
HIV Antibody Diagnostic Reagent Market -
Vendor strategy: Our analysis differentiates suppliers by technology depth, service footprint, consumables dependency and regulatory posture — enabling procurement leaders to prioritize partner lists and contract models (purchase, lease, reagent lock-in).
Worldwide Liquid Optically Clear Adhesive (LOCA) Market -
Regulatory compliance: New quality and biosafety controls that took effect in 2026 materially change qualification timelines for instrument manufacturers and laboratory adopters; readiness is now a competitive requirement.
-
M&A and partnerships: The market’s moderate concentration opens selective opportunities for tuck-in acquisitions and strategic alliances to secure capability gaps (sample prep, bioinformatics and digital evidence management).
-
Operational transformation: Investments in NG‑LIMS, automation and digital evidence chains are no longer optional for high-throughput public forensic labs seeking throughput, reproducibility and auditability.
What’s inside the PW Consulting report — operationally actionable content
-
Transparent market sizing and modelling: historic series (2020–2025), base-year benchmarks (2025) and scenario-modeled forecasts for 2026–2032 with sensitivity ranges to stress-test strategic plans.
-
Practical buyer toolkits: RFP templates for capital equipment and LIMS, procurement scoring matrices, and total cost of ownership (TCO) calculators that incorporate instrument uptime, consumables, service and training.
-
Vendor scorecards and channel maps: comparative assessments across performance, regulatory readiness, installed base, service coverage and consumables economics — designed for immediate shortlisting.
-
Regulatory playbook: step‑by‑step compliance checklists reflecting the latest QMS and biosafety requirements, plus procurement redlines for contracts subject to grant or federal funding constraints.
-
Technology adoption roadmaps: prioritized investment pathways for small, medium and national forensic laboratories, covering sequencing, mass spectrometry, imaging, digital forensics and evidence‑handling automation.
-
Strategic scenarios: four alternative industry trajectories (base case, accelerated technology adoption, constrained funding, and regulatory tightening) with recommended responses for each.
Market dynamics and near-term catalysts
-
Workload and capability expansion: Persistent caseload growth, combined with rising expectations for higher resolution forensic outputs (genomics, trace chemistry and digital evidence), sustains demand for both instruments and integrated workflows.
-
Public funding and procurement rhythms: Targeted grants and capital programs remain a key demand engine for public forensic labs; timing of awards materially affects procurement windows and vendor revenue phasing.
-
Digital transformation: NG‑LIMS and evidence lifecycle management initiatives are accelerating, requiring integration of instruments, software and chain‑of‑custody systems — an ecosystem play that benefits vendors with software and services capabilities.
-
Regulatory inflection points: The industry is adjusting to updated quality management frameworks and biosafety controls implemented at the start of 2026, affecting product certification timelines and supplier qualification criteria.
Competitive landscape — strengths, risks and strategic levers
The report provides a granular competitive assessment of the market’s leading suppliers and adjacent players. A high‑level synthesis follows below to orient strategic conversations.
-
Thermo Fisher Scientific: Broad portfolio strength across DNA, mass spectrometry and integrated workflows; deep service and global install base make it a default partner for large laboratory networks.
-
Agilent Technologies: Strong analytical instrumentation footprint in GC‑MS and LC‑MS; differentiated applications support in forensic toxicology and chemical identification.
-
Waters Corporation: Specialization in LC‑MS platforms and related chemistries positions it well for toxicology and metabolite identification demands.
-
PerkinElmer: Cross‑domain capabilities (spectroscopy, chromatography, imaging) that support both DNA workflow augmentation and chemical forensics.
-
Danaher/SCIEX: High‑performance mass spectrometry systems and a focus on sensitivity and quantitative screening for drug and trace analysis.
-
QIAGEN and Promega: Leaders in sample prep, nucleic acid workflows and STR solutions; they are core to DNA workflow efficiency and reproducibility.
-
Illumina/Verogen: NGS‑forensics vendors enabling complex genomic analyses and higher‑order identification use cases, particularly in specialized forensic genomics labs.
-
Bruker, Shimadzu and Horiba/SPEX: Strong niche capabilities in spectroscopy, materials characterization and Raman analysis that address trace evidence and materials identification.
-
Sirchie and Lynn Peavey: Specialist providers for evidence collection, field consumables and crime scene workflow tools, whose offerings tie upstream collection to downstream lab processing.
Market concentration metrics indicate a moderate level of aggregation: the top three suppliers account for roughly 42% of market value, while the top five account for about 58%. That structure favors scale players with global service networks, but it leaves meaningful whitespace for specialty vendors and software/service disruptors.
Regulatory and policy intercepts that will shape 2026 choices
-
FDA Quality Management System Regulation (QMSR): Effective in early 2026, manufacturers of certain forensic instruments that fall under medical device frameworks now face tightened QMS expectations aligned with ISO 13485. Supplier qualification and product release processes must be re-evaluated.
-
LDT carve‑outs and forensic use: The final LDT policy retains an exclusion for tests intended solely for law enforcement, but suppliers and labs should document intended use claims carefully to avoid regulatory ambiguity.
-
BIOSECURE Act implications: New restrictions signed into law in late 2025 impose procurement and collaboration constraints for federally funded organizations around select biotechnology equipment and services.
-
Funding programs: Targeted grants (e.g., NIJ awards and other capital funding) continue to subsidize modernization, creating periodic spikes in demand that vendors and labs can exploit if procurement timing is synchronized.
Recommendations for executive teams (what to do in 2026)
-
Prioritize QMS and supply‑chain due diligence now. Instrument vendors and labs must align contracts, validation plans and supplier audits with the updated QMSR timelines to avoid deployment delays.
-
Adopt a modular procurement strategy. Favor platforms that allow staged capability upgrades (e.g., add-on NGS modules, software‑first analytics) to preserve budget flexibility.
-
Invest in integration and data pipelines. Early NG‑LIMS adopters that integrate instruments, chain‑of‑custody, and analytics will unlock measurable productivity and defensibility gains.
-
Use public funding strategically. Map grant cycles into procurement roadmaps and align vendor negotiations to match award timing to reduce working capital exposure.
-
Protect operational continuity through dual sourcing and service level agreements. Prioritize vendors with local service footprints or documented third‑party field support channels.
-
Pursue targeted M&A or technology partnerships. Buyers seeking rapid capability expansion should prioritize targets that add software, bioinformatics, or specialized consumable portfolios.
How to use PW Consulting’s report
-
CEOs and CFOs: Use the market scenarios and TCO models to size capex envelopes and prioritize investment tranches for 2026–2027.
-
Procurement and supply chain leaders: Leverage vendor scorecards and RFP templates to shorten procurement cycles and negotiate favorable lifecycle terms.
-
Product and R&D teams: Align roadmaps to regulatory timelines and identify partnership opportunities for rapid go‑to‑market.
-
Investors and corporate development: Apply the competitive analysis and concentration metrics to identify acquisition targets and partnership candidates that improve market positioning.
PW Consulting’s Worldwide Forensic Lab Equipment Market report is structured to be immediately operational: models, templates, vendor analytics and regulatory playbooks are included to accelerate decision-making in 2026. For full segmentation tables, vendor scorecards, downloadable financial models and the complete strategy playbook, visit PW Consulting’s report page and request the full dataset and advisory briefings.
For detailed analysis of this topic, please visit the official page: Worldwide Forensic Lab Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Germacrene D Market to Expand at 5.02% CAGR, Forecasting USD 29.3 Million by 2032 as Europe Leads with USD 8.08M in 2025
By pmarketresearch, 2026-08-18
Germacrene D Market: Strategic Briefing for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present an executive briefing derived from our full Germacrene D Market report (base year 2025, forecast 2026–2032). This note synthesizes the directional trends, competitive signposts, and tactical imperatives that will determine success in the year ahead. It is intentionally designed as a strategic “trailer”: we surface the analysis, models, and implications that matter most to corporate leaders while reserving the granular segment-level datapoints for the full report.
Perovskite Inks Market
Market Snapshot: A compact data-driven frame
Germacrene D has moved from niche botanical curiosity toward a commercially relevant aroma and specialty chemical across fragrance, agricultural pheromones, and pharmaceutical research applications. On a macro level, PW Consulting’s model shows the market expanding from roughly USD 20.8 Million in 2025 to a projected USD 29.3 Million by 2032, reflecting a 5.02% CAGR over the forecast window (2026–2032). The historical track (2020–2025) demonstrates steady recovery and incremental adoption as sustainable sourcing and biotechnology-enabled production paths have matured.
O-(Benzotriazol-1-yl)-N,N,N',N'-Tetramethyluronium Tetrafluoroborate Market
Two structural observations are essential for 2026 planning: first, demand is broadening beyond legacy perfumery uses into formulation and research niches; second, supply-side innovation—especially fermentation and improved botanical extraction—continues to reshape cost curves and compliance positioning. These forces create a market environment where nimble players can scale rapidly, but where differentiation through quality, sustainability credentials, and regulatory clarity matters more than ever.
Ammonium Ionic Strength Adjustor Market
Why this report matters for 2026 decisions
- Time-sensitive supplier choices: Procurement cycles in 2026 will be influenced by certification renewals, fermentation capacity ramps, and the availability of food- and cosmetic-grade product. Understanding which suppliers can deliver certified, pesticide-free, and food-grade Germacrene D at scale is a near-term strategic necessity.
- R&D prioritization: Product formulators need to decide whether to commit to natural-origin claims, high-purity reagent routes, or hybrid positioning. Our forward-looking synthesis links raw material sourcing to formulation cost and claims risk to help prioritize R&D roadmaps.
- M&A and partnership targeting: With a market structure that remains fragmented, there are targeted consolidation opportunities and JV plays—particularly around fermentation IP and secure feedstock arrangements—that merit active evaluation in 2026.
What the full report contains — practical, transaction-ready intelligence
The PW Consulting Germacrene D Market report is built to be operational from day one. Key deliverables include:
- Topline market sizing and validated growth paths (historical and forecast) with sensitivity scenarios under alternate feedstock and regulatory shocks.
- Price and margin benchmarking at multiple purity levels, with a supply-cost matrix that maps botanical extraction versus microbial fermentation economics.
- Supply chain heatmaps showing bottlenecks, single-source risk, and logistics chokepoints relevant to 2026 procurement windows.
- Regulatory and safety dossier synthesis (FEMA/GRA S status, RIFM safety conclusions, and applicable food and cosmetic regulations) to support marketing claims and product registration strategies.
- Supplier and technology scorecards (incl. fermentation capacity, sustainability certifications, and traceability practices) to accelerate vendor selection and due diligence.
- Commercial playbooks for market entry and scaling—pricing tactics, channel strategies, and co-development templates for fragrance houses and ingredient suppliers.
- Scenario-based M&A screens and a prioritized list of acquisition targets and partnership archetypes aligned to strategic objectives (capacity, IP, market access).
Note: The full report contains granular regional and application segment analytics, detailed price curves, and contract-level supplier performance metrics; these are intentionally omitted here to preserve the value of the source dataset.
Competitive landscape: who to watch in 2026
The Germacrene D ecosystem sits at the intersection of specialty chemicals, natural extractives, and industrial biotechnology. The landscape is fragmented: the leading few players together represent a modest share of total market revenue, leaving ample room for focused competition and targeted consolidation.
- Isobionics B.V. (Geleen, Netherlands) — A pioneer in fermentation-derived sesquiterpenes, Isobionics markets an 85% natural Germacrene D that is positioned for flavor and fragrance segments with multiple compliance credentials (including kosher and pesticide-free claims). Their bio-manufacturing route and certification focus place them as a strategic supplier for customers prioritizing natural-origin claims and supply resilience.
- Elchemy — Known for high-purity Germacrene D offerings aimed at fragrance and personal care formulators; Elchemy’s packaged high-purity products support customers that prioritize analytical specification control and reproducibility.
- Cayman Chemical — Serves the research chemicals niche and remains a go-to source for laboratory-grade Germacrene D. Their position illustrates the bifurcation between research-only supply channels and commercial-grade ingredient suppliers.
- Chemical Bull Pvt. Ltd. — An example of a manufacturer focused on high-purity production under strict quality control frameworks; players like this provide regional supply resilience and competitive pricing pressure in certain markets.
- Global fragrance and flavor houses (Givaudan, Firmenich, Symrise, Takasago, Robertet, Treatt) — These incumbent integrators continue to exert influence through proprietary extraction capabilities, sustainable sourcing programs, and strategic partnerships. Their activities—product launches, co-development arrangements, and supplier consolidation—will be the primary demand-shaping forces in 2026.
Recent industry moves underscore the strategic stakes: certification renewals and product launches in 2025 highlight the competitive premium assigned to verified natural claims and supply continuity. Collaborative partnerships between large fragrance houses and botanical suppliers signal a push toward vertically integrated, resilient sourcing models.
Supply chain and regulatory dynamics shaping 2026
- Dual sourcing paths: Germacrene D is supplied either via botanical extraction from essential oils or through microbial fermentation using renewable sugar feedstocks. Each path has distinct cost, scalability, and claim implications for buyers.
- Regulatory clarity: Several commercial offerings already hold recognized status for flavor and fragrance use under prevailing frameworks, and recent safety assessments have not indicated genotoxicity or sensitization concerns at customary use levels. This regulatory backdrop reduces near-term claim risk but elevates the importance of documented compliance and traceability for marketing.
- Certification as a competitive moat: Certifications (kosher, halal, pesticide-free, GRAS/type designations) materially affect addressable customers in food and premium personal care. Suppliers that maintain robust certification portfolios will capture a pricing premium and longer contract tenures.
Investment signal: fragmentation and where value will emerge
Market concentration metrics show that the sector is not highly concentrated among the top players, indicating both opportunity and risk. Fragmentation creates arbitrage for specialist entrants and consolidation targets for strategic acquirers. For corporate strategists and private equity investors targeting 2026 initiatives, three value-creation themes should guide evaluation:
- Scale & integration: Acquire or partner with fermentation capacity or secure long-term botanical sourcing to lock in margins and claims.
- Certifications & traceability: Invest in certifications and digital traceability to enable premium positioning in food, cosmetic, and natural claims segments.
- Application adjacency: Expand into pheromones and niche pharmaceutical research supplies where technical specification and purity command higher ASPs.
How to use this analysis in 2026 planning
Leaders should treat Germacrene D as a strategic ingredient with differentiated risk-return profiles across sourcing channels. Recommended next steps for functional teams:
- Procurement: Run parallel qualification tracks for at least two suppliers—one fermentation-based, one botanical—to hedge against feedstock and certification risk.
- R&D/Product Development: Pilot dual-claim prototypes (natural-origin vs. high-purity synthetic) to learn consumer acceptance and cost implications before large-scale launches.
- Corporate Development: Launch targeted screens for bolt-on M&A and JV candidates that provide capacity, certification, or channel access; prioritize assets enabling near-term margin improvement.
- Regulatory & Quality: Consolidate documentation required for food/cosmetic claims and integrate supplier audits into annual compliance calendars to avoid disruptive delistings.
Closing — where to find the full intelligence
PW Consulting’s Germacrene D Market report is purpose-built to inform 2026 strategy, procurement, and M&A decisions with transaction-grade analytics and supplier intelligence. This briefing highlights the strategic contours and actionable implications while preserving the granular segmentation, pricing curves, and supplier scorecards that constitute the report’s proprietary value.
Executives and investment teams seeking the complete dataset—including regional and application splits, contract-level supplier metrics, and scenario-based pricing models—should consult the full report to convert these strategic signals into concrete plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Germacrene D Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Lead Pin Surface Treatment Chemicals Market at USD 1,354.7 Million (Base Year 2025), Forecast to Reach USD 2,133.02 Million in 2032 at a 6.74% CAGR (2026–2032) — Asia Pacific (USD 813.85M) and Electroplating Solutions Lead
By pmarketresearch, 2026-08-18
Worldwide Lead Pin Surface Treatment Chemicals Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s newest market research release on the Worldwide Lead Pin Surface Treatment Chemicals Market delivers forward-looking intelligence designed for executives and strategy teams planning for 2026 and beyond. Grounded in a rigorous base year of 2025 and a historical review covering 2020–2025, our forecast scenario extends to 2032. At the market level, revenues reached approximately USD 1,354.7 Million in 2025 and are projected to grow to roughly USD 2,133.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.74% over the 2026–2032 forecast window. These headline dynamics underline sustained demand expansion and meaningful opportunity for differentiated players across chemistry, process design and integrated packaging ecosystems.
Worldwide Drones for Petroleum Market
Why this report matters for 2026 strategic planning
-
Actionable forecasting: The 6.74% CAGR we model is not a top-line projection only — it is decomposed by macro drivers, technology adoption pathways and regulatory inflection points so leaders can prioritize near-term investments without sacrificing long-term resilience.
Disposable Blood Pressure Sensor Market -
Timing and prioritization: 2026 is a pivotal year for many organizations as supply chains reset post‑pandemic, materials costs remain volatile, and environmental regulations accelerate reformulation efforts. Our analysis highlights when and where pressure points will most likely materialize so firms can sequence capex, R&D and commercial initiatives to capture upside.
Laboratory FTIR Spectrometers Market -
Risk‑adjusted scenarios: We provide alternate scenarios that stress-test plans under adverse raw material price swings and progressive regulatory constraints, enabling decision-makers to calibrate hedging strategies and build contingency playbooks.
What the report delivers — practical content for operators and investors
-
Executive dashboards and model access: Dynamic market models (Excel) that allow you to re-run growth scenarios against user-defined assumptions for metal salt costs, VOC limits and plating-line throughput.
-
Go-to-market playbooks: Tactical roadmaps for chemical manufacturers and coatings formulators, including product prioritization matrices, channel strategies and customer segmentation frameworks tailored to lead‑pin and connector ecosystems.
-
Regulatory impact toolkit: A hands‑on guide mapping REACH, EPA and regional phasing timetables to product reformulation imperatives and compliance milestones. The toolkit includes a decision tree for selecting substitution strategies (e.g., chrome-free options, low‑VOC chemistries) across common process flows.
-
Supply chain stress tests: Heat maps and supplier consolidation indices that expose concentrated input risks and logistics bottlenecks — with mitigation playbooks such as dual-sourcing approaches, inventory hedging thresholds and toll-manufacturing arrangements.
-
Competitive benchmarking: Proprietary vendor scorecards covering product portfolio breadth, R&D cadence, regulatory preparedness and global footprint, enabling procurement and corporate development teams to shortlist candidates for partnerships, M&A or strategic alliances.
-
Commercial case studies: Real-world examples showing how formulators reduced hazardous constituents while preserving yield and cycle-time, plus examples of customer conversion economics for eco-friendly alternatives.
Competitive landscape — leaders, challengers and the implications for 2026
The market displays moderate concentration with a CR3 of approximately 41.5% and a CR5 near 56.9%, indicating that a handful of established chemistry providers continue to exercise meaningful influence while mid-sized and regional specialists retain opportunities to capture niche value. Our competitive assessment focuses on companies that demonstrate deep process knowledge, regulatory track records and the ability to support complex electronic packaging flows.
-
Technic Inc. (Cranston, Rhode Island, USA) — Known for specialty electroplating chemistries and precision process support, Technic’s emphasis on precious metal and tin/tin‑alloy solutions positions it well where performance and reliability are paramount. Recent trade show activity in early 2026 highlights continued outreach into adjacent precision markets (e.g., medical device finishes) that cross-sell into electronic component chemistries.
-
MKS | Atotech (Berlin, Germany) — With an extensive portfolio of wet chemical process solutions and pre‑treatment systems, Atotech is a key technology innovator for leadframe and connector processing. Its cleaner and deflashing families underscore the trend towards integrated formulations that simplify line integration and reduce operator handling risks.
-
JCU Corporation (Tokyo, Japan) — A specialist in alkaline electrocleaners, etchants and activators, JCU exemplifies the regional players that excel at high‑precision applications and at supporting convergent process lines typical of advanced IC packaging houses.
-
Shanghai Sinyang Semiconductor Materials Co., Ltd. (Shanghai, China) — As a respondent to large‑volume packaging demand, this supplier represents the competitive pressure from firms that leverage scale and local supply‑chain integration, particularly in major manufacturing corridors.
-
Nihon Parkerizing Co., Ltd. (Tokyo, Japan) — A broad provider of surface treatment chemistries that serves diverse industrial end markets; its capabilities highlight the opportunity for multi-industry firms to cross‑leverage R&D and manufacturing capacity into electronics finish applications.
For buyers and corporate development teams, the market structure implies distinct strategic options: partner with leading global formulators for advanced chemistries and compliance support, or engage nimble regional suppliers to optimize cost and proximity to assembly lines. Our vendor scorecards and negotiation playbooks are designed to accelerate those decisions while preserving optionality.
Regulatory and raw material dynamics — a dual lever shaping 2026 choices
Regulation and raw material price volatility are the dominant systemic forces shaping supplier economics and customer requirements. Global environmental frameworks such as REACH and incremental EPA restrictions continue to push formulators toward chrome‑free, low‑VOC and lower‑hazard chemistries. These regulatory trajectories are not just compliance issues; they reshape cost curves, capital intensity (e.g., investment in closed-loop effluent treatment) and time-to-market for reformulated products.
Concurrently, fluctuations in key inputs — metal salts, specialty acids and performance additives — materially affect gross margins and pricing discipline across the value chain. Our cost‑pass‑through models quantify at what points manufacturers will need to absorb price pressure versus renegotiate supplier contracts, and how procurement teams should revise hedging strategies in 2026 to protect margins without sacrificing growth.
Strategic recommendations for executives in 2026
-
Prioritize regulatory-ready pipelines: Accelerate reformulation projects for chrome‑free and low‑VOC chemistries, but sequence launches to align with customers’ readiness and certification timelines. Use pilot lines to derisk scale-up and capture early adopter premiums.
-
Invest selectively in modular manufacturing: Modular or toll‑manufacturing arrangements reduce capital exposure while enabling rapid responsiveness to localized demand spikes — a critical advantage where leadframe volumes are geographically concentrated.
-
Hedge raw material exposure using layered strategies: Combine tiered supplier contracts, strategic stockpiles for critical inputs and collaborative R&D with suppliers to secure favorable sourcing and co‑development terms.
-
Target high-value alveoli within the value chain: Consider bundling chemistries with process advisory services and analytics (e.g., plating-line digital monitoring) to move from a commodity supplier model toward a solutions provider model that captures service premiums.
-
Prepare for consolidation windows: Given the market’s moderate concentration, 2026–2028 is likely to present acquisition opportunities as mid‑sized players face investment needs to meet regulatory and scale requirements. Build a prioritized target list and pre‑approved integration templates.
How PW Consulting’s report supports implementation
Beyond diagnosis, our report is built for execution. Subscribers gain access to the forecast models, vendor scorecards, regulatory timetables and a prioritized set of near‑term actions calibrated to different risk appetites. For private equity and corporate development teams, the intelligence includes valuation multipliers adjusted for regulatory readiness and technology differentiation — critical inputs when sizing bids or structuring earn‑outs.
Next steps — where to get the full intelligence
This briefing intentionally outlines the strategic contours of the lead pin surface treatment chemicals market while withholding granular segmentation tables and proprietary supplier scoring that drive competitive advantage. To obtain the complete dataset, interactive models and supplier scorecards referenced here, visit the PW Consulting report page and request the full Worldwide Lead Pin Surface Treatment Chemicals Market report. Our team stands ready to run a tailored briefing for executive committees and investment committees to translate the findings into a 90‑day action plan.
For detailed analysis of this topic, please visit the official page: Worldwide Lead Pin Surface Treatment Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com