

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Tonsil Cancer Treatment Market to Top USD 1.54 Billion by 2032, Growing at a 6.42% CAGR

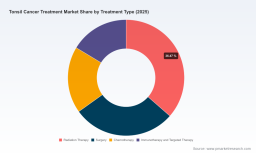
Worldwide Tonsil Cancer Treatment Market — Strategic Insights for 2026 Decision-Makers
PW Consulting today releases a forward-looking industry brief that synthesizes clinical, regulatory, commercial and payer dynamics shaping the worldwide tonsil cancer treatment market. Built on a rigorous base year of 2025 and a historical series from 2020–2025, our modeling shows the market reached approximately USD 996.0 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 6.42% through 2032, exceeding USD 1.5 billion by the end of the forecast window. This release is designed as a strategic “trailer” for executives, investors and clinical leaders who must make high-consequence choices in 2026; it demonstrates the depth and utility of our analysis while reserving detailed, segment-level datapoints for the full report.
HBM Controller IP Market
Why this report matters for 2026 planning
- Convergence of clinical breakthroughs and regulatory movement. A major perioperative immunotherapy approval in 2025 has already reconfigured treatment sequencing for resectable locally advanced disease, creating near-term demand pressures and long-run shifts in standard of care.
- Moderate market concentration shapes competitive dynamics. The market shows meaningful concentration among the largest oncology players, indicating that collaboration, licensing and targeted M&A will materially change competitive positions in 2026.
- Commercial and supply-chain policy shocks require rapid strategic responses. Emerging trade and manufacturing mandates are elevating nearshoring and capacity planning to board-level priorities.
- Payer scrutiny and patent lifecycle effects will compress margins for incumbent product portfolios while elevating premium pricing for late-stage, biomarker-driven therapies.
What PW Consulting’s report delivers — practical, transaction-ready intelligence
Our report is structured to be immediately operational for teams forming 2026 budgets, clinical development plans and commercial plays. Deliverables include:
Card Grading Services Market
- Market sizing and forecast (base year 2025; forecast 2026–2032) with scenario pathways tied to regulatory timelines, clinical readouts and reimbursement changes.
- Competitive landscaping that maps incumbent portfolios and late-stage pipelines to strategic imperatives (e.g., perioperative immunotherapy adoption, ADCs in HPV-positive disease).
- Playbooks for commercialization and access: pricing sensitivity matrices, payer negotiation templates, and formulary positioning checklists tailored to oncology market dynamics.
- Go-to-manufacturing and supply-chain decision framework addressing tariff exposure, capacity ramp calendars, and cost-to-serve modeling for on-patent vs. biosimilar eras.
- Clinical and regulatory scenario models that quantify the commercial impact of accelerated approvals, biomarker-driven label expansions, and negative trial outcomes.
- M&A and partnering heatmaps identifying capability gaps (e.g., ADC manufacturing, HPV-vaccine–peripheral immunotherapy combos, companion diagnostics) prioritized by strategic fit and execution risk.
- Actionable dashboards enabling executive briefings: customizable slide decks, investor-ready executive summaries, and an interactive model for sensitivity testing.
Competitive landscape — players, strategic postures and implications
The tonsil cancer treatment ecosystem blends large diversified oncology franchises with agile biotech innovators advancing modality-shifting assets. Key dynamics we highlight in the report include:
Data Encryption Storage Market
- Incumbent immunotherapy leaders have moved from metastatic settings into perioperative treatment paradigms. One leading PD-1 agent secured regulatory approval for neoadjuvant and adjuvant use in PD-L1–selected resectable head and neck disease in mid‑2025, accelerating hospital pathway redesigns and creating opportunities for companion diagnostics and perioperative services.
- Established oncology firms continue to support their positions through combination strategies — pairing checkpoint inhibitors with cytotoxics, radiation sensitizers, or targeted antibodies. These combinations increase both clinical complexity and commercial leverage, especially in hospital-based care pathways.
- Specialty biotechs are driving modality innovation. Antibody–drug conjugates (ADCs) and vaccine‑platform immunotherapies have advanced into late-stage development with regulatory alignment meetings in 2025, presenting candidates that could materially alter the treatment mix for HPV-positive oropharyngeal and tonsil cancers.
- Diagnostic and biomarker strategies are central. PD‑L1 expression and HPV status are increasingly determinative for therapeutic selection; firms that combine therapeutic assets with validated diagnostics command premium positioning.
- Clinical and academic centers are influential catalysts. Major cancer centers that led trials supporting the latest regulatory approvals will continue to set standards of care and accelerate physician adoption — a channel effect that companies must actively engage.
Collectively, these forces contribute to a market where the top three competitors hold a meaningful share but leave substantial room for innovative entrants to capture niche and combination-driven segments.
Regulatory, reimbursement and supply-chain headwinds & catalysts
- Regulatory catalysts: The 2025 approval of perioperative immunotherapy marked the first major label evolution in several years for head and neck oncology. That pathway has lowered the barrier for subsequent label extensions and has increased the visibility of surrogate endpoints in trial design.
- Reimbursement pressure: Oncology drug spending remains strongly affected by patent lifecycles. The post-patent entry environment drives rapid price decline, while payers promote generics/biosimilars through formulary design and cost-sharing structures. Companies must model erosion timelines and construct tiered access strategies.
- Trade and manufacturing risk: New import tariff regimes effective in late 2025 create a binary economics for manufacturers: invest in domestic manufacturing to avoid punitive tariffs or accept substantially higher cost structures for international supply. This is a near-term capital allocation decision for 2026.
- Cross-border treatment availability: Novel cellular therapies and certain advanced immunotherapies are available under EU standards before U.S. approval in some cases, creating treatment tourism and differential adoption curves that affect global demand projections.
Practical takeaways for executive decision-making in 2026
- Prioritize domestic manufacturing evaluations now. For companies with global supply footprints, our cost‑benefit simulations show accelerated onshore investment can materially reduce tariff exposure and protect net pricing in the U.S. market.
- Reprofile pipelines toward biomarker-led indications. PD‑L1 and HPV stratification are central to commercial value; late‑stage assets that include companion diagnostic strategies command higher uptake and more favorable reimbursement pathways.
- Design perioperative commercialization initiatives. Hospitals and surgical oncology networks are retooling care pathways; companies that support multidisciplinary adoption — through education, pathway resources and bundled contracting — will capture share faster.
- Model multiple regulatory scenarios in deal valuations. Accelerated approvals and conditional pathways increase upside but also raise execution risk; valuation models should stress-test both positive and negative pivotal outcomes.
- For payers and health systems: prepare coverage frameworks that balance short-term costs of novel perioperative regimens against longer-term reductions in recurrence and downstream treatment intensity.
- Investors should re-evaluate portfolio exposure to on-patent revenue cliffs and prioritize assets with durable market access constructs (diagnostics, unique mechanisms, or differentiated manufacturing).
How to use this “trailer” and where to find the full intelligence
This overview is intentionally calibrated to provide executive-grade context and to spotlight where decisive 2026 actions are required. The full PW Consulting Worldwide Tonsil Cancer Treatment Market report contains granular segmentations, region- and channel-level modeling, company market shares, primary research findings, five-year scenario matrices, and downloadable financial models. We have withheld detailed segmental tables and underlying raw datapoints from this summary to preserve the analytical integrity of the full report and to ensure high‑value engagement for subscribers seeking operational datasets.
PW Consulting offers tailored executive briefings, custom modeling engagements and data licensing for corporate planning and transaction due diligence. For organizations preparing budgets, revising pipelines, or evaluating manufacturing investments in 2026, the full report and an accompanying strategy workshop provide the practical tools necessary to convert insights into executable plans.
Contact PW Consulting to schedule a briefing and to obtain access to the complete dataset, including interactive scenario models and primary research appendices.
For detailed analysis of this topic, please visit the official page: Worldwide Tonsil Cancer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com