

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Forensic Lab Equipment Market Poised to Expand at a 7.15% CAGR (2026–2032)

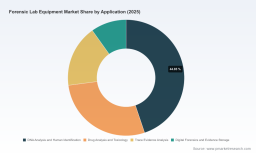
Worldwide Forensic Lab Equipment Market — 2026 Strategic Briefing
PW Consulting’s latest market study, Worldwide Forensic Lab Equipment Market (base year 2025; forecast 2026–2032), equips executive teams with the evidence-based intelligence required to make high-stakes decisions in 2026. The market reached USD 3,088.1 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 7.15% through the 2026–2032 forecast window, approaching USD 5,007.7 Million by 2032. This briefing distills the report’s strategic value: what leaders must act on now, what to monitor, and where to direct capital and capability investments to capture growth while managing regulatory and operational risk.
Disposable Suture Grasper Closure Device Market
Why this report matters for 2026 decision cycles
-
Capital allocation: With measurable mid-single-digit to high-single-digit growth ahead, organizations must sequence capex into high-impact platforms while preserving flexibility for rapid technology shifts (e.g., next‑generation sequencing, advanced mass spectrometry and digital forensics stacks).
HIV Antibody Diagnostic Reagent Market -
Vendor strategy: Our analysis differentiates suppliers by technology depth, service footprint, consumables dependency and regulatory posture — enabling procurement leaders to prioritize partner lists and contract models (purchase, lease, reagent lock-in).
Worldwide Liquid Optically Clear Adhesive (LOCA) Market -
Regulatory compliance: New quality and biosafety controls that took effect in 2026 materially change qualification timelines for instrument manufacturers and laboratory adopters; readiness is now a competitive requirement.
-
M&A and partnerships: The market’s moderate concentration opens selective opportunities for tuck-in acquisitions and strategic alliances to secure capability gaps (sample prep, bioinformatics and digital evidence management).
-
Operational transformation: Investments in NG‑LIMS, automation and digital evidence chains are no longer optional for high-throughput public forensic labs seeking throughput, reproducibility and auditability.
What’s inside the PW Consulting report — operationally actionable content
-
Transparent market sizing and modelling: historic series (2020–2025), base-year benchmarks (2025) and scenario-modeled forecasts for 2026–2032 with sensitivity ranges to stress-test strategic plans.
-
Practical buyer toolkits: RFP templates for capital equipment and LIMS, procurement scoring matrices, and total cost of ownership (TCO) calculators that incorporate instrument uptime, consumables, service and training.
-
Vendor scorecards and channel maps: comparative assessments across performance, regulatory readiness, installed base, service coverage and consumables economics — designed for immediate shortlisting.
-
Regulatory playbook: step‑by‑step compliance checklists reflecting the latest QMS and biosafety requirements, plus procurement redlines for contracts subject to grant or federal funding constraints.
-
Technology adoption roadmaps: prioritized investment pathways for small, medium and national forensic laboratories, covering sequencing, mass spectrometry, imaging, digital forensics and evidence‑handling automation.
-
Strategic scenarios: four alternative industry trajectories (base case, accelerated technology adoption, constrained funding, and regulatory tightening) with recommended responses for each.
Market dynamics and near-term catalysts
-
Workload and capability expansion: Persistent caseload growth, combined with rising expectations for higher resolution forensic outputs (genomics, trace chemistry and digital evidence), sustains demand for both instruments and integrated workflows.
-
Public funding and procurement rhythms: Targeted grants and capital programs remain a key demand engine for public forensic labs; timing of awards materially affects procurement windows and vendor revenue phasing.
-
Digital transformation: NG‑LIMS and evidence lifecycle management initiatives are accelerating, requiring integration of instruments, software and chain‑of‑custody systems — an ecosystem play that benefits vendors with software and services capabilities.
-
Regulatory inflection points: The industry is adjusting to updated quality management frameworks and biosafety controls implemented at the start of 2026, affecting product certification timelines and supplier qualification criteria.
Competitive landscape — strengths, risks and strategic levers
The report provides a granular competitive assessment of the market’s leading suppliers and adjacent players. A high‑level synthesis follows below to orient strategic conversations.
-
Thermo Fisher Scientific: Broad portfolio strength across DNA, mass spectrometry and integrated workflows; deep service and global install base make it a default partner for large laboratory networks.
-
Agilent Technologies: Strong analytical instrumentation footprint in GC‑MS and LC‑MS; differentiated applications support in forensic toxicology and chemical identification.
-
Waters Corporation: Specialization in LC‑MS platforms and related chemistries positions it well for toxicology and metabolite identification demands.
-
PerkinElmer: Cross‑domain capabilities (spectroscopy, chromatography, imaging) that support both DNA workflow augmentation and chemical forensics.
-
Danaher/SCIEX: High‑performance mass spectrometry systems and a focus on sensitivity and quantitative screening for drug and trace analysis.
-
QIAGEN and Promega: Leaders in sample prep, nucleic acid workflows and STR solutions; they are core to DNA workflow efficiency and reproducibility.
-
Illumina/Verogen: NGS‑forensics vendors enabling complex genomic analyses and higher‑order identification use cases, particularly in specialized forensic genomics labs.
-
Bruker, Shimadzu and Horiba/SPEX: Strong niche capabilities in spectroscopy, materials characterization and Raman analysis that address trace evidence and materials identification.
-
Sirchie and Lynn Peavey: Specialist providers for evidence collection, field consumables and crime scene workflow tools, whose offerings tie upstream collection to downstream lab processing.
Market concentration metrics indicate a moderate level of aggregation: the top three suppliers account for roughly 42% of market value, while the top five account for about 58%. That structure favors scale players with global service networks, but it leaves meaningful whitespace for specialty vendors and software/service disruptors.
Regulatory and policy intercepts that will shape 2026 choices
-
FDA Quality Management System Regulation (QMSR): Effective in early 2026, manufacturers of certain forensic instruments that fall under medical device frameworks now face tightened QMS expectations aligned with ISO 13485. Supplier qualification and product release processes must be re-evaluated.
-
LDT carve‑outs and forensic use: The final LDT policy retains an exclusion for tests intended solely for law enforcement, but suppliers and labs should document intended use claims carefully to avoid regulatory ambiguity.
-
BIOSECURE Act implications: New restrictions signed into law in late 2025 impose procurement and collaboration constraints for federally funded organizations around select biotechnology equipment and services.
-
Funding programs: Targeted grants (e.g., NIJ awards and other capital funding) continue to subsidize modernization, creating periodic spikes in demand that vendors and labs can exploit if procurement timing is synchronized.
Recommendations for executive teams (what to do in 2026)
-
Prioritize QMS and supply‑chain due diligence now. Instrument vendors and labs must align contracts, validation plans and supplier audits with the updated QMSR timelines to avoid deployment delays.
-
Adopt a modular procurement strategy. Favor platforms that allow staged capability upgrades (e.g., add-on NGS modules, software‑first analytics) to preserve budget flexibility.
-
Invest in integration and data pipelines. Early NG‑LIMS adopters that integrate instruments, chain‑of‑custody, and analytics will unlock measurable productivity and defensibility gains.
-
Use public funding strategically. Map grant cycles into procurement roadmaps and align vendor negotiations to match award timing to reduce working capital exposure.
-
Protect operational continuity through dual sourcing and service level agreements. Prioritize vendors with local service footprints or documented third‑party field support channels.
-
Pursue targeted M&A or technology partnerships. Buyers seeking rapid capability expansion should prioritize targets that add software, bioinformatics, or specialized consumable portfolios.
How to use PW Consulting’s report
-
CEOs and CFOs: Use the market scenarios and TCO models to size capex envelopes and prioritize investment tranches for 2026–2027.
-
Procurement and supply chain leaders: Leverage vendor scorecards and RFP templates to shorten procurement cycles and negotiate favorable lifecycle terms.
-
Product and R&D teams: Align roadmaps to regulatory timelines and identify partnership opportunities for rapid go‑to‑market.
-
Investors and corporate development: Apply the competitive analysis and concentration metrics to identify acquisition targets and partnership candidates that improve market positioning.
PW Consulting’s Worldwide Forensic Lab Equipment Market report is structured to be immediately operational: models, templates, vendor analytics and regulatory playbooks are included to accelerate decision-making in 2026. For full segmentation tables, vendor scorecards, downloadable financial models and the complete strategy playbook, visit PW Consulting’s report page and request the full dataset and advisory briefings.
For detailed analysis of this topic, please visit the official page: Worldwide Forensic Lab Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com