

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts 5.42% CAGR for Worldwide Ultra‑Low Temperature Freezers for Medical Market
By pmarketresearch, 2026-08-18
Worldwide Ultra Low Temperature Freezers for Medical Market — Strategic Preview
PW Consulting today releases a strategic preview accompanying our forthcoming market research report on the Worldwide Ultra Low Temperature (ULT) Freezers for Medical Market. Purpose-built for executives planning capital investments, procurement heads, product leaders and investors in 2026, this briefing distills the high-impact takeaways from a comprehensive study that spans historical performance (2020–2025), uses 2025 as the base year, and delivers a granular forecast through 2032.
Worldwide Amino Acetic Acid Market
Why this matters for 2026 decision cycles
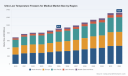
The ULT freezer market for medical use is no longer a niche equipment category — it is a business-critical intersection of clinical compliance, lifecycle cost management and sustainability targets. Our analysis shows the global market grew steadily through the 2020–2025 period and reached an inflection point in 2025. The market is positioned to expand at a compound annual growth rate (CAGR) of approximately 5.42% over the 2026–2032 forecast window, reaching materially larger scale by 2032.
Worldwide Mechanical Estimating Software Market
That trajectory creates two imperative realities for decision-makers in 2026:
Worldwide L-Glutamic Acid Market
- Capital allocation choices made this year — whether to retrofit legacy -86°C assets, replace with new energy-efficient units, or outsource storage to third-party biobanks — will determine five- to seven-year operating budgets and compliance risk profiles.
- Regulatory and certification changes are tightening validation requirements for storage equipment, raising the bar for product design, documentation and aftermarket service — decisions on suppliers, certification investments and service contracts must reflect that new baseline.
What the market dynamics mean in practice
Our report integrates macro drivers that are changing procurement and product strategies across hospitals, biobanks, pharmaceutical companies and research institutes. Key dynamics include:
- Regulatory tightening: The FDA’s Quality Management System Regulation (QMSR), effective February 2, 2026, introduces more prescriptive validation and documentation expectations for equipment used to store high-value medical products. In parallel, ULT freezers intended for storage of vaccines, human cells and tissues remain regulated under EU MDR as medical devices — a continuing design and compliance requirement for suppliers targeting clinical markets.
- Energy and total cost pressure: Legacy -86°C platforms impose high ongoing power costs and create sustainability headwinds for healthcare providers aiming to reduce carbon intensity. Technology advances — including improved insulation, dual-cooling architectures and non-hermetic compressor systems — are enabling substantial daily energy reductions, shifting procurement evaluation from purchase price toward lifecycle cost and environmental impact metrics.
- Consolidation and competitive structure: The market exhibits moderate concentration. Our concentration analysis indicates that the top three suppliers account for over forty percent of the global medical ULT freezer revenue base, while the top five approach the mid‑fifty percent range — a structure that shapes bargaining leverage, aftermarket service models and component supply strategies.
Competitive landscape — what leading suppliers are emphasizing
Manufacturers active in the medical ULT space are differentiating across three axes: compliance and documentation for regulated users; energy and lifecycle economics; and integrated service models (remote monitoring, validation support, and rapid-response maintenance). Our review of incumbent and emerging suppliers highlights distinct positioning:
- Thermo Fisher Scientific Inc. — portfolio depth and global services play. Emphasizes energy efficiency, temperature homogeneity and compliance support for clinical and biobanking customers.
- PHC Corporation (PHCbi) — dual-cooling and eco-efficiency. Continues to invest in dual-cooling architectures and recently expanded its ECO-focused product lines to target energy-conscious institutional buyers.
- Eppendorf AG — laboratory performance and precise control. Focuses on control systems and sample protection for research-intensive users.
- Haier Biomedical — cost and scale advantage. Competes with energy-efficient product variants and models certified for clinical use, leveraging manufacturing scale for price-sensitive markets.
- Helmer Scientific, B Medical Systems, Arctiko, Stirling Ultracold, NuAire, So-Low, Labcold, BINDER, LAUDA, Corepoint Scientific, Accucold — a mix of medical-grade specialists, energy-centric innovators, and regional manufacturers. These firms collectively broaden customer choice across features, certifications and service footprints.
Notably, early-2026 product activity — including new energy-optimized models introduced by major suppliers — underscores a market pivot: vendors are responding to buyer demand for validated, lower-energy ULT solutions that integrate with hospital quality systems.
Regulatory and operational implications for procurement and engineering teams
For organizations evaluating ULT assets in 2026, the convergence of regulation and energy mandates leads to concrete procurement criteria:
- Compliance-first specifications: Require suppliers to demonstrate alignment with FDA QMSR validation pathways and to provide MDR/ISO-compliant design documentation where applicable.
- Lifecycle costing and energy ROI: Shift procurement scoring to include energy consumption metrics, mean time between failures, and predictive maintenance capabilities — not just upfront cost.
- Service and validation packages: Favor vendor offerings that bundle validation kits, IQ/OQ protocols and extended service level agreements to reduce internal validation burden and speed time-to-use.
- Data and remote monitoring: Prioritize controllers and telemetry capable of secure data logging, audit trails and remote alarms to meet clinical chain-of-custody requirements.
Strategic playbook for suppliers, buyers and investors
Our report translates market signals into actionable strategies for three audiences:
- Suppliers and OEMs — Product and commercial strategies: Invest in medical-grade documentation, modular designs that reduce validation cycles, and energy technologies that demonstrably lower TCO. Pursue certification investments (e.g., ISO 13485) and develop bundled service offerings for clinical customers who prize end-to-end compliance.
- Healthcare and laboratory buyers — Procurement and asset-management strategies: Reframe decisions around validated TCO analyses, prioritize vendors with demonstrable compliance workflows, and assess retrofit versus replacement using scenario modelling that accounts for energy savings, downtime risk, and regulatory timelines.
- Investors and financiers — Investment themes: Target companies with differentiated energy platforms, recurring-service revenue models, or superior regulatory-support capabilities. Monitor consolidation dynamics; a mid-market with defined concentration metrics often creates acquisition and roll-up opportunities for scale and service uniformity.
What’s inside the PW Consulting report (practical, non-proprietary overview)
Our full report is constructed to be a working toolkit for 2026 strategy. It combines market sizing and a forward-looking forecast with a suite of operational deliverables that buyers and suppliers can act on immediately, including:
- Scenario-based demand models and TCO calculators that let you test retrofit vs. replacement outcomes under different energy-price and capital-allocation assumptions.
- Supplier benchmarking frameworks covering compliance posture, service coverage, energy performance, and aftermarket economics (presented without disclosing client-sensitive share details).
- Procurement templates and validation playbooks that align with FDA QMSR and EU MDR expectations — IQ/OQ checklists, documentation templates, and audit-ready evidence packages.
- Priority investment roadmaps for R&D and product managers outlining features that materially influence purchase decisions (e.g., dual-cooling redundancy, telemetry integration, and modular refrigeration systems).
- Regulatory impact assessments and risk matrices that connect device-level design choices to organizational validation workloads and compliance timelines.
Executive recommendation — immediate next steps for 2026
Leaders preparing 2026 budgets and capital plans should treat ULT freezer strategy as a cross-functional decision. We recommend four immediate actions:
- Run a short-form TCO and risk assessment across your ULT estate using energy and validation inputs — prioritize candidates for replacement where energy payback and compliance risk align.
- Insist on QMSR- and MDR-aligned evidence from suppliers during RFP stages; require validation support as part of the procurement package to reduce internal workload.
- Negotiate service pilots with telemetry-enabled units to validate real-world energy and uptime performance before committing to large fleet purchases.
- For suppliers, accelerate certification programs and shift commercial offers toward bundle models that lock in recurring revenue while lowering buyer adoption friction.
Where to access the full intelligence
This preview is a strategic extract from PW Consulting’s full report on the Worldwide Ultra Low Temperature Freezers for Medical Market. The complete study includes the full historical dataset, detailed regional and application forecasts, vendor scorecards, and downloadable tools referenced above. The full dataset and templates provide the operational depth required to execute 2026 investment and procurement plans with confidence.
To obtain the full report and associated decision-support tools, visit the PW Consulting publications page. Our team is available to arrange bespoke briefings and to run client-specific scenario workshops that map the report’s insights directly onto your capital and compliance timelines.
PW Consulting — transforming market intelligence into executable strategy for the medical cold chain.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra Low Temperature Freezers for Medical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Emergency Weatherproof Batten Market to Reach USD 603.7 Million by 2032 at 5.5% CAGR; Asia Pacific Leads with USD 135 Million
By pmarketresearch, 2026-08-18
Emergency Weatherproof Batten Market: Strategic Preview for 2026 Decision‑Making
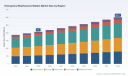
PW Consulting’s latest industry briefing offers a focused, strategic preview of the Emergency Weatherproof Batten market as companies prepare decisions for 2026. Built on a proprietary market model with a 2025 base year, the analysis synthesizes historical performance (2020–2025), near‑term dynamics, and a seven‑year forecast horizon (2026–2032). At the macro level, the market is expanding steadily — from an estimated USD 415 million in 2025 and growing at a compound annual growth rate (CAGR) of approximately 5.5% to reach roughly USD 604 million by 2032 — driven by energy‑efficiency transitions, tightening compliance requirements, and increased specification activity in harsh‑environment projects.
Flip Chip Packages Market
Why this preview matters to 2026 strategy
- The emergency weatherproof batten category sits at the intersection of safety regulation, energy transition, and resilient infrastructure spending. Procurement cycles for industrial, public infrastructure, and commercial projects commonly run on multi‑year timelines; the decisions made in 2026 will shape installation and retrofit volumes for the remainder of the decade.
- Regulatory alignment is becoming a commercial edge. Mandatory and best‑practice standards (for example, national emergency‑lighting codes and international fixture safety standards) are raising the bar on battery chemistry, ingress protection, and testing protocols — turning compliance from a checkbox into a supplier selection criterion.
- Operational cost reductions from LED migration and remote monitoring are now quantifiable and widely used in business cases for retrofits. Stakeholders who can demonstrate lower total cost of ownership (TCO) can capture specification wins in a market with measured supplier concentration (CR3 ≈ 22.5%, CR5 ≈ 31.8%).
What the market dynamics mean in practice
- Energy and operational efficiency are primary demand drivers. LED‑based emergency battens offer material energy savings and extended service lives versus legacy technologies, translating to lower lifecycle costs for asset owners and stronger ROI for retrofits.
- Battery technology and product robustness are differentiators. Adoption of LiFePO4 chemistry, longer warranty terms, and higher ingress/impact ratings (IP65/IP66, IK08) are de‑risking installations in outdoor and industrial settings and are increasingly required by specifiers.
- Compliance and testability influence procurement. Local and international standards (including national emergency‑lighting codes and IEC fixture safety requirements) directly affect product design, labelling, and post‑installation maintenance regimes; suppliers that provide straightforward compliance documentation and remote testing capabilities are favored.
- Supply‑chain and material trends are non‑trivial. For example, upstream price movements for engineering plastics used in housings and diffusers are creating episodic cost pressure; observed pricing data from China in early 2026 show downward price signals for polycarbonate driven by softer demand in adjacent sectors — a factor that affects margin planning and sourcing strategies.
Competitive landscape — positioning and tactical moves
Our competitive scan combines product profiling, recent product and compliance developments, and a supplier capability lens. The field features a mix of regional specialists and international OEMs, with clear segmentation between premium, compliance‑led players and cost‑focused manufacturers that serve OEM/ODM channels.
CCD Image Sensors Market
- Regional specialists with compliance‑led portfolios: Several established Australian manufacturers have built reputations on products engineered for harsh environments and code compliance. Their offerings increasingly include LiFePO4 batteries, selectable colour/output options, and “maintained” emergency operation modes to suit car parks, warehouses, and other critical facilities.
- Feature‑rich LED innovators: Vendors are differentiating through features such as white‑tuning, dimmability, wireguard/diffuser options, and integrated wireless monitoring platforms for remote diagnostics — all of which reduce onsite maintenance costs and support portfolio premiumization.
- China‑based OEM/ODM scale players: Industrial producers in Shenzhen and elsewhere continue to supply robust IP65/IP66 fixtures at competitive price points for large‑volume infrastructure projects (tunnels, workshops, outdoor sites), often offering native emergency systems and private‑label partnerships.
- Recent signals to watch: updates published in early 2026 by compliance‑active vendors and product launches announced in 2025–2026 indicate accelerating focus on enhanced emergency classifications, wireless monitoring, and temporary outdoor safety lighting — each reflecting different go‑to‑market plays.
Strategic implications and recommended actions for 2026
Based on our synthesis of market growth, regulatory drivers, supplier capabilities, and supply‑chain noise, PW Consulting recommends the following practical moves for firms participating in the emergency weatherproof batten value chain.
Reptile Heating and Lighting Supplies Market
- Manufacturers — prioritize certifiable robustness and TCO messaging. Product roadmaps should emphasize LiFePO4 battery integration, higher IP/IK ratings, and extended warranties. Equip product sheets with compliance evidence and lifetime cost calculators to convert specifiers focused on evacuation safety and lifecycle economics.
- Distributors & wholesalers — evolve from logistics to solutions provision. Expand capabilities to offer specification packages, on‑site testing services, and firmware/remote monitoring bundles. These value adds protect margins as price competition intensifies and enable recurring service revenue.
- Project owners & facility managers — build retrofit prioritization frameworks. Use energy‑and‑safety KPIs to rank retrofit candidates; target facilities where LED upgrades plus smart monitoring yield the fastest payback. Incorporate compliance audit clauses into procurement to ensure installed fixtures meet code and insurer expectations.
- Specifiers & consultants — demand testability and documentation. Insist on suppliers that provide clear evidence of compliance with national standards and international safety norms, as well as remote diagnostic capability for scheduled verification without full site interventions.
- Procurement & sourcing teams — mitigate material and logistics risk. Establish dual sourcing for critical plastics and battery components and negotiate flexible pricing clauses tied to a transparent input‑cost index. Consider regional manufacturing partnerships to shorten lead times for emergency projects.
What PW Consulting’s full report delivers (practical contents)
The full Emergency Weatherproof Batten Market report is structured to be actionable for commercial strategy and procurement decisions. Key deliverables include:
- Proprietary market model (historical 2020–2025, base year 2025) and scenario‑based forecasts through 2032, with sensitivity analysis covering demand shocks and regulatory tightening.
- Market segmentation across regions, product types, and applications with demand drivers and adoption curves (note: headline segmentation summaries are discussed in this preview; detailed segment figures are available in the full report).
- Supplier scorecards and comparative feature matrix covering design robustness, battery chemistry, monitoring capability, compliance documentation, warranty terms, and go‑to‑market strength.
- Commercial playbook including specification templates, procurement contract clauses, retrofit prioritization tool, and sample ROI models for LED + monitoring upgrades.
- Supply‑chain risk register and raw‑material sensitivity assessment with recommended sourcing mitigations and inventory strategies.
- Innovation radar and roadmap — from battery evolution to wireless remote testing — highlighting technology inflection points and expected timelines for wider adoption.
- Regulatory impact analysis covering national emergency lighting codes and IEC fixture safety requirements, plus a compliance checklist for specifiers and installers.
Near‑term watchlist (Q1–Q4 2026)
- Regulatory clarifications and enforcement activity in major markets — any updates to national emergency‑lighting codes will alter procurement requirements and retrofit schedules.
- Advances in remote monitoring platforms and standardized remote test protocols — early adopters will capture maintenance savings and long‑term contract wins.
- Raw material pricing trajectories for engineering plastics and battery cell supply dynamics — these will affect supplier margins and may trigger contract renegotiations or localized sourcing moves.
- Competitive product rollouts that bundle compliance documentation, longer warranties, and remote testability — expect suppliers that combine these features to expand spec share in safety‑sensitive verticals.
Concluding perspective
The Emergency Weatherproof Batten market is maturing into a solutions‑oriented sector where safety compliance, durability, and lifecycle economics govern commercial outcomes as much as unit price. With steady growth projected through 2032 at an approximate 5.5% CAGR, the commercial opportunity is meaningful for firms that can align product design, regulatory readiness, and service‑led go‑to‑market approaches. PW Consulting’s full report provides the granular segmentation, supplier benchmarking, and procurement tools needed to operationalize these insights. This press release intentionally omits detailed segment‑level data to protect the tactical intelligence contained in the full study; decision‑makers seeking the complete dataset, segmented forecasts, and supplier matrices are invited to access the full report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Emergency Weatherproof Batten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Processed Seafood Market Set to Reach USD 86,105.63 Million by 2032 at a 5.12% CAGR
By pmarketresearch, 2026-08-18
Worldwide Processed Seafood Market 2026: Strategic Imperatives from PW Consulting
As senior industry analysts at PW Consulting, we are releasing an executive preface to our new Worldwide Processed Seafood Market report — a focused, actionable briefing designed to sharpen corporate decisions throughout 2026. The processed seafood sector is entering a phase where steady volume growth, material-price volatility, evolving traceability obligations, and concentrated pockets of strategic scale are creating both clear opportunities and asymmetric risks. This pre-release summarizes the macro trajectory, competitive dynamics, regulatory inflection points, and the pragmatic toolset our full report delivers to executives preparing 2026 plans.
Worldwide Advertising Management Platform Market
Market trajectory at a glance
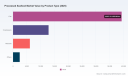
The processed seafood marketplace has expanded meaningfully over the last half-decade. PW Consulting’s baseline sizing shows a market that grew from roughly USD 48.5 billion in 2020 to approximately USD 60.8 billion by the 2025 base year. Under our forecasted scenarios for the 2026–2032 horizon, the market continues to expand at a compound annual growth rate of 5.12%, with an estimated market value of about USD 63.7 billion in 2026 and sustained growth thereafter.
Snowblower Market
That steady, mid-single-digit CAGR reflects three simultaneous dynamics: (1) persistent consumer demand for protein convenience and value-added seafood formats; (2) upward pressure on raw-material and logistics costs; and (3) regulatory and traceability investments that are shifting cost and capability requirements for processors and brand owners. For executives planning capital allocation, portfolio prioritization, or M&A activity in 2026, these macro facts are non-negotiable inputs.
Outdoor Fixed Screen Market
Why this report matters for 2026 decisions
- Practical forecasting tailored to decision windows: We translate market growth and price volatility into planning scenarios that align with typical 12–36 month corporate decision cycles, enabling CFOs and business unit heads to stress-test budgets and contract strategies.
- Regulatory-readiness mapping: The report maps current and imminent traceability, trace testing, and food-safety obligations to operational checklists and CAPEX timelines — critical for avoiding supply disruptions and costly recalls.
- Actionable competitor playbook: Beyond headline rankings, we profile leading processors by capability (cold chain, value-added manufacturing, brand reach) and suggest concrete counter-moves for market entrants and incumbents alike.
- Scenario-based sourcing strategies: We provide decision trees for diversifying raw-material channels, managing freight and tariff exposure, and optimizing buffer inventories under multiple price and supply-shock scenarios.
What the full report contains (practical modules)
- Dynamic market model — interactive dashboards with year-by-year baseline and scenario projections for 2020–2032, ready for export into financial models.
- Segmentation frameworks — region, processing type, and product type segmentation with historic series and forecast splits (note: this preface omits granular subsegment figures; full data tables are available with the report).
- Competitive matrix and capability maps — supplier footprints, vertical-integration scores, and value-chain strengths and weaknesses for major players.
- Regulatory & compliance playbook — FSMA traceability alignment, GDST modular standards implications, and food-safety testing programs translated into facility-level actions and investment timetables.
- Risk & resilience toolkit — recall-response templates, supplier audit prioritization, and insurance/indemnity negotiation guides tailored to processed seafood.
- Go-to-market & innovation levers — product-format prioritization (e.g., frozen value-add vs. commodity canned lines), private-label strategies, brand partnerships, and commercial pricing elasticity analysis.
Competitive landscape — what to watch in 2026
The processed seafood industry is structurally fragmented: the top three and top five firms account for single-digit to low-twenties percentage shares of global market value, leaving substantial room for regional champions and nimble innovators. This fragmentation creates fertile ground for strategic consolidation, targeted bolt-on acquisitions, and capability-driven differentiation.
- Thai Union Group PCL (Samut Sakhon, Thailand) — A global leader across canned tuna, frozen seafood, and value-added brands with an extensive worldwide supply chain. Recent strategic moves and partner investments position it to accelerate branded and private-label initiatives.
- Maruha Nichiro Corporation (Tokyo, Japan) — One of the largest integrated seafood concerns with broad processed seafood operations and deep procurement channels in Asia and beyond.
- Mowi ASA (Bergen, Norway) — The world’s largest salmon farming and processing company, focused on retail and foodservice fillets, portions, and value-added products.
- Nippon Suisan Kaisha (Nissui) (Tokyo, Japan) — A major integrated player with strong frozen and highly-processed product capabilities and global distribution reach.
- High Liner Foods (Nova Scotia, Canada) — A leading North American frozen value-added specialist; its 2025 acquisition activity expanded its branded portfolio and U.S. market depth.
- Trident Seafoods, Lerøy Seafood Group, Royal Greenland, Austevoll Seafood, Cooke Inc., Pacific Seafood Group, Bolton Group, Kyokuyo — Each brings differentiated strengths in wild-caught niches, aquaculture integration, regional distribution networks, or European market presence.
Collectively, these players illustrate two viable strategic archetypes for 2026: (1) scale-driven integration focused on raw-material security and cost efficiency; and (2) capability-driven specialization emphasizing branded value-adds, traceability differentiation, and retail/foodservice partnerships.
Regulatory and supply signals shaping near-term strategy
- Traceability standardization: The Global Dialogue on Seafood Traceability (GDST) public consultation (2026) signals a shift toward a commodity-agnostic, modular standard that will make traceability investments more interoperable but also raise minimum compliance thresholds for processed products.
- FSMA traceability expansion: New FSMA traceability obligations for items on the Food Traceability List introduce recordkeeping needs for farms and processors — companies will need to retrofit or upgrade batch-level traceability and supplier onboarding processes to maintain U.S. market access without friction.
- Food-safety testing and recalls: Recent recall events in frozen products underscore the operational impact of supplier eligibility and testing regimes. We map preventive controls and rapid response protocols that materially reduce recall cost and brand damage.
- Raw-material price pressure: International price indices and USDA outlooks point to above-average upward pressure on seafood pricing into 2026. Companies must plan both hedging and commercial tactics to preserve margin while retaining market share.
Practical recommendations for 2026 planning
- Prioritize traceability investments with ROI gating: Treat traceability as both compliance and commercial enablement. Phase investments by priority markets and SKU value rather than blanket upgrades.
- Revisit sourcing diversification: Move beyond single-origin reliance for high-risk species. Use dual-sourcing contracts and conditional inventory pooling to smooth supply shocks without significant working-capital increases.
- Accelerate value-added frozen capability where margin pools exist: Our market modelling shows compelling risk-adjusted returns for certain frozen value-added formats versus commodity canned lines — but the exact mix is company- and market-dependent; the full report provides the decision matrices and payback scenarios.
- Design targeted M&A playbooks: Given the fragmented market, bolt-on acquisitions can rapidly add processing footprint, retail relationships, or product formats. We provide a prioritized target-screen checklist and integration playbooks to de-risk 100-day plans.
- Embed recall readiness in commercial contracts: Standardize supplier obligations on testing, indemnities, and logistics, and align insurance strategies to preserve cash flow during events.
Case signals and near-term catalysts
A few recent developments signal where executives should allocate attention this quarter:
- High Liner Foods’ 2025 acquisition of leading U.S. frozen brands increased its value-added portfolio and illustrates the attractiveness of branded frozen lines in North America.
- Strategic investment in Thai Union by a major trading house highlights alliance-based approaches to securing scale and market access.
- GDST’s 2026 traceability consultation and FSMA updates elevate traceability from compliance ‘nice-to-have’ to strategic differentiator—companies that lead on verified traceability can command price premiums and preferred placement with large retailers.
- Recent recalls tied to supplier eligibility and contamination incidents are a reminder that operational controls and supplier vetting have direct balance-sheet consequences.
How PW Consulting helps — report deliverables and advisory options
The full report is designed as both an intelligence product and a practical implementation kit. Deliverables include:
- Downloadable time-series market model (2020–2032) with scenario toggles and exportable data tables.
- Segmentation dashboards by region, processing type, and product category (granular splits are available in the paid release).
- Competitive scorecards and M&A target prioritization framework tailored to client strategic intent.
- Operational playbooks for traceability upgrades, supplier risk management, and recall response.
For companies preparing budgets, negotiating supplier agreements, or evaluating acquisition targets in 2026, the intelligence and executable frameworks in our report compress months of research into decision-ready guidance. Because this release follows a “trailer” principle, we have intentionally withheld the granular segment tables and proprietary assumptions that underpin our models; these are included with the full report and our advisory engagements.
Next steps
Executives and investors who require the full dataset, scenario models, and tailored advisory — including workshops to align finance, procurement, and operations teams for 2026 risk scenarios — should contact PW Consulting for access to the complete Worldwide Processed Seafood Market report and accompanying consulting packages. The full report contains the granular segmentation data, forecast assumptions, and playbooks necessary to convert insight into immediate action.
PW Consulting remains committed to providing decision-grade intelligence that turns complex market dynamics into clear, executable strategies. In the face of rising input costs, evolving regulatory frameworks, and fragmented competitive dynamics, the companies that pair disciplined operational rigor with strategic investments in traceability and value-added formats will set the pace in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Processed Seafood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Breath Out Filters Market to Reach USD 1,444.78 Million by 2032 with 5.78% CAGR — Hospitals Segment Alone at USD 616.49 Million
By pmarketresearch, 2026-08-18
Worldwide Breath Out Filters Market — PW Consulting Report: Strategic Imperatives for 2026
PW Consulting today releases a comprehensive industry study, Worldwide Breath Out Filters Market (base year 2025, forecast 2026–2032), designed to equip senior executives, product leaders, purchasing heads and M&A teams with the intelligence required to make high-confidence decisions in 2026. The report combines rigorous market-sizing, regulatory mapping, supply-chain stress-testing and competitive benchmarking to translate technical filter performance into commercial advantage.
Polymeric Positive Temperature Coefficient Device Market
Market snapshot: scale, trajectory and concentration
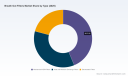
After a period of volatility between 2020 and 2025, the worldwide breath out (exhalation/breathing circuit) filters market stabilized at approximately USD 975 million in 2025 and is projected to expand to about USD 1.04 billion in 2026. PW Consulting’s modeled baseline shows a compound annual growth rate (CAGR) of 5.78% across the 2026–2032 forecast period, culminating in a materially larger market by 2032. Competitive concentration is meaningful: the top three suppliers account for a substantial portion of global revenue, and the top five consolidate more than half the market—an environment that supports both scale-focused incumbents and targeted challengers with differentiated value propositions.
Worldwide Mortgage CRM Software Market
Why 2026 is a pivotal decision year
- Normalization and capital planning: Healthcare providers that deferred capital refreshes and procurement process changes during recent years are entering a planning cycle in 2026. This creates an opportunity window for vendors that can couple clinical evidence with predictable supply and service terms.
- Regulatory tightening and product-design implications: Breathing system filters are regulated medical devices under established quality frameworks (including ISO and regional device clearance processes). Manufacturers that build regulatory-first development, manufacture and post-market surveillance into their roadmaps minimize commercialization risk.
- Procurement emphasis on infection control and economics: Hospital protocols around single-patient use and circuit management—balanced against episodic pressure to extend product dwell times in crisis scenarios—require nuanced value propositions that blend infection-control evidence, lifecycle cost and logistical simplicity.
- Supply and raw-material risk: The market relies on specialized hydrophobic and pleated membrane media and manufacturing practices that must be validated to medical-device standards. Raw material availability and validated vendor relationships will determine which manufacturers can scale without compromising quality.
What the report delivers — practical, operational intelligence
PW Consulting structured this study to be a doer's playbook rather than an academic survey. Key deliverables include:
Worldwide Antiinflammatory Drugs Market
- Market sizing and demand scenarios calibrated to hospital-capacity, anesthesia throughput and mechanical-ventilation usage profiles (base/accelerated/adverse cases).
- Regulatory and standards matrix mapping global pathways (including premarket submission expectations, ISO conformance, and country-specific nuances) and an action checklist for product submissions and conformity assessment.
- Supplier and product scorecards across clinical performance, manufacturing quality (ISO 13485 alignment), supply-chain resilience and cost-to-serve—designed to feed procurement RFPs.
- Raw-material dependency and supply-risk heatmaps that highlight single-source exposures and alternative-sourcing pathways for hydrophobic and electrostatic media.
- Go-to-market archetypes and pricing strategies for device OEMs, contract manufacturers and distributors—covering single-patient disposables, HME hybrids and machine-side filtration.
- M&A and partnership playbooks: target criteria, valuation sensitivities and integration checklists for bolt-on filtration assets and complementary respiratory-device portfolios.
- Operational playbooks for clinicians and hospital procurement teams to harmonize infection-control protocols with inventory policy (fresh patient-side filters, circuit duration rules, and emergency substitution workflows).
Competitive landscape: leaders, differentiators and strategic moves
The report’s competitive analysis profiles established filtration manufacturers and healthcare OEMs that shape market dynamics. Industry leaders are characterized by proven clinical-filter performance, validated manufacturing quality and breadth of channel access; mid-tier and niche players compete on specialization—such as humidification-compatible HMEs, ultra-low-resistance HEPA devices, and compact filters for portable oxygen/respiratory devices.
- Pentair (engineered filtration division) and Pall (Cytiva) stand out for validated high-efficiency appliances suitable for both patient- and machine-side applications and for their deep experience in medical manufacturing controls and regulatory compliance.
- European system suppliers and specialist filtration manufacturers provide broad portfolios spanning electrostatic, hydrophobic pleated media and HME combinations, enabling bundled sales into anesthesia and critical-care accounts.
- Large healthcare OEMs and anesthesia-platform vendors leverage compatibility and integrated consumable strategies to lock value into installed fleets; independent device suppliers focus on differentiated performance or cost leadership for specific use cases.
Recent regulatory clearances in 2025—illustrative of ongoing product refresh activity—show the pace of incremental innovation and market entry. The practical implication for 2026 decision-makers is clear: vendor selection must weigh not only nominal performance claims but also registration status and change-management capabilities.
Regulation, clinical practice and procurement—operational dynamics
Filters for anesthesia and respiratory care are subject to clear design and connector standards and typically follow Class II device pathways in several major jurisdictions. The single-patient-use requirement, coupled with guidance on device handling (no reprocessing, no steam or gas sterilization), shapes hospital inventory policies and total cost calculations. Clinically, service protocols that allow extended circuit duration with patient-side filter exchange create procurement patterns that favor predictable, single-use consumables and simplify traceability.
For manufacturers and purchasers alike, the message is that compliance and tested performance are table stakes; speed-to-market derives from disciplined submission strategies and post-market surveillance capabilities that align with modern hospital procurement expectations.
Six strategic imperatives for 2026
- Design for regulatory-first commercialization: Integrate ISO 13485-aligned processes from concept through production validation so that new SKUs hit market quickly with minimized regulatory friction.
- Pursue modular product platforms: Build families of filter modules (e.g., HME-compatible, high-flow HEPA, hydrophobic machine-side options) that share core components to reduce qualification time and cost.
- Secure raw-material partnerships: Lock multi-year agreements with media suppliers and validate second-source capability to avoid single-point failures during demand surges.
- Differentiate on service and logistics: Offer outcome-oriented contracts—bundling clinical training, inventory-as-a-service and just-in-time replenishment—to accelerate adoption among hospital systems.
- Targeted M&A and alliances: Use acquisition to buy capability (e.g., specialized hydrophobic media, manufacturing footprints in growth markets) rather than volumes alone; prioritize integration of regulatory and QA teams.
- Embed evidence in commercial messaging: Couple filtration performance metrics with peer-reviewed infection-control outcomes and lifecycle-cost models to win formulary inclusion.
How PW Consulting’s report helps you act in 2026
Executives will find this report most useful when planning near-term capital allocations, negotiating multi-year supply contracts, scoping product roadmaps, or screening M&A targets. The study’s scenario-based demand model lets procurement leaders stress-test inventory policies under hospital-capacity and clinical protocol shifts. Product and regulatory teams receive a prioritized checklist for global filings and clinical validation, while corporate development teams get an M&A heatmap and valuation sensitivity analysis tailored to filtration assets.
To preserve commercial value and to encourage hands-on engagement, the report employs a “teaser” release approach: this press summary highlights the analytical depth and the strategic insights available while reserving the detailed segmentation tables, supplier scorecards and proprietary scenario outputs for the full report portal.
Next steps
For executives planning budgets, vendor strategies, product launches or M&A activity in 2026, PW Consulting’s Worldwide Breath Out Filters Market study provides an actionable intelligence pack and a set of executable playbooks. Visit our website to access an executive summary, request a custom briefing or license the full dataset and interactive dashboards.
Contact PW Consulting to schedule a tailored workshop that maps the report’s insights to your organization’s 2026 priorities—whether you are an OEM, distributor, hospital system or investor seeking to convert market visibility into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Breath Out Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Casting Tip & Nozzle Market to Reach USD 480.88 Million by 2032, Growing at a 5.24% CAGR
By pmarketresearch, 2026-08-18
Worldwide Casting Tip And Nozzle Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study on the Worldwide Casting Tip And Nozzle Market delivers an evidence-based, actionable outlook tailored for executives making high-stakes decisions in 2026 and beyond. The market has shown steady recovery and growth through the early 2020s, expanding from a multi-hundred million USD base in 2020 to an estimated USD 336.11 Million in our 2025 base year. Under our central forecast the market continues to expand through the 2026–2032 horizon at a compound annual growth rate (CAGR) of approximately 5.24%, reaching roughly USD 481 Million by 2032. These macro trajectories reflect the combined effect of production intensity in primary metals, demand for higher surface quality, and investment in process efficiencies across continuous casting and die-casting operations.
Worldwide Mocap Camera Market
Why this report matters for 2026 choices
2026 is the inflection point for many strategic decisions in the casting tips and nozzles ecosystem. Companies face simultaneous pressures to raise productivity, reduce water and energy footprints, mitigate raw-material risk, and capture aftermarket revenue. Our work translates market momentum into decision-ready intelligence: where to allocate CAPEX, how to structure supplier contracts, which product innovations warrant accelerated R&D, and what M&A targets meet strategic criteria.
HBM Controller IP Market
-
Timing CAPEX and capacity: the forecast window identifies the optimal window for incremental capacity versus brownfield modernization.
Telemedicine Integrated Consultation Vehicle Market -
Supplier and materials strategy: granular materials risk scenarios inform whether to secure long-term supplies or pursue vertical integration for critical inserts and refractories.
-
Product strategy and aftermarket: the report prioritizes features and service offerings that convert one-time sales into recurring revenue streams.
What’s inside: operational, practitioner-oriented content
PW Consulting designed this study as a practical toolkit for commercial, technical and M&A teams. Content highlights include:
-
Market sizing and forecasting methodology (transparent assumptions and scenario variants) with an interactive model to stress-test pricing, production, and demand shocks.
-
Buyer and OEM segmentation frameworks and procurement personas to support targeted commercial outreach (note: detailed segmentation tables and proprietary split data are available in the full report package).
-
End-to-end supply chain maps and bottleneck analyses identifying critical upstream materials and single-source exposures.
-
Price and margin benchmarking across product families and distribution channels, with recommended margin-improvement levers.
-
Technical appendix on materials and manufacturing: performance trade-offs for ceramic fibers, aluminum silicate systems, zirconia inserts, and composite solutions.
-
Regulatory and quality-control playbooks for secondary cooling systems and continuous-casting spray patterns, intended for process engineers and compliance teams.
-
Transaction support: criteria checklists for bolt-on acquisitions and cross-border roll-ups, plus a short list of prioritized target profiles.
Competitive landscape — reading the field in 2026
The market exhibits moderate concentration: leading firms hold meaningful scale but room remains for niche specialists and technology-focused entrants. This structure favors both platform plays (to aggregate aftermarket services) and focused technology providers (to win technical specifications at OEMs).
-
Pyrotek Inc. — known for modular casting tip assemblies that reduce on-site assembly time and service complexity. Their emphasis on ready-to-insert systems presents a clear value proposition for casthouses focused on uptime and lean operations.
-
AdTech Metallurgical Materials — strong in high-temperature calcined products engineered for twin-roll continuous casting. Recent product catalog updates underscore a push to codify performance claims (e.g., non-stick finishes and dimensional stability at elevated temperatures) into standardized offerings for strip and foil mills.
-
Lechler / Spraying Systems Co. — both firms compete at the intersection of hydraulic and air-mist secondary cooling nozzles. Their differentiators are precision spray engineering, fluid-usage optimization, and strong integration capability with automation and cooling control systems.
-
Dyson Technical Ceramics, Zircoa, and other zirconia-focused suppliers — these specialists address erosion-resistant metering nozzles for steel continuous casting. Their strength is material science and long-run reliability, a premium buyers are willing to pay when extended casting times and quality imperatives dominate.
-
LMM Group and similar refractory suppliers — positioned on the ladle-to-tundish flow-control axis; they compete on delivery security, custom-form components and compatibility with foundry operational practices.
-
hotset GmbH — niche provider of sprue nozzle heaters delivering process control in hot-chamber die casting; a must-watch where die-casting productivity is a priority.
Recent vendor activity reinforces these trends: product catalog refreshes for high-temperature aluminum silicate nozzle families and ongoing engineering emphasis on non-stick, zero-shrinkage components point to incremental competition on materials and repeatability rather than simple price plays.
Materials, technology and process dynamics
Five technical themes shape supplier selection and product roadmaps for 2026:
-
Material performance: zirconia inserts, calcined aluminum silicate systems and ceramic-fiber composites remain the core material toolkit. Their selection is a trade-off among erosion resistance, thermal shock tolerance, and unit cost.
-
Spray and flow precision: uniform spray patterns and flow metering are non-negotiable for preventing surface defects and maximizing yield—driving demand for engineered nozzle geometries and retrofittable control modules.
-
Resource efficiency: water and air consumption reduction are now commercial attributes, not just regulatory responses—products that materially reduce utility intensity command premium placement.
-
Service and modularity: plug-and-play tip assemblies, exchangeable metering systems and aftermarket diagnostics increase uptime and shorten replacement cycles.
-
Digital integration: sensor-enabled nozzles and cloud analytics begin to shift value capture from hardware alone to closed-loop performance services.
High-impact strategic plays for 2026
Based on our scenario analysis, PW Consulting recommends the following priority moves for market participants and their investors:
-
Secure upstream raw-material exposure selectively — hedge zirconia and specialist ceramic supplies where possible, or qualify multiple qualified suppliers to lower single-source risk.
-
Shift to service-led monetization — couple nozzle hardware sales with performance guarantees, spare-part agreements, and remote diagnostics to increase lifetime value.
-
Target high-value niches with clear technical entry barriers (e.g., long-run tundish metering systems, twin-roll nozzles for thin-gauge aluminum) and use joint-development agreements to accelerate adoption.
-
Invest in retrofit-friendly products and field-installable upgrades that reduce OEM procurement cycles and open aftermarket channels.
-
Use M&A to consolidate fragmented aftermarket networks or to acquire sensor and analytics capabilities that accelerate a service transition.
-
Embed water- and energy-efficiency metrics into product specs to win tenders where sustainability is part of procurement scoring.
Top risks and mitigants
Key risks for 2026 decisions include raw-material price volatility, regulatory tightening around water use and emissions, and faster-than-expected substitution through novel materials or additive manufacturing. Each risk has practical mitigants documented in the report — from supplier diversification playbooks to staged CAPEX options and technical validation protocols for new materials.
How to use this report in your 2026 planning cycle
Procurement directors, plant managers, R&D leads and corporate development teams can use the report immediately to:
-
Build scenario-based procurement contracts that align supply commitments with expected production ramps.
-
Prioritize pilot projects that de-risk sensor-enabled nozzle deployments before full rollouts.
-
Screen acquisition targets using our proprietary target-fit scorecard to accelerate diligence.
-
Quantify savings opportunities from switching to higher-efficiency secondary cooling systems and from extending nozzle service life through design changes.
Proprietary data and next steps
To preserve the tactical advantage for report users, we present high-level market trajectories and strategic implications here while retaining the granular segment-level tables, regional splits, and full company benchmarking in the paid report package. That detailed dataset includes downloadable spreadsheets, an interactive forecasting model, full supplier scorecards and technical appendices that underpin the recommendations summarized above.
For teams preparing 2026 budgets, sourcing roadmaps or acquisition pipelines, PW Consulting’s Worldwide Casting Tip And Nozzle Market report is engineered to convert insight into executable plans. Visit our official report page to access the complete dataset, methodological notes, and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Casting Tip And Nozzle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Rocket Propulsion Systems Market Forecast to Grow at 7.5% CAGR, Rising from USD 6,480.5 Million in 2025 to USD 10,751.47 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide Rocket Propulsion System Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As governments and commercial actors accelerate plans for satellite constellations, reusable launchers, and deep-space exploration, the rocket propulsion systems market is entering a decisive phase. PW Consulting’s new market study — with a 2025 base year, a 2020–2025 historical analysis and a 2026–2032 forecast horizon — provides executives with the operational intelligence needed to shape boardroom decisions in 2026. The global market is on a multi-year ascent, underpinned by a steady compound annual growth rate (CAGR) of 7.5% and robust expansion heading into the forecast period. This release highlights the report’s strategic value without disclosing the granular subsegment datapoints reserved for subscribers.
Glass Axial NTC Thermistors Market
Market trajectory and what it means for near-term strategy
Between the historical window and the forecast horizon, the propulsion market demonstrates clear momentum driven by a mix of commercial launch demand, defence modernization, and renewed governmental investment in space exploration. The market’s pace of expansion — captured in a mid-single-digit to high-single-digit CAGR — signals that 2026 will be a make-or-break year for firms that must choose between scaling manufacturing capacity, pivoting to new propellant and engine architectures, or doubling down on service and integration offerings.
Gyratory Crusher Market
- Capital allocation: The growth profile supports disciplined capacity investments, particularly in modular production lines and additive manufacturing, but timing is critical to avoid capital misalignment.
- Product strategy: Diversification across propulsion technologies (chemical, electric, hybrid) should be evaluated against lifecycle economics and reuse strategies that are becoming standard expectations for new entrants.
- Risk-adjusted returns: With steady aggregate growth, companies that combine technology differentiation with resilient supply-chains and regulatory compliance will capture disproportionate upside.
What the report delivers — practical components for executive action
PW Consulting’s study is intentionally built for decision-makers who require actionable insights rather than descriptive overviews. The report contains:
Worldwide LED Desk Lamp Market
- End-to-end market sizing and a transparent forecasting model (2026–2032) that clients can adapt to their scenarios.
- Technology roadmaps and maturity assessments for liquid, solid, hybrid, and electric propulsion, including a short-list of disruptive enablers (e.g., additive manufacturing, methane and LOX architectures, electric pump-fed cycles).
- Supply-chain heatmaps that identify concentration risks at raw-material, propulsion component, and test-facility nodes, together with mitigation playbooks.
- Commercial and defence go-to-market templates—pricing frameworks, launch-service bundling options, and long-term service contracts that preserve margin as competition intensifies.
- M&A and partnership blueprints: target-screening criteria, synergies assessment, and valuation sensitivities calibrated to propulsion-specific earnings drivers.
- Regulatory and export-control compliance checklists mapped to major jurisdictions, and certification pathways for commercial orbital providers.
- Scenario-driven stress tests for production scale-up, supply-chain disruption, and regulatory tightening, along with prioritized contingency actions.
Competitive landscape — who matters and why
The market remains concentrated enough that incumbent vendors and rapid innovators each influence technology trajectories and commercial norms. Aggregate concentration metrics indicate that the top-tier companies control a meaningful share of industry revenues, reflecting a mix of long-cycle programmes and rapidly scaling private ventures. PW Consulting’s analysis synthesizes public disclosures, test milestones, and programme commitments to profile strategic postures across a representative set of players:
- Aerojet Rocketdyne (Canoga Park, CA) — A legacy propulsion house with deep heritage in cryogenic and modular liquid engines; a strategic asset for governmental heavy-lift programmes and a potential partner for organisations seeking to onshore critical liquid-engine production.
- SpaceX (Hawthorne, CA) — A market-shaper whose iterative engine development and integrated launch-stack economics have reset expectation curves for cost-per-kg and reusability margins.
- Blue Origin (Kent, WA) — Focused on methane/LOX architectures for medium-to-heavy lift, Blue Origin’s propulsion programmes are important for competitive benchmarking in methane-fueled staged architectures.
- Rocket Lab (Long Beach, CA) — Represents the small-to-medium launch segment’s move toward electric-pump-fed and Rutherford-style innovations; an example of how component-level innovation can cascade into new vehicle classes.
- Northrop Grumman (Falls Church, VA) and Avio (Colleferro, Italy) — Both firms illustrate enduring demand for large solid-rocket motor technologies in defence and institutional markets, where reliability and heritage matter more than unit-cost disruption.
- Newer entrants (Ursa Major, Relativity Space, Firefly, Stoke Space) — These companies demonstrate the commercial cycle of rapid prototyping, additive manufacturing, and vertical integration. They are important from a competitive-threat and partnership-opportunity perspective.
- Major OEMs in Asia (IHI Corporation, Mitsubishi Heavy Industries) — Reflect regional industrial strategies to sustain national launch capability and support commercial market entrants.
Recent industry events — test milestones, first flights, and contract awards — are reshaping partner and supplier strategies. Examples include full-duration static fires of next-generation engines, first flights of vehicles using new boosters, and government contract wins that restart legacy-production lines. These developments accelerate decisions around test-facility capacity, production scaling, and rightsized supplier portfolios.
Regulation, export controls and supply-cost dynamics — immediate operational priorities
- Export controls and ITAR: Propulsion technologies remain closely controlled in key jurisdictions. Organisations must incorporate export-license lead times and compliance costs into revenue models and partnership timetables.
- EU dual-use controls: Recent regulatory frameworks limit cross-border component flows; firms targeting non-domestic growth should structure supply chains to reduce strategic choke points.
- Certification regimes: Commercial operators must factor in regulatory qualification under aviation and spaceflight safety statutes as part of time-to-market and product roadmap planning.
- Raw-material pricing: Industrial inputs (for example, LOX pricing band observations) have implications for OPEX sensitivities and should inform long-term purchase agreements and on-site production investments.
- Geopolitical sourcing: Sanctions and export restrictions on specific foreign propulsion systems have driven substituted domestic supply programmes and new industrial partnerships—opportunities for companies that can offer certified alternatives.
Risks and mitigation — what to prioritize in 2026
Our risk matrix synthesises the primary threats to 2026 execution along with mitigants that can be operationalised immediately:
- Supply-chain concentration: Mitigate by dual-sourcing critical components, qualifying secondary suppliers, and investing in inventory hedging that balances working capital with mission assurance.
- Certification bottlenecks: Pre-position engineering resources on compliance pathways and engage regulators early through pilot qualification programmes.
- Capex misalignment: Defer non-essential greenfield capacity until validated demand signals; prefer modular upgrades and contract manufacturing to reduce fixed-cost exposure.
- Competitive commoditisation: Protect margins through system integration services, long-term maintenance contracts, and IP on manufacturing processes (e.g., printing geometries, unique turbopump designs).
- Regulatory shock: Scenario-plan for tightened export controls or sanctions; pursue localization and certified replacements where feasible.
Practical recommendations for boardrooms and corporate development teams
For 2026 decision cycles, PW Consulting recommends a three-track approach:
- De-risk and scale: Prioritise investments that shorten test-to-qualification timelines and enable scalable production without large upfront fixed costs. Where capital is required, stage investments against validated commercial commitments or firm government contracts.
- Partner and hedge: Combine strategic partnerships with nimble supplier qualification programs. Pursue JV structures in markets with restrictive export regimes to secure access while preserving compliance.
- Differentiate through services and systems: Move up the value chain by offering propulsion-as-a-service, integrated launch packages, or long-term sustainment contracts that smooth revenue volatility.
Why PW Consulting’s full report is decision-critical
This preview outlines the strategic contours that will influence outcomes in 2026, but boards and strategy teams require the full dataset and scenario models to act with precision. The complete report includes editable forecast models, supplier scorecards, technology readiness timelines, and a curated list of potential M&A and partnership targets with valuation and synergy assumptions. It also provides a regulatory playbook customised for major export-control regimes and certification pathways—tools that materially shorten analysis-to-decision cycles.
To access the full intelligence package — including source-modeled forecasts, proprietary risk scoring, and our recommended implementation roadmaps — PW Consulting invites corporate subscribers and institutional clients to download the comprehensive report or schedule a strategic briefing with our aerospace and defence practice leaders.
Closing note
The worldwide rocket propulsion system market delivers measurable growth and strategic opportunity, but success in 2026 will hinge on disciplined capital allocation, rigorous compliance, and an operational approach that converts technology advantage into resilient revenue streams. PW Consulting’s study is designed to equip leaders with the foresight and the playbooks to win — the full, granular intelligence is available in our complete report.
For detailed analysis of this topic, please visit the official page: Worldwide Rocket Propulsion System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Indirect Gas-fired Make-up Air Unit Market to Expand at 5.3% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Indirect Gas-fired Make-up Air Unit Market: Strategic Preview for 2026 Decision-Making
Executive summary
As organizations plan capital and specification decisions for 2026, PW Consulting’s new market study on the worldwide indirect gas-fired make-up air unit (MUA) market offers essential strategic context. The global market has expanded from roughly USD 682.5 million in 2020 to about USD 878.0 million in the report’s base year (2025), and our forecast points to continued expansion through 2032 with a compound annual growth rate (CAGR) of 5.3% across the 2026–2032 horizon. By 2032 the overall market is projected to surpass USD 1.26 billion. These topline dynamics matter for procurement, specification, and capital planning: they imply persistent demand, incremental technology adoption, and an environment where supply-chain resilience and compliance are deciding factors for buyers and vendors alike.
Worldwide Risk Advisory Service Market
Why this preview matters for 2026 procurement and engineering teams
-
Timing and scale: The market trajectory signals that 2026 will be a pivotal year for translating longer-term portfolio plans into orders. Organizations that align procurement cycles with expected vendor roadmaps and component availability will avoid costly delays.
UHPLC Columns Market -
Standards and permitting: Recent and upcoming regulatory changes—most notably strengthened ventilation requirements in California’s Title 24 that took effect for permit applications on or after January 1, 2026—mean equipment specified today may require additional controls, verification, or documentation at permit stage. Early specification reduces rework risk.
LV Breaker Panels Market -
Component constraints: Volatility in upstream materials markets (for example, steel pricing shocks observed in China and fluctuations in the global heat-exchanger supply base) will influence lead times and input costs. Buyers must balance total cost of ownership with availability risk.
Market dynamics and structural drivers
The market’s steady growth is supported by several durable forces. First, tightening indoor air quality expectations and ventilation codes are lifting baseline demand for dedicated make-up air solutions in commercial, institutional, and industrial projects. Second, a focus on energy efficiency – including tighter combustion and fan control strategies – is driving upgrades from legacy packaged equipment to units with higher modulation, advanced controls, and better heat-exchanger longevity. Third, industrial applications that require contaminant control create recurring replacement and retrofit activity, creating a multi-year demand stream rather than one-off installations.
On the supply side, the market shows moderate concentration: the top three players account for a meaningful share of the segment, while a broader set of regional and niche manufacturers make up an expanded competitive field. This constellation creates a market where established OEMs retain channel strength, but specialist vendors and system integrators can capture value through differentiated product features or service models.
Key headwinds and risk factors for 2026
-
Raw material and component inflation: Recent price movements in steel and tightness in heat-exchanger capacity are squeezing suppliers’ margins and extending lead times for certain configurations. Procurement teams should bake contingency into bid evaluation and consider early supplier engagement.
-
Regulatory complexity: National and state-level ventilation and energy codes continue to evolve. Compliance is increasingly tied to documentation of mechanical system performance at permit and occupancy phases, making factory testing and clear commissioning protocols a procurement differentiator.
-
Channel and specification inertia: Building owners and engineers often default to incumbent suppliers. New entrants or product innovations must demonstrate comprovable installation and maintenance advantages to displace entrenched options.
Competitive landscape: what buyers and strategists need to know
The competitive set combines large HVAC incumbents, regionally strong manufacturers, and specialist players focused on kitchen and industrial ventilation challenges. Below are strategic profiles that summarize capabilities and product positioning without divulging proprietary market shares.
-
Greenheck (Schofield, Wisconsin, USA) — A recognized leader for robust indirect gas-fired MUA product lines with flexible combustion control (staged/modulating options), broad capacity coverage, and multi-application suitability (outdoor, recirculating, VAV). Strengths: deep channel distribution, comprehensive product documentation, and strong aftermarket support. Recent documentation updates (notably multiple IOM revisions through 2024) reflect an emphasis on installation clarity and VAV integration—attributes valued by specifiers managing complex controls integration.
-
Modine HVAC (Racine, Wisconsin, USA) — Offers a portfolio that spans outdoor power-vented units and indoor separated combustion models tailored to commercial and industrial tempering needs. Strengths: heritage in packaged gas heating, demonstrated capability for indoor and outdoor installations, and product variations that address code-driven combustion-zone requirements.
-
Trane (Davidson, North Carolina, USA) — Brings scale, rugged packaged solutions, and integration capability with broader building HVAC ecosystems. Strengths: brand recognition, factory-integrated controls and service networks—an attractive proposition for projects seeking single-supplier accountability.
-
AbsolutAire (Kalamazoo, Michigan, USA) — A specialist in direct and indirect fired make-up air with experience in contaminant-control environments. Strengths: product customization and application expertise for environments where ventilation is part of air contaminant management strategy.
-
Applied Air (USA) — Known for packaged DOAS and ventilation solutions that incorporate indirect gas-fired options. Strengths: packaged-system thinking that simplifies coordination between ventilation and building energy targets.
-
Halton (Helsinki, Finland) — Serves commercial kitchens, institutional and industrial spaces with ETL-listed MUA-IF units, and recently updated start-up guidance for both direct and indirect systems—an indicator of investment in commissioning support and compliance documentation.
-
Accurex (USA) — Focused on commercial kitchen applications with product choices that prioritize heat-exchanger longevity. Strengths: application-specific engineering and horizontal-burner designs aimed at extending service life.
-
AAON (Tulsa, Oklahoma, USA) and Cambridge Air Solutions (USA) — Both provide DOAS and MUA solutions, with AAON bringing broader commercial/industrial platform synergies and Cambridge emphasizing patented low-fire-start technology and stainless-steel burners for high-performance tempered air delivery.
Recent product documentation and manual revisions from multiple vendors underscore the market’s emphasis on clear commissioning procedures, variable air volume compatibility, and compliance—areas that frequently determine the winning bid when performance differences are narrow.
What the full report contains (practical, actionable deliverables)
-
Market sizing and trajectory: Topline historicals and forecasts through 2032, plus sensitivity scenarios to stress-test procurement timelines.
-
Segmentation frameworks: Installation types, end-user applications, and regional overlays that explain where demand pockets and retrofit cycles will concentrate (note: granular segment tables and per-region dollar breakdowns are reserved for the full report).
-
Supply-chain health checks: Component risk maps (heat exchangers, controls, burners), lead-time benchmarks, and raw-material shock modeling to inform inventory or supplier-capacity commitments.
-
Regulatory and standards analysis: A practical guide to code impacts (including ASHRAE/ANSI standards and jurisdictional updates like Title 24) and their implications for specification language, factory testing, and submittal requirements.
-
Competitive benchmarking: Comparative capability matrices for the leading OEMs, typical commercial terms, and service-model trade-offs that influence lifecycle costs.
-
M&A and partnerships lens: Identification of attractive consolidation or partner targets for OEMs and system integrators seeking to accelerate technology adoption or geographic reach.
-
Procurement playbook: RFP templates, evaluation scorecards, and commissioning checklists designed for 2026 permit and construction timelines.
Strategic implications & recommended actions for 2026
-
Embed compliance early: Given evolving code enforcement and documentation demands, require vendor-submitted commissioning protocols and factory test reports at bid stage.
-
Mitigate component risk: For critical projects, secure lead-time commitments for heat exchangers and key assemblies or specify alternative validated suppliers to avoid single-source bottlenecks.
-
Value service and lifecycle cost: In a market with mid-level concentration and well-capitalized incumbents, service networks and spare-parts availability commonly tip decisions. Evaluate total lifecycle cost rather than headline unit price.
-
Pursue staged procurement: Where feasible, split orders to align with confirmed regulatory paths and observed price cycles for steel and other inputs, reducing exposure to single-point inflation risk.
-
Prefer documented integration: Seek vendors with demonstrable VAV compatibility, control integration references, and recent, actively maintained IOM/start-up documentation—these are leading indicators of lower installation risk.
Conclusion — how PW Consulting’s report helps you in 2026
For executives, specifiers, and procurement teams making allocation and supplier-selection decisions in 2026, the right market intelligence reduces execution risk and uncovers value opportunities. PW Consulting’s study combines a rigorous topline forecast (showing steady growth from USD ~878.0 million in 2025 toward a mid-2030s market milestone) with practical tools—procurement templates, supplier-risk matrices, and standards-compliance checklists—that translate insights into action. We deliberately retain granular regional and application-level tables in the paid report to protect the full analytical value for subscribers, but this preview highlights the critical dynamics that should shape near-term buying and engineering behavior.
Next steps
To obtain the full dataset, regional and end-use breakdowns, and the procurement playbook referenced above, access the complete Worldwide Indirect Gas-fired Make-up Air Unit Market report on PW Consulting’s website. The full deliverable includes raw data tables, vendor scorecards, and scenario-modeling files to support 2026 capital planning and specification updates.
For detailed analysis of this topic, please visit the official page: Worldwide Indirect Gas-fired Make-up Air Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Oil & Gas Digital Rock Analysis Market to Rise from USD 741.0 Million in 2025 to USD 1,683.7 Million by 2032 at a 12.44% CAGR — North America, Digital Imaging & Unconventional Reservoirs to Lead
By pmarketresearch, 2026-08-18
Worldwide Oil & Gas Digital Rock Analysis Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Oil & Gas Digital Rock Analysis Market delivers a decision-grade synthesis for energy-sector executives planning investments and operational pivots in 2026. The market has matured from early adopters toward repeatable industrial workflows; our analysis shows an overall market expansion from a 2025 base of USD 741.0 million (reported in USD Million) to an expected USD 1,683.7 million by 2032, tracking at a compound annual growth rate (CAGR) of 12.44% over the 2026–2032 forecast period. Equally important, the market exhibits meaningful concentration: the three largest providers control a majority share, with the top five consolidating roughly three quarters of commercial activity.
Non-walk-in Battery Compartment Market
Why This Market Matters to 2026 Strategic Plans
Digital rock analysis has graduated from proof-of-concept to a utility-level capability that materially affects reservoir modeling, enhanced recovery planning, and emerging subsurface services such as carbon capture and storage (CCS). For 2026, companies face three converging imperatives: accelerate time-to-action on subsurface risk, reduce per-well uncertainty to protect capital efficiency, and integrate pore-scale intelligence into enterprise digital twins. The growth trajectory and concentration dynamics highlighted in our report make clear that buyers and investors must think beyond one-off lab tests: procurement, data governance, and vendor orchestration are now strategic levers.
Worldwide Secure DNS Software Market
What the Report Provides — Practical, Executable Content
-
Market Architecture and Sizing Framework — A defensible top-down and bottom-up valuation that reconciles supplier revenues, service bundling, and addressable end-market use cases. The study links observable vendor activity to demand drivers across exploration, unconventional development, EOR, and CCS project pipelines.
Worldwide Spy Cameras Market -
Adoption and Implementation Playbooks — Step-by-step guides for integrating digital rock into corporate workflows, including sample data pipelines (from CT/NMR acquisition to image segmentation and pore-network extraction), QA/QC checklists, and recommended metadata standards to accelerate interoperability with reservoir simulators.
-
Vendor Benchmarking and Use-Case Mapping — A comparative evaluation of incumbent and specialist providers across capabilities (imaging fidelity, simulation toolchains, turnaround, domain expertise). Our vendor matrices identify where to source lab throughput, software, or hybrid managed services depending on the buyer’s strategic intent.
-
Scenario-Based Economic Models — Investor-ready ROI calculators and sensitivity tables that estimate value at stake from improved relative permeability curves, capillary pressure estimation, and micro-scale heterogeneity characterization. These models are tuned to the market growth assumptions and can be re-run with customized inputs.
-
Regulatory and Risk Modules — Practical guidance on monitoring regulatory headwinds and cost exposures (e.g., stewardship obligations and carbon pricing) that affect lifecycle economics for storage and EOR projects.
-
Proven Case Studies and Time-to-Value Examples — Documented examples where pore-scale integration compressed project timelines, reduced drilling risk, or unlocked new storage sites for CCS with measurable value impacts.
Competitive Landscape: Who Matters and Why
The market’s concentration reflects two dynamics: scale-enabled service integration by majors and focused innovation from boutique specialists. Leading oilfield service and technology firms provide end-to-end digital core workflows and leverage installed relationships to cross-sell core analysis into broader petrotechnical engagements. Specialized software and microscopy vendors supply high-fidelity building blocks that power third-party and in-house analyses.
-
SLB (Schlumberger Limited) — Brings integrated Digital SCAL capabilities that combine physical measurements with digital rock analytics to deliver rapid, micropore-informed flow performance simulations. Their strength lies in coupling global lab networks with reservoir modeling platforms for multi-scenario sensitivity analysis.
-
Halliburton — Known for accelerated workflows (e.g., FastSCAL™) that compress delivery schedules and enable parallel pore-scale simulation. The company’s approach focuses on operationalizing pore-scale outputs for reservoir description and near-term optimization.
-
Core Laboratories N.V. — A specialist in advanced core and fluid analysis, with recent capacity expansion targeted at unconventional plays. Investments in regional laboratory capability demonstrate a strategic bet on proximity and rapid turnaround for complex reservoirs.
-
Technology and Software Providers — Vendors such as Thermo Fisher, Math2Market, Dassault Systèmes, and ZEISS supply the imaging, visualization, and simulation toolchains that underpin digital rock physics. Their platforms are central to non-destructive pore-scale experiments and relative permeability modeling under EOR conditions.
-
Regional and Niche Players — Companies like Petricore and local technology providers support specialized offerings, particularly around CCS and integrated reservoir/monitoring suites. They are often differentiated by domain expertise and tailored service bundles for specific regulatory or project environments.
Recent market moves illustrate these dynamics: a major lab opening focused on unconventional core analysis in the Middle East expanded regional diagnostic capacity; strategic collaborations between service companies and specialist labs have demonstrably shortened delivery cycles; and cross-disciplinary alliances between digital rock specialists and CCS service providers are creating new integrated offerings that combine petrophysical and geochemical diagnostics. Our report documents these developments and analyzes the likely downstream effects on pricing, procurement, and partnership strategies.
Regulatory and Macro Factors That Will Shape 2026 Outcomes
Public policy continues to influence the value equation for digital rock investments. Carbon pricing schemes, increasing stewardship obligations for geologic storage, and country-level tax trajectories introduce explicit and implicit costs that change project selection criteria. For instance, recent policy actions have introduced stewardship fees and adjusted carbon taxation levels in key jurisdictions; globally, carbon pricing frameworks now cover a significant portion of emissions and have mobilized substantial public funding. These developments raise the bar for due diligence on subsurface projects and enhance the value of high-confidence pore-scale characterization for both EOR and CCS.
Strategic Imperatives and Actionable Recommendations for 2026
-
Adopt an Outcome-Oriented Procurement Model — Move from unit-price contracting to outcome-linked engagements where vendors are incentivized on time-to-insight and integration into reservoir models. This reduces the friction of data handoffs and aligns incentives across lab, software, and modeling teams.
-
Invest in Data Governance and Interoperability — Standardize metadata, file formats, and API contracts now to enable rapid scale-up when digital rock-derived inputs are needed across many wells or storage sites. Early investment here reduces long-term integration costs.
-
Pilot Hybrid Sourcing Models — Blend in-house competencies with specialist vendors to balance flexibility and scale. Use managed-service pilots to test turnaround and productionization constraints before committing to capital-intensive lab expansions.
-
Align Digital Rock Roadmaps with Carbon and EOR Strategies — Where CCS or EOR ambitions exist, prioritize digital rock assessments that quantify storage capacity, injectivity, and trapping mechanisms. Regulatory obligations around stewardship and carbon pricing make early, defensible subsurface characterization a competitive advantage.
-
Monitor Market Concentration and M&A Signals — The current concentration underscores the potential for strategic partnerships or acquisitions to secure access to proprietary datasets and workflows. Assess targets not only for capability but for complementary data holdings and geographic footprint.
What You Won’t Find in This Preview — and Where to Get It
This communiqué follows a “trailer” approach: we present the strategic implications, methodological rigor, and vendor dynamics that will guide 2026 decisions while intentionally omitting the report’s proprietary granular breakdowns—such as detailed regional shares, application-level revenue splits, and full vendor scorecards. Those detailed tables, scenario spreadsheets, and executable procurement templates are included in the full report package and are designed to be ingested directly into corporate capital planning and technical workflows.
For executives and investment teams preparing 2026 budgets and strategies, access to the full dataset and modelled scenarios will materially change the decision calculus. PW Consulting’s full report includes downloadable model files, vendor benchmark sheets, and configurable ROI tools to translate the high-level findings in this preview into specific investment and operational plans.
Closing Note for Decision-Makers
Digital rock analysis is no longer a niche capability—it is an enabler of higher confidence subsurface decisions that increasingly determine capital productivity. The market’s strong growth profile and concentration make 2026 a pivotal year to establish or recalibrate positioning. Whether your objective is to accelerate development, de-risk storage projects, or capture value through technology-led differentiation, the structured insights and operational playbooks in PW Consulting’s full study will provide the tactical fidelity you need to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Oil and Gas Digital Rock Analysis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com