

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 5.42% CAGR for Worldwide Ultra‑Low Temperature Freezers for Medical Market

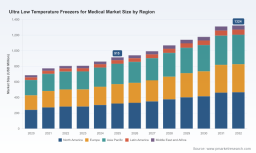
Worldwide Ultra Low Temperature Freezers for Medical Market — Strategic Preview
PW Consulting today releases a strategic preview accompanying our forthcoming market research report on the Worldwide Ultra Low Temperature (ULT) Freezers for Medical Market. Purpose-built for executives planning capital investments, procurement heads, product leaders and investors in 2026, this briefing distills the high-impact takeaways from a comprehensive study that spans historical performance (2020–2025), uses 2025 as the base year, and delivers a granular forecast through 2032.
Worldwide Amino Acetic Acid Market
Why this matters for 2026 decision cycles
The ULT freezer market for medical use is no longer a niche equipment category — it is a business-critical intersection of clinical compliance, lifecycle cost management and sustainability targets. Our analysis shows the global market grew steadily through the 2020–2025 period and reached an inflection point in 2025. The market is positioned to expand at a compound annual growth rate (CAGR) of approximately 5.42% over the 2026–2032 forecast window, reaching materially larger scale by 2032.
Worldwide Mechanical Estimating Software Market
That trajectory creates two imperative realities for decision-makers in 2026:
Worldwide L-Glutamic Acid Market
- Capital allocation choices made this year — whether to retrofit legacy -86°C assets, replace with new energy-efficient units, or outsource storage to third-party biobanks — will determine five- to seven-year operating budgets and compliance risk profiles.
- Regulatory and certification changes are tightening validation requirements for storage equipment, raising the bar for product design, documentation and aftermarket service — decisions on suppliers, certification investments and service contracts must reflect that new baseline.
What the market dynamics mean in practice
Our report integrates macro drivers that are changing procurement and product strategies across hospitals, biobanks, pharmaceutical companies and research institutes. Key dynamics include:
- Regulatory tightening: The FDA’s Quality Management System Regulation (QMSR), effective February 2, 2026, introduces more prescriptive validation and documentation expectations for equipment used to store high-value medical products. In parallel, ULT freezers intended for storage of vaccines, human cells and tissues remain regulated under EU MDR as medical devices — a continuing design and compliance requirement for suppliers targeting clinical markets.
- Energy and total cost pressure: Legacy -86°C platforms impose high ongoing power costs and create sustainability headwinds for healthcare providers aiming to reduce carbon intensity. Technology advances — including improved insulation, dual-cooling architectures and non-hermetic compressor systems — are enabling substantial daily energy reductions, shifting procurement evaluation from purchase price toward lifecycle cost and environmental impact metrics.
- Consolidation and competitive structure: The market exhibits moderate concentration. Our concentration analysis indicates that the top three suppliers account for over forty percent of the global medical ULT freezer revenue base, while the top five approach the mid‑fifty percent range — a structure that shapes bargaining leverage, aftermarket service models and component supply strategies.
Competitive landscape — what leading suppliers are emphasizing
Manufacturers active in the medical ULT space are differentiating across three axes: compliance and documentation for regulated users; energy and lifecycle economics; and integrated service models (remote monitoring, validation support, and rapid-response maintenance). Our review of incumbent and emerging suppliers highlights distinct positioning:
- Thermo Fisher Scientific Inc. — portfolio depth and global services play. Emphasizes energy efficiency, temperature homogeneity and compliance support for clinical and biobanking customers.
- PHC Corporation (PHCbi) — dual-cooling and eco-efficiency. Continues to invest in dual-cooling architectures and recently expanded its ECO-focused product lines to target energy-conscious institutional buyers.
- Eppendorf AG — laboratory performance and precise control. Focuses on control systems and sample protection for research-intensive users.
- Haier Biomedical — cost and scale advantage. Competes with energy-efficient product variants and models certified for clinical use, leveraging manufacturing scale for price-sensitive markets.
- Helmer Scientific, B Medical Systems, Arctiko, Stirling Ultracold, NuAire, So-Low, Labcold, BINDER, LAUDA, Corepoint Scientific, Accucold — a mix of medical-grade specialists, energy-centric innovators, and regional manufacturers. These firms collectively broaden customer choice across features, certifications and service footprints.
Notably, early-2026 product activity — including new energy-optimized models introduced by major suppliers — underscores a market pivot: vendors are responding to buyer demand for validated, lower-energy ULT solutions that integrate with hospital quality systems.
Regulatory and operational implications for procurement and engineering teams
For organizations evaluating ULT assets in 2026, the convergence of regulation and energy mandates leads to concrete procurement criteria:
- Compliance-first specifications: Require suppliers to demonstrate alignment with FDA QMSR validation pathways and to provide MDR/ISO-compliant design documentation where applicable.
- Lifecycle costing and energy ROI: Shift procurement scoring to include energy consumption metrics, mean time between failures, and predictive maintenance capabilities — not just upfront cost.
- Service and validation packages: Favor vendor offerings that bundle validation kits, IQ/OQ protocols and extended service level agreements to reduce internal validation burden and speed time-to-use.
- Data and remote monitoring: Prioritize controllers and telemetry capable of secure data logging, audit trails and remote alarms to meet clinical chain-of-custody requirements.
Strategic playbook for suppliers, buyers and investors
Our report translates market signals into actionable strategies for three audiences:
- Suppliers and OEMs — Product and commercial strategies: Invest in medical-grade documentation, modular designs that reduce validation cycles, and energy technologies that demonstrably lower TCO. Pursue certification investments (e.g., ISO 13485) and develop bundled service offerings for clinical customers who prize end-to-end compliance.
- Healthcare and laboratory buyers — Procurement and asset-management strategies: Reframe decisions around validated TCO analyses, prioritize vendors with demonstrable compliance workflows, and assess retrofit versus replacement using scenario modelling that accounts for energy savings, downtime risk, and regulatory timelines.
- Investors and financiers — Investment themes: Target companies with differentiated energy platforms, recurring-service revenue models, or superior regulatory-support capabilities. Monitor consolidation dynamics; a mid-market with defined concentration metrics often creates acquisition and roll-up opportunities for scale and service uniformity.
What’s inside the PW Consulting report (practical, non-proprietary overview)
Our full report is constructed to be a working toolkit for 2026 strategy. It combines market sizing and a forward-looking forecast with a suite of operational deliverables that buyers and suppliers can act on immediately, including:
- Scenario-based demand models and TCO calculators that let you test retrofit vs. replacement outcomes under different energy-price and capital-allocation assumptions.
- Supplier benchmarking frameworks covering compliance posture, service coverage, energy performance, and aftermarket economics (presented without disclosing client-sensitive share details).
- Procurement templates and validation playbooks that align with FDA QMSR and EU MDR expectations — IQ/OQ checklists, documentation templates, and audit-ready evidence packages.
- Priority investment roadmaps for R&D and product managers outlining features that materially influence purchase decisions (e.g., dual-cooling redundancy, telemetry integration, and modular refrigeration systems).
- Regulatory impact assessments and risk matrices that connect device-level design choices to organizational validation workloads and compliance timelines.
Executive recommendation — immediate next steps for 2026
Leaders preparing 2026 budgets and capital plans should treat ULT freezer strategy as a cross-functional decision. We recommend four immediate actions:
- Run a short-form TCO and risk assessment across your ULT estate using energy and validation inputs — prioritize candidates for replacement where energy payback and compliance risk align.
- Insist on QMSR- and MDR-aligned evidence from suppliers during RFP stages; require validation support as part of the procurement package to reduce internal workload.
- Negotiate service pilots with telemetry-enabled units to validate real-world energy and uptime performance before committing to large fleet purchases.
- For suppliers, accelerate certification programs and shift commercial offers toward bundle models that lock in recurring revenue while lowering buyer adoption friction.
Where to access the full intelligence
This preview is a strategic extract from PW Consulting’s full report on the Worldwide Ultra Low Temperature Freezers for Medical Market. The complete study includes the full historical dataset, detailed regional and application forecasts, vendor scorecards, and downloadable tools referenced above. The full dataset and templates provide the operational depth required to execute 2026 investment and procurement plans with confidence.
To obtain the full report and associated decision-support tools, visit the PW Consulting publications page. Our team is available to arrange bespoke briefings and to run client-specific scenario workshops that map the report’s insights directly onto your capital and compliance timelines.
PW Consulting — transforming market intelligence into executable strategy for the medical cold chain.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra Low Temperature Freezers for Medical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com