

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Rocket Propulsion Systems Market Forecast to Grow at 7.5% CAGR, Rising from USD 6,480.5 Million in 2025 to USD 10,751.47 Million by 2032

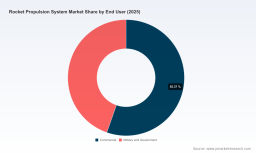
Worldwide Rocket Propulsion System Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As governments and commercial actors accelerate plans for satellite constellations, reusable launchers, and deep-space exploration, the rocket propulsion systems market is entering a decisive phase. PW Consulting’s new market study — with a 2025 base year, a 2020–2025 historical analysis and a 2026–2032 forecast horizon — provides executives with the operational intelligence needed to shape boardroom decisions in 2026. The global market is on a multi-year ascent, underpinned by a steady compound annual growth rate (CAGR) of 7.5% and robust expansion heading into the forecast period. This release highlights the report’s strategic value without disclosing the granular subsegment datapoints reserved for subscribers.
Glass Axial NTC Thermistors Market
Market trajectory and what it means for near-term strategy
Between the historical window and the forecast horizon, the propulsion market demonstrates clear momentum driven by a mix of commercial launch demand, defence modernization, and renewed governmental investment in space exploration. The market’s pace of expansion — captured in a mid-single-digit to high-single-digit CAGR — signals that 2026 will be a make-or-break year for firms that must choose between scaling manufacturing capacity, pivoting to new propellant and engine architectures, or doubling down on service and integration offerings.
Gyratory Crusher Market
- Capital allocation: The growth profile supports disciplined capacity investments, particularly in modular production lines and additive manufacturing, but timing is critical to avoid capital misalignment.
- Product strategy: Diversification across propulsion technologies (chemical, electric, hybrid) should be evaluated against lifecycle economics and reuse strategies that are becoming standard expectations for new entrants.
- Risk-adjusted returns: With steady aggregate growth, companies that combine technology differentiation with resilient supply-chains and regulatory compliance will capture disproportionate upside.
What the report delivers — practical components for executive action
PW Consulting’s study is intentionally built for decision-makers who require actionable insights rather than descriptive overviews. The report contains:
Worldwide LED Desk Lamp Market
- End-to-end market sizing and a transparent forecasting model (2026–2032) that clients can adapt to their scenarios.
- Technology roadmaps and maturity assessments for liquid, solid, hybrid, and electric propulsion, including a short-list of disruptive enablers (e.g., additive manufacturing, methane and LOX architectures, electric pump-fed cycles).
- Supply-chain heatmaps that identify concentration risks at raw-material, propulsion component, and test-facility nodes, together with mitigation playbooks.
- Commercial and defence go-to-market templates—pricing frameworks, launch-service bundling options, and long-term service contracts that preserve margin as competition intensifies.
- M&A and partnership blueprints: target-screening criteria, synergies assessment, and valuation sensitivities calibrated to propulsion-specific earnings drivers.
- Regulatory and export-control compliance checklists mapped to major jurisdictions, and certification pathways for commercial orbital providers.
- Scenario-driven stress tests for production scale-up, supply-chain disruption, and regulatory tightening, along with prioritized contingency actions.
Competitive landscape — who matters and why
The market remains concentrated enough that incumbent vendors and rapid innovators each influence technology trajectories and commercial norms. Aggregate concentration metrics indicate that the top-tier companies control a meaningful share of industry revenues, reflecting a mix of long-cycle programmes and rapidly scaling private ventures. PW Consulting’s analysis synthesizes public disclosures, test milestones, and programme commitments to profile strategic postures across a representative set of players:
- Aerojet Rocketdyne (Canoga Park, CA) — A legacy propulsion house with deep heritage in cryogenic and modular liquid engines; a strategic asset for governmental heavy-lift programmes and a potential partner for organisations seeking to onshore critical liquid-engine production.
- SpaceX (Hawthorne, CA) — A market-shaper whose iterative engine development and integrated launch-stack economics have reset expectation curves for cost-per-kg and reusability margins.
- Blue Origin (Kent, WA) — Focused on methane/LOX architectures for medium-to-heavy lift, Blue Origin’s propulsion programmes are important for competitive benchmarking in methane-fueled staged architectures.
- Rocket Lab (Long Beach, CA) — Represents the small-to-medium launch segment’s move toward electric-pump-fed and Rutherford-style innovations; an example of how component-level innovation can cascade into new vehicle classes.
- Northrop Grumman (Falls Church, VA) and Avio (Colleferro, Italy) — Both firms illustrate enduring demand for large solid-rocket motor technologies in defence and institutional markets, where reliability and heritage matter more than unit-cost disruption.
- Newer entrants (Ursa Major, Relativity Space, Firefly, Stoke Space) — These companies demonstrate the commercial cycle of rapid prototyping, additive manufacturing, and vertical integration. They are important from a competitive-threat and partnership-opportunity perspective.
- Major OEMs in Asia (IHI Corporation, Mitsubishi Heavy Industries) — Reflect regional industrial strategies to sustain national launch capability and support commercial market entrants.
Recent industry events — test milestones, first flights, and contract awards — are reshaping partner and supplier strategies. Examples include full-duration static fires of next-generation engines, first flights of vehicles using new boosters, and government contract wins that restart legacy-production lines. These developments accelerate decisions around test-facility capacity, production scaling, and rightsized supplier portfolios.
Regulation, export controls and supply-cost dynamics — immediate operational priorities
- Export controls and ITAR: Propulsion technologies remain closely controlled in key jurisdictions. Organisations must incorporate export-license lead times and compliance costs into revenue models and partnership timetables.
- EU dual-use controls: Recent regulatory frameworks limit cross-border component flows; firms targeting non-domestic growth should structure supply chains to reduce strategic choke points.
- Certification regimes: Commercial operators must factor in regulatory qualification under aviation and spaceflight safety statutes as part of time-to-market and product roadmap planning.
- Raw-material pricing: Industrial inputs (for example, LOX pricing band observations) have implications for OPEX sensitivities and should inform long-term purchase agreements and on-site production investments.
- Geopolitical sourcing: Sanctions and export restrictions on specific foreign propulsion systems have driven substituted domestic supply programmes and new industrial partnerships—opportunities for companies that can offer certified alternatives.
Risks and mitigation — what to prioritize in 2026
Our risk matrix synthesises the primary threats to 2026 execution along with mitigants that can be operationalised immediately:
- Supply-chain concentration: Mitigate by dual-sourcing critical components, qualifying secondary suppliers, and investing in inventory hedging that balances working capital with mission assurance.
- Certification bottlenecks: Pre-position engineering resources on compliance pathways and engage regulators early through pilot qualification programmes.
- Capex misalignment: Defer non-essential greenfield capacity until validated demand signals; prefer modular upgrades and contract manufacturing to reduce fixed-cost exposure.
- Competitive commoditisation: Protect margins through system integration services, long-term maintenance contracts, and IP on manufacturing processes (e.g., printing geometries, unique turbopump designs).
- Regulatory shock: Scenario-plan for tightened export controls or sanctions; pursue localization and certified replacements where feasible.
Practical recommendations for boardrooms and corporate development teams
For 2026 decision cycles, PW Consulting recommends a three-track approach:
- De-risk and scale: Prioritise investments that shorten test-to-qualification timelines and enable scalable production without large upfront fixed costs. Where capital is required, stage investments against validated commercial commitments or firm government contracts.
- Partner and hedge: Combine strategic partnerships with nimble supplier qualification programs. Pursue JV structures in markets with restrictive export regimes to secure access while preserving compliance.
- Differentiate through services and systems: Move up the value chain by offering propulsion-as-a-service, integrated launch packages, or long-term sustainment contracts that smooth revenue volatility.
Why PW Consulting’s full report is decision-critical
This preview outlines the strategic contours that will influence outcomes in 2026, but boards and strategy teams require the full dataset and scenario models to act with precision. The complete report includes editable forecast models, supplier scorecards, technology readiness timelines, and a curated list of potential M&A and partnership targets with valuation and synergy assumptions. It also provides a regulatory playbook customised for major export-control regimes and certification pathways—tools that materially shorten analysis-to-decision cycles.
To access the full intelligence package — including source-modeled forecasts, proprietary risk scoring, and our recommended implementation roadmaps — PW Consulting invites corporate subscribers and institutional clients to download the comprehensive report or schedule a strategic briefing with our aerospace and defence practice leaders.
Closing note
The worldwide rocket propulsion system market delivers measurable growth and strategic opportunity, but success in 2026 will hinge on disciplined capital allocation, rigorous compliance, and an operational approach that converts technology advantage into resilient revenue streams. PW Consulting’s study is designed to equip leaders with the foresight and the playbooks to win — the full, granular intelligence is available in our complete report.
For detailed analysis of this topic, please visit the official page: Worldwide Rocket Propulsion System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com