

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Processed Seafood Market Set to Reach USD 86,105.63 Million by 2032 at a 5.12% CAGR

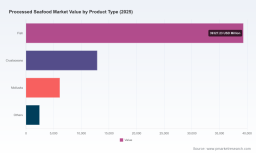
Worldwide Processed Seafood Market 2026: Strategic Imperatives from PW Consulting
As senior industry analysts at PW Consulting, we are releasing an executive preface to our new Worldwide Processed Seafood Market report — a focused, actionable briefing designed to sharpen corporate decisions throughout 2026. The processed seafood sector is entering a phase where steady volume growth, material-price volatility, evolving traceability obligations, and concentrated pockets of strategic scale are creating both clear opportunities and asymmetric risks. This pre-release summarizes the macro trajectory, competitive dynamics, regulatory inflection points, and the pragmatic toolset our full report delivers to executives preparing 2026 plans.
Worldwide Advertising Management Platform Market
Market trajectory at a glance
The processed seafood marketplace has expanded meaningfully over the last half-decade. PW Consulting’s baseline sizing shows a market that grew from roughly USD 48.5 billion in 2020 to approximately USD 60.8 billion by the 2025 base year. Under our forecasted scenarios for the 2026–2032 horizon, the market continues to expand at a compound annual growth rate of 5.12%, with an estimated market value of about USD 63.7 billion in 2026 and sustained growth thereafter.
Snowblower Market
That steady, mid-single-digit CAGR reflects three simultaneous dynamics: (1) persistent consumer demand for protein convenience and value-added seafood formats; (2) upward pressure on raw-material and logistics costs; and (3) regulatory and traceability investments that are shifting cost and capability requirements for processors and brand owners. For executives planning capital allocation, portfolio prioritization, or M&A activity in 2026, these macro facts are non-negotiable inputs.
Outdoor Fixed Screen Market
Why this report matters for 2026 decisions
- Practical forecasting tailored to decision windows: We translate market growth and price volatility into planning scenarios that align with typical 12–36 month corporate decision cycles, enabling CFOs and business unit heads to stress-test budgets and contract strategies.
- Regulatory-readiness mapping: The report maps current and imminent traceability, trace testing, and food-safety obligations to operational checklists and CAPEX timelines — critical for avoiding supply disruptions and costly recalls.
- Actionable competitor playbook: Beyond headline rankings, we profile leading processors by capability (cold chain, value-added manufacturing, brand reach) and suggest concrete counter-moves for market entrants and incumbents alike.
- Scenario-based sourcing strategies: We provide decision trees for diversifying raw-material channels, managing freight and tariff exposure, and optimizing buffer inventories under multiple price and supply-shock scenarios.
What the full report contains (practical modules)
- Dynamic market model — interactive dashboards with year-by-year baseline and scenario projections for 2020–2032, ready for export into financial models.
- Segmentation frameworks — region, processing type, and product type segmentation with historic series and forecast splits (note: this preface omits granular subsegment figures; full data tables are available with the report).
- Competitive matrix and capability maps — supplier footprints, vertical-integration scores, and value-chain strengths and weaknesses for major players.
- Regulatory & compliance playbook — FSMA traceability alignment, GDST modular standards implications, and food-safety testing programs translated into facility-level actions and investment timetables.
- Risk & resilience toolkit — recall-response templates, supplier audit prioritization, and insurance/indemnity negotiation guides tailored to processed seafood.
- Go-to-market & innovation levers — product-format prioritization (e.g., frozen value-add vs. commodity canned lines), private-label strategies, brand partnerships, and commercial pricing elasticity analysis.
Competitive landscape — what to watch in 2026
The processed seafood industry is structurally fragmented: the top three and top five firms account for single-digit to low-twenties percentage shares of global market value, leaving substantial room for regional champions and nimble innovators. This fragmentation creates fertile ground for strategic consolidation, targeted bolt-on acquisitions, and capability-driven differentiation.
- Thai Union Group PCL (Samut Sakhon, Thailand) — A global leader across canned tuna, frozen seafood, and value-added brands with an extensive worldwide supply chain. Recent strategic moves and partner investments position it to accelerate branded and private-label initiatives.
- Maruha Nichiro Corporation (Tokyo, Japan) — One of the largest integrated seafood concerns with broad processed seafood operations and deep procurement channels in Asia and beyond.
- Mowi ASA (Bergen, Norway) — The world’s largest salmon farming and processing company, focused on retail and foodservice fillets, portions, and value-added products.
- Nippon Suisan Kaisha (Nissui) (Tokyo, Japan) — A major integrated player with strong frozen and highly-processed product capabilities and global distribution reach.
- High Liner Foods (Nova Scotia, Canada) — A leading North American frozen value-added specialist; its 2025 acquisition activity expanded its branded portfolio and U.S. market depth.
- Trident Seafoods, Lerøy Seafood Group, Royal Greenland, Austevoll Seafood, Cooke Inc., Pacific Seafood Group, Bolton Group, Kyokuyo — Each brings differentiated strengths in wild-caught niches, aquaculture integration, regional distribution networks, or European market presence.
Collectively, these players illustrate two viable strategic archetypes for 2026: (1) scale-driven integration focused on raw-material security and cost efficiency; and (2) capability-driven specialization emphasizing branded value-adds, traceability differentiation, and retail/foodservice partnerships.
Regulatory and supply signals shaping near-term strategy
- Traceability standardization: The Global Dialogue on Seafood Traceability (GDST) public consultation (2026) signals a shift toward a commodity-agnostic, modular standard that will make traceability investments more interoperable but also raise minimum compliance thresholds for processed products.
- FSMA traceability expansion: New FSMA traceability obligations for items on the Food Traceability List introduce recordkeeping needs for farms and processors — companies will need to retrofit or upgrade batch-level traceability and supplier onboarding processes to maintain U.S. market access without friction.
- Food-safety testing and recalls: Recent recall events in frozen products underscore the operational impact of supplier eligibility and testing regimes. We map preventive controls and rapid response protocols that materially reduce recall cost and brand damage.
- Raw-material price pressure: International price indices and USDA outlooks point to above-average upward pressure on seafood pricing into 2026. Companies must plan both hedging and commercial tactics to preserve margin while retaining market share.
Practical recommendations for 2026 planning
- Prioritize traceability investments with ROI gating: Treat traceability as both compliance and commercial enablement. Phase investments by priority markets and SKU value rather than blanket upgrades.
- Revisit sourcing diversification: Move beyond single-origin reliance for high-risk species. Use dual-sourcing contracts and conditional inventory pooling to smooth supply shocks without significant working-capital increases.
- Accelerate value-added frozen capability where margin pools exist: Our market modelling shows compelling risk-adjusted returns for certain frozen value-added formats versus commodity canned lines — but the exact mix is company- and market-dependent; the full report provides the decision matrices and payback scenarios.
- Design targeted M&A playbooks: Given the fragmented market, bolt-on acquisitions can rapidly add processing footprint, retail relationships, or product formats. We provide a prioritized target-screen checklist and integration playbooks to de-risk 100-day plans.
- Embed recall readiness in commercial contracts: Standardize supplier obligations on testing, indemnities, and logistics, and align insurance strategies to preserve cash flow during events.
Case signals and near-term catalysts
A few recent developments signal where executives should allocate attention this quarter:
- High Liner Foods’ 2025 acquisition of leading U.S. frozen brands increased its value-added portfolio and illustrates the attractiveness of branded frozen lines in North America.
- Strategic investment in Thai Union by a major trading house highlights alliance-based approaches to securing scale and market access.
- GDST’s 2026 traceability consultation and FSMA updates elevate traceability from compliance ‘nice-to-have’ to strategic differentiator—companies that lead on verified traceability can command price premiums and preferred placement with large retailers.
- Recent recalls tied to supplier eligibility and contamination incidents are a reminder that operational controls and supplier vetting have direct balance-sheet consequences.
How PW Consulting helps — report deliverables and advisory options
The full report is designed as both an intelligence product and a practical implementation kit. Deliverables include:
- Downloadable time-series market model (2020–2032) with scenario toggles and exportable data tables.
- Segmentation dashboards by region, processing type, and product category (granular splits are available in the paid release).
- Competitive scorecards and M&A target prioritization framework tailored to client strategic intent.
- Operational playbooks for traceability upgrades, supplier risk management, and recall response.
For companies preparing budgets, negotiating supplier agreements, or evaluating acquisition targets in 2026, the intelligence and executable frameworks in our report compress months of research into decision-ready guidance. Because this release follows a “trailer” principle, we have intentionally withheld the granular segment tables and proprietary assumptions that underpin our models; these are included with the full report and our advisory engagements.
Next steps
Executives and investors who require the full dataset, scenario models, and tailored advisory — including workshops to align finance, procurement, and operations teams for 2026 risk scenarios — should contact PW Consulting for access to the complete Worldwide Processed Seafood Market report and accompanying consulting packages. The full report contains the granular segmentation data, forecast assumptions, and playbooks necessary to convert insight into immediate action.
PW Consulting remains committed to providing decision-grade intelligence that turns complex market dynamics into clear, executable strategies. In the face of rising input costs, evolving regulatory frameworks, and fragmented competitive dynamics, the companies that pair disciplined operational rigor with strategic investments in traceability and value-added formats will set the pace in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Processed Seafood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com