

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Indirect Gas-fired Make-up Air Unit Market to Expand at 5.3% CAGR Through 2032

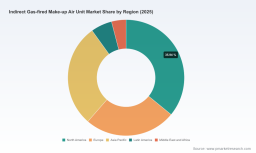
Worldwide Indirect Gas-fired Make-up Air Unit Market: Strategic Preview for 2026 Decision-Making
Executive summary
As organizations plan capital and specification decisions for 2026, PW Consulting’s new market study on the worldwide indirect gas-fired make-up air unit (MUA) market offers essential strategic context. The global market has expanded from roughly USD 682.5 million in 2020 to about USD 878.0 million in the report’s base year (2025), and our forecast points to continued expansion through 2032 with a compound annual growth rate (CAGR) of 5.3% across the 2026–2032 horizon. By 2032 the overall market is projected to surpass USD 1.26 billion. These topline dynamics matter for procurement, specification, and capital planning: they imply persistent demand, incremental technology adoption, and an environment where supply-chain resilience and compliance are deciding factors for buyers and vendors alike.
Worldwide Risk Advisory Service Market
Why this preview matters for 2026 procurement and engineering teams
-
Timing and scale: The market trajectory signals that 2026 will be a pivotal year for translating longer-term portfolio plans into orders. Organizations that align procurement cycles with expected vendor roadmaps and component availability will avoid costly delays.
UHPLC Columns Market -
Standards and permitting: Recent and upcoming regulatory changes—most notably strengthened ventilation requirements in California’s Title 24 that took effect for permit applications on or after January 1, 2026—mean equipment specified today may require additional controls, verification, or documentation at permit stage. Early specification reduces rework risk.
LV Breaker Panels Market -
Component constraints: Volatility in upstream materials markets (for example, steel pricing shocks observed in China and fluctuations in the global heat-exchanger supply base) will influence lead times and input costs. Buyers must balance total cost of ownership with availability risk.
Market dynamics and structural drivers
The market’s steady growth is supported by several durable forces. First, tightening indoor air quality expectations and ventilation codes are lifting baseline demand for dedicated make-up air solutions in commercial, institutional, and industrial projects. Second, a focus on energy efficiency – including tighter combustion and fan control strategies – is driving upgrades from legacy packaged equipment to units with higher modulation, advanced controls, and better heat-exchanger longevity. Third, industrial applications that require contaminant control create recurring replacement and retrofit activity, creating a multi-year demand stream rather than one-off installations.
On the supply side, the market shows moderate concentration: the top three players account for a meaningful share of the segment, while a broader set of regional and niche manufacturers make up an expanded competitive field. This constellation creates a market where established OEMs retain channel strength, but specialist vendors and system integrators can capture value through differentiated product features or service models.
Key headwinds and risk factors for 2026
-
Raw material and component inflation: Recent price movements in steel and tightness in heat-exchanger capacity are squeezing suppliers’ margins and extending lead times for certain configurations. Procurement teams should bake contingency into bid evaluation and consider early supplier engagement.
-
Regulatory complexity: National and state-level ventilation and energy codes continue to evolve. Compliance is increasingly tied to documentation of mechanical system performance at permit and occupancy phases, making factory testing and clear commissioning protocols a procurement differentiator.
-
Channel and specification inertia: Building owners and engineers often default to incumbent suppliers. New entrants or product innovations must demonstrate comprovable installation and maintenance advantages to displace entrenched options.
Competitive landscape: what buyers and strategists need to know
The competitive set combines large HVAC incumbents, regionally strong manufacturers, and specialist players focused on kitchen and industrial ventilation challenges. Below are strategic profiles that summarize capabilities and product positioning without divulging proprietary market shares.
-
Greenheck (Schofield, Wisconsin, USA) — A recognized leader for robust indirect gas-fired MUA product lines with flexible combustion control (staged/modulating options), broad capacity coverage, and multi-application suitability (outdoor, recirculating, VAV). Strengths: deep channel distribution, comprehensive product documentation, and strong aftermarket support. Recent documentation updates (notably multiple IOM revisions through 2024) reflect an emphasis on installation clarity and VAV integration—attributes valued by specifiers managing complex controls integration.
-
Modine HVAC (Racine, Wisconsin, USA) — Offers a portfolio that spans outdoor power-vented units and indoor separated combustion models tailored to commercial and industrial tempering needs. Strengths: heritage in packaged gas heating, demonstrated capability for indoor and outdoor installations, and product variations that address code-driven combustion-zone requirements.
-
Trane (Davidson, North Carolina, USA) — Brings scale, rugged packaged solutions, and integration capability with broader building HVAC ecosystems. Strengths: brand recognition, factory-integrated controls and service networks—an attractive proposition for projects seeking single-supplier accountability.
-
AbsolutAire (Kalamazoo, Michigan, USA) — A specialist in direct and indirect fired make-up air with experience in contaminant-control environments. Strengths: product customization and application expertise for environments where ventilation is part of air contaminant management strategy.
-
Applied Air (USA) — Known for packaged DOAS and ventilation solutions that incorporate indirect gas-fired options. Strengths: packaged-system thinking that simplifies coordination between ventilation and building energy targets.
-
Halton (Helsinki, Finland) — Serves commercial kitchens, institutional and industrial spaces with ETL-listed MUA-IF units, and recently updated start-up guidance for both direct and indirect systems—an indicator of investment in commissioning support and compliance documentation.
-
Accurex (USA) — Focused on commercial kitchen applications with product choices that prioritize heat-exchanger longevity. Strengths: application-specific engineering and horizontal-burner designs aimed at extending service life.
-
AAON (Tulsa, Oklahoma, USA) and Cambridge Air Solutions (USA) — Both provide DOAS and MUA solutions, with AAON bringing broader commercial/industrial platform synergies and Cambridge emphasizing patented low-fire-start technology and stainless-steel burners for high-performance tempered air delivery.
Recent product documentation and manual revisions from multiple vendors underscore the market’s emphasis on clear commissioning procedures, variable air volume compatibility, and compliance—areas that frequently determine the winning bid when performance differences are narrow.
What the full report contains (practical, actionable deliverables)
-
Market sizing and trajectory: Topline historicals and forecasts through 2032, plus sensitivity scenarios to stress-test procurement timelines.
-
Segmentation frameworks: Installation types, end-user applications, and regional overlays that explain where demand pockets and retrofit cycles will concentrate (note: granular segment tables and per-region dollar breakdowns are reserved for the full report).
-
Supply-chain health checks: Component risk maps (heat exchangers, controls, burners), lead-time benchmarks, and raw-material shock modeling to inform inventory or supplier-capacity commitments.
-
Regulatory and standards analysis: A practical guide to code impacts (including ASHRAE/ANSI standards and jurisdictional updates like Title 24) and their implications for specification language, factory testing, and submittal requirements.
-
Competitive benchmarking: Comparative capability matrices for the leading OEMs, typical commercial terms, and service-model trade-offs that influence lifecycle costs.
-
M&A and partnerships lens: Identification of attractive consolidation or partner targets for OEMs and system integrators seeking to accelerate technology adoption or geographic reach.
-
Procurement playbook: RFP templates, evaluation scorecards, and commissioning checklists designed for 2026 permit and construction timelines.
Strategic implications & recommended actions for 2026
-
Embed compliance early: Given evolving code enforcement and documentation demands, require vendor-submitted commissioning protocols and factory test reports at bid stage.
-
Mitigate component risk: For critical projects, secure lead-time commitments for heat exchangers and key assemblies or specify alternative validated suppliers to avoid single-source bottlenecks.
-
Value service and lifecycle cost: In a market with mid-level concentration and well-capitalized incumbents, service networks and spare-parts availability commonly tip decisions. Evaluate total lifecycle cost rather than headline unit price.
-
Pursue staged procurement: Where feasible, split orders to align with confirmed regulatory paths and observed price cycles for steel and other inputs, reducing exposure to single-point inflation risk.
-
Prefer documented integration: Seek vendors with demonstrable VAV compatibility, control integration references, and recent, actively maintained IOM/start-up documentation—these are leading indicators of lower installation risk.
Conclusion — how PW Consulting’s report helps you in 2026
For executives, specifiers, and procurement teams making allocation and supplier-selection decisions in 2026, the right market intelligence reduces execution risk and uncovers value opportunities. PW Consulting’s study combines a rigorous topline forecast (showing steady growth from USD ~878.0 million in 2025 toward a mid-2030s market milestone) with practical tools—procurement templates, supplier-risk matrices, and standards-compliance checklists—that translate insights into action. We deliberately retain granular regional and application-level tables in the paid report to protect the full analytical value for subscribers, but this preview highlights the critical dynamics that should shape near-term buying and engineering behavior.
Next steps
To obtain the full dataset, regional and end-use breakdowns, and the procurement playbook referenced above, access the complete Worldwide Indirect Gas-fired Make-up Air Unit Market report on PW Consulting’s website. The full deliverable includes raw data tables, vendor scorecards, and scenario-modeling files to support 2026 capital planning and specification updates.
For detailed analysis of this topic, please visit the official page: Worldwide Indirect Gas-fired Make-up Air Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com