

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Casting Tip & Nozzle Market to Reach USD 480.88 Million by 2032, Growing at a 5.24% CAGR

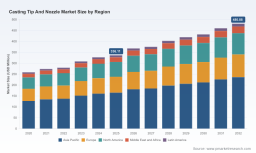
Worldwide Casting Tip And Nozzle Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study on the Worldwide Casting Tip And Nozzle Market delivers an evidence-based, actionable outlook tailored for executives making high-stakes decisions in 2026 and beyond. The market has shown steady recovery and growth through the early 2020s, expanding from a multi-hundred million USD base in 2020 to an estimated USD 336.11 Million in our 2025 base year. Under our central forecast the market continues to expand through the 2026–2032 horizon at a compound annual growth rate (CAGR) of approximately 5.24%, reaching roughly USD 481 Million by 2032. These macro trajectories reflect the combined effect of production intensity in primary metals, demand for higher surface quality, and investment in process efficiencies across continuous casting and die-casting operations.
Worldwide Mocap Camera Market
Why this report matters for 2026 choices
2026 is the inflection point for many strategic decisions in the casting tips and nozzles ecosystem. Companies face simultaneous pressures to raise productivity, reduce water and energy footprints, mitigate raw-material risk, and capture aftermarket revenue. Our work translates market momentum into decision-ready intelligence: where to allocate CAPEX, how to structure supplier contracts, which product innovations warrant accelerated R&D, and what M&A targets meet strategic criteria.
HBM Controller IP Market
-
Timing CAPEX and capacity: the forecast window identifies the optimal window for incremental capacity versus brownfield modernization.
Telemedicine Integrated Consultation Vehicle Market -
Supplier and materials strategy: granular materials risk scenarios inform whether to secure long-term supplies or pursue vertical integration for critical inserts and refractories.
-
Product strategy and aftermarket: the report prioritizes features and service offerings that convert one-time sales into recurring revenue streams.
What’s inside: operational, practitioner-oriented content
PW Consulting designed this study as a practical toolkit for commercial, technical and M&A teams. Content highlights include:
-
Market sizing and forecasting methodology (transparent assumptions and scenario variants) with an interactive model to stress-test pricing, production, and demand shocks.
-
Buyer and OEM segmentation frameworks and procurement personas to support targeted commercial outreach (note: detailed segmentation tables and proprietary split data are available in the full report package).
-
End-to-end supply chain maps and bottleneck analyses identifying critical upstream materials and single-source exposures.
-
Price and margin benchmarking across product families and distribution channels, with recommended margin-improvement levers.
-
Technical appendix on materials and manufacturing: performance trade-offs for ceramic fibers, aluminum silicate systems, zirconia inserts, and composite solutions.
-
Regulatory and quality-control playbooks for secondary cooling systems and continuous-casting spray patterns, intended for process engineers and compliance teams.
-
Transaction support: criteria checklists for bolt-on acquisitions and cross-border roll-ups, plus a short list of prioritized target profiles.
Competitive landscape — reading the field in 2026
The market exhibits moderate concentration: leading firms hold meaningful scale but room remains for niche specialists and technology-focused entrants. This structure favors both platform plays (to aggregate aftermarket services) and focused technology providers (to win technical specifications at OEMs).
-
Pyrotek Inc. — known for modular casting tip assemblies that reduce on-site assembly time and service complexity. Their emphasis on ready-to-insert systems presents a clear value proposition for casthouses focused on uptime and lean operations.
-
AdTech Metallurgical Materials — strong in high-temperature calcined products engineered for twin-roll continuous casting. Recent product catalog updates underscore a push to codify performance claims (e.g., non-stick finishes and dimensional stability at elevated temperatures) into standardized offerings for strip and foil mills.
-
Lechler / Spraying Systems Co. — both firms compete at the intersection of hydraulic and air-mist secondary cooling nozzles. Their differentiators are precision spray engineering, fluid-usage optimization, and strong integration capability with automation and cooling control systems.
-
Dyson Technical Ceramics, Zircoa, and other zirconia-focused suppliers — these specialists address erosion-resistant metering nozzles for steel continuous casting. Their strength is material science and long-run reliability, a premium buyers are willing to pay when extended casting times and quality imperatives dominate.
-
LMM Group and similar refractory suppliers — positioned on the ladle-to-tundish flow-control axis; they compete on delivery security, custom-form components and compatibility with foundry operational practices.
-
hotset GmbH — niche provider of sprue nozzle heaters delivering process control in hot-chamber die casting; a must-watch where die-casting productivity is a priority.
Recent vendor activity reinforces these trends: product catalog refreshes for high-temperature aluminum silicate nozzle families and ongoing engineering emphasis on non-stick, zero-shrinkage components point to incremental competition on materials and repeatability rather than simple price plays.
Materials, technology and process dynamics
Five technical themes shape supplier selection and product roadmaps for 2026:
-
Material performance: zirconia inserts, calcined aluminum silicate systems and ceramic-fiber composites remain the core material toolkit. Their selection is a trade-off among erosion resistance, thermal shock tolerance, and unit cost.
-
Spray and flow precision: uniform spray patterns and flow metering are non-negotiable for preventing surface defects and maximizing yield—driving demand for engineered nozzle geometries and retrofittable control modules.
-
Resource efficiency: water and air consumption reduction are now commercial attributes, not just regulatory responses—products that materially reduce utility intensity command premium placement.
-
Service and modularity: plug-and-play tip assemblies, exchangeable metering systems and aftermarket diagnostics increase uptime and shorten replacement cycles.
-
Digital integration: sensor-enabled nozzles and cloud analytics begin to shift value capture from hardware alone to closed-loop performance services.
High-impact strategic plays for 2026
Based on our scenario analysis, PW Consulting recommends the following priority moves for market participants and their investors:
-
Secure upstream raw-material exposure selectively — hedge zirconia and specialist ceramic supplies where possible, or qualify multiple qualified suppliers to lower single-source risk.
-
Shift to service-led monetization — couple nozzle hardware sales with performance guarantees, spare-part agreements, and remote diagnostics to increase lifetime value.
-
Target high-value niches with clear technical entry barriers (e.g., long-run tundish metering systems, twin-roll nozzles for thin-gauge aluminum) and use joint-development agreements to accelerate adoption.
-
Invest in retrofit-friendly products and field-installable upgrades that reduce OEM procurement cycles and open aftermarket channels.
-
Use M&A to consolidate fragmented aftermarket networks or to acquire sensor and analytics capabilities that accelerate a service transition.
-
Embed water- and energy-efficiency metrics into product specs to win tenders where sustainability is part of procurement scoring.
Top risks and mitigants
Key risks for 2026 decisions include raw-material price volatility, regulatory tightening around water use and emissions, and faster-than-expected substitution through novel materials or additive manufacturing. Each risk has practical mitigants documented in the report — from supplier diversification playbooks to staged CAPEX options and technical validation protocols for new materials.
How to use this report in your 2026 planning cycle
Procurement directors, plant managers, R&D leads and corporate development teams can use the report immediately to:
-
Build scenario-based procurement contracts that align supply commitments with expected production ramps.
-
Prioritize pilot projects that de-risk sensor-enabled nozzle deployments before full rollouts.
-
Screen acquisition targets using our proprietary target-fit scorecard to accelerate diligence.
-
Quantify savings opportunities from switching to higher-efficiency secondary cooling systems and from extending nozzle service life through design changes.
Proprietary data and next steps
To preserve the tactical advantage for report users, we present high-level market trajectories and strategic implications here while retaining the granular segment-level tables, regional splits, and full company benchmarking in the paid report package. That detailed dataset includes downloadable spreadsheets, an interactive forecasting model, full supplier scorecards and technical appendices that underpin the recommendations summarized above.
For teams preparing 2026 budgets, sourcing roadmaps or acquisition pipelines, PW Consulting’s Worldwide Casting Tip And Nozzle Market report is engineered to convert insight into executable plans. Visit our official report page to access the complete dataset, methodological notes, and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Casting Tip And Nozzle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com