

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Formamidinium Iodide (FAI) Market to Soar from USD 62.5 Million in 2025 to USD 360.6 Million by 2032 at a 28.42% CAGR, Fueled by Ultra‑High‑Purity Demand in Perovskite Solar Cells

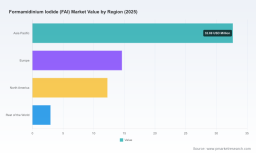
Formamidinium Iodide (FAI) Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive summary
Formamidinium Iodide (FAI) has moved from niche reagent to strategic feedstock within the perovskite ecosystem. PW Consulting’s latest market study shows the FAI market expanding at a compound annual growth rate (CAGR) of 28.42% through our forecast horizon. The market has grown from an estimated USD 16.5 million in 2020 to USD 62.5 million in 2025 and — under our base-case modeling — is projected to exceed USD 360 million by 2032. For executives positioning portfolios, supply chains, and R&D roadmaps in 2026, this trajectory turns a once-tactical material purchase into a potential strategic choke point and a lever for differentiation in solar and opto-electronics value chains.
High Payload Robot Market
Why 2026 is a pivotal planning year
- Commercialization inflection: As perovskite cell efficiency and stability milestones converge with scalable manufacturing techniques, demand for high-performance precursors accelerates. Our demand model shows step-change adoption starting in 2026 as pilot lines transition to early commercial throughput.
- Cost and regulatory squeeze: High-grade FAI manufacturing requires specialized purification technology. PW Consulting’s costing analysis flags a roughly 30% increase in manufacturing expense for ultra‑high‑purity grades relative to standard grades, and regulatory classifications of certain iodine-containing precursors are adding incremental production costs where they apply (estimated +12–18% in affected jurisdictions).
- Strategic supplier selection matters: With market concentration moderate but meaningful (CR3 ≈ 42% and CR5 ≈ 58% in our coverage), buyers face realistic counterparty risk that can influence project timelines and margins. Procurement choices made in 2026 will shape access and price stability into the late 2020s.
Market trajectory and commercial implications
Our top-line numbers serve two functions: they quantify scale and they provide a framework for scenario analysis. The market’s implied growth profile — from the mid‑tens of USD million in 2020 to several hundred million by the early 2030s — reflects a combination of componentization in perovskite PV, increasing adoption in opto-electronic applications, and the premium placed on ultra‑high‑purity precursors for high-efficiency device architectures.
Acetyl L-Carnitine Powder Market
For corporate strategy, the arithmetic is clear: product roadmaps that assume low-cost, commoditized precursor supply risk margin compression as purity and regulatory demands push per‑unit costs higher. Conversely, players that secure differentiated supply sources, invest in upstream purification, or develop tolerance‑for‑impurities in device chemistry can capture disproportionate value.
Omega 3 Nutritional Supplements Market
Drivers, technical context, and regulatory overlays
- Technical advantage: FAI is the stoichiometric precursor for the formamidinium lead iodide (FAPbI3) family that exhibits a narrower bandgap (~1.48 eV) compared with methylammonium‑based perovskites (~1.57 eV). This physical property supports higher theoretical solar conversion efficiency and explains the premium placed on FAI in cell designs targeting higher-efficiency stack architectures.
- Purity economics: The performance gap narrows rapidly if impurities induce phase instabilities or trap states. Achieving ultra‑high purity necessitates additional capital equipment and process steps, which our industrial benchmarking pegs at near‑term cost premiums of roughly 30% versus standard grades. That premium is a material input into device LCOE calculations — and a strategic variable for both materials and device manufacturers.
- Regulatory risk: Evolving chemical classifications in multiple jurisdictions create a non‑trivial compliance and cost overlay. In regions where certain iodine‑containing precursors are regulated as high‑concern substances, manufacturers face permit hurdles, expanded testing, and higher operational expenses — our regional dynamics assessment estimates a 12–18% uplift in production cost where these rules apply.
Competitive landscape — who matters and why
The supplier universe spans small high‑precision specialty houses to larger firms with broad chemical portfolios. Our qualitative and comparative assessment identifies the following strategic archetypes:
- Specialist high‑purity producers: Companies that emphasize in‑house synthesis and ultralow moisture content control position themselves as partners for R&D and early commercial lines. Their strengths are process control, custom packaging for sensitive handling, and small‑batch flexibility.
- Scale‑oriented suppliers with industrial packaging: Firms offering bench‑to‑industrial supply and a diversity of packaging/quantity options are attractive to integrators moving from lab to pilot line, because they reduce the friction of volume ramping.
- Broad distributors and catalog players: These firms facilitate rapid access for research and prototyping but may lack the process improvements and documentation industrial customers require for scale‑up or regulatory compliance.
- Vertically integrated or listed manufacturers: Some manufacturers combine broader chemical portfolios and capital access, enabling investments in purification lines, regulatory programs, and supply security initiatives more readily than small specialists.
Across these archetypes, the competitive battleground centers on three axes: purity and moisture control, supply continuity and scale, and regulatory / documentation capabilities (e.g., REACH compliance, material safety data fidelity, and alternative precursor traceability). In our supplier heatmaps, each named firm is evaluated against those criteria to support buy‑side prioritization (detailed scorecards are reserved for the full report).
Key strategic moves for corporates in 2026
- Secure staged supply commitments: Negotiate two‑tier agreements that bind initial R&D volumes while enabling conditional volume increases tied to pilot‑to‑commercial milestones. Include quality‑by‑lot reporting and moisture limits as contract triggers.
- Pursue selective vertical integration or strategic partnerships: For device manufacturers with high volume targets, backward integration into precursor production — or long‑term tolling/contract manufacturing agreements — materially reduces exposure to spot volatility and regulatory shock.
- Invest in impurity tolerance R&D: Materials science options that reduce reliance on ultra‑high‑purity feedstock (e.g., compositional engineering, additive strategies, defect passivation) can convert raw material premiums into device performance resilience.
- Build regulatory and compliance playbooks: Implement region‑specific mapping of classification risk and associated cost impacts. Quantify how permitting timelines could affect project milestones and embed contingency buffers in rollout plans.
- Prioritize supplier due diligence: Beyond price, evaluate moisture control protocols, trace metal analysis, process reproducibility, and secondary sourcing options. Our report provides a due‑diligence checklist tailored to FAI procurement.
What PW Consulting’s FAI Market report delivers (practical, action‑oriented)
This release is intentionally a strategic preview. The full report equips executives with the operational tools needed to translate market insight into decisions — without disclosing the proprietary segment models that underpin our consulting work. Core deliverables include:
- Scenario‑based market modeling (base, upside, downside) with sensitivity levers for purity premiums, regulatory cost uplifts, and adoption curves for perovskite commercialization.
- Supplier scorecards and short‑list methodology: a repeatable framework to evaluate purity control, scale readiness, documentation practices, and commercial terms. (Note: full supplier rankings and detailed metrics are part of the paid deliverable.)
- Procurement playbook and template contract language: staged volume commitments, quality acceptance testing, traceability clauses, and penalty structures for non‑conforming batches.
- Regulatory impact matrix and compliance roadmap: jurisdictional mapping, likely permitting timelines, and mitigation tactics to neutralize the estimated 12–18% regional cost uplift where applicable.
- Technology readiness and R&D prioritization guide: where to invest in device chemistry vs precursor supply, and how to evaluate the ROI of internal purification capacity.
- M&A and partnership screening criteria: identifying targets for bolt‑on purification capabilities, tolling agreements, or downstream offtake paths aligned with your commercial timeline.
Competitive callouts — how leading suppliers are being positioned
Across the supplier universe, several tactical differentiators stand out. Some firms emphasize ultra‑high purity production with extremely low moisture content and small‑batch flexibility, making them natural partners for early adopters and device developers. Others combine industrial packaging and bench‑to‑industrial supply chains to facilitate volume scaling. Global distributors play the role of fast access and catalog convenience but may require supplemental QA documentation for industrial adoption. Finally, listed and larger manufacturers bring capital to expand purification capacity and support regulatory programs faster than smaller players.
How to use this preview in 2026 planning
- Use the market growth rates and the directional size forecasts here to stress‑test capital allocation and procurement budgets for pilot and early commercial projects.
- Assess whether to lock in long‑term supply now, hedge through diversified sourcing, or invest in purification capacity — guided by your exposure to device performance sensitivity to precursor purity.
- Factor regulatory cost adders into LCOE and margin models and prioritize jurisdictions where compliance pathways are clearer or faster to execute.
Next steps — obtaining the full advisory package
This preview is designed to establish the strategic contours and to prompt executive action. PW Consulting’s full Formamidinium Iodide Market report contains the proprietary segment analysis, supplier rankings, and executable templates that procurement, corporate development, and R&D teams need to act in 2026. For access to the full dataset, supplier scorecards, and tailored advisory engagements, please contact PW Consulting via our official channels to arrange delivery of the complete deliverable and optional deep‑dive workshops.
For detailed analysis of this topic, please visit the official page: Formamidinium Iodide (FAI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com