

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
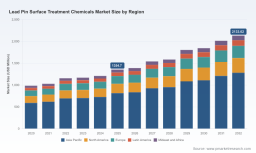
PW Consulting: Worldwide Lead Pin Surface Treatment Chemicals Market at USD 1,354.7 Million (Base Year 2025), Forecast to Reach USD 2,133.02 Million in 2032 at a 6.74% CAGR (2026–2032) — Asia Pacific (USD 813.85M) and Electroplating Solutions Lead

Worldwide Lead Pin Surface Treatment Chemicals Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s newest market research release on the Worldwide Lead Pin Surface Treatment Chemicals Market delivers forward-looking intelligence designed for executives and strategy teams planning for 2026 and beyond. Grounded in a rigorous base year of 2025 and a historical review covering 2020–2025, our forecast scenario extends to 2032. At the market level, revenues reached approximately USD 1,354.7 Million in 2025 and are projected to grow to roughly USD 2,133.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.74% over the 2026–2032 forecast window. These headline dynamics underline sustained demand expansion and meaningful opportunity for differentiated players across chemistry, process design and integrated packaging ecosystems.
Worldwide Drones for Petroleum Market
Why this report matters for 2026 strategic planning
-
Actionable forecasting: The 6.74% CAGR we model is not a top-line projection only — it is decomposed by macro drivers, technology adoption pathways and regulatory inflection points so leaders can prioritize near-term investments without sacrificing long-term resilience.
Disposable Blood Pressure Sensor Market -
Timing and prioritization: 2026 is a pivotal year for many organizations as supply chains reset post‑pandemic, materials costs remain volatile, and environmental regulations accelerate reformulation efforts. Our analysis highlights when and where pressure points will most likely materialize so firms can sequence capex, R&D and commercial initiatives to capture upside.
Laboratory FTIR Spectrometers Market -
Risk‑adjusted scenarios: We provide alternate scenarios that stress-test plans under adverse raw material price swings and progressive regulatory constraints, enabling decision-makers to calibrate hedging strategies and build contingency playbooks.
What the report delivers — practical content for operators and investors
-
Executive dashboards and model access: Dynamic market models (Excel) that allow you to re-run growth scenarios against user-defined assumptions for metal salt costs, VOC limits and plating-line throughput.
-
Go-to-market playbooks: Tactical roadmaps for chemical manufacturers and coatings formulators, including product prioritization matrices, channel strategies and customer segmentation frameworks tailored to lead‑pin and connector ecosystems.
-
Regulatory impact toolkit: A hands‑on guide mapping REACH, EPA and regional phasing timetables to product reformulation imperatives and compliance milestones. The toolkit includes a decision tree for selecting substitution strategies (e.g., chrome-free options, low‑VOC chemistries) across common process flows.
-
Supply chain stress tests: Heat maps and supplier consolidation indices that expose concentrated input risks and logistics bottlenecks — with mitigation playbooks such as dual-sourcing approaches, inventory hedging thresholds and toll-manufacturing arrangements.
-
Competitive benchmarking: Proprietary vendor scorecards covering product portfolio breadth, R&D cadence, regulatory preparedness and global footprint, enabling procurement and corporate development teams to shortlist candidates for partnerships, M&A or strategic alliances.
-
Commercial case studies: Real-world examples showing how formulators reduced hazardous constituents while preserving yield and cycle-time, plus examples of customer conversion economics for eco-friendly alternatives.
Competitive landscape — leaders, challengers and the implications for 2026
The market displays moderate concentration with a CR3 of approximately 41.5% and a CR5 near 56.9%, indicating that a handful of established chemistry providers continue to exercise meaningful influence while mid-sized and regional specialists retain opportunities to capture niche value. Our competitive assessment focuses on companies that demonstrate deep process knowledge, regulatory track records and the ability to support complex electronic packaging flows.
-
Technic Inc. (Cranston, Rhode Island, USA) — Known for specialty electroplating chemistries and precision process support, Technic’s emphasis on precious metal and tin/tin‑alloy solutions positions it well where performance and reliability are paramount. Recent trade show activity in early 2026 highlights continued outreach into adjacent precision markets (e.g., medical device finishes) that cross-sell into electronic component chemistries.
-
MKS | Atotech (Berlin, Germany) — With an extensive portfolio of wet chemical process solutions and pre‑treatment systems, Atotech is a key technology innovator for leadframe and connector processing. Its cleaner and deflashing families underscore the trend towards integrated formulations that simplify line integration and reduce operator handling risks.
-
JCU Corporation (Tokyo, Japan) — A specialist in alkaline electrocleaners, etchants and activators, JCU exemplifies the regional players that excel at high‑precision applications and at supporting convergent process lines typical of advanced IC packaging houses.
-
Shanghai Sinyang Semiconductor Materials Co., Ltd. (Shanghai, China) — As a respondent to large‑volume packaging demand, this supplier represents the competitive pressure from firms that leverage scale and local supply‑chain integration, particularly in major manufacturing corridors.
-
Nihon Parkerizing Co., Ltd. (Tokyo, Japan) — A broad provider of surface treatment chemistries that serves diverse industrial end markets; its capabilities highlight the opportunity for multi-industry firms to cross‑leverage R&D and manufacturing capacity into electronics finish applications.
For buyers and corporate development teams, the market structure implies distinct strategic options: partner with leading global formulators for advanced chemistries and compliance support, or engage nimble regional suppliers to optimize cost and proximity to assembly lines. Our vendor scorecards and negotiation playbooks are designed to accelerate those decisions while preserving optionality.
Regulatory and raw material dynamics — a dual lever shaping 2026 choices
Regulation and raw material price volatility are the dominant systemic forces shaping supplier economics and customer requirements. Global environmental frameworks such as REACH and incremental EPA restrictions continue to push formulators toward chrome‑free, low‑VOC and lower‑hazard chemistries. These regulatory trajectories are not just compliance issues; they reshape cost curves, capital intensity (e.g., investment in closed-loop effluent treatment) and time-to-market for reformulated products.
Concurrently, fluctuations in key inputs — metal salts, specialty acids and performance additives — materially affect gross margins and pricing discipline across the value chain. Our cost‑pass‑through models quantify at what points manufacturers will need to absorb price pressure versus renegotiate supplier contracts, and how procurement teams should revise hedging strategies in 2026 to protect margins without sacrificing growth.
Strategic recommendations for executives in 2026
-
Prioritize regulatory-ready pipelines: Accelerate reformulation projects for chrome‑free and low‑VOC chemistries, but sequence launches to align with customers’ readiness and certification timelines. Use pilot lines to derisk scale-up and capture early adopter premiums.
-
Invest selectively in modular manufacturing: Modular or toll‑manufacturing arrangements reduce capital exposure while enabling rapid responsiveness to localized demand spikes — a critical advantage where leadframe volumes are geographically concentrated.
-
Hedge raw material exposure using layered strategies: Combine tiered supplier contracts, strategic stockpiles for critical inputs and collaborative R&D with suppliers to secure favorable sourcing and co‑development terms.
-
Target high-value alveoli within the value chain: Consider bundling chemistries with process advisory services and analytics (e.g., plating-line digital monitoring) to move from a commodity supplier model toward a solutions provider model that captures service premiums.
-
Prepare for consolidation windows: Given the market’s moderate concentration, 2026–2028 is likely to present acquisition opportunities as mid‑sized players face investment needs to meet regulatory and scale requirements. Build a prioritized target list and pre‑approved integration templates.
How PW Consulting’s report supports implementation
Beyond diagnosis, our report is built for execution. Subscribers gain access to the forecast models, vendor scorecards, regulatory timetables and a prioritized set of near‑term actions calibrated to different risk appetites. For private equity and corporate development teams, the intelligence includes valuation multipliers adjusted for regulatory readiness and technology differentiation — critical inputs when sizing bids or structuring earn‑outs.
Next steps — where to get the full intelligence
This briefing intentionally outlines the strategic contours of the lead pin surface treatment chemicals market while withholding granular segmentation tables and proprietary supplier scoring that drive competitive advantage. To obtain the complete dataset, interactive models and supplier scorecards referenced here, visit the PW Consulting report page and request the full Worldwide Lead Pin Surface Treatment Chemicals Market report. Our team stands ready to run a tailored briefing for executive committees and investment committees to translate the findings into a 90‑day action plan.
For detailed analysis of this topic, please visit the official page: Worldwide Lead Pin Surface Treatment Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com