

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Tank Cleaning Service Market to Hit $14.44 Billion by 2032 with 6.5% CAGR finds PW Consulting
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Tank Cleaning Services Market: Navigating Growth, Compliance, and Consolidation Through 2032
The industrial tank cleaning services sector is undergoing a structural transformation driven by tightening environmental regulations, evolving automation capabilities, and a complex competitive landscape that rewards operational precision and strategic scale. As enterprises across energy, chemicals, and water management navigate shifting compliance mandates and cost pressures, the ability to anticipate market trajectories, evaluate competitor positioning, and align service delivery with operational risk frameworks has become a critical differentiator. Our latest research initiative delivers a comprehensive, decision-ready analysis of this industry, offering executives and strategy teams a clear roadmap for positioning within a market projected to expand from 9.28 billion USD in 2025 to 14.44 billion USD by 2032, sustained by a compound annual growth rate of 6.5 percent. This article outlines the analytical architecture of the study, highlights the strategic dimensions that will shape competitive outcomes, and demonstrates how the intelligence framework can be directly applied to enterprise planning, risk mitigation, and capital allocation decisions in the coming planning cycles.
Macro Trajectory and the Strategic Imperative for Forward-Looking Planning
Understanding the direction and velocity of market expansion is only the starting point for strategic positioning. The sector has demonstrated consistent, compounding growth across the historical window, moving from 6.9 billion USD in 2020 through a sequence of steady annual increases to reach 8.73 billion USD in 2024, before crossing the 9 billion threshold in 2025. The forward trajectory embedded in our base-case methodology indicates accelerated momentum as operational backlogs, regulatory modernization, and infrastructure renewal cycles converge. By 2026, the market is expected to reach 9.8 billion USD, with continued expansion leading to 11.03 billion USD in 2028 and approaching 13.13 billion USD by 2030. The terminal projection of 14.44 billion USD by 2032 underscores a durable growth avenue, provided that service providers and downstream operators can align their capacity planning, technology adoption, and compliance architectures with the pace of market maturation.
Underwater Hull Cleaning Service Market
For corporate strategists, this trajectory is not merely a numerical forecast. It represents a signal of expanding operational complexity. As gross output scales, the requirements for personnel safety protocols, hazardous residue management, environmental containment, and turnaround scheduling intensify. Executives evaluating market entry, service line diversification, or capacity investment must therefore base their decisions on a granular understanding of demand drivers, regional deployment patterns, and the economics of service delivery models. Our research isolates these variables within a structured analytical framework, enabling leaders to translate top-line market growth into actionable capacity planning, partnership strategy, and procurement positioning without relying on industry generalizations or unverified directional trends.
Scope, Structure, and Decision-Ready Analytical Depth
The report is engineered as a practical intelligence asset rather than a high-level market summary. It maps the full value chain of tank cleaning services, from field deployment and hazardous material handling to decontamination methodologies, sludge and residue recovery, waste stream routing, and post-cleaning verification. Each segment of the service lifecycle is evaluated through the lens of operational feasibility, labor intensity, equipment utilization, regulatory exposure, and margin dynamics, allowing clients to benchmark their internal service models against prevailing industry structures.
The analysis employs a multi-dimensional segmentation architecture that disaggregates market behavior across service type, application end-use, and geographic deployment. Rather than presenting isolated data points, the study examines how these segments interact: where labor-intensive approaches remain dominant, where mechanized and semi-mechanized solutions are gaining traction, which application verticals generate recurring demand cycles, and how regional market characteristics influence pricing architecture, contract structures, and service availability. This layered approach enables decision-makers to identify where value is created, where cost pressures accumulate, and which service configurations are best aligned with their operational footprint.
In addition to structural market analysis, the report delivers demand forecasting that integrates historical consumption patterns, projected industrial activity levels, and the anticipated impact of regulatory evolution. The forecasting methodology accounts for the cyclical nature of tank cleaning demand in energy and chemicals, the steady maintenance-driven requirements in water and wastewater operations, and the emerging growth signals from specialized industrial applications. By connecting demand forecasts to service capacity and compliance readiness, the study gives clients a practical tool for scenario planning, investment prioritization, and risk-adjusted resource allocation.
Competitive Positioning, M&A Activity, and the Shifting Value Chain
The competitive environment is characterized by a consolidated tier of established service providers operating alongside specialized regional players and technology-focused entrants. Industry concentration metrics indicate that the top three participants together command 46.8 percent of revenue, while the top five account for 58.2 percent, signaling a market where scale, geographic coverage, and specialized compliance capabilities confer meaningful competitive advantage. Yet concentration alone does not define competitive outcomes. Differentiation increasingly depends on service integration, turnaround execution reliability, safety performance, and the ability to manage complex contaminant profiles under stringent environmental and occupational health standards.
The company profiles included in the study examine a cross-section of active participants with distinct strategic postures. Firms with strong North American operational bases are evaluated for their field service capabilities, permitting and safety frameworks, and positioning across industrial verticals. Providers headquartered in Europe and the Middle East are assessed for their environmental service integration, waste handling networks, and capacity to serve multinational operator requirements. Participants with growing presence in Asia Pacific and broader emerging industrial corridors are analyzed for their scaling strategies, technology adoption paths, and ability to meet localized compliance expectations while competing on cost and responsiveness. Rather than offering static organizational summaries, the report links each company’s operational footprint to the segments where demand is most durable and the competitive pressures most acute.
A defining feature of the current market cycle is the acceleration of consolidation and capability expansion through merger activity and targeted service launches. Recent corporate developments illustrate how strategic players are reshaping their addressable market and strengthening their hazardous waste and treatment infrastructure. In mid-2025, a significant service modernization move expanded robotic crude oil tank cleaning capabilities, incorporating advanced robotic systems, online desludging technologies, and enhanced oil sludge recovery solutions. This type of capability investment signals a broader industry shift toward reducing manual entry exposure, improving turnaround efficiency, and capturing higher-value recovery streams from residual hydrocarbons.
On the consolidation front, a major European environmental services enterprise moved aggressively to expand its North American hazardous waste footprint through a multi-stage acquisition of a U.S. industrial waste specialist. After a definitive agreement was announced in late 2025, the transaction was completed in mid-2026 with a value of approximately 3 billion USD, nearly doubling the acquirer’s U.S. hazardous waste capacity and strengthening its capabilities across treatment, storage, disposal, and advanced contaminant management, including PFAS-related solutions. This transaction is strategically significant because it links tank cleaning and related industrial decontamination services to a broader integrated waste and treatment ecosystem. For competitors, it raises the bar on service integration, compliance breadth, and the ability to serve operators who increasingly prefer consolidated environmental management partners over fragmented service providers.
Regulatory Pressures, Safety Dynamics, and Operational Risk Architecture
Market growth cannot be evaluated in isolation from the regulatory and safety environment that governs tank cleaning operations. Occupational safety requirements and confined space entry protocols have become central determinants of cost structure, scheduling reliability, and reputational exposure. Supervisory responsibilities for safe work procedures, permit administration, personal protective equipment deployment, and exposure monitoring for hydrocarbon vapors, gases, and oxygen concentrations form the baseline for compliant operations. Where these controls are inconsistently applied, the consequences extend beyond immediate safety incidents to include enforcement actions, financial penalties, project delays, and contract-driven reputational damage.
Recent enforcement activity underscores the financial and operational stakes involved. In mid-2024, a major regulatory citation was issued following serious procedural failures during tank cleaning operations, including the absence of atmospheric testing inside a tank prior to entry. The resulting proposed penalty exceeded 800,000 USD and reflected repeated and serious violations under occupational safety regulations. This case is instructive for strategic planners because it highlights two reinforcing realities: first, compliance discipline is a direct line item in operational cost and risk exposure; second, safety failures can disrupt service schedules, impair client confidence, and create liability exposure that ripples across multi-year contracts and multi-site operations.
From a strategic perspective, these dynamics elevate the importance of integrated risk management within service delivery. Providers that invest in atmospheric monitoring protocols, standardized permit workflows, trained entry supervision, and systematic hazard evaluation are better positioned to protect margin integrity, reduce unplanned downtime, and differentiate themselves in competitive procurement processes. For operators procuring tank cleaning services, procurement strategy increasingly involves evaluating vendor safety records, regulatory readiness, and incident management architecture as core qualification criteria. The research captures these compliance and safety dimensions not as peripheral considerations but as structural inputs into demand behavior, pricing resilience, and competitive selection logic.
Labor Economics, Automation, and the Cost of Service Delivery
Labor cost dynamics continue to shape service economics and capacity planning. As skilled labor becomes more constrained and wage expectations rise, the viability of high-touch manual cleaning models depends on the efficient deployment of personnel, the predictability of turnaround windows, and the ability to minimize rework and re-entry cycles. At the same time, organizations are reassessing the balance between labor-intensive execution and mechanized assistance where site conditions, tank geometry, and contaminant profiles make automation feasible. This does not imply a wholesale substitution of manual services; rather, it points to a more nuanced deployment logic in which service type selection is driven by tank configuration, hazard classification, residue characteristics, turnaround urgency, and total delivered cost.
The shift toward more advanced cleaning approaches is reinforced by the desire to reduce human exposure in hazardous atmospheres, shorten non-productive time, and improve recovery efficiency from hydrocarbon sludge and other residual streams. Providers investing in robotic systems, specialized desludging equipment, and enhanced recovery workflows are building operational advantages in environments where safety requirements are stringent and turnaround schedules are compressed. Simultaneously, firms with strong field crews and mature procedural discipline continue to compete effectively in applications where flexibility, adaptability, and rapid mobilization remain decisive. The report evaluates these competing delivery models within a shared analytical framework so that clients can determine where automation investment yields durable returns and where traditional service execution remains economically rational.
Application Drivers and Vertical-Specific Demand Patterns
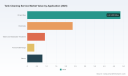
Tank cleaning demand is distributed across multiple industrial verticals, each with distinct operational rhythms, contaminant profiles, compliance expectations, and service cadence. The energy sector, particularly oil and gas, continues to anchor a substantial share of demand due to the scale of storage infrastructure, the complexity of hydrocarbon residues, and the need for scheduled maintenance, turnaround support, and sludge management. Chemical processing represents another core demand center, where cross-contamination prevention, vessel preparation, and hazardous residue handling require specialized procedures and rigorous verification. Water and wastewater treatment operations generate recurring cleaning requirements tied to infrastructure maintenance and process integrity, while food and beverage applications, though smaller in absolute scale, introduce stringent hygiene and material compliance considerations that affect service design and documentation.
The study maps these application dynamics to service demand intensity, contract frequency, and regional deployment patterns, allowing clients to identify where their service offerings align most naturally with underlying industrial activity. For companies seeking to diversify exposure or expand into adjacent verticals, the vertical-level analysis clarifies which applications demand higher procedural specialization, which generate more consistent recurring revenue, and which are more sensitive to production cycles, regulatory cycles, and capital expenditure timing. By connecting application behavior to service economics, the report supports targeted commercial strategy rather than broad-based market participation.
Geographic Deployment, Regional Nuances, and Strategic Allocation
Regional market behavior reflects differences in industrial density, regulatory maturity, operator preferences, and the existing base of service capacity. North American and European markets are shaped by well-established compliance frameworks, mature procurement practices, and a strong emphasis on safety performance and integrated environmental handling. Asia Pacific reflects a broader and faster-evolving industrial base, with growing infrastructure investment, expanding refining and chemical activity, and increasing adoption of specialized cleaning and waste handling services. Latin American and Middle East-Africa markets present distinct deployment considerations linked to project-driven demand, energy infrastructure activity, and the pace of regulatory formalization.
The research does not treat regional analysis as a static share table. Instead, it examines the operational implications of regional demand: how service models must adapt to local permitting environments, how mobilization and logistics influence cost competitiveness, and how multinational operators evaluate vendor consistency across jurisdictions. For enterprises planning capacity expansion, partnership development, or cross-border service standardization, this regional lens is essential for aligning investment decisions with realistic demand intensity and competitive conditions. The full segmentation detail is developed within the report to support granular strategic choices without oversimplifying regional complexity.
Tank Cleaning Service Market
Why This Research Matters for 2026 Strategic Decisions
The 2026 planning horizon places enterprise decision-makers at the intersection of market expansion, regulatory tightening, safety accountability, and competitive consolidation. In this environment, strategy teams need more than directional market narratives. They require a structured evidence base that connects market size evolution, demand drivers, service type economics, vertical-specific behavior, regional deployment logic, competitor positioning, and recent corporate developments into a coherent planning framework. The report is designed to serve that function. It provides the analytical scaffolding to support decisions about service line investment, geographic prioritization, procurement qualification standards, partnership and acquisition screening, and operational risk investment.
Equally important, the study is built to support scenario thinking. Because market growth trajectories, regulatory enforcement intensity, labor cost conditions, and consolidation activity can evolve in multiple directions, decision-makers benefit from an analysis that identifies which variables most influence outcome sensitivity and where strategic flexibility should be preserved. Whether the objective is to defend an existing service position, enter a new regional or vertical market, evaluate a vendor base, or assess the implications of competitor consolidation, the research is structured to translate market intelligence into executable strategic direction.
Positioning Your Organization Ahead of the Next Market Cycle
The tank cleaning services market is expanding within a framework of rising operational expectations. Growth is real, but so are the compliance, safety, labor, and competitive pressures that shape who captures value and how. Enterprises that ground their 2026 decisions in a rigorous understanding of demand drivers, service economics, regulatory exposure, and competitive structure will be better positioned to allocate capital efficiently, negotiate from an informed stance, and build service models that are resilient under changing conditions. For organizations seeking a comprehensive and decision-focused view of the industry, the complete research provides the segmentation depth, competitor context, regulatory analysis, and forward-looking intelligence necessary to move from market awareness to strategic action.
For detailed analysis of this topic, please visit the official page: Tank Cleaning Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Disposable Tableware Market to Hit $221M by 2032, Growing at 4.02% CAGR from 2026-2032
By pmarketresearch, 2026-09-15
Navigating the Disposable Tableware Market: Strategic Intelligence for 2026 and Beyond
Executive Overview
The global disposable tableware market stands at a critical inflection point as we move through 2026. What was once a commodity-driven sector defined by volume and price competition has evolved into a complex landscape shaped by regulatory mandates, material innovation, and shifting consumer expectations. For executives, procurement leaders, and investors, the ability to distinguish between transient trends and structural shifts is no longer optional. It is a prerequisite for capital allocation, product portfolio strategy, and regional expansion planning.
This article serves as a strategic preview of PW Consulting's latest Disposable Tableware Market research. Rather than offering surface-level summaries, our analysis is designed to equip decision-makers with actionable intelligence that bridges historical performance with forward-looking scenario planning. The following sections outline the market's structural trajectory, the competitive architecture defining the sector, and the regulatory forces actively reshaping demand patterns. Readers seeking granular segmentation data, detailed company profiles, and quantified forecast models are encouraged to access the full report for complete market intelligence.
Market Trajectory and Growth Dynamics
The disposable tableware market has demonstrated consistent expansion over the past half-decade, reflecting resilient demand across foodservice, institutional, and residential channels. Historical data from 2020 through 2025 reveals a market that navigated supply chain disruptions, inflationary pressures, and evolving procurement behaviors while maintaining an upward trajectory. By the close of 2025, the global market had reached a revenue base of approximately 168.0 million USD, building on a foundation of 100.0 million USD recorded in 2020.
Looking ahead, our forecast period spanning 2026 through 2032 projects measured but steady growth. The market is expected to open 2026 at approximately 171.6 million USD and continue its ascent toward 221.02 million USD by 2032. This trajectory corresponds to a compound annual growth rate of 4.02 percent, a figure that underscores a market characterized by incremental expansion rather than explosive volatility. Such a growth profile rewards strategic patience, operational efficiency, and the ability to capture share through differentiation rather than scale alone.
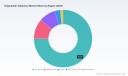
It is important to recognize that aggregate figures tell only part of the story. The distribution of value across material categories, application channels, and geographic territories reveals a far more nuanced picture. Certain material segments are experiencing accelerated adoption driven by regulatory tailwinds and consumer preference shifts, while regional markets exhibit markedly different maturity profiles and growth catalysts. Our full report dissects these dynamics with precision, providing the granular breakdowns necessary for targeted strategy formulation.
The Competitive Architecture
The competitive landscape of the disposable tableware market is defined by a diverse set of players, each navigating the tension between cost efficiency, material innovation, and sustainability mandates. Market concentration metrics indicate a relatively fragmented environment, with the top three firms accounting for approximately 22.0 percent of total market share and the top five firms commanding roughly 28.5 percent. This dispersion suggests that while established incumbents hold meaningful positions, there remains ample room for differentiation, niche positioning, and regional leadership.
Several companies exemplify the strategic postures currently shaping the sector. Pactiv Evergreen Inc., headquartered in Lake Forest, Illinois, maintains a focused offering across paper and plastic disposable tableware tailored for both foodservice operators and consumer channels. Their portfolio reflects a balance between traditional performance expectations and the operational requirements of high-volume service environments.
Huhtamaki Oyj, based in Helsinki, Finland, has built its reputation on branded paper and molded fiber tableware solutions, including the well-known Chinet brand for foodservice and institutional applications. Their emphasis on molded fiber technology positions them at the intersection of performance and sustainability, an increasingly critical alignment as end-users seek alternatives to conventional materials.
Dart Container Corporation, operating from Mason, Michigan, has long been associated with foam and plastic disposable tableware. However, their strategic trajectory includes a notable transition toward compostable lines, exemplified by initiatives such as Bare by Solo. This shift illustrates a broader industry pattern: incumbent players leveraging existing distribution networks and customer relationships while incrementally pivoting toward environmentally aligned product architectures.
Genpak LLC, located in Charlotte, North Carolina, continues to serve the foodservice sector with expanded polystyrene and paper-based disposable tableware. Their dual-material approach allows them to address varied performance and cost requirements across different service formats. Meanwhile, Reynolds Consumer Products Inc., headquartered in Atlanta, Georgia, integrates disposable tableware within a broader consumer products portfolio, leveraging brand recognition and retail distribution to maintain relevance in household and casual dining segments.
Novolex Holdings LLC, based in Virginia Beach, Virginia, provides plastic and paper disposable tableware solutions across foodservice and retail channels. Their diversified material strategy enables them to respond flexibly to regional demand variations and procurement specifications. Berry Global Inc., from Evansville, Indiana, contributes molded fiber and plastic single-service tableware to the market, reflecting the ongoing relevance of both traditional and alternative material pathways.
On the sustainability-oriented side of the competitive spectrum, Green Paper Products LLC in Highland Heights, Ohio, focuses on biodegradable and compostable paper-based disposable tableware. Eco-Products Inc., operating from Boulder, Colorado, extends this focus further by developing biodegradable options derived from bagasse, bamboo, and plant-based materials. World Centric, based in Rohnert Park, California, similarly emphasizes sustainable, plant-based, and compostable disposable tableware, aligning product development with evolving environmental expectations.
Sabert Corporation, located in Sayreville, New Jersey, rounds out this competitive overview with plastic and paper disposable tableware tailored for commercial and institutional use. Their positioning highlights the enduring importance of bulk procurement, consistency, and compliance with institutional specifications.
The presence of both traditional material specialists and sustainability-focused entrants creates a dynamic competitive environment. Incumbents are not merely defending share; they are actively reshaping portfolios, acquiring capabilities, and responding to regulatory and consumer pressure. Our full report provides detailed competitive profiling, strategic assessment, and positioning analysis for each key player, enabling clients to benchmark their own strategies against the market's most relevant participants.
Ceramic Tableware Market
Regulatory and Environmental Currents Reshaping Demand
No discussion of the disposable tableware market in 2026 would be complete without addressing the regulatory and environmental forces that are actively redirecting demand. These forces are not peripheral concerns; they are central drivers of product development, procurement criteria, and regional market dynamics.
In January 2025, California's statewide ban on expanded polystyrene foodware took effect under SB 54, a landmark regulation that has redirected demand toward paper, molded-fiber, and recyclable alternatives. The implications of this policy extend far beyond California's borders. As one of the largest consumer markets in the United States, California's regulatory posture often influences procurement standards, supplier capabilities, and product development priorities across the broader North American landscape. Companies that fail to adapt their offerings to accommodate EPS restrictions risk losing access to significant volume channels.
Similarly, in December 2025, Canada activated Single-use Plastics Prohibition Regulations affecting the manufacture, import, and sale of prohibited foodservice ware. This regulatory milestone introduces new compliance requirements and demand shifts across the Canadian market, with ripple effects for North American supply chains and cross-border procurement strategies. Organizations operating in or serving the Canadian market must account for these restrictions in their product planning and sourcing decisions.
On the innovation front, November 2024 saw the introduction of a new paper plate invention that has been characterized as a breakthrough in the disposable plate industry. While specific technical details warrant deeper examination, the emergence of such innovations signals an ongoing commitment to material advancement within the sector. Breakthroughs of this nature can alter cost structures, performance expectations, and sustainability profiles, creating new opportunities for differentiation and market entry.
Regulatory developments are further complemented by evolving standards around material composition. The FDA maintains an inventory of Post-Consumer Recycled plastics No Objection Letters, allowing disposable tableware and cutlery with up to 100 percent recycled content in contact with all food types under specific conditions of use. This regulatory framework opens pathways for increased recycled content integration, supporting circular economy objectives while providing manufacturers with flexibility in material sourcing and product design.
These regulatory and innovation dynamics are not isolated events. They are part of a broader pattern in which environmental considerations, policy mandates, and technological advancement converge to reshape what is possible, permissible, and commercially viable in the disposable tableware sector. Our report examines these forces in detail, mapping their implications for market segments, competitive positioning, and strategic planning horizons.
What the Full Report Delivers
The Disposable Tableware Market research published by PW Consulting is structured to provide executive-level clarity without sacrificing analytical depth. The report is designed for professionals who require more than high-level trends; it delivers the structured intelligence necessary to support investment decisions, product strategy, market entry evaluation, and competitive benchmarking.
Key components of the report include:
- Comprehensive market sizing and forecast modeling covering the historical period from 2020 through 2025 and the forecast horizon extending to 2032, with revenue projections expressed in million USD and annualized growth rates contextualized within broader economic and industry conditions.
- Detailed segmentation analysis across material categories, application channels, and geographic regions, enabling clients to identify high-priority segments, assess growth differentials, and align resource allocation with market opportunity.
- In-depth competitive profiling of key market participants, including strategic positioning, product portfolio characteristics, and relevant corporate developments that inform competitive dynamics.
- Regulatory and environmental analysis mapping the impact of policy mandates, material standards, and innovation trends on demand patterns, compliance requirements, and strategic options.
- Market concentration and share distribution metrics that provide context for competitive intensity, barriers to entry, and the potential for consolidation or niche expansion.
- Forward-looking scenario considerations that help executives anticipate inflection points, evaluate risk exposures, and prepare adaptive strategies for varying market conditions.
The report is intended for a broad range of stakeholders, including corporate strategy teams, product development leaders, procurement and supply chain executives, investors evaluating sector exposure, and consultants supporting client engagements in the foodservice packaging and disposable goods space. By consolidating market data, competitive intelligence, and regulatory context into a single analytical framework, the report reduces the time and effort required to develop informed, defensible strategies.
Strategic Implications for 2026 Decision-Makers
As organizations navigate the disposable tableware market in 2026, several strategic imperatives emerge from the market's structure and trajectory. First, the 4.02 percent compound annual growth rate projected through 2032 suggests a market that rewards precision over speculation. Growth is present, but it is distributed unevenly across segments and regions. Capturing value requires targeted focus rather than broad-based assumptions.
Second, the regulatory environment is no longer a background condition; it is an active determinant of product viability and market access. The California EPS ban, Canada's single-use plastics regulations, and evolving FDA guidance on recycled content all impose compliance requirements while simultaneously creating opportunities for companies that proactively align their portfolios with emerging standards. Strategic planning must incorporate regulatory timelines and regional variation as core inputs rather than afterthoughts.
Third, the competitive landscape's moderate fragmentation offers both challenges and opportunities. With no single firm dominating the market, there is room for differentiated positioning based on material expertise, sustainability credentials, regional presence, or application-specific performance. Companies that invest in clear value propositions and credible alignment with end-user priorities are better positioned to command preference in a market where price alone is increasingly insufficient as a differentiator.
Fourth, material innovation and sustainability expectations are converging to reshape procurement criteria. The emergence of new paper-based technologies, the expansion of compostable and plant-based alternatives, and the regulatory encouragement of recycled content all point toward a future in which material choice carries strategic weight. Organizations that monitor these developments closely and integrate them into product planning will be better equipped to respond to shifting demand patterns.
Disposable Tableware Market
Finally, the geographic distribution of market value underscores the importance of regional strategy. Markets do not grow uniformly, and regulatory, cultural, and economic factors create distinct opportunity profiles across territories. A nuanced understanding of regional dynamics enables more effective resource allocation, partnership selection, and market entry or expansion timing.
Accessing Complete Market Intelligence
This article has provided a strategic overview of the disposable tableware market's structure, trajectory, competitive dynamics, and regulatory context as of 2026. However, the full depth of analysis required for confident decision-making extends beyond what can be captured in a summary format. Detailed segmentation data, quantified regional and material breakdowns, comprehensive company profiles, and scenario-based forecasting models are essential components of a complete strategic assessment.
PW Consulting's full Disposable Tableware Market report delivers this comprehensive intelligence, organized for immediate applicability by executive teams, strategy professionals, and investment analysts. The report is designed to serve as a reference point for strategic planning, competitive evaluation, and market opportunity assessment throughout the 2026 to 2032 forecast period.
For organizations seeking to ground their 2026 decisions in rigorous, up-to-date market intelligence, the complete report provides the data, analysis, and contextual insight necessary to move from understanding to action. We invite you to access the full publication to obtain the detailed segmentation figures, competitive assessments, and forward-looking models that will support your strategic objectives in the disposable tableware market.
For detailed analysis of this topic, please visit the official page: Disposable Tableware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gas Compressors Market Hits $6.1B in 2025, Projected to Reach $8.23B by 2032 at 4.4% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Global Gas Compressors Market: A 2026 Decision-Maker's Guide
The global industrial landscape is undergoing a profound transformation, driven by the dual engines of energy security and the urgent transition toward lower-carbon operations. At the heart of this complex engineering ecosystem lies the gas compressor, a critical asset class that enables everything from natural gas transmission and liquefied natural gas (LNG) processing to petrochemical manufacturing and emerging carbon capture initiatives. As we move further into the 2026 fiscal cycle, understanding the trajectory of this market is no longer just an engineering concern; it is a boardroom imperative. The decisions made today regarding procurement, capacity expansion, and compliance strategy will define operational resilience and profitability for the next decade.
PW Consulting's latest comprehensive market research on the Gas Compressors Market offers a rigorous, data-rich foundation for navigating this volatility. This article serves as a strategic overview of the key dynamics shaping the sector, highlighting the urgent need for granular intelligence in an environment characterized by tightening regulations, shifting supply chain economics, and intense competitive maneuvering. The findings underscore why a deep dive into our full report is essential for stakeholders aiming to secure a competitive edge from 2026 through 2032.
Defining the Market Trajectory: From Recovery to Structural Growth
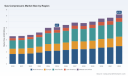
The gas compressors market has demonstrated remarkable resilience and steady expansion over the recent past. Following a period of consolidation and demand recovery, the sector has settled into a robust growth phase characterized by consistent valuation increases across the global footprint. Drawing from historical data spanning the early 2020s, the market has evolved from a baseline of moderate valuation into a sophisticated multi-billion-dollar ecosystem. The upward momentum evident in the mid-2020s reflects not merely a rebound from prior disruptions but a structural expansion fueled by sustained investment in energy infrastructure, industrial capacity, and environmental compliance technologies.
Our analysis projects that this trajectory will maintain a steady compound annual growth rate throughout the forecast period. This growth is underpinned by a confluence of macroeconomic and sector-specific drivers. Continued reliance on natural gas as a transition fuel, coupled with aggressive capacity expansions in Asia and the Middle East, ensures a steady baseline of demand for core compression equipment. Simultaneously, the accelerating deployment of industrial gas systems and power generation assets provides diverse revenue streams that buffer the market against single-sector downturns. However, realizing this projected valuation requires more than passive market participation; it demands an acute awareness of the regulatory and economic variables that are rapidly reshaping the cost of doing business.
Stakeholders reviewing the high-level market size figures will recognize a clear path toward value expansion, but the devil is in the details. The sheer magnitude of the projected market by the end of the decade masks significant variations in regional maturity, technology adoption rates, and application-specific bottlenecks. Our full research deconstructs these aggregate numbers, offering a granular view that separates speculative hype from actionable investment signals. Without this granular dissection, executives risk misallocating capital or underestimating the lifecycle costs of their compression assets.
Navigating the Regulatory and Dynamic Shifts
No discussion of the 2026 compressor landscape is complete without addressing the seismic shifts in environmental regulation. The era of voluntary emissions stewardship is giving way to mandated, enforceable limits that carry substantial financial penalties. A prime example of this new reality is the regulatory evolution occurring in North America, where states such as Colorado have adopted revisions to Regulation Number 7, aligning with federal emission standards. These updates introduce specific methane emissions limits applicable to centrifugal compressors—both wet and dry seal variants—as well as reciprocating compressors used in oil and gas operations. Effective for the 2027 operational cycle, these regulations require facilities to maintain emissions below specified volumetric flow rate limits, fundamentally altering the engineering specifications and selection criteria for new installations and retrofits.
Furthermore, the financial stakes of non-compliance have been escalated by federal-level policy. The introduction of a Waste Emissions Charge, applied to methane emissions from natural gas compressor stations at a rate of $1,500 per ton starting in 2026, transforms environmental compliance from a technical challenge into a direct line-item cost consideration. For operators managing large fleets of compression assets, the margin for error has vanished. This charge incentivizes the rapid adoption of high-efficiency sealing technologies, leak detection systems, and potentially the accelerated replacement of aging equipment that cannot be economically retrofitted. Our report provides a detailed analysis of how these regulatory layers interact with operational budgets, helping clients model the total cost of ownership under the new compliance regime.
Beyond regulation, the supply-side economics are also presenting headwinds that require strategic foresight. The Producer Price Index for Air and Gas Compressor Manufacturing has reached elevated levels, signaling persistent cost pressures in raw materials and component manufacturing. These cost dynamics are compounded by the labor-intensive nature of large-scale compressor deployment. For instance, large reciprocating gas compressors utilized in pipeline applications require significant skilled labor for installation and periodic overhauls. Industry analysis indicates that these labor requirements can contribute 5 to 10% of the initial capital cost in annual maintenance expenses. In an environment of skilled labor shortages, this maintenance burden becomes a critical risk factor. Our study evaluates how manufacturers and operators are responding, from localizing service networks to investing in modular skid designs that reduce field installation complexity.
Competitive Landscape and Strategic Positioning
The global gas compressors market is characterized by a moderately concentrated competitive structure, where a handful of key players wield significant influence over technology standards and market share. Our analysis reveals that the top three companies command a substantial portion of the market revenue, while the top five extend their collective grip even further. This concentration highlights the importance of strategic partnerships, licensing agreements, and technological differentiation for both incumbents and new entrants. The competitive arena is divided across multiple vectors, including the type of compressor technology, the application vertical, and geographic reach.
In the natural gas and energy sectors, several formidable players have cemented their positions through specialized engineering capabilities. Ariel Corporation, based in Mount Vernon, Ohio, maintains a strong focus on high-speed reciprocating gas compressors tailored for natural gas pipelines, LNG, and oil & gas applications. Their expertise underscores the continued relevance of reciprocating technology in high-pressure transmission scenarios. Similarly, Ingersoll Rand, headquartered in Davidson, North Carolina, offers a broad portfolio of centrifugal and reciprocating gas compressors, serving the natural gas and energy sectors with a reputation for reliability and integration. Arrow Engine & Compression, operating out of Tulsa, Oklahoma, further reinforces the North American strength in reciprocating compressors for natural gas transmission and processing, catering to the specific needs of midstream operators. Archrock, also based in Houston, distinguishes itself by focusing on gas compression services, rentals, and equipment, offering a flexible asset-light model that appeals to operators seeking scalable compression capacity without heavy capital expenditure.
On the large-scale gas processing and LNG front, the competition intensifies with global energy conglomerates. Siemens Energy, with its Berlin headquarters, brings immense engineering weight to large-scale centrifugal compressors designed for gas processing, pipelines, and LNG facilities. Their integration capabilities allow for comprehensive solution delivery that spans the entire value chain. Everllence, based in Munich, is carving a distinct niche by focusing on axial and centrifugal compressors for challenging environments, including LNG, Floating Production Storage and Offloading (FPSO) vessels, and carbon capture & storage projects. Their strategic agility was highlighted by a major contract awarded in March 2026 for two radial barrel compressor skids to support Thailand's first carbon capture and storage project at the Arthit gas field. This project, which enables the capture and storage of 1 million tons of CO2 per year, exemplifies the growing intersection of traditional compression technology and decarbonization infrastructure. GE (Baker Hughes Energy Innovations), headquartered in Houston, remains a dominant force with centrifugal compressors for oil & gas, pipelines, and LNG facilities, leveraging decades of experience in turbomachinery.
The industrial and process segments are also contested by specialized manufacturers. Burckhardt Compression, from Winterthur, Switzerland, offers both centrifugal and reciprocating compressors targeting oil & gas, chemical, LNG, and hydrogen mobility segments, positioning itself at the forefront of the hydrogen economy pivot. Atlas Copco, based in Stockholm, focuses on energy-efficient gas compressors for industrial and process applications, appealing to clients prioritizing operational efficiency and sustainability. Chart Industries, located in Ball Ground, Georgia, provides specialized compressors and related systems for LNG and gas processing, while Bauer Compressors, also from Munich, targets CNG and process gas compressors for industrial and vehicle applications, addressing the growing demand for compressed natural gas infrastructure. Caterpillar Inc., headquartered in Irving, Texas, complements the landscape with gas compression systems and engines for power generation and industrial use, offering integrated power and compression solutions.
The interplay between these companies is dynamic. Recent developments, such as the aforementioned Everllence order for CCS, signal how technology providers are aligning their product roadmaps with government-backed decarbonization initiatives. Meanwhile, manufacturers must also contend with the regulatory pressures mentioned earlier, forcing them to innovate in seal technology and emissions monitoring. Our full report provides a deep-dive competitor benchmarking analysis, evaluating each entity's product portfolio strength, geographic coverage, and strategic response to regulatory shifts. We reveal which players are best positioned to capture value in specific sub-segments, without diluting the proprietary granularity that makes our intelligence actionable.
Operating, Application, and Regional Nuances
While aggregate growth numbers provide the macro view, the true strategic value lies in understanding the segmentation drivers that dictate demand patterns. The market is segmented by compressor type, application, and region, each with distinct growth profiles and competitive pressures. In terms of technology, the split between centrifugal, reciprocating, screw, and axial compressors reflects a trade-off between capacity, pressure requirements, efficiency, and cost. Centrifugal compressors dominate in large-scale continuous flow applications such as pipelines and LNG, where reliability and throughput are paramount. Reciprocating compressors remain essential for high-pressure, low-volume applications, often found in wellheads and specific processing stages. Screw and axial compressors serve niche but critical roles in industrial gases and specialized processing, respectively. The choice of technology is increasingly influenced not just by technical specs but by emissions compliance capabilities; for instance, the distinction between wet and dry seal centrifugal compressors now carries direct regulatory and cost implications due to methane leak constraints.
Gas Compressors Market
Application-wise, the oil & gas production segment continues to be the dominant anchor of the market, driven by ongoing extraction activities and midstream infrastructure needs. However, petrochemical plants, power generation, and industrial gases segments offer diverse growth vectors. Power generation demand is tied to the resilience of the grid and the role of gas-fired plants in balancing renewable intermittency. Industrial gases demand is expanding with the growth of manufacturing and the emergence of hydrogen and syngas applications. Our report dissects the revenue contribution and growth trajectories of these application areas, helping clients identify which verticals offer the most attractive risk-adjusted returns.
Regionally, the market exhibits a complex tapestry of maturity and emerging opportunity. North America maintains a significant share of the global market, supported by a mature shale gas ecosystem and aggressive midstream expansion. Europe represents a regulated, efficiency-driven market with strong ties to hydrogen and CCS initiatives. Asia Pacific is a region of high growth potential, fueled by industrialization, energy demand, and infrastructure development in key economies. Latin America and the Middle East & Africa contribute meaningful volumes, often linked to specific hydrocarbon projects and industrialization efforts. However, analyzing regional share without the context of local regulatory frameworks, supply chain maturity, and competitive intensity can lead to flawed market entry strategies. Our research provides the necessary regional intelligence, mapping out the specific drivers, barriers, and key local players that define each geography, enabling clients to prioritize their market engagement with precision.
Air Compressors Market
Why This Report is Indispensable for 2026 Decision-Making
In a market environment defined by regulatory tightening, cost volatility, and technological evolution, generic industry summaries are insufficient for strategic planning. The PW Consulting Gas Compressors Market research report is designed to bridge the gap between high-level awareness and operational execution. It goes beyond stating that the market is growing; it quantifies the impact of the $1,500 per ton Waste Emissions Charge on fleet economics. It illuminates how the Pumping Price Index fluctuations affect procurement timing and contract negotiations. It reveals how the labor cost burden for large reciprocating compressors influences the total cost of ownership versus electrification or modular alternatives.
The report serves as a comprehensive toolkit for a wide range of stakeholders. For manufacturers and technology providers, it offers a clear view of competitive positioning, white spaces for product development, and the regulatory features that customers will demand in the coming years. For operators and EPC contractors, it provides the data needed to optimize asset selection, plan maintenance budgets, and mitigate compliance risks. For investors and financial analysts, it delivers the granular segmentation and forecasting data required to validate investment theses and assess market concentration risks. The inclusion of detailed profiles on key companies, coupled with recent developments tracking, ensures that decision-makers are aware of the latest strategic moves and order flows that signal market direction.
Moreover, the forecast period extending to 2032 allows for long-term capacity planning. The projected growth trajectory suggests sustained demand, but the path is not linear. Variables such as the pace of the energy transition, the adoption of new emissions technologies, and geopolitical shifts in energy trade will create inflection points. Our report models these scenarios, providing sensitivity analyses that help clients stress-test their strategies against multiple futures. By understanding the interplay between the dominant oil & gas application and the emerging CCS and hydrogen segments, stakeholders can build portfolios that are resilient to sector-specific shocks.
Conclusion: Access the Full Intelligence
The gas compressors market in 2026 presents a paradox of stability and disruption. The macro fundamentals point to steady growth and expanding value, yet the micro-level dynamics of regulation, cost, and technology are rewriting the rules of engagement. The Waste Emissions Charge, the Colorado Regulation Number 7 updates, and the elevated manufacturing costs are not transient issues; they are structural changes that will define the competitive landscape for years. Similarly, the strategic moves by companies like Everllence into carbon capture compression signal a market that is adapting to broader environmental goals, creating new revenue streams while challenging legacy product lines.
To navigate this complexity, organizations need more than anecdotal evidence or top-line market size figures. They need a detailed, data-backed roadmap that exposes the hidden drivers of value and risk. PW Consulting's full market research report delivers this intelligence. It unpacks the segmentation splits by type, application, and region, revealing the specific sub-markets that offer the highest growth potential and the most favorable competitive conditions. It provides a rigorous analysis of the market concentration and the strategic postures of the leading players, from Ariel and Ingersoll Rand to Siemens Energy and Everllence.
Do not leave your 2026 strategy to chance. Equip your team with the precise, actionable insights required to optimize investments, ensure compliance, and capture market share in a rapidly evolving industry. Visit the source webpage to access the complete Gas Compressors Market report, download the detailed segmentation tables, and leverage the full depth of our analyst expertise. The future of gas compression is being written now; ensure you have the intelligence to lead rather than follow.
For detailed analysis of this topic, please visit the official page: Gas Compressors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 2025 Global Commercial Vehicle Market Hits $1.29 Trillion, CAGR 6.5% to 2032
By pmarketresearch, 2026-09-15
Charting the Commercial Vehicle Market Trajectory: Strategic Intelligence for 2026 Decision-Makers
The global commercial vehicle industry stands at a critical inflection point. As organizations navigate shifting regulatory frameworks, accelerated electrification timelines, and evolving logistics demands, the ability to anticipate market movements has transitioned from a competitive advantage to an operational necessity. Our latest Commercial Vehicle Market research delivers a comprehensive, data-driven foundation for enterprise strategy through the end of the decade and beyond. This report is engineered to translate macroeconomic trends into actionable intelligence, enabling executives, supply chain leaders, and investment teams to position their portfolios with precision.
Drawing on a rigorous analytical methodology, the study captures market performance from 2020 through 2025 and projects forward across a six-year forecast horizon. The narrative that follows is not merely a collection of figures. It is a structural examination of how demand vectors, technology adoption curves, and competitive consolidation patterns are reshaping the commercial mobility landscape. Readers will find a clear pathway to strategic clarity, while the full dataset and granular scenario models remain accessible through our complete research portal.
Macro Market Trajectory and Growth Foundations
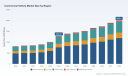
The commercial vehicle sector has demonstrated remarkable resilience and expansion over the past half-decade. Between 2020 and 2025, the market expanded from approximately 815.3 billion USD to 1292.42 billion USD, reflecting a compound annual growth rate that underscores sustained enterprise investment in fleet modernization, infrastructure development, and cross-border trade optimization. This upward trajectory has accelerated into the current baseline year, positioning the industry at a scale that demands disciplined forecasting and scenario-aware planning.
Looking ahead, the forecast window through 2032 projects continued expansion, with the market anticipated to surpass the 2 trillion USD threshold by the close of the period. The overall growth profile carries a projected CAGR of 6.5 percent, signaling a steady but structurally evolving demand environment. This rate of expansion is not uniform across all vectors. It reflects diverging adoption cycles, regional policy maturity, and varying capital expenditure pacing among fleet operators. Understanding where growth concentrates, and where it lags, requires moving beyond headline numbers into the segmentation architecture that drives real-world procurement decisions.
For executives evaluating capital allocation, capacity planning, or market entry strategies, these macro indicators serve as the starting point rather than the destination. The report delves into how baseline growth interacts with regional policy shifts, supply chain constraints, and technology transition costs, offering a layered view that supports both short-term tactical adjustments and long-horizon strategic positioning.
Structural Demand Breakdown: Vehicle Categories, Applications, and Regional Channels
Commercial vehicle demand is fundamentally segmented by platform type, operational application, and geographic distribution channels. Each dimension carries distinct procurement cycles, regulatory exposure, and technologically induced cost structures. The report maps these dimensions to reveal where purchasing power is concentrating and how end-user priorities are shifting.
The vehicle type landscape spans light commercial platforms, heavy-duty trucks, and bus segments, each serving different operational envelopes and total-cost-of-ownership profiles. Application-driven demand further fragments the market across logistics and transportation networks, construction and infrastructure projects, agriculture and mining operations, public transit systems, and specialized use cases. Meanwhile, regional market distribution reflects varying degrees of industrial activity, trade corridor intensity, and policy-driven fleet transformation mandates.
Rather than presenting isolated percentages, the research synthesizes these segmentation layers into a cohesive demand framework. Executives will see how application growth rates interact with vehicle category preferences, how regional procurement patterns diverge based on economic structure and regulatory timelines, and where cross-segment opportunities emerge for manufacturers, component suppliers, and service providers. The full segmentation matrices, volume projections, and channel-specific revenue flows are available within the complete dataset, enabling precise portfolio alignment without exposure to fragmented or outdated proxies.
Competitive Landscape and Strategic Positioning
The commercial vehicle ecosystem is defined by a concentrated yet highly competitive group of multinational manufacturers, each pursuing distinct technology roadmaps and regional expansion strategies. Market concentration metrics indicate that the top three players command approximately 22.4 percent of industry revenue, while the top five extend their combined share to roughly 29.7 percent. This distribution suggests a market where scale matters, yet differentiation through powertrain innovation, commercial service networks, and regional customization remains a decisive competitive lever.
Worldwide Commercial Vehicle Leaf Spring Market
Several industry leaders anchor the competitive landscape. Daimler Truck AG operates a comprehensive portfolio spanning light, medium, and heavy-duty trucks as well as city and intercity buses under multiple brand umbrellas, reinforcing its global reach across diverse commercial applications. PACCAR Inc. maintains a strong presence through premium heavy-duty platforms and light commercial offerings, with a focus on engineering-driven performance and dealer-centric service models. Volvo Group continues to advance its truck division across long-haul, vocational, and urban use cases, with expanding electric model lineups targeting emissions-sensitive procurement cycles.
Traton SE leverages a multi-brand structure encompassing established truck platforms and emerging electric solutions, while Hyundai Motor Company has scaled its medium and heavy-duty commercial divisions alongside electric variants designed for regional and urban deployment. In parallel, Tata Motors Limited anchors commercial vehicle supply across trucks, buses, and electric platforms tailored to high-volume emerging market demand. Iveco Group N.V. provides light, medium, and heavy commercial applications across truck and bus categories, and CNH Industrial N.V. extends its footprint through agricultural and vocational equipment lines that intersect with commercial mobility needs. BYD Auto Co., Ltd. has also become increasingly relevant through its commercial truck and bus offerings, particularly where electric and hybrid platforms align with urban fleet transitions.
The report assesses these players not merely by product breadth, but by strategic posture: electrification investment pacing, regional manufacturing footprints, after-sales service capacity, and responsiveness to regulatory timelines. Competitive benchmarking within the study highlights where scale advantages translate into pricing power, where technology differentiation creates premium positioning, and where consolidation or partnership activity may reshape market shares over the forecast period.
Commercial Vehicle Market
Regulatory Acceleration and Technology Transition Dynamics
Regulatory pressure has become one of the most defining forces shaping commercial vehicle procurement cycles. In the United States, the EPA 2027 heavy-duty vehicle emissions standards mandate an approximate 80 percent reduction in NOx emissions compared to current levels. This requirement pushes manufacturers and fleet buyers toward advanced after-treatment architectures and hybrid or electric powertrains, effectively compressing the timeline for compliance-related product transitions. These standards are not confined to one jurisdiction; they interact with broader international commitments and regional mandates that collectively raise the cost of inaction.
At the global level, the Global Memorandum of Understanding on Zero-Emission Medium- and Heavy-Duty Vehicles commits signatories to achieving 30 percent net-zero tailpipe emission sales by 2030. This target aligns with U.S. objectives calling for 30 percent zero-emission medium- and heavy-duty vehicle sales by 2030 and a full transition toward 100 percent by 2040. Such commitments create a policy scaffold that influences procurement planning, infrastructure investment, and total-cost-of-ownership modeling across multiple markets simultaneously.
In California, the Advanced Clean Trucks rule intensifies this trajectory by requiring a defined percentage of new commercial vehicle sales to be zero-emission, with non-compliant vehicles facing prohibition by 2035. Together, these regulatory developments form a cascading compliance environment where OEMs and fleet operators must anticipate product availability, charging or fueling infrastructure readiness, and operational range requirements well in advance of mandate deadlines.
The research evaluates these regulatory layers as strategic variables rather than background noise. It maps the cost and timing implications of emissions compliance, examines how electrification adoption curves interact with fleet renewal cycles, and identifies where policy momentum creates both risk exposure and first-mover opportunity for organizations that prepare early.
Operational Intelligence Embedded in the Report
Beyond macro forecasting and competitive profiling, the study is built to support operational decision-making. It integrates procurement-relevant analysis that helps procurement teams, engineering leaders, and commercial strategy teams align purchasing roadmaps with market realities. The report includes detailed assessment frameworks that evaluate demand sensitivity to fuel and energy pricing, the impact of emissions compliance on vehicle total cost of ownership, and the interplay between infrastructure readiness and fleet electrification timing.
Strategic scenario planning is another core component. Readers gain access to forward-looking models that connect regulatory milestones, technology availability, and regional demand shifts to potential market outcomes. These scenarios are designed to test resilience across multiple operating conditions, enabling organizations to stress-test supply commitments, aftermarket service planning, and regional expansion decisions. The study also covers aftermarket and service-network implications, recognizing that commercial vehicle value creation increasingly depends on uptime assurance, component lifecycle management, and digital fleet monitoring capabilities.
By combining quantitative forecasting with qualitative industry assessment, the report delivers a practical toolset for executive planning. It is structured to answer the questions that matter most to commercial vehicle stakeholders: where demand is likely to strengthen, which technology pathways are gaining procurement traction, how competitive dynamics may shift pricing and availability, and what strategic responses will preserve margin and market position through the end of the forecast horizon.
How This Research Supports 2026 Decision-Making
Entering 2026, commercial vehicle organizations face a decision environment defined by simultaneous disruption and opportunity. Regulatory deadlines are approaching faster than many fleet renewal cycles. Electrification technologies are advancing, but adoption remains uneven across applications and regions. Supply chain constraints, labor dynamics, and infrastructure readiness continue to influence procurement timing and cost structures. In this context, decisions made in the near term will determine competitiveness over the balance of the decade.
This research is designed to reduce uncertainty in that decision process. It provides a unified view of market size evolution, segmentation behavior, and competitive positioning, grounded in a transparent analytical structure. Executives can use the findings to prioritize investment across vehicle platforms, align regional strategies with demand maturity, and anticipate the strategic implications of zero-emission mandates before they become binding constraints. The report also supports investor and board-level discussions by clarifying growth drivers, concentration risks, and the strategic value of technology differentiation in a market where top players hold meaningful but not dominant share.
Importantly, the study is intended as an entry point to deeper intelligence. The narrative presented here highlights the analytical framework, strategic themes, and macroeconomic direction that shape the commercial vehicle sector. The complete research package extends this foundation with segmented projections, detailed company assessments, regional demand breakdowns, and scenario-based modeling that enable precise operational planning. Organizations seeking to convert market intelligence into execution-ready strategy can access the full dataset and supporting analysis through our comprehensive market research portal, where the complete Commercial Vehicle Market report awaits.
For leaders tasked with navigating the next phase of commercial mobility, the value of rigorous, forward-looking research is clear. The market will continue to expand, but the distribution of that growth will reward organizations that plan with precision, anticipate regulatory and technological shifts early, and ground their strategies in robust market evidence. This report provides that evidence base and the strategic lens needed to act on it.
For detailed analysis of this topic, please visit the official page: Commercial Vehicle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the Tylosin Market: Navigating Growth and Regulatory Shifts Through 2032
As the global livestock and companion animal sectors continue to evolve under the dual pressures of protein demand intensification and tightening pharmacological oversight, the strategic planning of market participants requires more than surface-level trend forecasting. Timely, granular, and decision-ready intelligence becomes the differentiator between reactive positioning and deliberate market leadership. This latest research release examines the Tylosin market across the 2026–2032 forecasting horizon, delivering a comprehensive analytical framework designed for executives, R&D directors, procurement strategists, and commercial leaders who must act with precision in a highly regulated, moderately concentrated, and structurally resilient segment.
The market has demonstrated steady expansion through the historical window of 2020–2025, with annual valuations climbing from 79.0 million USD to an estimated 104.0 million USD by the base year. Looking forward, the trajectory projects continued momentum, anchoring a forecast period CAGR of 5.6 percent across the 2026–2032 span. By the close of the forecast window, revenue scale is expected to extend meaningfully beyond the 150 million USD threshold. These top-line figures establish a backdrop of durable demand, but the strategic value of this study lies in its dissection of the forces that will shape how growth is captured, defended, and reinvested. This preview outlines the analytical architecture, competitive framing, and regulatory context embedded in the full report, while reserving the granular, procurement-actionable data for direct access to the complete intelligence package.
A Decision Architecture Built for 2026 Strategy Cycles
Enterprise decision-makers entering 2026 face a landscape where historical performance is no longer sufficient for forward allocation. The report is structured to translate market scale into actionable strategic pathways, focusing on three interlocking dimensions: demand propagation, competitive positioning, and regulatory-enabling dynamics. Rather than presenting isolated metrics, the analysis maps market behavior into operational scenarios that guide capacity planning, portfolio prioritization, procurement hedging, and geographic expansion sequencing.
At the core of the research is a multilayered market model built on historical calibration and forward scenario analysis. The study traces how demand vectors have evolved through 2025 and projects how structural drivers will re-weight market participation over the coming seven years. It evaluates where volume concentration is likely to persist, where substitution risk may alter formulation economics, and how regulatory cycles can compress or extend adoption curves. The objective is not to describe what the market is, but to equip leadership teams with the logic required to determine where to invest, where to consolidate, and where to monitor before committing resources.
Because the market operates with defined competitive density, a purely aggregate view can mask vulnerabilities and missed opportunities. The full study therefore places heavy emphasis on segment-level migration patterns, application-driven demand differentiation, and the strategic implications of product-type economics. The report also integrates supply-side realities such as formulation manufacturing complexity, quality standards, and the operational constraints that shape regional fulfillment. These layers combine to provide a practical roadmap for market entry assessment, competitive benchmarking, and long-range planning.
In the pages that follow, readers will find structured assessments across region, product type, and application, together with scenario-ready framing for pricing dynamics, replacement behavior, and procurement risk. The analysis is intended to serve both strategic planners evaluating market exposure and operational teams refining commercial execution. To maintain analytical integrity, the preview below highlights the strategic architecture and industry context while reserving the full segmentation detail and comparative metrics for the complete report.
Competitive Positioning and the Emerging Regulatory-Momentum Dynamic
A market of this scale and growth cadence does not evolve in isolation. The competitive environment reflects a moderate concentration profile, where a limited group of established players holds meaningful but not dominant share. This fragmentation creates both opportunity and friction: it allows capable entrants and incumbents to differentiate through formulation strategy, regulatory positioning, and regional commercial execution, while simultaneously raising the importance of speed, compliance readiness, and application-specific value communication.
The research profiles the competitive field with attention to formulation families, application alignment, and operational footprint. Among the companies analyzed, Elanco US Inc., headquartered in Indianapolis, Indiana, is examined for its branded approach to Tylosin tartrate and phosphate formulations, with emphasis on veterinary therapeutic contexts such as swine dysentery, respiratory disease management, and beef cattle liver abscess reduction. Huvepharma EOOD, based in Sofia, Bulgaria, is assessed for its Tylovet-branded tartrate and phosphate offerings and premixes, with positioning that spans swine dysentery, porcine proliferative enteropathies, chronic respiratory disease in poultry, and feed efficiency support in beef heifers. These profiles are not merely corporate summaries; they are framed as strategic benchmarks, helping readers understand how formulation breadth, species-specific indications, and premix integration influence commercial differentiation.
What elevates the competitive discussion beyond static profiling is recent regulatory momentum. Over the past year, the approval environment has introduced notable inflection points that are shaping how established formulations are positioned within production systems. In October 2024, FDA approval was secured for Elanco’s Tylan in combination with MGA, Experior, and Rumensin for growing beef heifers in confinement. By May 2024, supplemental NADA actions had been recorded for both Elanco US Inc. and Huvepharma EOOD, reflecting continued regulatory engagement across the sector. Most recently, in July 2025, FDA approval extended to Huvepharma’s Tylovet combination with MGA, Experior, and Monovet for confined beef heifers, supporting weight gain, feed efficiency, coccidiosis control, ammonia emission reduction, and liver abscess prevention.
Tylosin Market
Worldwide Josamycin Market
These milestones are treated in the report as strategic signals rather than isolated news items. Regulatory approvals of combination formulations can expand addressable use-cases, alter competitive dynamics within specific production segments, and influence procurement preferences as operational benefits become more clearly defined. For decision-makers, the implication is twofold: competitive advantage may increasingly accrue to organizations that integrate regulatory readiness with formulation strategy, and demand patterns may shift as approved combinations unlock operational efficiencies in targeted livestock applications. The full study translates these signals into competitive scenario mapping, providing context on how approval momentum can influence share movement, formulation preference, and the strategic positioning of incumbent players.
Industry Dynamics: Growth Drivers, Constraints, and Strategic Implications
No strategic outlook is complete without a clear view of the forces that accelerate, constrain, or redirect market behavior. In the Tylosin sector, growth is supported by enduring demand tied to livestock production intensity, veterinary therapeutic needs, and companion animal care applications, while the pace and shape of expansion are influenced by regulatory scrutiny, formulation economics, and regional adoption variance. The research integrates these dynamics into a cohesive narrative that helps executives separate cyclical noise from structural change.
On the demand side, the market benefits from consistent usage patterns across core animal health applications. Livestock-related demand remains a dominant demand anchor, reflecting the importance of disease management, performance support, and herd health protocols in commercial production environments. At the same time, companion animal and specialty application pathways contribute differentiated demand profiles that can alter regional commercial priorities and formulation preferences. The report examines how these application streams interact with procurement behavior, seasonal and production-cycle volatility, and substitution sensitivities that may influence product-type economics.
Regulatory and compliance dynamics are equally central to strategic interpretation. As illustrated by the recent approval activity, the regulatory environment can both enable and reshape market participation. Approvals for combination formulations in specific production contexts can create new commercial opportunities, but they also raise the operational bar for compliance readiness, manufacturing consistency, and documentation rigor. In this environment, organizations that align R&D, regulatory affairs, and commercial strategy are better positioned to convert approval momentum into durable market advantage. The study explores these interactions without reducing them to simplistic cause-and-effect claims, instead mapping them as strategic variables that influence timing, distribution, and competitive response.
Supply-side and regional considerations further complicate the landscape. Manufacturing complexity, formulation standardization, and distribution pathways influence how efficiently demand can be served across geographies. Regional variation in adoption, regulatory interpretation, and veterinary practice patterns can create pockets of stronger or weaker momentum, which in turn shape where commercial resources should be concentrated. The full report provides a structured evaluation of these dynamics, enabling readers to understand not just where growth is occurring, but why it is occurring there, and what it means for resource allocation.
What the Full Research Delivers: Content, Structure, and Strategic Utility
The complete study is designed as a practical executive instrument rather than a passive market summary. It brings together historical calibration, forward-looking modeling, competitive profiling, and regulatory context within a unified analytical framework. The objective is to give leadership teams a defensible basis for strategy development in 2026 and beyond, with content organized for rapid extraction of the insights most relevant to each functional role.
Among the report’s core components is an in-depth segmentation analysis that disaggregates the market across region, type, and application. This structure allows readers to evaluate demand concentration, identify differential growth behavior, and understand where market economics are most sensitive to operational or regulatory changes. The report also includes competitive landscape assessment, with company-level framing that connects product strategy, application focus, and recent regulatory or commercial developments to broader positioning implications. Regulatory and approval milestones are incorporated as dynamic inputs, helping readers interpret how policy and compliance events can shift market behavior over the forecast horizon.
In addition to descriptive analysis, the study provides scenario-aware interpretation designed for planning under uncertainty. Rather than presenting a single deterministic path, it frames the market in terms of likely trajectories, potential disruption points, and strategic response options. This approach is particularly valuable for teams evaluating capacity investment, formulation portfolio decisions, procurement strategies, and market-entry or expansion planning. By linking macroeconomic direction with segment-level logic, the report supports both high-level strategic alignment and more granular commercial execution.
To illustrate the utility of the full analysis, consider how a commercial leader might use the complete segmentation logic to prioritize regional focus, or how a corporate development team could use competitive profiling and regulatory momentum mapping to evaluate partnership, licensing, or acquisition opportunities. Likewise, procurement and supply strategy teams can use the report’s structural view of demand concentration and application-driven consumption to better anticipate volume variability and formulation preference shifts. The study is built with these practical applications in mind, transforming market intelligence into a working tool for cross-functional decision-making.
Why the Complete Dataset Matters for 2026 Decisions
Strategic decisions in this market carry execution risk when they rely on partial visibility. While headline growth figures and broad competitive themes provide useful orientation, the operational value of market intelligence is realized only when it is sufficiently detailed to inform timing, prioritization, and risk calibration. A 5.6 percent forecast CAGR, for example, is directionally meaningful, but its strategic relevance depends on how growth is distributed across applications, product types, and regions, and on how those distributions interact with regulatory change and competitive response.
The complete report is therefore constructed to close the gap between directional insight and decision-grade evidence. It preserves the strategic narrative outlined here while extending into the granular segmentation detail, comparative metrics, and scenario framing that enterprise teams require for concrete action. Readers seeking to evaluate market entry, benchmark competitors, plan procurement exposure, or align commercial resources with high-probability growth vectors will find the full dataset essential.
For organizations preparing for 2026 and the years that follow, the strategic question is not whether the Tylosin market will continue to expand, but how to position within that expansion with clarity, discipline, and regulatory awareness. The full research release is designed to answer that question with depth, structure, and practical utility. To access the detailed segmentation analysis, competitive benchmarks, and scenario frameworks that complete this strategic picture, request the full report through the source page and equip your leadership team with the intelligence needed to act decisively.
For detailed analysis of this topic, please visit the official page: Tylosin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Diamond Wire Saw Market Hits $1.1B in 2025, Projected 5.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Next Cycle: Unpacking the Diamond Wire Saw Market Outlook
As industries accelerate toward higher precision manufacturing and sustainable material processing, the diamond wire saw market stands at a critical inflection point. For executives navigating capital allocation, supply chain optimization, and technology procurement in 2026, understanding the underlying demand architecture is no longer optional. This strategic briefing introduces our latest comprehensive market research, designed to translate macroeconomic trajectories, competitive positioning, and technological shifts into actionable intelligence for boardroom decision-making.
The sector has demonstrated remarkable resilience through recent volatility, and the forward trajectory suggests continued structural expansion. Our analysis frames the 2026 landscape as a decisive year where operational efficiency, material-grade advancements, and application-specific cutting architectures will separate market leaders from marginal participants. The following insights synthesize historical performance, near-term forecasts, and competitive dynamics to establish the strategic foundation for your next planning cycle.
Market Trajectory and Structural Fundamentals
Historical data reveals a market that has consistently expanded despite periodic demand disruptions and raw material price fluctuations. From a baseline of approximately 910 million USD in the early 2020s, the industry progressed through measured growth phases, crossing the 1.1 billion USD threshold by the mid-2020s. This progression reflects not merely cyclical recovery but a fundamental shift in how precision cutting technologies are integrated across high-value manufacturing pipelines.
The forecast horizon extending through 2032 maps a consistent upward trajectory, with a compound annual growth rate of 5.2 percent anchoring long-term planning assumptions. At this pace, the market is projected to approach the 1.6 billion USD mark by the end of the decade, underscoring sustained demand from both legacy industrial applications and emerging technology sectors. For strategic planners, this growth profile suggests that capacity investments, R&D allocation, and vendor partnerships must be evaluated against a steadily expanding addressable market rather than short-term demand spikes.
Several structural drivers reinforce this outlook. The ongoing transition toward higher-purity materials in electronics and renewable energy manufacturing requires cutting technologies that minimize subsurface damage, reduce kerf loss, and maintain consistency across high-volume production runs. Simultaneously, traditional sectors such as stone processing and construction materials continue to modernize equipment fleets, replacing abrasive or legacy mechanical methods with diamond wire architectures that deliver longer service life and lower operational friction. These overlapping demand currents create a diversified revenue base that buffers against single-sector downturns.
Segmentation Dynamics and Demand Architecture
The market's composition reflects a clear division between product architectures, application verticals, and geographic demand centers. Understanding which segments command premium positioning versus volume-driven scale is essential for pricing strategy, product roadmap development, and go-to-market execution.
Diamond Wire Saw Market
- Product Type Evolution. The market differentiates primarily between electroplated and resin-bonded diamond wire formulations, alongside specialized variants tailored for niche geometries or extreme hardness materials. Electroplated configurations continue to capture substantial share due to their suitability for high-precision slicing and consistent diamond exposure, particularly in environments where edge quality and repeatability dictate yield outcomes. Resin-bonded alternatives serve applications where flexibility, cost-efficiency, and moderate cutting force are acceptable trade-offs. The balance between these architectures shapes vendor portfolios and influences procurement decisions across industrial buyers.
- Application Verticals. Demand is anchored across semiconductor wafer manufacturing, photovoltaic cell cutting, stone and concrete processing, and optical glass fabrication. Each vertical carries distinct performance requirements. Semiconductor and photovoltaic applications prioritize micron-level precision, minimal thermal disruption, and compatibility with large-format ingots. Stone and concrete segments emphasize throughput, blade durability, and adaptability to variable material densities. Optical glass cutting demands surface integrity and scratch-free finishes to preserve optical performance. The interplay of these requirements determines which wire configurations and machine architectures gain traction in specific buyer communities.
- Regional Demand Patterns. Growth is distributed across multiple economic zones, with certain regions exhibiting stronger concentration in high-technology manufacturing and others maintaining robust industrial processing volumes. Supply chain localization, import dependencies, and regional certification requirements further shape procurement pathways. Buyers increasingly evaluate total cost of ownership, lead time reliability, and after-sales technical support alongside unit pricing, particularly as equipment downtime carries measurable production penalties in high-throughput environments.
Competitive Landscape and Strategic Positioning
The industry features a concentrated competitive structure, with the top three players accounting for approximately 65 percent of total market revenue and the top five firms representing around 82 percent. This concentration signals the presence of established technology platforms, strong customer linkages, and significant barriers to entry for newcomers lacking proprietary coating technologies or proven service networks. For buyers and investors alike, monitoring the strategic moves of incumbent players provides early signals of pricing behavior, innovation pacing, and potential consolidation pathways.
Well Diamond Saws SA, headquartered in Switzerland, has built its reputation over decades as a manufacturer of specialized diamond wire saw systems designed for hard and brittle materials. The company's emphasis on patented synthetic diamond wire coatings and low-heat cutting methodologies positions it within precision-oriented application segments where thermal damage and material stress must be minimized. Its global distribution footprint, encompassing thousands of deployed units, reflects long-standing acceptance among operators prioritizing process stability and surface quality.
Ensoll Tools Technology Co., Ltd., based in China, has developed a focused portfolio around endless diamond wire loops and integrated cutting machines. With a substantial patent portfolio and a one-stop solution approach, the company addresses industrial buyers seeking coordinated equipment and consumables architectures. Its operational standards, including ISO 9001 certification for production processes, highlight a commitment to manufacturing consistency that resonates with procurement teams managing quality assurance across multiple shift environments.
GTI Technologies, Inc., operating from the United States, serves as a supplier and distributor of Takatori diamond wire saws and related products. The company's focus on high-speed slicing for semiconductors, advanced materials, and quarrying applications underscores the value of multi-wire systems in throughput-intensive settings. By bridging specialized product lines with application expertise, the firm supports buyers who require fast cycle times while maintaining the integrity of delicate or high-value workpieces.
Recent industry activity reinforces the pace of product evolution. In mid-2025, JSEDM introduced diamond wire saw machines at a major semiconductor exhibition, unveiling multi-size compatible systems targeting 6-inch, 8-inch, and 12-inch ingot formats, with completion milestones set for mid-2026. This development signals growing emphasis on flexible machine architectures capable of accommodating varying wafer and ingot dimensions without complete line retooling. Alongside this, a major stone-processing equipment release highlighted the continued push toward high-speed diamond wire solutions in masonry and construction material applications, reflecting broader modernization trends in traditional industrial segments. Meanwhile, technology provider updates showcased over a decade of iterative innovation in diamond wire cutting, reinforcing the narrative that incremental improvements in coating durability, wire tension control, and machine ergonomics remain central to competitive differentiation.
Operational Dynamics and Investment Considerations
Beyond headline figures and vendor profiles, the operational environment introduces several variables that influence purchasing strategy and capital planning. Wire pricing and configuration choices, for instance, vary significantly by application intensity. Premium single-wire systems designed for semiconductor-grade precision typically command higher per-meter costs, while multi-wire configurations optimized for high-volume solar production operate at a lower unit price point due to economies of scale and different performance tolerances. Buyers must therefore evaluate not just the nominal equipment cost but the total cutting solution economics aligned with their throughput targets and yield requirements.
Technical specifications also shape implementation decisions. Standard wire lengths, diameter ranges, and speed limitations are calibrated to specific machine platforms and material profiles. Systems engineered to operate with minimal applied force and controlled wire velocities help prevent thermal buildup and preserve workpiece integrity, an especially relevant consideration for brittle or optically sensitive materials. These engineering parameters influence operator training, maintenance intervals, and consumable replacement cycles, all of which contribute to the effective cost of production over the equipment lifecycle.
From a strategic planning perspective, decision-makers should consider several interconnected factors when evaluating market participation or procurement timing:
- Alignment between wire technology selection and the dominant material formats in the production pipeline, including diameters, hardness profiles, and defect sensitivity.
- Assessment of machine flexibility to accommodate format transitions, particularly as wafer, ingot, and panel dimensions continue to evolve across semiconductor and photovoltaic lines.
- Supplier reliability indicators such as certification status, patent depth, service coverage, and historical uptime performance under continuous operation conditions.
- Sensitivity of total cost models to consumable pricing, replacement frequency, and the operational trade-offs between higher-precision single-wire setups and higher-throughput multi-wire configurations.
- Geographic and logistics considerations affecting lead times, spare parts availability, and regional support responsiveness.
These considerations do not operate in isolation. A procurement choice that reduces per-unit consumable expense may increase cycle time or require additional quality inspection overhead. Conversely, an investment in higher-precision equipment may yield downstream benefits in yield recovery and reduced rework. The optimal configuration depends on a disciplined evaluation of process constraints, volume expectations, and quality thresholds unique to each operational context.
Conclusion and Strategic Call to Action
The diamond wire saw market presents a compelling blend of steady structural growth, concentrated competitive dynamics, and continuous technological refinement. As manufacturing sectors demand higher precision, lower waste, and greater flexibility across material formats, the companies and procurement teams that act on rigorous, granular intelligence will secure a measurable advantage in both cost efficiency and process reliability. The broader market trajectory supports long-term planning, but the specific allocation of resources, the selection of equipment architectures, and the timing of vendor partnerships require insight that extends well beyond aggregate forecasts.
Our full market research publication provides the depth required to translate these dynamics into executable strategy. It delivers a comprehensive mapping of segmentation performance, regional demand behavior, competitive benchmarking, product-type economics, application-specific procurement drivers, and the operational variables that shape total cost of ownership across major industry verticals. The complete dataset, scenario frameworks, and strategic recommendations are structured to support capital planning, product portfolio decisions, and supply chain negotiations with confidence.
For leaders preparing for the 2026 decision cycle, the next step is to access the full research suite and integrate its detailed intelligence into your strategic planning process. The aggregate outlook is clear, but the precision of your execution will depend on the granularity of the data guiding your investments.
Worldwide Wire Saw Market
For detailed analysis of this topic, please visit the official page: Diamond Wire Saw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Aerospace Materials Market Hits $32B in 2025, Projects 8.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Aerospace Materials Market 2026: Strategic Intelligence for Enterprise Decision-Making
The aerospace materials sector stands at a critical inflection point as the industry navigates a transformative decade defined by evolving aircraft architectures, stringent sustainability mandates, and shifting geopolitical supply chains. For executives, investors, and operational leaders, the difference between reactive positioning and proactive strategy lies in the quality of market intelligence. Our latest Aerospace Materials Market research study delivers precisely that: a comprehensive, data-driven framework designed to inform high-stakes decisions throughout 2026 and the extended forecast horizon through 2032.
This report is not merely an aggregation of historical figures. It is a strategic navigation tool built to decode complexity, quantify opportunity, and expose the operational realities shaping material selection, capacity planning, and competitive positioning across the global aerospace value chain. Below, we outline the analytical architecture of the study, the market dynamics it captures, and why these insights carry immediate relevance for enterprise strategy in 2026.
The Macro Trajectory: What the Top-Line Data Reveals
The overall market has exhibited persistent, compounding growth across the historical observation window spanning 2020 through 2025. Revenue expanded from approximately 25,504 million USD in 2020 to a baseline of 32,000 million USD by 2025. This trajectory reflects a sector resilient to cyclical aircraft delivery fluctuations, propelled instead by long-term fleet renewal programs, weight-reduction imperatives, and the gradual penetration of advanced composites into primary structural applications.
Looking forward, the forecast period from 2026 through 2032 projects continued expansion at a compound annual growth rate of 8.2 percent. Under this growth profile, market revenue is positioned to surpass 34,200 million USD in 2026 and climb toward the mid-55,000 million USD range by the close of the forecast window in 2032. These macro projections serve as the analytical backbone of the report, but they are never presented in isolation. Instead, they are contextualized against the operational realities, regulatory shifts, and competitive maneuvers that will determine which organizations capture disproportionate value as the market matures.
Decoding the Competitive Landscape
Market concentration remains a defining characteristic of the sector. The three largest players command a combined share of approximately 45.5 percent, while the top five firms collectively account for 52.8 percent of total revenue. This concentration signals a market where scale, certification depth, and long-term supplier relationships confer durable advantages, yet it also leaves meaningful room for specialized innovators, regional entrants, and vertically integrated material producers to compete on performance, cost, or technology differentiation.
The report profiles the core competitive set with granular attention to their aerospace-specific offerings and strategic positioning. Leading global suppliers of carbon fiber, prepregs, honeycomb cores, resins, and advanced composites certified for commercial aerospace primary and secondary structures anchor the upper tier of the market. Parallel to these established composites specialists, major international manufacturers have been scaling aerospace-grade carbon fiber, prepreg, and composite material production to support next-generation aircraft programs. Japanese producers contribute high-performance thermoplastics and advanced fabric architectures tailored to demanding aerospace applications. European carbon fiber reinforcement and prepreg suppliers maintain strong integration with continental aerospace and industrial ecosystems. Meanwhile, multinational specialty chemical and materials groups are intensifying development of thermoplastic composites, engineered resins, and specialty polymers designed for both structural and interior aerospace applications.
These profiles are not static descriptions. Each company assessment is framed around competitive moats, supply chain dependencies, certification status, and the strategic implications of their recent operational moves. This approach enables readers to map competitor intentions, anticipate supply-side disruptions, and identify partnership, sourcing, or investment opportunities that align with their own strategic objectives.
Recent Developments That Redefine Competitive Benchmarks
The pace of technological and commercial activity across the competitive set has accelerated markedly in recent months, and the report integrates these developments as actionable intelligence rather than isolated news items. In October 2025, a major Japanese materials producer introduced an advanced braided fabric architecture designed for lightweight aircraft structures, emphasizing improved mechanical performance and faster manufacturing throughput. Such launches signal a clear industry direction: the convergence of material performance gains with production efficiency improvements that directly impact aircraft program economics.
Aerospace Materials Market
During the Paris Air Show in May 2025, a leading composites supplier showcased new lightweight aerospace composite technologies alongside automated manufacturing systems and fuel-efficient structural concepts. Trade show activity of this caliber reflects both technological ambition and the increasing importance of demonstrating manufacturability at scale. In September 2025, an advanced materials company secured FAA-sponsored National Center for Advanced Materials Performance qualification for a next-generation epoxy resin system, reinforcing the critical role of certification milestones in accelerating material adoption. By November 2025, another specialist firm achieved full commercial availability of high-performance thermoplastic granules and powders, expanding the material toolkit for aerospace applications that demand recyclability, toughness, or simplified processing.
Capacity expansion remains equally pivotal. In December 2025, a major chemical group announced plans to expand carbon fiber production capacity across Japan and the United States to meet rising demand from commercial aviation and next-generation programs. These combined movements illustrate a market where product innovation, certification progress, and capacity builds are tightly interlocked, and where timing, geography, and regulatory alignment increasingly determine competitive outcomes.
Regulatory and Raw Material Dynamics Shaping 2026
Material costs, trade policy, and environmental compliance now exert direct influence on procurement strategy, program pricing, and supplier selection. The report treats these dynamics as first-order variables rather than peripheral context. PAN-based carbon fiber precursor prices rose approximately 3 percent in the first quarter of 2026, driven by acrylonitrile feedstock increases and logistics disruptions. Acrylonitrile upstream costs themselves climbed 2 to 3 percent in early 2026 as a result of maintenance outages and supply tightness across Asian production basins. These cost pressures ripple through composite value chains, influencing resin formulation decisions, alternate material evaluations, and negotiated pricing structures with airframe and engine manufacturers.
On the regulatory front, US tariffs on PAN-based carbon fiber imports took effect in 2025, altering cost structures for producers and raising compliance burdens for aerospace material suppliers navigating cross-border trade. At the same time, stricter environmental regulations governing graphite fiber production in developed markets, including the United States, Japan, and China, have tightened manufacturing permits and increased the operational cost of maintaining compliant output. These constraints are reshaping regional sourcing logic and encouraging dual-sourcing, regionalized production, and material substitution assessments.
Aerospace Sealants Market
Regulatory evolution is not uniformly restrictive. FAA Advisory Circular 33.15-3, issued in 2025, streamlined certification processes for established aerospace alloys and composites. For organizations with mature qualification portfolios, this development can shorten time-to-market for incremental design updates and reduce certification overhead. For newer entrants or novel material systems, the same landscape requires careful navigation of qualification pathways. The report captures these trade-offs explicitly so that readers can assess how certification strategy interacts with product roadmap decisions, supplier evaluation criteria, and regional market entry plans.
What the Study Delivers: Practical Analytical Modules
The research is structured to convert market complexity into usable decision frameworks. It combines macro market sizing with forward-looking modeling, segmentation analysis that isolates demand drivers by type and application, regional comparisons that highlight shifting center-of-gravity dynamics, and competitive intelligence that maps company strategies against market structure. Crucially, the report does not present segmentation data as static slices. It contextualizes each split against the underlying drivers, restraint factors, and adoption cycles that explain why certain material categories and application segments command disproportionate growth or resilience.
Readers gain access to structured evaluations covering material performance trends, certification and qualification pathways, supply chain sensitivities, and the strategic implications of raw material cost volatility. The study also examines how regional manufacturing capabilities, trade policy exposure, and environmental compliance requirements influence sourcing strategies and capacity planning. Each analytical module is designed to support concrete outcomes: refining procurement roadmaps, prioritizing material development investments, assessing market entry or expansion scenarios, and benchmarking internal performance against the operational rhythms of leading competitors.
Why This Research Matters for 2026 Decision-Making
Enterprise decisions in aerospace materials are increasingly interdependent. Procurement choices intersect with certification timelines. Capacity commitments must account for trade policy and feedstock volatility. Product roadmaps need to align with automated manufacturing expectations and evolving environmental regulations. In this environment, organizations that rely on fragmented intelligence or backward-looking benchmarks risk misallocating capital, misreading competitor intent, or underestimating the operational friction embedded in material transitions.
This study provides a consolidated view that connects market growth expectations with the structural forces shaping them. It enables leadership teams to evaluate where differentiation is achievable, where scale and certification confer protection, and where disruption is most likely to emerge from new material systems, regional capacity builds, or regulatory realignments. By integrating the top-line growth profile, concentration dynamics, competitive moves, and cost and compliance pressures into a single analytical narrative, the report equips decision-makers to act with greater confidence and precision throughout 2026 and beyond.
The Full Intelligence Landscape Awaits
The aerospace materials market is expanding, but its value is not distributed evenly across participants, regions, applications, or material categories. Understanding where growth concentrates, which competitive advantages are durable, and how regulatory and raw material shifts alter the playing field requires the depth and structure included in the complete study.
This preview offers a strategic overview of the macro trajectory, competitive architecture, and market dynamics that define the sector today. The full report extends far beyond this introduction, delivering the detailed segmentation context, regional analysis, company-level competitive assessments, supply-side sensitivity evaluations, and forward-looking scenario frameworks that enterprise teams need to translate market intelligence into actionable strategy. For leaders seeking to align investment, sourcing, and innovation decisions with the most current and comprehensive market picture available, the complete study provides the analytical foundation required to move decisively in 2026 and across the forecast horizon.
For detailed analysis of this topic, please visit the official page: Aerospace Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Fencing Market to Reach $15.5B by 2032, Growing at 4.2% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Metal Fencing Market: A 2026 Outlook
The metal fencing sector stands at a pivotal inflection point as the global economy recalibrates around security, infrastructure resilience, and supply chain sovereignty. For executives, investors, and procurement leaders operating in 2026, the ability to navigate shifting trade policies, evolving material preferences, and localized manufacturing dynamics will define competitive positioning over the coming decade. Our latest comprehensive research on the Metal Fencing Market delivers the granular intelligence required to transform these macro-level uncertainties into actionable strategy.
Market trajectories over the past five years have demonstrated remarkable resilience despite macroeconomic headwinds, with historical valuations tracing a clear consolidation pattern before stabilizing at a baseline of 11,650.00 Million USD in 2025. Looking forward, the sector is positioned to recover and expand, projected to reach 12,464.48 Million USD in 2026 and climb steadily to 15,540.00 Million USD by 2032. This growth path reflects a compound annual growth rate of 4.2 percent across the forecast horizon, signaling steady demand augmentation rather than speculative surges. The underlying drivers extend beyond simple population growth; they encompass heightened perimeter security requirements, replacing aging infrastructure with durable metal systems, and the ongoing realignment of global manufacturing footprints.
What distinguishes this research from conventional industry summaries is its emphasis on decision-ready frameworks. Rather than presenting isolated statistics, the analysis maps growth vectors to operational levers, enabling stakeholders to calibrate capacity planning, regional deployment, and product-mix optimization with precision. The following sections outline the strategic architecture of the report and demonstrate why its insights are indispensable for 2026 planning cycles.
Mapping the Competitive Landscape
The metal fencing ecosystem is characterized by a moderately fragmented structure, with consolidated players commanding a combined share that leaves substantial room for specialized manufacturers and regional specialists to capture niche premiums. Our analysis evaluates the strategic positioning of leading enterprises, including AMICO Security, Calimet Co., Inc., Bull Barn Fence Factory, and Gregory Fence, each of which illustrates distinct approaches to value creation in a complex market environment.
AMICO Security, operating from Birmingham, Alabama, has built a legacy since 1939 around metal fence systems, wire mesh fencing, and perimeter security solutions. Its longevity reflects an ability to adapt product portfolios to evolving security standards while maintaining manufacturing continuity. Calimet Co., Inc., based in South El Monte, California, differentiates through an assembled-in-USA value proposition, offering gate automation solutions and metal fence components that appeal to buyers prioritizing domestic supply chain integrity. Bull Barn Fence Factory serves agricultural and industrial segments with high-quality woven wire and barbed wire fencing products, demonstrating how material specialization can anchor a defensible market position. Gregory Fence, headquartered in Canton, Ohio, focuses on American-made steel fence systems and C-post products engineered for perimeter protection, aligning closely with infrastructure and commercial security demands.
Recent activity among these players underscores the sector's operational vitality. Throughout February 2026, multiple manufacturers exhibited their metal fence systems, woven wire fencing solutions, and steel fence platforms at The Fence Show & Security Expo, signaling sustained investment in product demonstration, channel development, and customer engagement. These exhibition footprints are not merely promotional events; they represent strategic touchpoints where manufacturers validate specifications, gather competitive intelligence, and secure downstream partnerships that will influence distribution dynamics through the forecast period.
Regulatory and Supply Chain Dynamics
Trade policy developments have introduced a new layer of complexity to sourcing strategies, particularly within the United States market. On January 15, 2025, the U.S. Department of Commerce initiated an antidumping and countervailing duty investigation into temporary steel fencing from the People's Republic of China. The subsequent determination by the U.S. International Trade Commission on April 9, 2026 concluded that such imports materially injure domestic industry, resulting in antidumping and countervailing duty orders. These regulatory actions reshape cost structures, alter supplier eligibility, and compel buyers to re-evaluate procurement timelines and inventory buffers. For market participants, the implications extend beyond tariff calculations; they affect contract negotiations, production scheduling, and the competitive calculus between imported and domestically fabricated solutions.
Raw material conditions further influence manufacturing economics. According to the World Steel Association, global crude steel production reached 153.4 million tonnes in April 2026, representing a 1.9 percent decrease compared to the same period in 2025. While month-to-month fluctuations are inherent to cyclical industrial activity, the availability of updated reference data through World Steel in Figures 2026 provides analysts and operations leaders with a more complete picture of production and trade flows. These material dynamics intersect directly with fencing product costing, especially for steel-dominant segments, and highlight the need for scenario-based procurement planning that accounts for input volatility.
Metal Fencing Market
Our research integrates these regulatory and material factors into a cohesive dynamics framework, allowing readers to assess how policy shifts and supply conditions compound across different market nodes. By mapping the interaction between trade remedies, domestic capacity utilization, and material cost trajectories, the report equips decision-makers with the context required to anticipate disruption rather than merely react to it.
Decoding Segmentation and Demand Architecture
The market's structural composition reflects a diversified demand base spanning residential, commercial, and industrial applications, alongside a material mix anchored by steel, aluminium, wrought iron, and supplementary product categories. Each segment carries distinct procurement motivations, specification requirements, and lifecycle considerations. Residential deployments typically prioritize aesthetic integration, durability, and localized installer networks, while commercial projects emphasize security performance, compliance with institutional standards, and scalable installation footprints. Industrial applications, meanwhile, demand robustness under harsh operating conditions, often combining fencing with broader perimeter management and access control systems.
On the material side, steel continues to command substantial market weight given its strength-to-cost profile and broad applicability across security and infrastructure contexts. Aluminium offers corrosion resistance and lighter handling characteristics that appeal to specific environmental and architectural requirements. Wrought iron maintains a presence where ornamental value and perceived durability align with premium positioning. The report examines these material segments not as static share allocations but as strategic choices influenced by regional availability, fabrication capabilities, end-use specifications, and total cost of ownership calculations.
Importantly, the research avoids reductive regional generalizations. Instead, it evaluates demand intensity, competitive density, and sourcing behavior across major geographic corridors, revealing where domestic manufacturing advantages, import dependency patterns, and local code requirements shape procurement outcomes. This approach ensures that readers understand how segment performance varies in practice rather than relying on aggregate figures that obscure operational realities.
Electric Fencing Market
What the Report Delivers: Operational Intelligence for 2026
This market research is structured to support concrete executive action across multiple functional areas. The analytical content extends well beyond high-level sizing, offering a multidimensional view that connects market size evolution to strategic execution. Key components include:
- A detailed historical and forecast trajectory that contextualizes 2025 baseline conditions against the 2026 to 2032 growth pathway, enabling realistic capacity and revenue planning.
- Segment-level analysis that decomposes demand by application type and material composition, clarifying where differentiation opportunities and margin protection strategies are most viable.
- Regional evaluation frameworks that assess competitive intensity, supply chain configuration, and procurement behavior without relying on oversimplified geographic narratives.
- Competitive profiling of leading manufacturers, including strategic capabilities, product orientations, and recent market-facing activities that indicate near-term positioning.
- Regulatory and trade impact assessments that translate duty orders, investigation outcomes, and raw material production data into sourcing and risk-management considerations.
- Scenario-oriented guidance that helps organizations stress-test assumptions around input costs, import availability, and demand pacing under varying macroeconomic conditions.
Each section is designed to feed directly into planning workflows. Whether the objective is to refine a product portfolio, restructure a distribution footprint, negotiate supplier contracts, or evaluate merger and acquisition targets, the report's architecture supports evidence-based choices rather than intuition-led reactions.
Translating Insights into Executive Action
For 2026 decision-making, the strategic value of this research lies in its capacity to bridge market structure with operational consequence. Executives can use the findings to determine where to allocate capital for capacity expansion, which material segments warrant increased specification focus, and how trade remedy outcomes may alter the cost competitiveness of domestic versus imported fencing solutions. Procurement teams can leverage the regulatory and raw material analysis to structure contracts that Mitigate exposure to duty-driven price volatility and production fluctuations. Sales and marketing leaders can align messaging and channel strategies with the application segments and regional demand patterns that demonstrate the strongest growth momentum.
The fragmented competitive structure, with a consolidated share that leaves meaningful headroom for specialized firms, also creates opportunities for targeted market entry, partnership development, and product-line extension. Companies that understand how leading manufacturers position themselves around domestic assembly, automation integration, agricultural and industrial specialization, or perimeter security performance will be better equipped to identify whitespace and defend existing positions.
Furthermore, the interplay between regulatory developments, material supply conditions, and segment demand underscores the importance of integrated planning. Organizations that treat trade policy, raw material cycles, and application-specific procurement behavior as isolated concerns risk missing the compounding effects that shape total land-and-security economics. This research consolidates those variables into a single analytical environment, reducing the friction between market observation and strategic response.
Access the Full Strategic Assessment
The metal fencing market's trajectory through 2032 will reward organizations that combine disciplined market intelligence with agile execution. While this article outlines the strategic contours and decision frameworks embedded in our latest study, the complete research contains the detailed segmentation analysis, competitive intelligence, regulatory impact mapping, and scenario-based guidance necessary to operationalize these insights at the enterprise level. To access the full dataset, proprietary segmentations, and comprehensive company profiles that underpin this analysis, we invite you to explore the complete report through our official research portal.
For leaders preparing for 2026 planning cycles, the difference between reactive positioning and proactive strategy will depend on the depth and precision of the intelligence at hand. Our Metal Fencing Market research is designed to deliver exactly that foundation, enabling informed decisions grounded in rigorous analysis rather than generalized industry narratives.
For detailed analysis of this topic, please visit the official page: Metal Fencing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com