

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
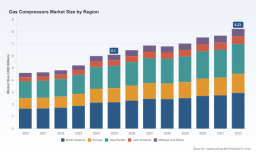
PW Consulting: Gas Compressors Market Hits $6.1B in 2025, Projected to Reach $8.23B by 2032 at 4.4% CAGR

Strategic Imperatives in the Global Gas Compressors Market: A 2026 Decision-Maker's Guide
The global industrial landscape is undergoing a profound transformation, driven by the dual engines of energy security and the urgent transition toward lower-carbon operations. At the heart of this complex engineering ecosystem lies the gas compressor, a critical asset class that enables everything from natural gas transmission and liquefied natural gas (LNG) processing to petrochemical manufacturing and emerging carbon capture initiatives. As we move further into the 2026 fiscal cycle, understanding the trajectory of this market is no longer just an engineering concern; it is a boardroom imperative. The decisions made today regarding procurement, capacity expansion, and compliance strategy will define operational resilience and profitability for the next decade.
PW Consulting's latest comprehensive market research on the Gas Compressors Market offers a rigorous, data-rich foundation for navigating this volatility. This article serves as a strategic overview of the key dynamics shaping the sector, highlighting the urgent need for granular intelligence in an environment characterized by tightening regulations, shifting supply chain economics, and intense competitive maneuvering. The findings underscore why a deep dive into our full report is essential for stakeholders aiming to secure a competitive edge from 2026 through 2032.
Defining the Market Trajectory: From Recovery to Structural Growth
The gas compressors market has demonstrated remarkable resilience and steady expansion over the recent past. Following a period of consolidation and demand recovery, the sector has settled into a robust growth phase characterized by consistent valuation increases across the global footprint. Drawing from historical data spanning the early 2020s, the market has evolved from a baseline of moderate valuation into a sophisticated multi-billion-dollar ecosystem. The upward momentum evident in the mid-2020s reflects not merely a rebound from prior disruptions but a structural expansion fueled by sustained investment in energy infrastructure, industrial capacity, and environmental compliance technologies.
Our analysis projects that this trajectory will maintain a steady compound annual growth rate throughout the forecast period. This growth is underpinned by a confluence of macroeconomic and sector-specific drivers. Continued reliance on natural gas as a transition fuel, coupled with aggressive capacity expansions in Asia and the Middle East, ensures a steady baseline of demand for core compression equipment. Simultaneously, the accelerating deployment of industrial gas systems and power generation assets provides diverse revenue streams that buffer the market against single-sector downturns. However, realizing this projected valuation requires more than passive market participation; it demands an acute awareness of the regulatory and economic variables that are rapidly reshaping the cost of doing business.
Stakeholders reviewing the high-level market size figures will recognize a clear path toward value expansion, but the devil is in the details. The sheer magnitude of the projected market by the end of the decade masks significant variations in regional maturity, technology adoption rates, and application-specific bottlenecks. Our full research deconstructs these aggregate numbers, offering a granular view that separates speculative hype from actionable investment signals. Without this granular dissection, executives risk misallocating capital or underestimating the lifecycle costs of their compression assets.
Navigating the Regulatory and Dynamic Shifts
No discussion of the 2026 compressor landscape is complete without addressing the seismic shifts in environmental regulation. The era of voluntary emissions stewardship is giving way to mandated, enforceable limits that carry substantial financial penalties. A prime example of this new reality is the regulatory evolution occurring in North America, where states such as Colorado have adopted revisions to Regulation Number 7, aligning with federal emission standards. These updates introduce specific methane emissions limits applicable to centrifugal compressors—both wet and dry seal variants—as well as reciprocating compressors used in oil and gas operations. Effective for the 2027 operational cycle, these regulations require facilities to maintain emissions below specified volumetric flow rate limits, fundamentally altering the engineering specifications and selection criteria for new installations and retrofits.
Furthermore, the financial stakes of non-compliance have been escalated by federal-level policy. The introduction of a Waste Emissions Charge, applied to methane emissions from natural gas compressor stations at a rate of $1,500 per ton starting in 2026, transforms environmental compliance from a technical challenge into a direct line-item cost consideration. For operators managing large fleets of compression assets, the margin for error has vanished. This charge incentivizes the rapid adoption of high-efficiency sealing technologies, leak detection systems, and potentially the accelerated replacement of aging equipment that cannot be economically retrofitted. Our report provides a detailed analysis of how these regulatory layers interact with operational budgets, helping clients model the total cost of ownership under the new compliance regime.
Beyond regulation, the supply-side economics are also presenting headwinds that require strategic foresight. The Producer Price Index for Air and Gas Compressor Manufacturing has reached elevated levels, signaling persistent cost pressures in raw materials and component manufacturing. These cost dynamics are compounded by the labor-intensive nature of large-scale compressor deployment. For instance, large reciprocating gas compressors utilized in pipeline applications require significant skilled labor for installation and periodic overhauls. Industry analysis indicates that these labor requirements can contribute 5 to 10% of the initial capital cost in annual maintenance expenses. In an environment of skilled labor shortages, this maintenance burden becomes a critical risk factor. Our study evaluates how manufacturers and operators are responding, from localizing service networks to investing in modular skid designs that reduce field installation complexity.
Competitive Landscape and Strategic Positioning
The global gas compressors market is characterized by a moderately concentrated competitive structure, where a handful of key players wield significant influence over technology standards and market share. Our analysis reveals that the top three companies command a substantial portion of the market revenue, while the top five extend their collective grip even further. This concentration highlights the importance of strategic partnerships, licensing agreements, and technological differentiation for both incumbents and new entrants. The competitive arena is divided across multiple vectors, including the type of compressor technology, the application vertical, and geographic reach.
In the natural gas and energy sectors, several formidable players have cemented their positions through specialized engineering capabilities. Ariel Corporation, based in Mount Vernon, Ohio, maintains a strong focus on high-speed reciprocating gas compressors tailored for natural gas pipelines, LNG, and oil & gas applications. Their expertise underscores the continued relevance of reciprocating technology in high-pressure transmission scenarios. Similarly, Ingersoll Rand, headquartered in Davidson, North Carolina, offers a broad portfolio of centrifugal and reciprocating gas compressors, serving the natural gas and energy sectors with a reputation for reliability and integration. Arrow Engine & Compression, operating out of Tulsa, Oklahoma, further reinforces the North American strength in reciprocating compressors for natural gas transmission and processing, catering to the specific needs of midstream operators. Archrock, also based in Houston, distinguishes itself by focusing on gas compression services, rentals, and equipment, offering a flexible asset-light model that appeals to operators seeking scalable compression capacity without heavy capital expenditure.
On the large-scale gas processing and LNG front, the competition intensifies with global energy conglomerates. Siemens Energy, with its Berlin headquarters, brings immense engineering weight to large-scale centrifugal compressors designed for gas processing, pipelines, and LNG facilities. Their integration capabilities allow for comprehensive solution delivery that spans the entire value chain. Everllence, based in Munich, is carving a distinct niche by focusing on axial and centrifugal compressors for challenging environments, including LNG, Floating Production Storage and Offloading (FPSO) vessels, and carbon capture & storage projects. Their strategic agility was highlighted by a major contract awarded in March 2026 for two radial barrel compressor skids to support Thailand's first carbon capture and storage project at the Arthit gas field. This project, which enables the capture and storage of 1 million tons of CO2 per year, exemplifies the growing intersection of traditional compression technology and decarbonization infrastructure. GE (Baker Hughes Energy Innovations), headquartered in Houston, remains a dominant force with centrifugal compressors for oil & gas, pipelines, and LNG facilities, leveraging decades of experience in turbomachinery.
The industrial and process segments are also contested by specialized manufacturers. Burckhardt Compression, from Winterthur, Switzerland, offers both centrifugal and reciprocating compressors targeting oil & gas, chemical, LNG, and hydrogen mobility segments, positioning itself at the forefront of the hydrogen economy pivot. Atlas Copco, based in Stockholm, focuses on energy-efficient gas compressors for industrial and process applications, appealing to clients prioritizing operational efficiency and sustainability. Chart Industries, located in Ball Ground, Georgia, provides specialized compressors and related systems for LNG and gas processing, while Bauer Compressors, also from Munich, targets CNG and process gas compressors for industrial and vehicle applications, addressing the growing demand for compressed natural gas infrastructure. Caterpillar Inc., headquartered in Irving, Texas, complements the landscape with gas compression systems and engines for power generation and industrial use, offering integrated power and compression solutions.
The interplay between these companies is dynamic. Recent developments, such as the aforementioned Everllence order for CCS, signal how technology providers are aligning their product roadmaps with government-backed decarbonization initiatives. Meanwhile, manufacturers must also contend with the regulatory pressures mentioned earlier, forcing them to innovate in seal technology and emissions monitoring. Our full report provides a deep-dive competitor benchmarking analysis, evaluating each entity's product portfolio strength, geographic coverage, and strategic response to regulatory shifts. We reveal which players are best positioned to capture value in specific sub-segments, without diluting the proprietary granularity that makes our intelligence actionable.
Operating, Application, and Regional Nuances
While aggregate growth numbers provide the macro view, the true strategic value lies in understanding the segmentation drivers that dictate demand patterns. The market is segmented by compressor type, application, and region, each with distinct growth profiles and competitive pressures. In terms of technology, the split between centrifugal, reciprocating, screw, and axial compressors reflects a trade-off between capacity, pressure requirements, efficiency, and cost. Centrifugal compressors dominate in large-scale continuous flow applications such as pipelines and LNG, where reliability and throughput are paramount. Reciprocating compressors remain essential for high-pressure, low-volume applications, often found in wellheads and specific processing stages. Screw and axial compressors serve niche but critical roles in industrial gases and specialized processing, respectively. The choice of technology is increasingly influenced not just by technical specs but by emissions compliance capabilities; for instance, the distinction between wet and dry seal centrifugal compressors now carries direct regulatory and cost implications due to methane leak constraints.
Gas Compressors Market
Application-wise, the oil & gas production segment continues to be the dominant anchor of the market, driven by ongoing extraction activities and midstream infrastructure needs. However, petrochemical plants, power generation, and industrial gases segments offer diverse growth vectors. Power generation demand is tied to the resilience of the grid and the role of gas-fired plants in balancing renewable intermittency. Industrial gases demand is expanding with the growth of manufacturing and the emergence of hydrogen and syngas applications. Our report dissects the revenue contribution and growth trajectories of these application areas, helping clients identify which verticals offer the most attractive risk-adjusted returns.
Regionally, the market exhibits a complex tapestry of maturity and emerging opportunity. North America maintains a significant share of the global market, supported by a mature shale gas ecosystem and aggressive midstream expansion. Europe represents a regulated, efficiency-driven market with strong ties to hydrogen and CCS initiatives. Asia Pacific is a region of high growth potential, fueled by industrialization, energy demand, and infrastructure development in key economies. Latin America and the Middle East & Africa contribute meaningful volumes, often linked to specific hydrocarbon projects and industrialization efforts. However, analyzing regional share without the context of local regulatory frameworks, supply chain maturity, and competitive intensity can lead to flawed market entry strategies. Our research provides the necessary regional intelligence, mapping out the specific drivers, barriers, and key local players that define each geography, enabling clients to prioritize their market engagement with precision.
Air Compressors Market
Why This Report is Indispensable for 2026 Decision-Making
In a market environment defined by regulatory tightening, cost volatility, and technological evolution, generic industry summaries are insufficient for strategic planning. The PW Consulting Gas Compressors Market research report is designed to bridge the gap between high-level awareness and operational execution. It goes beyond stating that the market is growing; it quantifies the impact of the $1,500 per ton Waste Emissions Charge on fleet economics. It illuminates how the Pumping Price Index fluctuations affect procurement timing and contract negotiations. It reveals how the labor cost burden for large reciprocating compressors influences the total cost of ownership versus electrification or modular alternatives.
The report serves as a comprehensive toolkit for a wide range of stakeholders. For manufacturers and technology providers, it offers a clear view of competitive positioning, white spaces for product development, and the regulatory features that customers will demand in the coming years. For operators and EPC contractors, it provides the data needed to optimize asset selection, plan maintenance budgets, and mitigate compliance risks. For investors and financial analysts, it delivers the granular segmentation and forecasting data required to validate investment theses and assess market concentration risks. The inclusion of detailed profiles on key companies, coupled with recent developments tracking, ensures that decision-makers are aware of the latest strategic moves and order flows that signal market direction.
Moreover, the forecast period extending to 2032 allows for long-term capacity planning. The projected growth trajectory suggests sustained demand, but the path is not linear. Variables such as the pace of the energy transition, the adoption of new emissions technologies, and geopolitical shifts in energy trade will create inflection points. Our report models these scenarios, providing sensitivity analyses that help clients stress-test their strategies against multiple futures. By understanding the interplay between the dominant oil & gas application and the emerging CCS and hydrogen segments, stakeholders can build portfolios that are resilient to sector-specific shocks.
Conclusion: Access the Full Intelligence
The gas compressors market in 2026 presents a paradox of stability and disruption. The macro fundamentals point to steady growth and expanding value, yet the micro-level dynamics of regulation, cost, and technology are rewriting the rules of engagement. The Waste Emissions Charge, the Colorado Regulation Number 7 updates, and the elevated manufacturing costs are not transient issues; they are structural changes that will define the competitive landscape for years. Similarly, the strategic moves by companies like Everllence into carbon capture compression signal a market that is adapting to broader environmental goals, creating new revenue streams while challenging legacy product lines.
To navigate this complexity, organizations need more than anecdotal evidence or top-line market size figures. They need a detailed, data-backed roadmap that exposes the hidden drivers of value and risk. PW Consulting's full market research report delivers this intelligence. It unpacks the segmentation splits by type, application, and region, revealing the specific sub-markets that offer the highest growth potential and the most favorable competitive conditions. It provides a rigorous analysis of the market concentration and the strategic postures of the leading players, from Ariel and Ingersoll Rand to Siemens Energy and Everllence.
Do not leave your 2026 strategy to chance. Equip your team with the precise, actionable insights required to optimize investments, ensure compliance, and capture market share in a rapidly evolving industry. Visit the source webpage to access the complete Gas Compressors Market report, download the detailed segmentation tables, and leverage the full depth of our analyst expertise. The future of gas compression is being written now; ensure you have the intelligence to lead rather than follow.
For detailed analysis of this topic, please visit the official page: Gas Compressors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com