

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metal Fencing Market to Reach $15.5B by 2032, Growing at 4.2% CAGR

Strategic Imperatives in the Metal Fencing Market: A 2026 Outlook
The metal fencing sector stands at a pivotal inflection point as the global economy recalibrates around security, infrastructure resilience, and supply chain sovereignty. For executives, investors, and procurement leaders operating in 2026, the ability to navigate shifting trade policies, evolving material preferences, and localized manufacturing dynamics will define competitive positioning over the coming decade. Our latest comprehensive research on the Metal Fencing Market delivers the granular intelligence required to transform these macro-level uncertainties into actionable strategy.
Market trajectories over the past five years have demonstrated remarkable resilience despite macroeconomic headwinds, with historical valuations tracing a clear consolidation pattern before stabilizing at a baseline of 11,650.00 Million USD in 2025. Looking forward, the sector is positioned to recover and expand, projected to reach 12,464.48 Million USD in 2026 and climb steadily to 15,540.00 Million USD by 2032. This growth path reflects a compound annual growth rate of 4.2 percent across the forecast horizon, signaling steady demand augmentation rather than speculative surges. The underlying drivers extend beyond simple population growth; they encompass heightened perimeter security requirements, replacing aging infrastructure with durable metal systems, and the ongoing realignment of global manufacturing footprints.
What distinguishes this research from conventional industry summaries is its emphasis on decision-ready frameworks. Rather than presenting isolated statistics, the analysis maps growth vectors to operational levers, enabling stakeholders to calibrate capacity planning, regional deployment, and product-mix optimization with precision. The following sections outline the strategic architecture of the report and demonstrate why its insights are indispensable for 2026 planning cycles.
Mapping the Competitive Landscape
The metal fencing ecosystem is characterized by a moderately fragmented structure, with consolidated players commanding a combined share that leaves substantial room for specialized manufacturers and regional specialists to capture niche premiums. Our analysis evaluates the strategic positioning of leading enterprises, including AMICO Security, Calimet Co., Inc., Bull Barn Fence Factory, and Gregory Fence, each of which illustrates distinct approaches to value creation in a complex market environment.
AMICO Security, operating from Birmingham, Alabama, has built a legacy since 1939 around metal fence systems, wire mesh fencing, and perimeter security solutions. Its longevity reflects an ability to adapt product portfolios to evolving security standards while maintaining manufacturing continuity. Calimet Co., Inc., based in South El Monte, California, differentiates through an assembled-in-USA value proposition, offering gate automation solutions and metal fence components that appeal to buyers prioritizing domestic supply chain integrity. Bull Barn Fence Factory serves agricultural and industrial segments with high-quality woven wire and barbed wire fencing products, demonstrating how material specialization can anchor a defensible market position. Gregory Fence, headquartered in Canton, Ohio, focuses on American-made steel fence systems and C-post products engineered for perimeter protection, aligning closely with infrastructure and commercial security demands.
Recent activity among these players underscores the sector's operational vitality. Throughout February 2026, multiple manufacturers exhibited their metal fence systems, woven wire fencing solutions, and steel fence platforms at The Fence Show & Security Expo, signaling sustained investment in product demonstration, channel development, and customer engagement. These exhibition footprints are not merely promotional events; they represent strategic touchpoints where manufacturers validate specifications, gather competitive intelligence, and secure downstream partnerships that will influence distribution dynamics through the forecast period.
Regulatory and Supply Chain Dynamics
Trade policy developments have introduced a new layer of complexity to sourcing strategies, particularly within the United States market. On January 15, 2025, the U.S. Department of Commerce initiated an antidumping and countervailing duty investigation into temporary steel fencing from the People's Republic of China. The subsequent determination by the U.S. International Trade Commission on April 9, 2026 concluded that such imports materially injure domestic industry, resulting in antidumping and countervailing duty orders. These regulatory actions reshape cost structures, alter supplier eligibility, and compel buyers to re-evaluate procurement timelines and inventory buffers. For market participants, the implications extend beyond tariff calculations; they affect contract negotiations, production scheduling, and the competitive calculus between imported and domestically fabricated solutions.
Raw material conditions further influence manufacturing economics. According to the World Steel Association, global crude steel production reached 153.4 million tonnes in April 2026, representing a 1.9 percent decrease compared to the same period in 2025. While month-to-month fluctuations are inherent to cyclical industrial activity, the availability of updated reference data through World Steel in Figures 2026 provides analysts and operations leaders with a more complete picture of production and trade flows. These material dynamics intersect directly with fencing product costing, especially for steel-dominant segments, and highlight the need for scenario-based procurement planning that accounts for input volatility.
Metal Fencing Market
Our research integrates these regulatory and material factors into a cohesive dynamics framework, allowing readers to assess how policy shifts and supply conditions compound across different market nodes. By mapping the interaction between trade remedies, domestic capacity utilization, and material cost trajectories, the report equips decision-makers with the context required to anticipate disruption rather than merely react to it.
Decoding Segmentation and Demand Architecture
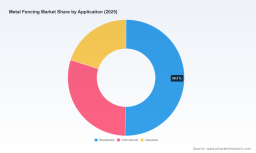
The market's structural composition reflects a diversified demand base spanning residential, commercial, and industrial applications, alongside a material mix anchored by steel, aluminium, wrought iron, and supplementary product categories. Each segment carries distinct procurement motivations, specification requirements, and lifecycle considerations. Residential deployments typically prioritize aesthetic integration, durability, and localized installer networks, while commercial projects emphasize security performance, compliance with institutional standards, and scalable installation footprints. Industrial applications, meanwhile, demand robustness under harsh operating conditions, often combining fencing with broader perimeter management and access control systems.
On the material side, steel continues to command substantial market weight given its strength-to-cost profile and broad applicability across security and infrastructure contexts. Aluminium offers corrosion resistance and lighter handling characteristics that appeal to specific environmental and architectural requirements. Wrought iron maintains a presence where ornamental value and perceived durability align with premium positioning. The report examines these material segments not as static share allocations but as strategic choices influenced by regional availability, fabrication capabilities, end-use specifications, and total cost of ownership calculations.
Importantly, the research avoids reductive regional generalizations. Instead, it evaluates demand intensity, competitive density, and sourcing behavior across major geographic corridors, revealing where domestic manufacturing advantages, import dependency patterns, and local code requirements shape procurement outcomes. This approach ensures that readers understand how segment performance varies in practice rather than relying on aggregate figures that obscure operational realities.
Electric Fencing Market
What the Report Delivers: Operational Intelligence for 2026
This market research is structured to support concrete executive action across multiple functional areas. The analytical content extends well beyond high-level sizing, offering a multidimensional view that connects market size evolution to strategic execution. Key components include:
- A detailed historical and forecast trajectory that contextualizes 2025 baseline conditions against the 2026 to 2032 growth pathway, enabling realistic capacity and revenue planning.
- Segment-level analysis that decomposes demand by application type and material composition, clarifying where differentiation opportunities and margin protection strategies are most viable.
- Regional evaluation frameworks that assess competitive intensity, supply chain configuration, and procurement behavior without relying on oversimplified geographic narratives.
- Competitive profiling of leading manufacturers, including strategic capabilities, product orientations, and recent market-facing activities that indicate near-term positioning.
- Regulatory and trade impact assessments that translate duty orders, investigation outcomes, and raw material production data into sourcing and risk-management considerations.
- Scenario-oriented guidance that helps organizations stress-test assumptions around input costs, import availability, and demand pacing under varying macroeconomic conditions.
Each section is designed to feed directly into planning workflows. Whether the objective is to refine a product portfolio, restructure a distribution footprint, negotiate supplier contracts, or evaluate merger and acquisition targets, the report's architecture supports evidence-based choices rather than intuition-led reactions.
Translating Insights into Executive Action
For 2026 decision-making, the strategic value of this research lies in its capacity to bridge market structure with operational consequence. Executives can use the findings to determine where to allocate capital for capacity expansion, which material segments warrant increased specification focus, and how trade remedy outcomes may alter the cost competitiveness of domestic versus imported fencing solutions. Procurement teams can leverage the regulatory and raw material analysis to structure contracts that Mitigate exposure to duty-driven price volatility and production fluctuations. Sales and marketing leaders can align messaging and channel strategies with the application segments and regional demand patterns that demonstrate the strongest growth momentum.
The fragmented competitive structure, with a consolidated share that leaves meaningful headroom for specialized firms, also creates opportunities for targeted market entry, partnership development, and product-line extension. Companies that understand how leading manufacturers position themselves around domestic assembly, automation integration, agricultural and industrial specialization, or perimeter security performance will be better equipped to identify whitespace and defend existing positions.
Furthermore, the interplay between regulatory developments, material supply conditions, and segment demand underscores the importance of integrated planning. Organizations that treat trade policy, raw material cycles, and application-specific procurement behavior as isolated concerns risk missing the compounding effects that shape total land-and-security economics. This research consolidates those variables into a single analytical environment, reducing the friction between market observation and strategic response.
Access the Full Strategic Assessment
The metal fencing market's trajectory through 2032 will reward organizations that combine disciplined market intelligence with agile execution. While this article outlines the strategic contours and decision frameworks embedded in our latest study, the complete research contains the detailed segmentation analysis, competitive intelligence, regulatory impact mapping, and scenario-based guidance necessary to operationalize these insights at the enterprise level. To access the full dataset, proprietary segmentations, and comprehensive company profiles that underpin this analysis, we invite you to explore the complete report through our official research portal.
For leaders preparing for 2026 planning cycles, the difference between reactive positioning and proactive strategy will depend on the depth and precision of the intelligence at hand. Our Metal Fencing Market research is designed to deliver exactly that foundation, enabling informed decisions grounded in rigorous analysis rather than generalized industry narratives.
For detailed analysis of this topic, please visit the official page: Metal Fencing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com