

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Diamond Wire Saw Market Hits $1.1B in 2025, Projected 5.2% CAGR Through 2032

Strategic Intelligence for the Next Cycle: Unpacking the Diamond Wire Saw Market Outlook
As industries accelerate toward higher precision manufacturing and sustainable material processing, the diamond wire saw market stands at a critical inflection point. For executives navigating capital allocation, supply chain optimization, and technology procurement in 2026, understanding the underlying demand architecture is no longer optional. This strategic briefing introduces our latest comprehensive market research, designed to translate macroeconomic trajectories, competitive positioning, and technological shifts into actionable intelligence for boardroom decision-making.
The sector has demonstrated remarkable resilience through recent volatility, and the forward trajectory suggests continued structural expansion. Our analysis frames the 2026 landscape as a decisive year where operational efficiency, material-grade advancements, and application-specific cutting architectures will separate market leaders from marginal participants. The following insights synthesize historical performance, near-term forecasts, and competitive dynamics to establish the strategic foundation for your next planning cycle.
Market Trajectory and Structural Fundamentals
Historical data reveals a market that has consistently expanded despite periodic demand disruptions and raw material price fluctuations. From a baseline of approximately 910 million USD in the early 2020s, the industry progressed through measured growth phases, crossing the 1.1 billion USD threshold by the mid-2020s. This progression reflects not merely cyclical recovery but a fundamental shift in how precision cutting technologies are integrated across high-value manufacturing pipelines.
The forecast horizon extending through 2032 maps a consistent upward trajectory, with a compound annual growth rate of 5.2 percent anchoring long-term planning assumptions. At this pace, the market is projected to approach the 1.6 billion USD mark by the end of the decade, underscoring sustained demand from both legacy industrial applications and emerging technology sectors. For strategic planners, this growth profile suggests that capacity investments, R&D allocation, and vendor partnerships must be evaluated against a steadily expanding addressable market rather than short-term demand spikes.
Several structural drivers reinforce this outlook. The ongoing transition toward higher-purity materials in electronics and renewable energy manufacturing requires cutting technologies that minimize subsurface damage, reduce kerf loss, and maintain consistency across high-volume production runs. Simultaneously, traditional sectors such as stone processing and construction materials continue to modernize equipment fleets, replacing abrasive or legacy mechanical methods with diamond wire architectures that deliver longer service life and lower operational friction. These overlapping demand currents create a diversified revenue base that buffers against single-sector downturns.
Segmentation Dynamics and Demand Architecture
The market's composition reflects a clear division between product architectures, application verticals, and geographic demand centers. Understanding which segments command premium positioning versus volume-driven scale is essential for pricing strategy, product roadmap development, and go-to-market execution.
Diamond Wire Saw Market
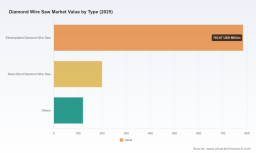
- Product Type Evolution. The market differentiates primarily between electroplated and resin-bonded diamond wire formulations, alongside specialized variants tailored for niche geometries or extreme hardness materials. Electroplated configurations continue to capture substantial share due to their suitability for high-precision slicing and consistent diamond exposure, particularly in environments where edge quality and repeatability dictate yield outcomes. Resin-bonded alternatives serve applications where flexibility, cost-efficiency, and moderate cutting force are acceptable trade-offs. The balance between these architectures shapes vendor portfolios and influences procurement decisions across industrial buyers.
- Application Verticals. Demand is anchored across semiconductor wafer manufacturing, photovoltaic cell cutting, stone and concrete processing, and optical glass fabrication. Each vertical carries distinct performance requirements. Semiconductor and photovoltaic applications prioritize micron-level precision, minimal thermal disruption, and compatibility with large-format ingots. Stone and concrete segments emphasize throughput, blade durability, and adaptability to variable material densities. Optical glass cutting demands surface integrity and scratch-free finishes to preserve optical performance. The interplay of these requirements determines which wire configurations and machine architectures gain traction in specific buyer communities.
- Regional Demand Patterns. Growth is distributed across multiple economic zones, with certain regions exhibiting stronger concentration in high-technology manufacturing and others maintaining robust industrial processing volumes. Supply chain localization, import dependencies, and regional certification requirements further shape procurement pathways. Buyers increasingly evaluate total cost of ownership, lead time reliability, and after-sales technical support alongside unit pricing, particularly as equipment downtime carries measurable production penalties in high-throughput environments.
Competitive Landscape and Strategic Positioning
The industry features a concentrated competitive structure, with the top three players accounting for approximately 65 percent of total market revenue and the top five firms representing around 82 percent. This concentration signals the presence of established technology platforms, strong customer linkages, and significant barriers to entry for newcomers lacking proprietary coating technologies or proven service networks. For buyers and investors alike, monitoring the strategic moves of incumbent players provides early signals of pricing behavior, innovation pacing, and potential consolidation pathways.
Well Diamond Saws SA, headquartered in Switzerland, has built its reputation over decades as a manufacturer of specialized diamond wire saw systems designed for hard and brittle materials. The company's emphasis on patented synthetic diamond wire coatings and low-heat cutting methodologies positions it within precision-oriented application segments where thermal damage and material stress must be minimized. Its global distribution footprint, encompassing thousands of deployed units, reflects long-standing acceptance among operators prioritizing process stability and surface quality.
Ensoll Tools Technology Co., Ltd., based in China, has developed a focused portfolio around endless diamond wire loops and integrated cutting machines. With a substantial patent portfolio and a one-stop solution approach, the company addresses industrial buyers seeking coordinated equipment and consumables architectures. Its operational standards, including ISO 9001 certification for production processes, highlight a commitment to manufacturing consistency that resonates with procurement teams managing quality assurance across multiple shift environments.
GTI Technologies, Inc., operating from the United States, serves as a supplier and distributor of Takatori diamond wire saws and related products. The company's focus on high-speed slicing for semiconductors, advanced materials, and quarrying applications underscores the value of multi-wire systems in throughput-intensive settings. By bridging specialized product lines with application expertise, the firm supports buyers who require fast cycle times while maintaining the integrity of delicate or high-value workpieces.
Recent industry activity reinforces the pace of product evolution. In mid-2025, JSEDM introduced diamond wire saw machines at a major semiconductor exhibition, unveiling multi-size compatible systems targeting 6-inch, 8-inch, and 12-inch ingot formats, with completion milestones set for mid-2026. This development signals growing emphasis on flexible machine architectures capable of accommodating varying wafer and ingot dimensions without complete line retooling. Alongside this, a major stone-processing equipment release highlighted the continued push toward high-speed diamond wire solutions in masonry and construction material applications, reflecting broader modernization trends in traditional industrial segments. Meanwhile, technology provider updates showcased over a decade of iterative innovation in diamond wire cutting, reinforcing the narrative that incremental improvements in coating durability, wire tension control, and machine ergonomics remain central to competitive differentiation.
Operational Dynamics and Investment Considerations
Beyond headline figures and vendor profiles, the operational environment introduces several variables that influence purchasing strategy and capital planning. Wire pricing and configuration choices, for instance, vary significantly by application intensity. Premium single-wire systems designed for semiconductor-grade precision typically command higher per-meter costs, while multi-wire configurations optimized for high-volume solar production operate at a lower unit price point due to economies of scale and different performance tolerances. Buyers must therefore evaluate not just the nominal equipment cost but the total cutting solution economics aligned with their throughput targets and yield requirements.
Technical specifications also shape implementation decisions. Standard wire lengths, diameter ranges, and speed limitations are calibrated to specific machine platforms and material profiles. Systems engineered to operate with minimal applied force and controlled wire velocities help prevent thermal buildup and preserve workpiece integrity, an especially relevant consideration for brittle or optically sensitive materials. These engineering parameters influence operator training, maintenance intervals, and consumable replacement cycles, all of which contribute to the effective cost of production over the equipment lifecycle.
From a strategic planning perspective, decision-makers should consider several interconnected factors when evaluating market participation or procurement timing:
- Alignment between wire technology selection and the dominant material formats in the production pipeline, including diameters, hardness profiles, and defect sensitivity.
- Assessment of machine flexibility to accommodate format transitions, particularly as wafer, ingot, and panel dimensions continue to evolve across semiconductor and photovoltaic lines.
- Supplier reliability indicators such as certification status, patent depth, service coverage, and historical uptime performance under continuous operation conditions.
- Sensitivity of total cost models to consumable pricing, replacement frequency, and the operational trade-offs between higher-precision single-wire setups and higher-throughput multi-wire configurations.
- Geographic and logistics considerations affecting lead times, spare parts availability, and regional support responsiveness.
These considerations do not operate in isolation. A procurement choice that reduces per-unit consumable expense may increase cycle time or require additional quality inspection overhead. Conversely, an investment in higher-precision equipment may yield downstream benefits in yield recovery and reduced rework. The optimal configuration depends on a disciplined evaluation of process constraints, volume expectations, and quality thresholds unique to each operational context.
Conclusion and Strategic Call to Action
The diamond wire saw market presents a compelling blend of steady structural growth, concentrated competitive dynamics, and continuous technological refinement. As manufacturing sectors demand higher precision, lower waste, and greater flexibility across material formats, the companies and procurement teams that act on rigorous, granular intelligence will secure a measurable advantage in both cost efficiency and process reliability. The broader market trajectory supports long-term planning, but the specific allocation of resources, the selection of equipment architectures, and the timing of vendor partnerships require insight that extends well beyond aggregate forecasts.
Our full market research publication provides the depth required to translate these dynamics into executable strategy. It delivers a comprehensive mapping of segmentation performance, regional demand behavior, competitive benchmarking, product-type economics, application-specific procurement drivers, and the operational variables that shape total cost of ownership across major industry verticals. The complete dataset, scenario frameworks, and strategic recommendations are structured to support capital planning, product portfolio decisions, and supply chain negotiations with confidence.
For leaders preparing for the 2026 decision cycle, the next step is to access the full research suite and integrate its detailed intelligence into your strategic planning process. The aggregate outlook is clear, but the precision of your execution will depend on the granularity of the data guiding your investments.
Worldwide Wire Saw Market
For detailed analysis of this topic, please visit the official page: Diamond Wire Saw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com