

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Tank Cleaning Service Market to Hit $14.44 Billion by 2032 with 6.5% CAGR finds PW Consulting

Strategic Intelligence for the Tank Cleaning Services Market: Navigating Growth, Compliance, and Consolidation Through 2032
The industrial tank cleaning services sector is undergoing a structural transformation driven by tightening environmental regulations, evolving automation capabilities, and a complex competitive landscape that rewards operational precision and strategic scale. As enterprises across energy, chemicals, and water management navigate shifting compliance mandates and cost pressures, the ability to anticipate market trajectories, evaluate competitor positioning, and align service delivery with operational risk frameworks has become a critical differentiator. Our latest research initiative delivers a comprehensive, decision-ready analysis of this industry, offering executives and strategy teams a clear roadmap for positioning within a market projected to expand from 9.28 billion USD in 2025 to 14.44 billion USD by 2032, sustained by a compound annual growth rate of 6.5 percent. This article outlines the analytical architecture of the study, highlights the strategic dimensions that will shape competitive outcomes, and demonstrates how the intelligence framework can be directly applied to enterprise planning, risk mitigation, and capital allocation decisions in the coming planning cycles.
Macro Trajectory and the Strategic Imperative for Forward-Looking Planning
Understanding the direction and velocity of market expansion is only the starting point for strategic positioning. The sector has demonstrated consistent, compounding growth across the historical window, moving from 6.9 billion USD in 2020 through a sequence of steady annual increases to reach 8.73 billion USD in 2024, before crossing the 9 billion threshold in 2025. The forward trajectory embedded in our base-case methodology indicates accelerated momentum as operational backlogs, regulatory modernization, and infrastructure renewal cycles converge. By 2026, the market is expected to reach 9.8 billion USD, with continued expansion leading to 11.03 billion USD in 2028 and approaching 13.13 billion USD by 2030. The terminal projection of 14.44 billion USD by 2032 underscores a durable growth avenue, provided that service providers and downstream operators can align their capacity planning, technology adoption, and compliance architectures with the pace of market maturation.
Underwater Hull Cleaning Service Market
For corporate strategists, this trajectory is not merely a numerical forecast. It represents a signal of expanding operational complexity. As gross output scales, the requirements for personnel safety protocols, hazardous residue management, environmental containment, and turnaround scheduling intensify. Executives evaluating market entry, service line diversification, or capacity investment must therefore base their decisions on a granular understanding of demand drivers, regional deployment patterns, and the economics of service delivery models. Our research isolates these variables within a structured analytical framework, enabling leaders to translate top-line market growth into actionable capacity planning, partnership strategy, and procurement positioning without relying on industry generalizations or unverified directional trends.
Scope, Structure, and Decision-Ready Analytical Depth
The report is engineered as a practical intelligence asset rather than a high-level market summary. It maps the full value chain of tank cleaning services, from field deployment and hazardous material handling to decontamination methodologies, sludge and residue recovery, waste stream routing, and post-cleaning verification. Each segment of the service lifecycle is evaluated through the lens of operational feasibility, labor intensity, equipment utilization, regulatory exposure, and margin dynamics, allowing clients to benchmark their internal service models against prevailing industry structures.
The analysis employs a multi-dimensional segmentation architecture that disaggregates market behavior across service type, application end-use, and geographic deployment. Rather than presenting isolated data points, the study examines how these segments interact: where labor-intensive approaches remain dominant, where mechanized and semi-mechanized solutions are gaining traction, which application verticals generate recurring demand cycles, and how regional market characteristics influence pricing architecture, contract structures, and service availability. This layered approach enables decision-makers to identify where value is created, where cost pressures accumulate, and which service configurations are best aligned with their operational footprint.
In addition to structural market analysis, the report delivers demand forecasting that integrates historical consumption patterns, projected industrial activity levels, and the anticipated impact of regulatory evolution. The forecasting methodology accounts for the cyclical nature of tank cleaning demand in energy and chemicals, the steady maintenance-driven requirements in water and wastewater operations, and the emerging growth signals from specialized industrial applications. By connecting demand forecasts to service capacity and compliance readiness, the study gives clients a practical tool for scenario planning, investment prioritization, and risk-adjusted resource allocation.
Competitive Positioning, M&A Activity, and the Shifting Value Chain
The competitive environment is characterized by a consolidated tier of established service providers operating alongside specialized regional players and technology-focused entrants. Industry concentration metrics indicate that the top three participants together command 46.8 percent of revenue, while the top five account for 58.2 percent, signaling a market where scale, geographic coverage, and specialized compliance capabilities confer meaningful competitive advantage. Yet concentration alone does not define competitive outcomes. Differentiation increasingly depends on service integration, turnaround execution reliability, safety performance, and the ability to manage complex contaminant profiles under stringent environmental and occupational health standards.
The company profiles included in the study examine a cross-section of active participants with distinct strategic postures. Firms with strong North American operational bases are evaluated for their field service capabilities, permitting and safety frameworks, and positioning across industrial verticals. Providers headquartered in Europe and the Middle East are assessed for their environmental service integration, waste handling networks, and capacity to serve multinational operator requirements. Participants with growing presence in Asia Pacific and broader emerging industrial corridors are analyzed for their scaling strategies, technology adoption paths, and ability to meet localized compliance expectations while competing on cost and responsiveness. Rather than offering static organizational summaries, the report links each company’s operational footprint to the segments where demand is most durable and the competitive pressures most acute.
A defining feature of the current market cycle is the acceleration of consolidation and capability expansion through merger activity and targeted service launches. Recent corporate developments illustrate how strategic players are reshaping their addressable market and strengthening their hazardous waste and treatment infrastructure. In mid-2025, a significant service modernization move expanded robotic crude oil tank cleaning capabilities, incorporating advanced robotic systems, online desludging technologies, and enhanced oil sludge recovery solutions. This type of capability investment signals a broader industry shift toward reducing manual entry exposure, improving turnaround efficiency, and capturing higher-value recovery streams from residual hydrocarbons.
On the consolidation front, a major European environmental services enterprise moved aggressively to expand its North American hazardous waste footprint through a multi-stage acquisition of a U.S. industrial waste specialist. After a definitive agreement was announced in late 2025, the transaction was completed in mid-2026 with a value of approximately 3 billion USD, nearly doubling the acquirer’s U.S. hazardous waste capacity and strengthening its capabilities across treatment, storage, disposal, and advanced contaminant management, including PFAS-related solutions. This transaction is strategically significant because it links tank cleaning and related industrial decontamination services to a broader integrated waste and treatment ecosystem. For competitors, it raises the bar on service integration, compliance breadth, and the ability to serve operators who increasingly prefer consolidated environmental management partners over fragmented service providers.
Regulatory Pressures, Safety Dynamics, and Operational Risk Architecture
Market growth cannot be evaluated in isolation from the regulatory and safety environment that governs tank cleaning operations. Occupational safety requirements and confined space entry protocols have become central determinants of cost structure, scheduling reliability, and reputational exposure. Supervisory responsibilities for safe work procedures, permit administration, personal protective equipment deployment, and exposure monitoring for hydrocarbon vapors, gases, and oxygen concentrations form the baseline for compliant operations. Where these controls are inconsistently applied, the consequences extend beyond immediate safety incidents to include enforcement actions, financial penalties, project delays, and contract-driven reputational damage.
Recent enforcement activity underscores the financial and operational stakes involved. In mid-2024, a major regulatory citation was issued following serious procedural failures during tank cleaning operations, including the absence of atmospheric testing inside a tank prior to entry. The resulting proposed penalty exceeded 800,000 USD and reflected repeated and serious violations under occupational safety regulations. This case is instructive for strategic planners because it highlights two reinforcing realities: first, compliance discipline is a direct line item in operational cost and risk exposure; second, safety failures can disrupt service schedules, impair client confidence, and create liability exposure that ripples across multi-year contracts and multi-site operations.
From a strategic perspective, these dynamics elevate the importance of integrated risk management within service delivery. Providers that invest in atmospheric monitoring protocols, standardized permit workflows, trained entry supervision, and systematic hazard evaluation are better positioned to protect margin integrity, reduce unplanned downtime, and differentiate themselves in competitive procurement processes. For operators procuring tank cleaning services, procurement strategy increasingly involves evaluating vendor safety records, regulatory readiness, and incident management architecture as core qualification criteria. The research captures these compliance and safety dimensions not as peripheral considerations but as structural inputs into demand behavior, pricing resilience, and competitive selection logic.
Labor Economics, Automation, and the Cost of Service Delivery
Labor cost dynamics continue to shape service economics and capacity planning. As skilled labor becomes more constrained and wage expectations rise, the viability of high-touch manual cleaning models depends on the efficient deployment of personnel, the predictability of turnaround windows, and the ability to minimize rework and re-entry cycles. At the same time, organizations are reassessing the balance between labor-intensive execution and mechanized assistance where site conditions, tank geometry, and contaminant profiles make automation feasible. This does not imply a wholesale substitution of manual services; rather, it points to a more nuanced deployment logic in which service type selection is driven by tank configuration, hazard classification, residue characteristics, turnaround urgency, and total delivered cost.
The shift toward more advanced cleaning approaches is reinforced by the desire to reduce human exposure in hazardous atmospheres, shorten non-productive time, and improve recovery efficiency from hydrocarbon sludge and other residual streams. Providers investing in robotic systems, specialized desludging equipment, and enhanced recovery workflows are building operational advantages in environments where safety requirements are stringent and turnaround schedules are compressed. Simultaneously, firms with strong field crews and mature procedural discipline continue to compete effectively in applications where flexibility, adaptability, and rapid mobilization remain decisive. The report evaluates these competing delivery models within a shared analytical framework so that clients can determine where automation investment yields durable returns and where traditional service execution remains economically rational.
Application Drivers and Vertical-Specific Demand Patterns
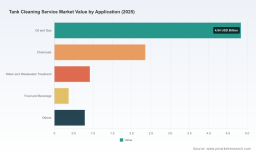
Tank cleaning demand is distributed across multiple industrial verticals, each with distinct operational rhythms, contaminant profiles, compliance expectations, and service cadence. The energy sector, particularly oil and gas, continues to anchor a substantial share of demand due to the scale of storage infrastructure, the complexity of hydrocarbon residues, and the need for scheduled maintenance, turnaround support, and sludge management. Chemical processing represents another core demand center, where cross-contamination prevention, vessel preparation, and hazardous residue handling require specialized procedures and rigorous verification. Water and wastewater treatment operations generate recurring cleaning requirements tied to infrastructure maintenance and process integrity, while food and beverage applications, though smaller in absolute scale, introduce stringent hygiene and material compliance considerations that affect service design and documentation.
The study maps these application dynamics to service demand intensity, contract frequency, and regional deployment patterns, allowing clients to identify where their service offerings align most naturally with underlying industrial activity. For companies seeking to diversify exposure or expand into adjacent verticals, the vertical-level analysis clarifies which applications demand higher procedural specialization, which generate more consistent recurring revenue, and which are more sensitive to production cycles, regulatory cycles, and capital expenditure timing. By connecting application behavior to service economics, the report supports targeted commercial strategy rather than broad-based market participation.
Geographic Deployment, Regional Nuances, and Strategic Allocation
Regional market behavior reflects differences in industrial density, regulatory maturity, operator preferences, and the existing base of service capacity. North American and European markets are shaped by well-established compliance frameworks, mature procurement practices, and a strong emphasis on safety performance and integrated environmental handling. Asia Pacific reflects a broader and faster-evolving industrial base, with growing infrastructure investment, expanding refining and chemical activity, and increasing adoption of specialized cleaning and waste handling services. Latin American and Middle East-Africa markets present distinct deployment considerations linked to project-driven demand, energy infrastructure activity, and the pace of regulatory formalization.
The research does not treat regional analysis as a static share table. Instead, it examines the operational implications of regional demand: how service models must adapt to local permitting environments, how mobilization and logistics influence cost competitiveness, and how multinational operators evaluate vendor consistency across jurisdictions. For enterprises planning capacity expansion, partnership development, or cross-border service standardization, this regional lens is essential for aligning investment decisions with realistic demand intensity and competitive conditions. The full segmentation detail is developed within the report to support granular strategic choices without oversimplifying regional complexity.
Tank Cleaning Service Market
Why This Research Matters for 2026 Strategic Decisions
The 2026 planning horizon places enterprise decision-makers at the intersection of market expansion, regulatory tightening, safety accountability, and competitive consolidation. In this environment, strategy teams need more than directional market narratives. They require a structured evidence base that connects market size evolution, demand drivers, service type economics, vertical-specific behavior, regional deployment logic, competitor positioning, and recent corporate developments into a coherent planning framework. The report is designed to serve that function. It provides the analytical scaffolding to support decisions about service line investment, geographic prioritization, procurement qualification standards, partnership and acquisition screening, and operational risk investment.
Equally important, the study is built to support scenario thinking. Because market growth trajectories, regulatory enforcement intensity, labor cost conditions, and consolidation activity can evolve in multiple directions, decision-makers benefit from an analysis that identifies which variables most influence outcome sensitivity and where strategic flexibility should be preserved. Whether the objective is to defend an existing service position, enter a new regional or vertical market, evaluate a vendor base, or assess the implications of competitor consolidation, the research is structured to translate market intelligence into executable strategic direction.
Positioning Your Organization Ahead of the Next Market Cycle
The tank cleaning services market is expanding within a framework of rising operational expectations. Growth is real, but so are the compliance, safety, labor, and competitive pressures that shape who captures value and how. Enterprises that ground their 2026 decisions in a rigorous understanding of demand drivers, service economics, regulatory exposure, and competitive structure will be better positioned to allocate capital efficiently, negotiate from an informed stance, and build service models that are resilient under changing conditions. For organizations seeking a comprehensive and decision-focused view of the industry, the complete research provides the segmentation depth, competitor context, regulatory analysis, and forward-looking intelligence necessary to move from market awareness to strategic action.
For detailed analysis of this topic, please visit the official page: Tank Cleaning Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com