

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 2025 Global Commercial Vehicle Market Hits $1.29 Trillion, CAGR 6.5% to 2032

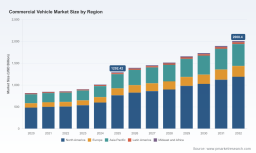
Charting the Commercial Vehicle Market Trajectory: Strategic Intelligence for 2026 Decision-Makers
The global commercial vehicle industry stands at a critical inflection point. As organizations navigate shifting regulatory frameworks, accelerated electrification timelines, and evolving logistics demands, the ability to anticipate market movements has transitioned from a competitive advantage to an operational necessity. Our latest Commercial Vehicle Market research delivers a comprehensive, data-driven foundation for enterprise strategy through the end of the decade and beyond. This report is engineered to translate macroeconomic trends into actionable intelligence, enabling executives, supply chain leaders, and investment teams to position their portfolios with precision.
Drawing on a rigorous analytical methodology, the study captures market performance from 2020 through 2025 and projects forward across a six-year forecast horizon. The narrative that follows is not merely a collection of figures. It is a structural examination of how demand vectors, technology adoption curves, and competitive consolidation patterns are reshaping the commercial mobility landscape. Readers will find a clear pathway to strategic clarity, while the full dataset and granular scenario models remain accessible through our complete research portal.
Macro Market Trajectory and Growth Foundations
The commercial vehicle sector has demonstrated remarkable resilience and expansion over the past half-decade. Between 2020 and 2025, the market expanded from approximately 815.3 billion USD to 1292.42 billion USD, reflecting a compound annual growth rate that underscores sustained enterprise investment in fleet modernization, infrastructure development, and cross-border trade optimization. This upward trajectory has accelerated into the current baseline year, positioning the industry at a scale that demands disciplined forecasting and scenario-aware planning.
Looking ahead, the forecast window through 2032 projects continued expansion, with the market anticipated to surpass the 2 trillion USD threshold by the close of the period. The overall growth profile carries a projected CAGR of 6.5 percent, signaling a steady but structurally evolving demand environment. This rate of expansion is not uniform across all vectors. It reflects diverging adoption cycles, regional policy maturity, and varying capital expenditure pacing among fleet operators. Understanding where growth concentrates, and where it lags, requires moving beyond headline numbers into the segmentation architecture that drives real-world procurement decisions.
For executives evaluating capital allocation, capacity planning, or market entry strategies, these macro indicators serve as the starting point rather than the destination. The report delves into how baseline growth interacts with regional policy shifts, supply chain constraints, and technology transition costs, offering a layered view that supports both short-term tactical adjustments and long-horizon strategic positioning.
Structural Demand Breakdown: Vehicle Categories, Applications, and Regional Channels
Commercial vehicle demand is fundamentally segmented by platform type, operational application, and geographic distribution channels. Each dimension carries distinct procurement cycles, regulatory exposure, and technologically induced cost structures. The report maps these dimensions to reveal where purchasing power is concentrating and how end-user priorities are shifting.
The vehicle type landscape spans light commercial platforms, heavy-duty trucks, and bus segments, each serving different operational envelopes and total-cost-of-ownership profiles. Application-driven demand further fragments the market across logistics and transportation networks, construction and infrastructure projects, agriculture and mining operations, public transit systems, and specialized use cases. Meanwhile, regional market distribution reflects varying degrees of industrial activity, trade corridor intensity, and policy-driven fleet transformation mandates.
Rather than presenting isolated percentages, the research synthesizes these segmentation layers into a cohesive demand framework. Executives will see how application growth rates interact with vehicle category preferences, how regional procurement patterns diverge based on economic structure and regulatory timelines, and where cross-segment opportunities emerge for manufacturers, component suppliers, and service providers. The full segmentation matrices, volume projections, and channel-specific revenue flows are available within the complete dataset, enabling precise portfolio alignment without exposure to fragmented or outdated proxies.
Competitive Landscape and Strategic Positioning
The commercial vehicle ecosystem is defined by a concentrated yet highly competitive group of multinational manufacturers, each pursuing distinct technology roadmaps and regional expansion strategies. Market concentration metrics indicate that the top three players command approximately 22.4 percent of industry revenue, while the top five extend their combined share to roughly 29.7 percent. This distribution suggests a market where scale matters, yet differentiation through powertrain innovation, commercial service networks, and regional customization remains a decisive competitive lever.
Worldwide Commercial Vehicle Leaf Spring Market
Several industry leaders anchor the competitive landscape. Daimler Truck AG operates a comprehensive portfolio spanning light, medium, and heavy-duty trucks as well as city and intercity buses under multiple brand umbrellas, reinforcing its global reach across diverse commercial applications. PACCAR Inc. maintains a strong presence through premium heavy-duty platforms and light commercial offerings, with a focus on engineering-driven performance and dealer-centric service models. Volvo Group continues to advance its truck division across long-haul, vocational, and urban use cases, with expanding electric model lineups targeting emissions-sensitive procurement cycles.
Traton SE leverages a multi-brand structure encompassing established truck platforms and emerging electric solutions, while Hyundai Motor Company has scaled its medium and heavy-duty commercial divisions alongside electric variants designed for regional and urban deployment. In parallel, Tata Motors Limited anchors commercial vehicle supply across trucks, buses, and electric platforms tailored to high-volume emerging market demand. Iveco Group N.V. provides light, medium, and heavy commercial applications across truck and bus categories, and CNH Industrial N.V. extends its footprint through agricultural and vocational equipment lines that intersect with commercial mobility needs. BYD Auto Co., Ltd. has also become increasingly relevant through its commercial truck and bus offerings, particularly where electric and hybrid platforms align with urban fleet transitions.
The report assesses these players not merely by product breadth, but by strategic posture: electrification investment pacing, regional manufacturing footprints, after-sales service capacity, and responsiveness to regulatory timelines. Competitive benchmarking within the study highlights where scale advantages translate into pricing power, where technology differentiation creates premium positioning, and where consolidation or partnership activity may reshape market shares over the forecast period.
Commercial Vehicle Market
Regulatory Acceleration and Technology Transition Dynamics
Regulatory pressure has become one of the most defining forces shaping commercial vehicle procurement cycles. In the United States, the EPA 2027 heavy-duty vehicle emissions standards mandate an approximate 80 percent reduction in NOx emissions compared to current levels. This requirement pushes manufacturers and fleet buyers toward advanced after-treatment architectures and hybrid or electric powertrains, effectively compressing the timeline for compliance-related product transitions. These standards are not confined to one jurisdiction; they interact with broader international commitments and regional mandates that collectively raise the cost of inaction.
At the global level, the Global Memorandum of Understanding on Zero-Emission Medium- and Heavy-Duty Vehicles commits signatories to achieving 30 percent net-zero tailpipe emission sales by 2030. This target aligns with U.S. objectives calling for 30 percent zero-emission medium- and heavy-duty vehicle sales by 2030 and a full transition toward 100 percent by 2040. Such commitments create a policy scaffold that influences procurement planning, infrastructure investment, and total-cost-of-ownership modeling across multiple markets simultaneously.
In California, the Advanced Clean Trucks rule intensifies this trajectory by requiring a defined percentage of new commercial vehicle sales to be zero-emission, with non-compliant vehicles facing prohibition by 2035. Together, these regulatory developments form a cascading compliance environment where OEMs and fleet operators must anticipate product availability, charging or fueling infrastructure readiness, and operational range requirements well in advance of mandate deadlines.
The research evaluates these regulatory layers as strategic variables rather than background noise. It maps the cost and timing implications of emissions compliance, examines how electrification adoption curves interact with fleet renewal cycles, and identifies where policy momentum creates both risk exposure and first-mover opportunity for organizations that prepare early.
Operational Intelligence Embedded in the Report
Beyond macro forecasting and competitive profiling, the study is built to support operational decision-making. It integrates procurement-relevant analysis that helps procurement teams, engineering leaders, and commercial strategy teams align purchasing roadmaps with market realities. The report includes detailed assessment frameworks that evaluate demand sensitivity to fuel and energy pricing, the impact of emissions compliance on vehicle total cost of ownership, and the interplay between infrastructure readiness and fleet electrification timing.
Strategic scenario planning is another core component. Readers gain access to forward-looking models that connect regulatory milestones, technology availability, and regional demand shifts to potential market outcomes. These scenarios are designed to test resilience across multiple operating conditions, enabling organizations to stress-test supply commitments, aftermarket service planning, and regional expansion decisions. The study also covers aftermarket and service-network implications, recognizing that commercial vehicle value creation increasingly depends on uptime assurance, component lifecycle management, and digital fleet monitoring capabilities.
By combining quantitative forecasting with qualitative industry assessment, the report delivers a practical toolset for executive planning. It is structured to answer the questions that matter most to commercial vehicle stakeholders: where demand is likely to strengthen, which technology pathways are gaining procurement traction, how competitive dynamics may shift pricing and availability, and what strategic responses will preserve margin and market position through the end of the forecast horizon.
How This Research Supports 2026 Decision-Making
Entering 2026, commercial vehicle organizations face a decision environment defined by simultaneous disruption and opportunity. Regulatory deadlines are approaching faster than many fleet renewal cycles. Electrification technologies are advancing, but adoption remains uneven across applications and regions. Supply chain constraints, labor dynamics, and infrastructure readiness continue to influence procurement timing and cost structures. In this context, decisions made in the near term will determine competitiveness over the balance of the decade.
This research is designed to reduce uncertainty in that decision process. It provides a unified view of market size evolution, segmentation behavior, and competitive positioning, grounded in a transparent analytical structure. Executives can use the findings to prioritize investment across vehicle platforms, align regional strategies with demand maturity, and anticipate the strategic implications of zero-emission mandates before they become binding constraints. The report also supports investor and board-level discussions by clarifying growth drivers, concentration risks, and the strategic value of technology differentiation in a market where top players hold meaningful but not dominant share.
Importantly, the study is intended as an entry point to deeper intelligence. The narrative presented here highlights the analytical framework, strategic themes, and macroeconomic direction that shape the commercial vehicle sector. The complete research package extends this foundation with segmented projections, detailed company assessments, regional demand breakdowns, and scenario-based modeling that enable precise operational planning. Organizations seeking to convert market intelligence into execution-ready strategy can access the full dataset and supporting analysis through our comprehensive market research portal, where the complete Commercial Vehicle Market report awaits.
For leaders tasked with navigating the next phase of commercial mobility, the value of rigorous, forward-looking research is clear. The market will continue to expand, but the distribution of that growth will reward organizations that plan with precision, anticipate regulatory and technological shifts early, and ground their strategies in robust market evidence. This report provides that evidence base and the strategic lens needed to act on it.
For detailed analysis of this topic, please visit the official page: Commercial Vehicle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com