

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Aerospace Materials Market Hits $32B in 2025, Projects 8.2% CAGR Through 2032

Aerospace Materials Market 2026: Strategic Intelligence for Enterprise Decision-Making
The aerospace materials sector stands at a critical inflection point as the industry navigates a transformative decade defined by evolving aircraft architectures, stringent sustainability mandates, and shifting geopolitical supply chains. For executives, investors, and operational leaders, the difference between reactive positioning and proactive strategy lies in the quality of market intelligence. Our latest Aerospace Materials Market research study delivers precisely that: a comprehensive, data-driven framework designed to inform high-stakes decisions throughout 2026 and the extended forecast horizon through 2032.
This report is not merely an aggregation of historical figures. It is a strategic navigation tool built to decode complexity, quantify opportunity, and expose the operational realities shaping material selection, capacity planning, and competitive positioning across the global aerospace value chain. Below, we outline the analytical architecture of the study, the market dynamics it captures, and why these insights carry immediate relevance for enterprise strategy in 2026.
The Macro Trajectory: What the Top-Line Data Reveals
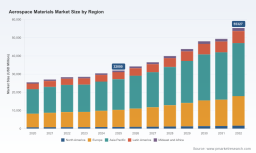
The overall market has exhibited persistent, compounding growth across the historical observation window spanning 2020 through 2025. Revenue expanded from approximately 25,504 million USD in 2020 to a baseline of 32,000 million USD by 2025. This trajectory reflects a sector resilient to cyclical aircraft delivery fluctuations, propelled instead by long-term fleet renewal programs, weight-reduction imperatives, and the gradual penetration of advanced composites into primary structural applications.
Looking forward, the forecast period from 2026 through 2032 projects continued expansion at a compound annual growth rate of 8.2 percent. Under this growth profile, market revenue is positioned to surpass 34,200 million USD in 2026 and climb toward the mid-55,000 million USD range by the close of the forecast window in 2032. These macro projections serve as the analytical backbone of the report, but they are never presented in isolation. Instead, they are contextualized against the operational realities, regulatory shifts, and competitive maneuvers that will determine which organizations capture disproportionate value as the market matures.
Decoding the Competitive Landscape
Market concentration remains a defining characteristic of the sector. The three largest players command a combined share of approximately 45.5 percent, while the top five firms collectively account for 52.8 percent of total revenue. This concentration signals a market where scale, certification depth, and long-term supplier relationships confer durable advantages, yet it also leaves meaningful room for specialized innovators, regional entrants, and vertically integrated material producers to compete on performance, cost, or technology differentiation.
The report profiles the core competitive set with granular attention to their aerospace-specific offerings and strategic positioning. Leading global suppliers of carbon fiber, prepregs, honeycomb cores, resins, and advanced composites certified for commercial aerospace primary and secondary structures anchor the upper tier of the market. Parallel to these established composites specialists, major international manufacturers have been scaling aerospace-grade carbon fiber, prepreg, and composite material production to support next-generation aircraft programs. Japanese producers contribute high-performance thermoplastics and advanced fabric architectures tailored to demanding aerospace applications. European carbon fiber reinforcement and prepreg suppliers maintain strong integration with continental aerospace and industrial ecosystems. Meanwhile, multinational specialty chemical and materials groups are intensifying development of thermoplastic composites, engineered resins, and specialty polymers designed for both structural and interior aerospace applications.
These profiles are not static descriptions. Each company assessment is framed around competitive moats, supply chain dependencies, certification status, and the strategic implications of their recent operational moves. This approach enables readers to map competitor intentions, anticipate supply-side disruptions, and identify partnership, sourcing, or investment opportunities that align with their own strategic objectives.
Recent Developments That Redefine Competitive Benchmarks
The pace of technological and commercial activity across the competitive set has accelerated markedly in recent months, and the report integrates these developments as actionable intelligence rather than isolated news items. In October 2025, a major Japanese materials producer introduced an advanced braided fabric architecture designed for lightweight aircraft structures, emphasizing improved mechanical performance and faster manufacturing throughput. Such launches signal a clear industry direction: the convergence of material performance gains with production efficiency improvements that directly impact aircraft program economics.
Aerospace Materials Market
During the Paris Air Show in May 2025, a leading composites supplier showcased new lightweight aerospace composite technologies alongside automated manufacturing systems and fuel-efficient structural concepts. Trade show activity of this caliber reflects both technological ambition and the increasing importance of demonstrating manufacturability at scale. In September 2025, an advanced materials company secured FAA-sponsored National Center for Advanced Materials Performance qualification for a next-generation epoxy resin system, reinforcing the critical role of certification milestones in accelerating material adoption. By November 2025, another specialist firm achieved full commercial availability of high-performance thermoplastic granules and powders, expanding the material toolkit for aerospace applications that demand recyclability, toughness, or simplified processing.
Capacity expansion remains equally pivotal. In December 2025, a major chemical group announced plans to expand carbon fiber production capacity across Japan and the United States to meet rising demand from commercial aviation and next-generation programs. These combined movements illustrate a market where product innovation, certification progress, and capacity builds are tightly interlocked, and where timing, geography, and regulatory alignment increasingly determine competitive outcomes.
Regulatory and Raw Material Dynamics Shaping 2026
Material costs, trade policy, and environmental compliance now exert direct influence on procurement strategy, program pricing, and supplier selection. The report treats these dynamics as first-order variables rather than peripheral context. PAN-based carbon fiber precursor prices rose approximately 3 percent in the first quarter of 2026, driven by acrylonitrile feedstock increases and logistics disruptions. Acrylonitrile upstream costs themselves climbed 2 to 3 percent in early 2026 as a result of maintenance outages and supply tightness across Asian production basins. These cost pressures ripple through composite value chains, influencing resin formulation decisions, alternate material evaluations, and negotiated pricing structures with airframe and engine manufacturers.
On the regulatory front, US tariffs on PAN-based carbon fiber imports took effect in 2025, altering cost structures for producers and raising compliance burdens for aerospace material suppliers navigating cross-border trade. At the same time, stricter environmental regulations governing graphite fiber production in developed markets, including the United States, Japan, and China, have tightened manufacturing permits and increased the operational cost of maintaining compliant output. These constraints are reshaping regional sourcing logic and encouraging dual-sourcing, regionalized production, and material substitution assessments.
Aerospace Sealants Market
Regulatory evolution is not uniformly restrictive. FAA Advisory Circular 33.15-3, issued in 2025, streamlined certification processes for established aerospace alloys and composites. For organizations with mature qualification portfolios, this development can shorten time-to-market for incremental design updates and reduce certification overhead. For newer entrants or novel material systems, the same landscape requires careful navigation of qualification pathways. The report captures these trade-offs explicitly so that readers can assess how certification strategy interacts with product roadmap decisions, supplier evaluation criteria, and regional market entry plans.
What the Study Delivers: Practical Analytical Modules
The research is structured to convert market complexity into usable decision frameworks. It combines macro market sizing with forward-looking modeling, segmentation analysis that isolates demand drivers by type and application, regional comparisons that highlight shifting center-of-gravity dynamics, and competitive intelligence that maps company strategies against market structure. Crucially, the report does not present segmentation data as static slices. It contextualizes each split against the underlying drivers, restraint factors, and adoption cycles that explain why certain material categories and application segments command disproportionate growth or resilience.
Readers gain access to structured evaluations covering material performance trends, certification and qualification pathways, supply chain sensitivities, and the strategic implications of raw material cost volatility. The study also examines how regional manufacturing capabilities, trade policy exposure, and environmental compliance requirements influence sourcing strategies and capacity planning. Each analytical module is designed to support concrete outcomes: refining procurement roadmaps, prioritizing material development investments, assessing market entry or expansion scenarios, and benchmarking internal performance against the operational rhythms of leading competitors.
Why This Research Matters for 2026 Decision-Making
Enterprise decisions in aerospace materials are increasingly interdependent. Procurement choices intersect with certification timelines. Capacity commitments must account for trade policy and feedstock volatility. Product roadmaps need to align with automated manufacturing expectations and evolving environmental regulations. In this environment, organizations that rely on fragmented intelligence or backward-looking benchmarks risk misallocating capital, misreading competitor intent, or underestimating the operational friction embedded in material transitions.
This study provides a consolidated view that connects market growth expectations with the structural forces shaping them. It enables leadership teams to evaluate where differentiation is achievable, where scale and certification confer protection, and where disruption is most likely to emerge from new material systems, regional capacity builds, or regulatory realignments. By integrating the top-line growth profile, concentration dynamics, competitive moves, and cost and compliance pressures into a single analytical narrative, the report equips decision-makers to act with greater confidence and precision throughout 2026 and beyond.
The Full Intelligence Landscape Awaits
The aerospace materials market is expanding, but its value is not distributed evenly across participants, regions, applications, or material categories. Understanding where growth concentrates, which competitive advantages are durable, and how regulatory and raw material shifts alter the playing field requires the depth and structure included in the complete study.
This preview offers a strategic overview of the macro trajectory, competitive architecture, and market dynamics that define the sector today. The full report extends far beyond this introduction, delivering the detailed segmentation context, regional analysis, company-level competitive assessments, supply-side sensitivity evaluations, and forward-looking scenario frameworks that enterprise teams need to translate market intelligence into actionable strategy. For leaders seeking to align investment, sourcing, and innovation decisions with the most current and comprehensive market picture available, the complete study provides the analytical foundation required to move decisively in 2026 and across the forecast horizon.
For detailed analysis of this topic, please visit the official page: Aerospace Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com