

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Infrared Lens Market Hits $192.35M in 2025, Projected to Reach $315.68M by 2032 at 7.52% CAGR
By pmarketresearch, 2026-09-15
Navigating the Infrared Lens Market: Strategic Intelligence for the 2026 Decision Cycle
The infrared (IR) lens market is undergoing a period of structural transformation. Between 2020 and 2025, global revenue expanded from approximately 138.45 million USD to 192.35 million USD, reflecting a steady compound annual growth trajectory that analysts project will sustain a 7.52 percent CAGR through 2032. By the end of the forecast window, the market is expected to surpass 315.68 million USD. These figures, drawn from PW Consulting’s latest infrared lens market research, are more than historical markers. They signal a maturing supply chain, shifting material dependencies, and an intensifying competitive landscape that demands precise, forward-looking strategy.
For executives, procurement leaders, and R&D directors operating in 2026, the question is no longer whether infrared optics will continue to expand, but how to position organizations within a market defined by material scarcity, geopolitical realignment, and rapid product iteration. This article outlines the strategic architecture of our newly released market study, explains why its analytical framework is built for immediate enterprise decision-making, and previews the competitive and operational dynamics that will shape capital allocation, sourcing strategy, and product roadmaps over the next six years.
Why 2026 Demands a More Granular Market Lens
The 2025-to-2026 inflection point is particularly consequential. Forecast data places 2026 revenue at 208.75 million USD, with incremental growth accelerating through 2027 and 2028 before settling into a more measured climb toward 2032. This trajectory masks underlying volatility. Two structural forces are reshaping how infrared optics are sourced, designed, and deployed: raw material supply constraints and regulatory-driven sourcing requirements.
Germanium supply chain disruptions have already translated into extended lead times and pricing adjustments across the IR optics sector. At the same time, export controls on critical materials originating from China have introduced new risk vectors for defense, industrial, and automotive manufacturers. In response, domestic production of alternative materials, including chalcogenide glass, has gained momentum in the United States, creating a parallel supply pathway that reduces reliance on constrained import channels. These dynamics are not peripheral. They directly affect cost structures, time-to-market, and contractual flexibility.
Meanwhile, procurement standards tied to U.S. defense programs increasingly require NDAA-compliant domestic sourcing for infrared lens assemblies. Organizations that have built their supply chains around legacy international suppliers are now confronting compliance gaps that can delay program execution or disqualify bids entirely. The intersection of material scarcity, regulatory compliance, and domestic capacity expansion means that 2026 purchasing and engineering decisions must be informed by more than unit pricing. They require a comprehensive view of supplier resilience, material substitution pathways, and regional production footprints.
Our infrared lens market research is structured to translate these macro-level pressures into actionable intelligence. Rather than presenting static market snapshots, the study maps how supply chain architecture, material innovation, and regulatory frameworks are interacting to redefine competitive advantage.
What the Research Delivers: Operational Intelligence Over Headline Figures
A market study earns its place in the executive workflow when it bridges high-level trends with executable insights. PW Consulting’s infrared lens market report is built around that principle. The analysis begins with historical performance from 2020 through 2025 and extends into a forecast period running from 2026 to 2032, allowing decision-makers to evaluate both retrospective momentum and forward exposure. All figures are denominated in USD and measured in millions, providing a consistent baseline for financial modeling and scenario planning.
Beyond aggregate revenue and CAGR, the report dissects the market across three operational dimensions: type, application, and region. The type breakdown examines the relative positioning of germanium, silicon, and other materials, highlighting how performance requirements and cost constraints are influencing material adoption. The application analysis isolates demand drivers across thermal imaging, night vision, and other use cases, revealing where volume growth is being generated and which segments are experiencing the most intense pricing or specification pressure. The regional assessment maps revenue distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing context for where production capacity, end-user demand, and regulatory environments are converging.
Critically, none of these breakdowns are presented as static percentages or isolated figures. Each segmentation layer is evaluated against supply-side constraints, technological substitution trends, and end-market procurement behavior. This approach ensures that readers understand not just where revenue is concentrated, but why it is concentrated there, what could disrupt that concentration, and how to build strategy around both continuity and change.
Infrared Lens (IR Lens) Market
The report also integrates a competitive landscape assessment that goes beyond company profiles. It evaluates how vertically integrated manufacturers, specialty material producers, and subsystem integrators are positioning themselves across defense, surveillance, automotive, medical, and industrial applications. The analysis considers product portfolio breadth, material strategy, geographic manufacturing presence, and recent commercial activity, allowing readers to benchmark their own capabilities against the firms that are actively shaping market direction.
Competitive Positioning and the 2026 Vendor Landscape
The infrared lens market is characterized by a moderately concentrated competitive structure. CR3 concentration sits at 41.2 percent, while CR5 reaches 58.5 percent, indicating that a relatively small group of established players commands a substantial share of revenue, but that meaningful opportunity remains for specialized and regionally focused manufacturers. The companies that dominate this landscape do so through different strategic levers: vertical integration, material science differentiation, application-specific engineering, and defense-oriented compliance readiness.
LightPath Technologies continues to emphasize vertically integrated production of custom IR lenses and assemblies, with a particular focus on germanium alternatives and mid- to long-wave infrared solutions for defense, surveillance, and thermal imaging. Its strategy reflects a broader industry tilt toward reducing exposure to constrained raw material channels while maintaining performance standards required by high-stakes applications. Umicore has built its presence on high-performance LWIR lenses using proprietary germanium and GASIR chalcogenide glasses, supplying both raw materials and finished assemblies across automotive, medical, and security markets. The company’s integration across material production and assembly illustrates how controlling the upstream supply chain can compress costs and improve delivery reliability.
Tamron has positioned itself around precision optics for uncooled IR lenses, targeting automotive, surveillance, and security applications where volume production and consistency matter as much as optical performance. Ophir Optronics Solutions remains focused on precision IR optics, including continuous zoom lenses spanning MWIR, SWIR, and LWIR bands for defense, security, and industrial use. Its recent product catalog release in 2026 underscores an ongoing push to expand specification flexibility for systems integrators who need adaptive optical configurations. Beijing Lenstech and Kunming Full-wave Infrared Technology represent the growing capability base in China, developing precision IR lenses and uncooled components for thermal imaging and industrial applications, with a notable orientation toward military and civilian thermal systems.
On the defense and high-performance subsystem side, Raytheon and Teledyne FLIR illustrate how EO/IR integration is becoming a strategic differentiator. Raytheon supplies lens assemblies and sub-systems for missile seekers, infrared search and track, and space applications, where performance tolerances and reliability requirements are exceptionally demanding. Teledyne FLIR operates as an OEM provider of custom MWIR/LWIR assemblies and continuous zoom lenses for thermal imaging across defense, automotive, and uncrewed systems, and its 2026 announcement of a new LWIR camera module designed for high-volume production highlights the market’s shift toward scalable, supply-continuous architectures. Edmund Optics and Resolve Optics round out the landscape by serving both stock and custom demand across germanium, zinc selenide, sapphire, silicon, and other substrates, supporting thermal imaging, spectroscopy, CO2 laser, and broader industrial applications.
These profiles are not presented in isolation. The research situates each company within broader supply chain dynamics, material substitution pathways, and application-specific procurement behavior, allowing readers to assess which vendors are best positioned to support particular program requirements, sourcing strategies, or partnership models.
Infrared Detector Market
Recent Developments That Are Reshaping Sourcing and Design Decisions
The market’s direction is being influenced not only by long-term forecasts but by recent product and technology milestones. In early 2026, Flinders University published work on a repairable polymer-based infrared lens using sulfur and organic co-monomers as a sustainable germanium alternative for thermal imaging. While still reflective of academic and applied research momentum, this development signals a continuing interest in material substitution that could, over time, alter cost structures and supply dependencies for specific thermal imaging applications.
At the same time, commercial product activity is accelerating. Ophir Optronics Solutions released its 2026 IR optics catalog, introducing new SWIR and MWIR zoom lenses that expand specification options for systems requiring adaptive field-of-view and resolution profiles. Teledyne FLIR OEM followed with an announcement of a new LWIR camera module optimized for high-volume production and supply continuity, a move that speaks directly to the manufacturing and procurement priorities of organizations seeking predictable availability and scalable integration.
These developments matter because they illustrate the market’s dual trajectory: one thread focused on material innovation and sustainability, another on production scalability and supply assurance. For enterprise planners, the implication is that sourcing strategies cannot be static. Material alternatives, catalog-level specification expansion, and module-level production design are all becoming relevant variables in procurement, product architecture, and risk management decisions.
Strategic Takeaways for the 2026 Decision Cycle
The infrared lens market is expanding, but expansion alone does not guarantee strategic advantage. The firms that will navigate 2026 successfully are those that treat market growth as a backdrop against which sourcing resilience, material strategy, and compliance readiness must be actively managed. Several implications emerge clearly from the current landscape.
- Supply chain diversification is no longer optional. Germanium constraints and export control risks are reshaping lead times, pricing, and program feasibility. Organizations need visibility into alternative material pathways, domestic production capacity, and supplier-level compliance posture.
- Material substitution is moving from research interest to commercial consideration. Chalcogenide glass production and polymer-based lens research are expanding the set of options available for specific thermal imaging and industrial applications. Decision-makers should evaluate where substitution is technically viable, economically justified, and supply-secure.
- Compliance and sourcing origin are becoming competitive requirements. NDAA-aligned domestic sourcing expectations are influencing procurement eligibility for U.S. defense programs. Vendor selection must now account for regulatory alignment as well as optical performance and cost.
- Vertical integration and scalable module design are emerging as differentiators. Companies that control raw material and assembly processes, or that engineer for high-volume production continuity, are better positioned to manage cost and availability pressure across demanding application cycles.
- Competitive concentration creates both risk and opportunity. With CR3 at 41.2 percent and CR5 at 58.5 percent, a small group of players exercises substantial market influence, yet segmentation across materials, applications, and regions leaves room for specialized positioning and targeted partnerships.
These takeaways are not abstract. They directly inform capital planning, supplier qualification, R&D prioritization, and regional sourcing strategy. The full market research study translates each of these themes into structured analysis, enabling organizations to benchmark their exposure, identify vulnerabilities, and prioritize the moves that will matter most over the 2026-to-2032 horizon.
Access the Full Intelligence: Why the Complete Report Matters
The outline above provides the strategic frame, but the detailed segmentation values, competitor positioning matrices, application-level demand drivers, regional revenue distribution, and supply-chain risk mappings are essential for precise decision-making. Those elements are intentionally withheld from this preview so that readers can assess the depth of the full study before committing to the complete dataset and analysis.
The complete infrared lens market research offers a consolidated view of historical performance, forecast trajectory, segmentation dynamics, competitive profiles, recent product and technology developments, and the operational implications of material and regulatory shifts. It is designed for teams that need to align procurement, engineering, and strategy around a single, coherent market picture rather than fragmented data points.
For organizations planning 2026 sourcing strategies, evaluating vendor partnerships, or shaping product roadmaps for thermal imaging, night vision, and adjacent infrared applications, the full report provides the granularity required to move from directional awareness to executable strategy. The market is growing, the competitive structure is evolving, and the firms that act on detailed intelligence will be best positioned to capture value while managing the supply, compliance, and material risks that define this phase of the infrared lens market.
For detailed analysis of this topic, please visit the official page: Infrared Lens (IR Lens) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Paint Protection Film Market Report: $655.5M in 2025, 6.4% CAGR to $1.01B by 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave of Growth: Strategic Insights into the Paint Protection Film Market
The global automotive aftermarket and surface protection industries are undergoing a phase of rapid evolution, driven by heightened consumer awareness of asset preservation, advancements in polymer technology, and a recovering global vehicle production landscape. As businesses look toward 2026 and beyond, the Paint Protection Film (PPF) market stands out as a critical arena for strategic investment and operational adjustment. PW Consulting's latest in-depth market research offers a comprehensive roadmap for stakeholders aiming to capitalize on the projected expansion of this sector.
This analysis serves as an introduction to the broader strategic intelligence contained within our full report. By examining historical trajectories, growth vectors, and competitive dynamics, we highlight the necessity of precise data-driven decision-making in a market characterized by both robust demand and intricate manufacturing complexities.
Market Trajectory and Financial Outlook
Understanding the macroeconomic flow of the Paint Protection Film industry is the first step toward building a resilient business strategy. Our research tracks revenue trends from 2020 through the base year of 2025, providing a solid foundation for forecasting the period from 2026 to 2032. The market has demonstrated consistent resilience, recovering from global supply chain disruptions to establish a steady upward climb in valuation.
TPU Type Paint Protection Film Market
In 2020, the global market began its recovery phase with a valuation reflecting the initial post-pandemic adjustments. Over the subsequent five years, the industry has consolidated its growth, reaching a significant market size by 2025. Looking forward, the momentum is expected to accelerate. The forecast period indicates a compound annual growth rate (CAGR) that suggests sustained expansion rather than speculative spikes. This growth is underpinned by increasing vehicle ownership in emerging markets and the rising adoption of protective films in high-value automotive segments across developed regions.
Strategic planners must note that while the top-line figures indicate healthy growth, the underlying drivers vary significantly by product type and application vertical. The transition from basic protection to premium, self-healing solutions represents a shift in value capture within the supply chain. Our report dissects these value pools without exposing sensitive segmentation data in this summary, ensuring that the full analysis remains a proprietary asset for our clients.
Technology and Material Dynamics
The core of the PPF market lies in material science. The industry has moved beyond simple adhesive films to sophisticated polyurethane-based solutions that offer self-healing properties, hydrophobicity, and exceptional clarity. According to industry market data, polyurethane base films maintain a dominant share in global Paint Protection Film production. This dominance is driven by the material's ability to recover from minor abrasions, thereby extending the aesthetic life of vehicle paint.
Furthermore, TPU films are increasingly recognized as the primary raw material for advanced self-healing and hydrophobic Paint Protection Film. Manufacturers investing in aliphatic TPU technologies are positioning themselves to capture the premium segment of the market, where performance and longevity justify higher price points. The interplay between raw material costs, technological capabilities, and end-user demand creates a complex landscape that requires careful navigation.
Our research details the technical specifications and manufacturing capabilities required to compete at the highest levels. From the USA-based production of aliphatic TPU films to the high-volume manufacturing hubs in Asia, the supply chain is becoming increasingly specialized. Understanding these technological nuances is critical for companies deciding whether to vertically integrate, partner with film manufacturers, or focus solely on distribution and installation.
Key Technical Trends Influencing Strategy
- Self-Healing Capabilities: The demand for films that can recover from stone chips and scratches without visible damage is reshaping product development roadmaps.
- Hydrophobic and Oleophobic Coatings: Enhanced surface energy properties are becoming a key differentiator, reducing maintenance costs for end-users and adding value to installation services.
- Finish Variety: While high gloss remains standard, there is a growing niche for matte and satin finishes, catering to customized automotive aesthetics.
- Installation Efficiency: Pressure-sensitive adhesives and dry-install technologies are being refined to reduce installation time and waste, impacting service center throughput.
Competitive Landscape and Market Concentration
The Paint Protection Film market is characterized by a mix of established multinational corporations and specialized niche manufacturers. Market concentration data indicates a moderately consolidated environment, where a significant portion of revenue is held by key players who have secured strong distribution networks and brand recognition. The CR3 and CR5 metrics highlight the influence of top-tier competitors, yet there remains ample room for innovation-driven entrants.
Geographic diversity in headquarters does not necessarily dictate market reach. Many leading manufacturers based in the United States maintain a global footprint, while powerful manufacturing capacities located in China supply a vast portion of the global demand. This dynamic creates a competitive tension between localized manufacturing benefits, such as faster logistics for North American installers, and cost-effective production scales available in other regions.
Profile of Market Leaders
Our report provides detailed profiles of the entities shaping the industry. These companies are not merely selling film; they are selling comprehensive protection ecosystems.
- LEGEND PPF: With a focus on North American installers, this company manufactures aliphatic TPU-based Paint Protection Film in the USA, emphasizing supply chain localization and support for regional installation networks.
- XPEL Inc.: Known for self-healing Paint Protection Film products, XPEL designs solutions specifically to protect against rock chips, scratches, and scuffs, maintaining a strong brand identity around durability and aesthetic preservation.
- 3M Company: Leveraging its vast industrial portfolio, 3M produces Scotchgard Pro Series Paint Protection Film lines, integrating PPF into a broader suite of automotive protection offerings.
- STEK USA: This manufacturer focuses on hydrophobic and self-healing Paint Protection Film with extreme clarity and depth, offering multiple finishes to cater to diverse consumer preferences.
- UPPF-USA: As a pioneer in advanced Paint Protection Film technology, UPPF-USA maintains control over every product line with in-house manufacturing, a legacy dating back to 1996.
- Pure PPF: Leading the market in bespoke premium colored and clear Paint Protection Film, this company targets the high-end customization segment where personalization is paramount.
- Ceramic Pro: Representing the next evolution in automotive surface protection and durability, Ceramic Pro combines film technology with coating systems to offer comprehensive surface solutions.
- LLumar Films: Their Platinum Paint Protection Film line is often combined with window tinting and ceramic coatings, creating bundled value propositions for installers and consumers.
- TeckWrap International: Specializing in pressure-sensitive adhesive Paint Protection Film, TeckWrap integrates PPF as part of broader automotive film offerings, recently demonstrating dry-install Color Paint Protection Film technology.
- ORAFOL Europe GmbH: Based in Germany, ORAFOL presents an advanced Paint Protection Film range available in high gloss or matte finishes with unmatched clarity, serving the European and global markets.
- Kehui: Located in Shanghai, Kehui positions itself as a global leader in Paint Protection Film manufacturing with a focus on automotive-grade TPU films.
- Sino Vinyl: Based in Guangzhou, this company manufactures High-performance Paint Protection Film to top standards, competing on quality and consistency in the Asian manufacturing sector.
- GSWF: From Zhejiang, GSWF offers Paint Protection Film products as part of high-quality automotive film offerings, targeting both domestic and export markets.
- REEDEE: Based in Guangdong, REEDEE emphasizes Paint Protection Film manufactured to the highest possible standards, focusing on quality control in production.
- Livinyl: Also in Guangdong, Livinyl stands as one of the key manufacturers in China, contributing to the region's significant output in the global PPF supply chain.
Recent Strategic Developments and Industry Context
The competitive landscape is not static. Recent developments indicate that innovation and visibility at major industry events are critical for maintaining market position. Companies are actively showcasing new technologies to gain share and signal technological leadership.
Paint Protection Film Market
For instance, in 2025 and 2026, several key players participated in major exhibitions such as SEMA and Autocosmetica. Ceramic Pro showcased groundbreaking innovations in automotive surface protection including Paint Protection Film at SEMA 2025 with new product lineups and unreleased items. Similarly, LLumar Films participated in the SEMA Show with demonstrations of immersive Paint Protection Film, window film, and ceramic coatings. These events serve as barometers for industry direction, highlighting the convergence of film, coatings, and tinting technologies.
Furthermore, TeckWrap International demonstrated dry-install Color Paint Protection Film technology at Autocosmetica 2026, signaling a shift towards easier installation processes. ORAFOL presented an advanced Paint Protection Film range at the ORAFOL + ISA tradeshow in Orlando. These exhibitions underscore the importance of real-time intelligence gathering. Our report captures these developments to help clients anticipate competitor moves and identify potential partnership opportunities or threats.
Regulatory and Standards Environment
Beyond competition, regulatory frameworks are shaping the market. The industry is seeing increased attention on material standards and environmental compliance. For example, the Bureau of Indian Standards (BIS) issued PPF and polymer standards, alongside UNEP PPF and polymer standards. These regulations impact market entry requirements and product specifications, particularly in regions with stringent quality controls. Companies must ensure their products comply with local and international norms to avoid barriers to trade. Our analysis includes a review of these regulatory dynamics to assist in compliance planning and risk assessment.
Demand Drivers and Application Segments
The growth of the Paint Protection Film market is propelled by diverse application areas, though the automotive sector remains the dominant force. The need to protect vehicle resale value and aesthetics in an environment of increasing traffic density and road debris is a primary driver. However, the utility of PPF extends beyond personal vehicles.
Our research explores the breadth of applications, noting that while Automotive & Transportation leads in revenue contribution, other sectors are emerging. The Electrical & Electronics sector utilizes protective films for sensitive equipment, and various Other Applications present niche opportunities. The versatility of PPF materials allows for adaptation across these verticals, provided manufacturers can tailor properties such as flexibility, adhesion, and clarity to specific use cases.
Strategic focus should be placed on understanding the specific pain points in each application segment. For automotive, it is durability and aesthetics. For electronics, it may be protection against environmental stressors without interfering with functionality. Our full report segments the market to reveal where the highest value growth opportunities lie, helping clients allocate resources efficiently.
Strategic Recommendations for 2026 Decision Makers
As we move through 2026, stakeholders in the Paint Protection Film market must adopt a proactive stance. The convergence of material innovation, competitive pressure, and regulatory changes requires a holistic view of the industry. Below are key strategic areas that our research highlights for consideration:
- Supply Chain Resilience: Given the geographic diversity of manufacturers, companies should evaluate their supply chain risks. Diversifying sources or securing long-term contracts with key TPU and polyurethane film producers can mitigate volatility.
- Technology Investment: Investing in or partnering with companies that possess advanced self-healing and hydrophobic technologies is crucial. The market is shifting towards premium solutions, and legacy products may face margin compression.
- Market Positioning: Understanding the competitive concentration helps in defining positioning. Whether aiming to compete as a premium brand like XPEL or STEK, or as a cost-effective manufacturer leveraging scale, clarity on value proposition is essential.
- Regional Compliance: Keeping abreast of standards such as those issued by BIS and UNEP is necessary for global expansion. Non-compliance can result in significant market access delays.
- Aftermarket Integration: The value of PPF is often realized through installation quality. Building strong relationships with installers or investing in training programs can enhance product reputation and reduce warranty claims.
Conclusion
The Paint Protection Film market is poised for significant growth, driven by technological advancements and a global increase in vehicle protection awareness. However, capturing this growth requires more than just general market knowledge. It demands precise insights into segmentation, competitive moves, and material trends.
PW Consulting's comprehensive report on the Paint Protection Film Market offers the depth required to navigate this complex landscape. From detailed revenue forecasts to granular analysis of key players and raw material dynamics, this research is designed to empower strategic decision-making in 2026 and beyond. The overview provided here scratches the surface of the intelligence available. To unlock the full potential of your strategy with accurate data, segmentation details, and actionable recommendations, we invite you to access the complete study.
Stay ahead of the curve by grounding your decisions in verified, in-depth industry intelligence. The future of surface protection is clear, and the opportunities for those prepared are substantial.
For detailed analysis of this topic, please visit the official page: Paint Protection Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Toothbrush Market to Hit $344.8M by 2032, 6.98% CAGR
By pmarketresearch, 2026-09-15
Navigating the Electric Toothbrush Market: Strategic Insights for 2026 and Beyond
The global oral care landscape is undergoing a profound transformation. As consumer awareness of preventive health rises and digital health ecosystems mature, the electric toothbrush has evolved from a luxury accessory into a foundational component of daily wellness routines. For executives, investors, and product strategists operating in 2026, understanding the structural shifts within this category is no longer optional. It is a prerequisite for capital allocation, portfolio optimization, and competitive positioning.
PW Consulting’s latest market research on the electric toothbrush industry delivers a comprehensive, forward-looking analysis designed specifically to inform executive decision-making. This report synthesizes historical performance, forward trajectories, competitive intelligence, and regulatory dynamics into a single strategic framework. Below, we outline the core findings and explain why this intelligence is critical for navigating the 2026-2032 horizon.
Market Evolution: From Recovery to Sustained Expansion
Over the past five years, the electric toothbrush sector has demonstrated remarkable resilience and consistent growth. Building on a solid 2020 baseline, the market has expanded steadily through 2025, with annual revenue climbing to approximately 215.0 million USD. The trajectory reflects more than pandemic-era behavioral adjustments; it signals a structural shift in how consumers approach oral hygiene. As households replace aging manual devices and upgrade to smarter, feature-rich alternatives, the category has established a durable growth engine.
Looking ahead, our forecasting models project the market to reach 234.59 million USD in 2026, accelerating toward 344.8 million USD by 2032. This expansion is underpinned by a compound annual growth rate of 6.98 percent across the forecast period. Such a rate places the category firmly in the upper tier of consumer healthcare growth segments, driven by a confluence of technological innovation, demographic tailwinds, and evolving reimbursement frameworks. Importantly, the growth is not uniform. Regional adoption curves, price-tier preferences, and application-specific demand patterns vary significantly, and capturing the right opportunity requires granular, scenario-based analysis rather than broad-brush assumptions.
Product Architecture and Application Segmentation
The electric toothbrush market is not a monolith. It is defined by distinct technological pathways, each with its own value proposition, manufacturing complexity, and consumer affinity. Sonic technology currently dominates the revenue landscape, reflecting widespread consumer preference for quiet operation, perceived gentleness, and compatibility with premium branding. Rotary systems maintain a strong foothold, particularly among users who prioritize clinical plaque removal efficacy and established brand lineage. Ultrasonic and hybrid approaches, while smaller in absolute terms, represent high-growth niches where smart connectivity and clinical validation converge.
On the application side, adult consumers continue to drive the majority of category spend, but the growth narrative is increasingly diversified. Children’s oral care represents a strategically vital segment, as early habit formation creates long-term brand loyalty and opens doors to family-oriented subscription and replacement models. The geriatric population segment, while currently smaller, is gaining strategic attention as aging demographics intersect with rising periodontal health awareness and caregiver purchasing decisions. Understanding the margin profiles, replacement cycle economics, and channel dynamics across these applications is essential for portfolio planning and go-to-market execution.
Competitive Landscape: Established Giants and Disruptive Entrants
The competitive architecture of the electric toothbrush market reflects a layered ecosystem. At the top tier, multinational healthcare and consumer goods corporations leverage decades of brand equity, clinical research, and retail distribution muscle. Royal Philips N.V. continues to lead with its Philips Sonicare portfolio, emphasizing next-generation sonic technology, pressure-sensing intelligence, and app-driven engagement. Procter & Gamble Co. maintains a formidable position through its Oral-B line, with oscillating-rotation engineering and recent iO Series introductions designed to lower the barrier for manual-to-electric switchers. Colgate-Palmolive Company reinforces its oral care dominance with oscillating-rotation electric toothbrushes that align with its broader preventive health messaging.
Beneath the incumbent layer, a dynamic set of specialists and technology-forward challengers is reshaping consumer expectations. Water Pik, Inc. has carved out a differentiated position by integrating sonic oscillation with water flossing, appealing to consumers seeking all-in-one oral hygiene solutions. Foreo has gained traction with medical-grade silicone bristle designs that emphasize gentleness and aesthetic premiumization. quip has disrupted the category through minimalist design, subscription-friendly brush pod systems, and intuitive sensor feedback. Oclean Technology Co., Ltd. is pushing the boundaries of AI coaching and smart-app integration, positioning electric brushing as a data-rich, professionally guided experience.
The supply-side landscape is equally complex. A robust network of Chinese manufacturers, including Relish Tech, Auxbon, Shenzhen Libai Technology, and several Ningbo- and Shenzhen-based OEM/ODM producers, provides the industry with scalable manufacturing capacity, compliance certifications, and customization flexibility. Their role in enabling private-label programs and rapid feature iteration underscores the importance of understanding not just end-brand competition, but the entire value chain from component sourcing to regulatory compliance.
Recent Strategic Moves and Industry Dynamics
The pace of product innovation and corporate maneuvering in 2025 and early 2026 illustrates how aggressively players are competing for share. In January 2025, Procter & Gamble Co. launched the Oral-B iO2 model, explicitly engineered to simplify the transition from manual brushing. In February 2026, quip expanded its Ultra family with the Ultra Lite Sonic Electric Toothbrush, reinforcing its focus on ease of use, pressure monitoring, and long battery life. Most recently, in March 2026, Royal Philips N.V. unveiled two new Philips Sonicare ranges, pairing next-generation sonic technology with a refreshed brand direction. These launches are not isolated product refreshes; they are strategic signals about where each company believes value will be created over the next half-decade.
Underpinning these competitive moves are structural forces that will shape profitability and market access. Electric toothbrushes are classified as Class II medical devices under FDA regulations, requiring 510(k) premarket notification clearance for U.S. market entry. Powered toothbrushes must also comply with ISO 19452:2022 performance testing standards, creating a baseline of technical rigor that raises the barrier for low-quality entrants while rewarding manufacturers with established quality systems. On the materials side, toothbrush head compliance demands adherence to biocompatibility testing and FDA 21 CFR Part 177 requirements, reinforcing the importance of supply-chain transparency and documentation.
Cost structures are equally critical for strategic planning. As of 2026, manufacturing costs for electric toothbrushes range from 6 to 11 USD per unit for entry-level models, scaling to 31 to 55 USD per unit for ultra-premium smart devices. This wide cost band directly influences pricing architecture, margin potential, and the economic viability of feature-rich versus basic offerings. At the same time, the potential expansion of FSA/HSA eligibility for oral care products, as highlighted in recent public policy discussions, could meaningfully increase consumer purchasing power and accelerate adoption in price-sensitive segments.
Strategic Implications for 2026 Decision-Makers
For executives evaluating market entry, expansion, or portfolio refresh in 2026, several strategic questions demand rigorous, data-backed answers. Where should R&D investment be directed to balance clinical credibility with consumer-desired smart features? How should pricing and channel strategy adapt to the coexistence of low-cost manufacturing ecosystems and premium brand positioning? Which regional markets offer the strongest combination of growth potential and competitive whitespace? And how should companies prepare for regulatory and reimbursement shifts that could alter demand elasticity overnight?
Electric Toothbrush Market
The answers to these questions cannot be derived from high-level market size figures alone. They require detailed segmentation analysis, margin decomposition, competitive benchmarking, and scenario modeling that accounts for regulatory, cost, and consumer behavior variables. That is precisely the intent behind this report.
What You Will Find Inside the Full Report
PW Consulting’s complete Electric Toothbrush Market research goes far beyond headline numbers. The study is structured to support actionable decision-making across product strategy, commercial planning, and risk assessment. The report includes:
- Historical market sizing and forward forecasts with transparent methodological assumptions, enabling scenario planning across base, upside, and downside trajectories.
- Deep-dive segmentation analysis across technology types, application groups, and geographic regions, with attention to adoption maturity, replacement cycles, and channel dynamics.
- Competitive profiling of leading multinational brands, specialist innovators, and manufacturing partners, including recent product launches, positioning strategies, and ecosystem partnerships.
- Regulatory and standards mapping covering FDA classification requirements, ISO testing frameworks, biocompatibility compliance, and the implications of emerging reimbursement discussions.
- Supply-side and cost-structure analysis that connects manufacturing economics to pricing strategy, margin potential, and private-label feasibility.
- Strategic recommendations for portfolio prioritization, feature investment, geographic expansion, and competitive differentiation in a market that is simultaneously consolidating and fragmenting.
Each section is designed to be immediately useful for cross-functional teams. Product leaders will find guidance on feature prioritization and technology roadmapping. Commercial teams will gain clarity on pricing architecture, channel selection, and consumer segmentation. Executives and investors will benefit from a structured view of competitive intensity, market concentration, and long-term growth sustainability.
Power Toothbrush Market
Why This Research Matters Now
The electric toothbrush market in 2026 sits at the intersection of healthcare innovation, consumer technology, and regulated product manufacturing. Growth is real, but it is unevenly distributed. The winners in the next cycle will be those who can navigate the tension between premiumization and accessibility, between clinical validation and consumer experience, and between global scale and regional specificity. They will also be the organizations that treat regulatory compliance, cost discipline, and data-driven personalization as strategic capabilities rather than operational afterthoughts.
This report provides the intelligence infrastructure needed to make those decisions with confidence. It strips away the noise, focuses on the structural drivers that will shape demand and competition through 2032, and equips leadership teams with a clear framework for action.
To access the full analysis, including detailed segmentation data, competitive benchmarking, regional outlooks, and scenario-based forecasts, visit the PW Consulting market research portal. The complete report is available now for teams ready to turn market intelligence into strategic advantage.
For detailed analysis of this topic, please visit the official page: Electric Toothbrush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Power Cords Market to Hit $6,680M by 2032, Driven by 6.2% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Power Cords and Extension Cords Market: Navigating the 2026–2032 Forecast
As global electrification accelerates, infrastructure upgrades multiply, and connected devices proliferate across every sector, the power distribution ecosystem has become a focal point for strategic procurement, manufacturing planning, and competitive positioning. The Power Cords & Extension Cords Market is no longer a commoditized afterthought; it is a dynamic, regulation-sensitive, and geographically divergent segment where supply chain resilience, material economics, and compliance agility dictate margins. PW Consulting’s latest market research delivers a comprehensive, data-anchored view of this landscape, calibrated specifically to inform enterprise decisions across the 2026–2032 horizon.
This article serves as a strategic preview of the full report. It frames the macroeconomic trajectory, outlines the analytical architecture of the study, highlights the competitive dynamics shaping the sector, and embeds the latest regulatory and raw material developments that are already influencing sourcing strategies and product roadmaps. The objective is to demonstrate the report’s decision-ready rigor while preserving the granular breakdowns, scenario modeling, and proprietary benchmarking that reside in the complete publication.
Appliance Power Cord Market
Market Trajectory and the 2026–2032 Growth Arc
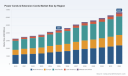
The historical baseline tells a clear story of steady, compounding expansion. From 2020 through 2025, the global market scaled from approximately 3.26 billion USD to an estimated 4.40 billion USD, reflecting resilient end-user demand, sustained construction and renovation activity, and the ongoing electrification of both consumer and commercial environments. That momentum carries decisively into the forecast window: the market is projected to reach roughly 4.63 billion USD in 2026 and continue its upward path toward approximately 6.68 billion USD by 2032.
Central to this trajectory is a sustained compound annual growth rate of 6.2 percent across the forecast period. While the headline figure signals healthy expansion, the real strategic value lies in what drives it. Growth is not uniformly distributed; it is being shaped by diverging regional development cycles, application-specific procurement patterns, and a structural split between indoor deployment, outdoor resilience requirements, and heavy-duty industrial specifications. Enterprises that treat the market as a single block risk misallocating capacity, mispricing SKUs, or overlooking compliance-driven substitution trends. The full report disentangles these layers, offering a calibrated view of where volume concentrates, where margin profiles diverge, and where short-cycle demand spikes are most likely to emerge.
For CFOs and supply chain leaders, the forecast is not merely a planning number; it is a stress test for inventory architecture, vendor diversification, and capital allocation. For product managers, it frames which performance tiers and certification pathways will command premium positioning. For competitive intelligence teams, it establishes the baseline against which market share shifts, pricing pressure, and regional entry timing can be measured.
Report Architecture: From Macro Signals to Operational Playbooks
The study is engineered to move beyond descriptive sizing and into actionable strategy. It combines rigorous historical reconstruction with forward-looking scenario analysis, giving leadership teams a multi-dimensional lens on demand, supply, and regulatory risk. The report’s structure is designed for direct integration into corporate planning cycles, with sections that translate market intelligence into procurement calendars, product portfolio decisions, and geographic expansion logic.
Readers can expect detailed segmentation mapping that clarifies how volume and value split across deployment environments and end-use contexts, without reducing the market to a single average. The analysis distinguishes between indoor configurations that dominate routine consumer and commercial setups, outdoor-rated solutions that must satisfy weather, abrasion, and UV resilience requirements, and heavy-duty variants engineered for sustained industrial loads and harsher operating conditions. Each category carries distinct material specifications, testing regimes, and price elasticity characteristics, and the report maps these differences to sourcing implications and commercial positioning.
Equally critical is the regional lens. Demand is shaped by local construction rhythms, retrofit cycles, data center build-outs, healthcare facility upgrades, and the pace of electrification in both developed and emerging markets. The publication provides a structured geographic framework that helps executives prioritize distribution partnerships, assess tariff and logistics exposure, and anticipate where certification requirements will create barriers or opportunities. Rather than presenting static share snapshots, the report contextualizes regional behavior within infrastructure spending patterns, import/export flows, and local compliance timelines.
The report also embeds procurement-relevant indicators, including material price trajectories, lead-time sensitivity, and the operational impact of standards revisions. By linking market size dynamics to the cost and compliance variables that actually move margins, the study enables scenario planning that is grounded in operational reality rather than theoretical growth curves.
Competitive Landscape: Coexistence of Scale Players and Niche Specialists
The competitive structure of the power cords and extension cords market reflects a deliberate division of labor between broad-line manufacturers and application-focused specialists. The full report profiles a cross-section of companies that illustrate how different strategic postures coexist within the same industry, each capturing value through distinct combinations of geographic reach, certification depth, and product engineering.
Southwire Company LLC, headquartered in Carrollton, GA, exemplifies the integrated producer that anchors its offerings in building wire, cable, and extension cords for utility, industrial, and commercial applications. Its position underscores the importance of vertical cohesion between core wire infrastructure and downstream power delivery products. Volex plc, based in Basingstoke, Hampshire, operates as a global integrated manufacturer of power cords, plugs, connectors, and custom wiring harnesses, serving consumer, industrial, and data center uses. Its profile highlights the strategic premium associated with custom configuration capabilities and multi-market qualification portfolios.
In residential and commercial electricals, Havells Ltd and Goldmedal Electricals demonstrate how regional manufacturing strength and broad distribution networks can secure enduring share in home electricals, flexible cables, switches, and power accessories. Their presence reinforces the reality that volume-driven segments reward brand trust, retail access, and consistent compliance execution as much as technical differentiation. At the same time, specialized manufacturers such as Ningbo Biaoda Electric Co., Ltd., YFC-Boneagle Electric Co., Ltd., Kord King, Electri-Cord Manufacturing, Jiaxing Hongzhou Cable Co., Ltd., Webber Electronics, Inc., Z-Tronix Inc., and Quail Electronics, Inc. illustrate the depth of capability available for hospital-grade, medical, dental, industrial, OEM, and international configuration requirements. These players often compete on certification breadth, custom cord-set engineering, and the ability to serve demanding end-use standards rather than on undifferentiated volume alone.
Strategically, the market structure matters because it shapes sourcing flexibility. Buyers can calibrate their supplier base between scale reliability and specialized compliance, while manufacturers must decide whether to compete on breadth, on certified performance in high-stakes applications, or on speed and configuration agility. The full report examines these positioning choices in greater depth, mapping how company footprints align with the segmentation and regional dynamics that drive demand.
Power Cords & Extension Cords Market
Regulatory and Material Dynamics Reshaping Sourcing Calculus
The market’s forward path is increasingly conditioned by the interplay of standards evolution and raw material economics. Two dynamics deserve particular attention because they directly influence product design, qualification timelines, and cost structures.
On the regulatory side, the July 30, 2025 revision of UL 817 introduced new requirements for Heater-Use Power-Supply Cords, with the broader standard for Cord Sets and Power-Supply Cords having been updated on the same date. For manufacturers and specifiers, this is not a procedural footnote; it is a product definition event. Heater-related applications impose distinct thermal, loading, and safety expectations, and revisions of this nature typically trigger requalification cycles, documentation updates, and in some cases material or construction adjustments. Companies that anticipate the operational implications of UL 817 changes can shorten time-to-compliance and reduce the risk of specification rejections, while those that treat standards revision as a back-office task may face delayed launches and eroded quoting accuracy.
On the cost side, polymer pricing remains a central variable in cord and cable economics. As of April 2026, PVC pricing diverged meaningfully by geography: China PVC prices reached approximately 735.45 USD per metric ton, while U.S. PVC prices stood at about 822.45 USD per metric ton. That gap is strategically significant for any organization balancing offshore sourcing, domestic production, inventory timing, and pass-through pricing. Material volatility of this nature influences not only direct cost of goods, but also the relative attractiveness of different product tiers, the feasibility of long-term supply agreements, and the negotiation leverage between buyers and suppliers. It also interacts with certification requirements, since material substitution in response to cost pressure must still satisfy performance and safety expectations.
Together, these forces define a market environment where compliance agility and input-cost intelligence are competitive differentiators. The full report integrates these developments into the broader dynamics section, linking standards and materials to segmentation behavior, regional cost structures, and the strategic options available to both producers and procurement organizations.
Why the 2026 Decision Window Demands This Level of Intelligence
Entering 2026, enterprises face a convergence of planning imperatives that makes high-resolution market intelligence essential. Demand is expanding at a durable pace, but the composition of that demand varies by environment, application, and region. Standards are being refined in ways that affect product eligibility and qualification lead times. Material pricing is diverging across geographies, altering the economics of sourcing models that may have appeared balanced on paper. In this context, decisions made on the basis of coarse market narratives are increasingly likely to produce suboptimal capacity allocation, misaligned SKU emphasis, or unanticipated compliance exposure.
The strategic value of this study lies in its ability to convert these moving parts into a coherent decision framework. It helps leadership teams answer practical questions: where should inventory and production emphasis be placed to match the most resilient demand pools; which product categories carry the strongest combination of volume and margin durability; how should supplier portfolios be structured to absorb material volatility and certification cycles; and where do regional dynamics create entry timing advantages or risks. By anchoring these questions in a 2026–2032 horizon, the report enables plans that are forward-compatible rather than reactive.
For organizations that compete on reliability, certified performance, or configuration agility, the publication also serves as a benchmarking foundation. Understanding how market size, segmentation behavior, and competitive positioning interlock makes it possible to calibrate go-to-market priorities, refine pricing strategy, and anticipate where differentiation will command premium attention in specification processes.
What the Complete Study Unlocks
This preview has outlined the structural logic of the market, the trajectory implied by the historical and forecast data, the competitive architecture that defines how value is captured, and the regulatory and material variables that are already reshaping operational calculus. The full report extends well beyond this frame. It delivers the detailed segmentation analysis, regional demand context, company profiling depth, standards impact assessment, and material-cost sensitivity perspective needed to translate macro direction into executable plans.
Because the study is designed to support real-world decision cycles, the complete version includes the granular breakdowns, scenario considerations, and benchmarking references that leadership teams require when setting procurement calendars, prioritizing product development, evaluating distribution geography, and stress-testing sourcing strategies against regulatory and input-cost shifts. These elements are intentionally developed in full within the publication so that readers can apply them directly to internal planning without having to reconstruct the underlying logic.
For executives, analysts, and operations leaders who need to align strategy with the realities of a growing but increasingly complex market, the complete research offers the evidentiary base and structural clarity required to move from awareness to action. To access the full segmentation detail, competitive profiles, regional context, and compliance and materials analysis, and to integrate the complete forecast with your internal planning models, visit the source page for the Power Cords & Extension Cords Market research and obtain the full report.
For detailed analysis of this topic, please visit the official page: Power Cords & Extension Cords Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Fiber Cement Market Hits $22.45 Billion in 2025, 4.08% CAGR Forecast to 2032
By pmarketresearch, 2026-09-15
The Fiber Cement Market in 2026 A Strategic Crossroads for Construction and Manufacturing Leaders
The global fiber cement market stands at a decisive inflection point as it moves through the 2026-2032 forecast horizon. An economy that reached 22.45 billion USD in 2025 is not merely expanding; it is restructuring around material innovation, regulatory realignment, and shifting end-use expectations. For executives, procurement leaders, and investors, the question is no longer whether fiber cement will grow, but how capital, capacity, and competitive positioning should be allocated to capture durable advantage. Our latest Fiber Cement Market study translates these macro trajectories into an actionable decision framework, giving leadership teams the precision they need to plan capacity, pricing, distribution, and product architecture through the end of the decade.
This research is built for those who must act, not merely observe. The analysis spans historical performance from 2020 to 2025, establishes a 2025 base year, and projects forward to 2032 with disciplined scenario logic. Total revenue is tracked in USD across a billion-unit scale, reflecting a maturation pathway that moves from 22.59 billion USD in 2026 toward 29.71 billion USD in 2032. That trajectory implies a compound annual growth rate of 4.08 percent, a pace that signals sustained demand while simultaneously exposing the operational friction points that can erode margin if left unmanaged. The study treats this growth as a strategic asset and a risk surface, mapping both the upside and the pressure points that will shape enterprise outcomes over the next seven years.
What makes this intelligence especially valuable in 2026 is its timing. The industry is navigating a convergence of forces that will test supply chain resilience, cost discipline, and product differentiation at the same time. Raw material price volatility for cement and cellulose is reshaping input economics, while labor cost escalation in high-cost states continues to push up total project cost for siding and exterior applications. At the same time, regulatory attention is intensifying, with the United States Environmental Protection Agency issuing guidance on safe use and exposure to fibrous silicate minerals in manufacturing, and the government of British Columbia proposing additional safety measures for fibrous silicate minerals in plants. These developments are not peripheral news; they alter compliance costs, operational standards, and the speed at which new capacity can be brought online. The report integrates these realities into a single operational lens so that leaders can forecast not just demand, but the true cost and feasibility of serving that demand.
Why This Study Matters for 2026 Enterprise Decisions
Strategic planning in 2026 requires more than a top-line growth assumption. It requires a granular view of where value is created and where it leaks. The market’s structure is concentrated enough to reward scale, yet dynamic enough to open opportunities for disciplined regional and product plays. With the top three competitors accounting for 60.0 percent of market share and the top five reaching 70.0 percent, the competitive field is clearly tiered. That concentration changes the logic of entry, expansion, and defense. Organizations must understand which segments carry the greatest margin potential, which geographies offer the most efficient route to volume, and which product forms align with emerging specification trends. This report is designed to answer those questions with a level of clarity that supports capital deployment and go-to-market strategy, without forcing leaders to guess at the underlying segmentation logic.
The study is also timed to support decisions that depend on near-term visibility. Forecasts begin at 22.59 billion USD in 2026 and step upward through 24.18 billion USD in 2027, 24.52 billion USD in 2028, 25.83 billion USD in 2029, and 27.95 billion USD in 2030, before reaching an end-of-horizon range that closes at 29.24 billion USD in 2031 and 29.71 billion USD in 2032. These figures are not presented as abstract numbers. They are used to anchor scenario planning, identify when demand intensifies, and highlight the intervals in which competitors are most likely to adjust capacity, pricing, or distribution. For a procurement director monitoring cellulose and cement cost exposure, that cadence matters. For a regional business unit evaluating whether to expand distribution, it matters even more.
Inside the Report Architecture and Practical Utility
The study is organized to move from market structure to execution, ensuring that insights can be operationalized rather than simply read. It examines the market through multiple lenses, including type, application, and region, so that users can map growth into the specific business lines and territories that matter most to their organization. The type view addresses the product architecture that defines sourcing, formulation, and differentiation strategies. The application view connects demand to functional use cases in siding, roofing, molding and trim, flooring, and other end markets, helping teams understand where specification momentum and replacement cycles are likely to shape volume. The regional view supports distribution planning, plant siting logic, and competitive targeting by showing where demand is accumulating and where saturation or cost pressure may alter the route to profit.
Beyond segmentation, the report translates market structure into competitive strategy. It profiles the organizations that are defining the pace of the industry, from established building-product leaders to regional specialists with strong local execution. The analysis does not stop at corporate description. It examines how each player’s product focus, manufacturing footprint, and market posture position them for the next phase of growth, and it identifies where concentration creates either a defensive moat or an incentive for disruption. This company-level intelligence is especially useful for teams evaluating partnership opportunities, competitive threats, or potential acquisition targets, because it relates each organization’s specific offerings to the larger demand architecture.
The study also integrates a forward-looking set of industry developments that carry direct operational implications. Recent activity shows how fast the competitive and standards environment can change. In February 2025, James Hardie Building Products Inc. unveiled new and expanded Hardie products, including Artisan Trim, at the NAHB International Builders Show, signaling continued product-line broadening in response to specification opportunities. In May 2025, the company announced a three-year exclusive distribution agreement with Davidson Homes for Hardie siding and trim products, an example of how channel control and builder relationships are becoming central to share defense and growth. Later, in October 2025, ICC-ES proposed new criteria for fibre-cement siding complying with ASTM C1186 or ISO 8336 in combustible and noncombustible construction, an indication that the regulatory and testing environment is tightening around material performance and application rules. Each of these events is treated as a strategic signal, not just an industry headline, and the report explains what they imply for product roadmaps, channel strategy, and compliance readiness.
Equally important, the report provides a practical view of the cost and risk environment. It addresses raw material price fluctuations for cement and cellulose that raise production costs, and it places those pressures within the broader context of labor and total project economics. It also reflects the regulatory landscape shaping manufacturing operations, including EPA guidance on safe use and exposure to fibrous silicate minerals and British Columbia’s proposed additional safety measures for plants. These inputs are woven into the analysis so that readers can assess the full stack of operational constraints, from input procurement to worker safety, compliance documentation, and final installed cost. For organizations that must justify capital expenditure or renegotiate supply terms, that integrated view is what turns information into decision support.
Competitive Positioning and the Shape of Industry Leadership
The competitive map in this study is built to show where advantage is durable and where it is contestable. The market’s concentration profile means that a limited number of firms hold substantial influence over pricing expectations, specification penetration, and channel relationships. At the same time, the breadth of profiled organizations indicates that leadership is not monolithic. Different companies compete through different product forms, end-use strengths, and regional reach, which creates a market in which specialization can still outperform undifferentiated scale in the right context.
James Hardie Industries PLC, headquartered in Ireland, continues to anchor the market with a focused offering built around Hardie fiber cement siding and backer boards. Its recent product unveiling and exclusive distribution agreement underscore a strategy that combines product expansion with channel exclusivity, reinforcing brand preference and builder-level pull. ETEX Group, based in Belgium, competes with fiber cement boards and sheets, positioning around building-envelope and construction use cases where board performance and consistency matter. Saint-Gobain, headquartered in France, brings a wider construction-products footprint and offers fiber cement products for construction applications, leveraging scale and technical breadth across multiple building systems. Nichiha Corporation, based in Japan, emphasizes high-performance fiber cement panels and siding, aligning with markets that value precise engineering and exterior durability. Cembrit Holding A/S, from Denmark, focuses on fiber cement siding and exterior products, supporting architectural and weather-exposed applications where finish and long-term performance drive specification decisions.
Fiber Cement Market
Regional specialists and application-focused players round out the competitive landscape and add important nuance to market strategy. Allura USA operates in the United States with fiber cement siding products, while American Fiber Cement Corporation provides boards and sheets for construction-related demand. Elementia Materials contributes fiber cement products for construction from Mexico, and Everest Industries Limited supports board demand from India. CSR Limited extends fiber cement products from Australia, and Plycem Corporation competes in the U.S. market with siding and boards. Swisspearl Group, headquartered in Switzerland, emphasizes fiber cement cladding and siding, aligning with architectural exterior solutions. Together, these organizations illustrate that the market is not only contested by global leaders but also shaped by companies that win through regional density, product specificity, or cost-efficient manufacturing.
This diversity is strategically meaningful. For an incumbent, it highlights the need to protect specification share, strengthen distribution agreements, and reduce exposure to input and compliance cost shocks. For a challenger or regional operator, it suggests that targeted product forms, localized service, and selective channel partnerships can create defensible positions even in a concentrated market. The study connects these competitive realities to the segmentation logic described earlier, allowing readers to see where each company’s strengths intersect with demand pools and where gaps may open for new investment or partnership.
Strategic Implications for Capital, Supply Chain, and Growth Planning
The most valuable use of this research is to convert market direction into internal priorities. In a market projected to expand from 22.59 billion USD in 2026 to 29.71 billion USD in 2032, the organizations that outperform will be those that treat growth as a systems problem. They will align product architecture with specification momentum, build supply chains that can absorb raw material volatility without eroding margin, and prepare for regulatory change as part of operational planning rather than as an afterthought. They will also recognize that construction-sector demand is increasingly shaped by project economics, including labor and material cost dynamics in high-cost regions, which can alter both replacement cycles and new-build adoption.
Because the report keeps its most precise segmentation detail and company-level scenario data inside the full publication, it preserves the analytical tension that makes the study useful. Leaders can see the shape of the market, understand the forces moving it, and identify where strategic action matters most, while reserving the deeper quantitative detail for the moment they are ready to commit capital or revise a commercial plan. That structure is intentional. It allows executives to build confidence in the research rigor and then retrieve the specific numbers, split data, and playbook-level recommendations that support board-level decisions.
Fiber Cement Board Market
For 2026, the strategic takeaway is straightforward. Fiber cement is expanding within a market that is large enough to matter and structured enough to reward disciplined strategy. The firms that will benefit most are those that can read the market not just as a growth curve, but as a map of concentration, regulation, input risk, product form, and application demand. This report provides that map. It gives decision-makers the context to see where the market is heading, the competitive logic to understand who is gaining ground, and the operational grounding to act with confidence.
The full study goes further by delivering the detailed segmentation, regional and application-level revenue context, and company-specific strategic readouts that support precise planning. Those elements are where the research moves from directional insight to executable intelligence. Readers looking to lock in capacity strategy, refine pricing models, prioritize channels, or evaluate competitive exposure will find the complete dataset and scenario framework essential. For teams preparing for the 2026-2032 window, this publication offers both the high-level view needed to set direction and the deeper market intelligence required to execute it.
For detailed analysis of this topic, please visit the official page: Fiber Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting PC Power Supply Market to Hit $322.2M by 2032 with 4.89% CAGR as ATX Dominates Global Revenue
By pmarketresearch, 2026-09-15
Navigating the Power Core: Strategic Insights into the 2026 PC Power Supply Market
The personal computer power supply unit (PSU) has evolved from a commoditized accessory into a critical determinant of system stability, efficiency, and performance capability. As we move through 2026, the market is experiencing a confluence of regulatory pressure, hardware evolution, and shifting demand patterns that demand careful strategic navigation. PW Consulting's latest comprehensive market research on the PC Power Supply Market offers a detailed roadmap for stakeholders aiming to capitalize on these shifts. This article outlines the macro environment, competitive dynamics, and operational realities shaping the sector, serving as a preview to the full intelligence available in our report.
Market Trajectory and Valuation Context
Understanding the magnitude of the opportunity requires a clear view of the historical growth path and the projected expansion phase. Over the historical review period from 2020 to 2025, the global market for PC power supplies demonstrated resilience despite supply chain volatility. Valued at approximately 163.15 million USD in 2020, the market climbed to 177.81 million USD in 2021. A slight correction occurred in 2022 with a valuation of 173.29 million USD, followed by a recovery trajectory that saw figures reach 193.0 million USD in 2023 and 195.33 million USD in 2024. By the base year of 2025, the market had expanded significantly to 230.67 million USD.
DIN Rail Power Supply Market
The forecast period spanning 2026 through 2032 indicates sustained growth momentum. Starting at an estimated 236.6 million USD in 2026, the market is projected to ascend steadily, reaching 259.36 million USD in 2027 and 268.41 million USD in 2028. Further projections place the valuation at 287.67 million USD in 2029, 297.72 million USD in 2030, 317.62 million USD in 2031, and culminating at 322.2 million USD in 2032. This trajectory reflects a compound annual growth rate of 4.89 percent over the forecast horizon. These figures underscore a market that is not merely recovering but structurally expanding, driven by higher wattage requirements and efficiency mandates. Our full report dissects the velocity of this growth across specific timeframes to help planners align their capacity and investment cycles.
Structural Shifts in Market Segmentation
The composition of the market is undergoing significant recalibration. Historically dominated by standard desktop configurations, the landscape is now fragmented by form factor innovations and specialized industrial needs. The breadth of product types available to consumers and enterprises has widened, with standard ATX units maintaining a substantial footprint while smaller form factors like SFX are carving out niche relevance for compact builds. Additionally, the application spectrum is diversifying. While desktop computing remains the primary revenue engine, industrial applications are emerging as a distinct and growing segment, fueled by the need for robust power solutions in specialized computing environments.
Regional dynamics also play a pivotal role in shaping demand and supply chains. North America continues to represent a significant portion of market activity, reflecting high adoption rates of high-performance hardware. Europe maintains a strong presence, influenced heavily by regional regulatory frameworks. The Asia Pacific region contributes a substantial share, driven by manufacturing hubs and growing domestic consumption. Latin America and the Middle East and Africa represent emerging avenues with varying degrees of penetration. Detailed regional analysis within our study reveals specific growth vectors and potential friction points in logistics and distribution that are critical for market entry strategies.
Regulatory and Technological Dynamics
One of the most profound drivers of change in the PC power supply sector is the regulatory environment. The release of the ATX 3.1 specification in September 2023 marked a turning point. This specification introduced the 12V-2x6 connector and mandated a maximum hold-up time of 12 milliseconds to adequately support GPU power excursions. Compliance with these standards is no longer optional for manufacturers targeting the high-end segment, forcing a reevaluation of design architectures and component sourcing.
Simultaneously, energy efficiency regulations are tightening globally. The European Ecodesign Directive and California's Title 20 standards have imposed stricter no-load efficiency limits. These mandates are accelerating the adoption of advanced technologies such as digital control loops and synchronous rectification. Manufacturers must balance the cost of implementing these technologies against the competitive necessity of achieving high efficiency ratings like 80 Plus Titanium or Platinum. Our report provides a granular analysis of how these regulations impact cost structures and time-to-market for different product tiers.
Supply Chain Volatility and Cost Pressures
Operational stability is currently challenged by fluctuations in raw material costs. The passive component raw material price index, which tracks essential elements such as nickel, copper, aluminum, zinc, palladium, ruthenium, tantalum, silver, and oil, stood at 3,399 per index unit in November 2025. This represents an 8 percent rise from April 2012 levels, indicating a long-term upward pressure on input costs. Furthermore, specific supply chain disruptions have impacted critical components. Ferrite core prices within the PC PSU supply chain surged 22 percent year-over-year in the first quarter of 2026 due to supply disruptions at Asian producers.
These cost pressures necessitate sophisticated procurement strategies and pricing models. Companies that can secure stable supply lines for critical materials while maintaining margin integrity will hold a distinct advantage. The full market study includes a sensitivity analysis on raw material pricing and its potential impact on final unit economics over the forecast period.
Competitive Landscape and Key Players
The market exhibits a moderately concentrated structure, with the top three companies holding a combined share of 37.5 percent and the top five reaching 45.0 percent. This fragmentation suggests room for strategic consolidation or aggressive growth by key players. Several industry leaders are defining the pace of innovation through product launches and technological compliance.
-
FSP Group (Taiwan): A dominant force focusing on high-efficiency solutions. Their portfolio includes full modular ATX 3.1 and PCIe 5.1 ready PSUs with 80 Plus Titanium and Cybenetics Titanium efficiency. Flagship models like the MEGA TI 1650W and VITA GM 1000W exemplify their commitment to high-performance computing. In May 2026, FSP Group unveiled the FSP2000-57APB 2000W ATX 3.1 flagship power supply specifically targeting on-premise computing and AI workloads, signaling a strategic pivot toward high-density power solutions.
-
Seasonic (Japan): Renowned for premium quality, Seasonic offers fully modular ATX 3.1 compliant PSUs with 80 Plus Platinum and Cybenetics Titanium ratings. Their Prime TX and Vertex series are benchmarks for reliability. The company continues to set standards for efficiency and noise levels in the enthusiast segment.
-
be quiet! (Germany): Specializing in low-noise operations, be quiet! offers the Ultra-quiet Dark Power series and Pure Power 13 M PSUs. These units feature high-efficiency Gold to Titanium ratings meeting ATX 3.1 standards. In May 2026, they launched the Pure Power 13 M and Titan PLA series ATX 3.1 PSUs, emphasizing enhanced quiet operation and modular design.
-
Corsair (United States): A key player in the gaming and workstation space, Corsair provides HX-i, RMx, and RMe modular ATX 3.1 PSUs. These units boast 80 Plus Platinum and Cybernetics Platinum efficiency. In February 2026, Corsair introduced updated HX1500i and RMe series PSUs fully compliant with ATX 3.1 and PCIe 5.1 standards, reinforcing their position in the high-end build market.
-
Super Flower (Taiwan): Known for the Leadex Titanium and VII Platinum PRO series, Super Flower delivers full modular designs with 80 Plus Titanium and Cybenetics Platinum certifications. Their support for PCIe 5.1 ensures compatibility with the latest graphical processing units.
-
Lite-On Technology (Taiwan): Offering ATX and SFX PC power supply modules with output up to 2200W, Lite-On focuses on Platinum efficiency and full-range input for desktop and workstation applications. In May 2026, they demonstrated integrated power solutions for AI data centers and high-performance PCs at COMPUTEX 2026, highlighting their expansion into broader computing infrastructure.
PC Power Supply Market -
AcBel Polytech Inc. (Taiwan): Catering to both industrial and consumer sectors, AcBel provides PC PSUs with CRPS and slim designs. Their units reach up to 3200W with 80 Plus Titanium efficiency and include redundancy features, making them suitable for critical industrial applications.
-
Delta Electronics (Taiwan): A major electronics manufacturer, Delta supplies desktop and workstation switching PSUs. Their focus on high efficiency, 80 Plus ratings, and support for ATX 3.1 standards ensures they remain relevant in the enterprise and commercial PC segments.
-
ASRock (Taiwan): Primarily known for motherboards, ASRock has entered the PSU space with Steel Legend SL and Phantom Gaming modular PSUs. These offer ATX 3.1 compliance, Gold to Platinum efficiency, and PCIe 5.1 support, providing an integrated ecosystem option for builders.
-
Huntkey (China): Showcasing high-performance PC power supplies, Huntkey presented innovative designs for gaming and workstation applications at COMPUTEX Taipei 2025. Their focus on AI and gaming applications indicates a strategic alignment with high-growth hardware segments.
-
Enermax (Taiwan): With the Revolution III series, Enermax delivers fully modular ATX 3.1 and PCIe 5.1 PSUs. Their focus on high efficiency and low noise operation appeals to users seeking balanced performance and acoustics.
-
SilverStone (Taiwan): Offering the SX and SX Pro series, SilverStone provides high-wattage Platinum PSUs with modular cables. Their ATX 3.1 compliance ensures they meet the latest technical requirements for modern builds.
Strategic Implications for 2026 Decision Makers
For executives and strategists operating in this space, the data points to several critical action areas. First, the shift toward ATX 3.1 and PCIe 5.1 compliance is not merely a technical update but a market barrier. Products that fail to meet these specifications risk obsolescence in the high-performance segment. Second, the rising cost of raw materials suggests that vertical integration or long-term supplier contracts may become necessary to protect margins. Third, the growing importance of industrial applications and AI-related workloads suggests that diversification beyond consumer desktops could unlock significant revenue streams.
The concentration of market share among top players indicates that while the market is accessible, competing on efficiency and innovation is paramount. Companies must decide whether to compete on price in the lower tiers or differentiate through premium efficiency ratings and specialized features like those seen in the Titanium and Platinum categories. Furthermore, regional regulations require localized strategies, particularly in Europe and North America, where compliance costs can impact pricing competitiveness.
Accessing the Full Intelligence
This overview provides a snapshot of the macro trends, competitive moves, and regulatory pressures defining the PC Power Supply Market in 2026. However, the complexity of the supply chain, the nuances of regional demand, and the specific financial projections require a deeper dive. PW Consulting's full market research report contains detailed segmentation data, comprehensive company profiles, historical data tables, and forecast models that are essential for building robust business cases.
Stakeholders seeking to validate market entry strategies, optimize product portfolios, or benchmark against key competitors are advised to consult the complete study. The full report offers the granularity needed to translate these high-level insights into actionable operational plans. By leveraging this intelligence, organizations can navigate the volatility of raw material costs, align with regulatory shifts, and position themselves to capture value in a market projected to grow steadily through 2032.
As the industry continues to evolve with technological advancements and regulatory updates, staying informed with precise data is the most effective hedge against uncertainty. We invite you to explore the complete findings to ensure your strategic decisions are grounded in the most current and comprehensive market intelligence available.
For detailed analysis of this topic, please visit the official page: PC Power Supply Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti-Decubitus Cushions Market Hits USD 737.71M in 2025, Expands at 6.05% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Intelligence for the Anti-decubitus Cushions Market (2026–2032)
The global landscape for pressure injury prevention is undergoing a structural shift. As healthcare systems worldwide grapple with aging demographics, prolonged hospitalization costs, and an increasing emphasis on patient mobility, the anti-decubitus cushions market has emerged as a critical intersection of medical device innovation, reimbursement policy, and material science. For executives, investors, and product strategists, the period from 2026 through 2032 represents a decisive window where competitive positioning, regulatory navigation, and supply chain resilience will separate market leaders from followers.
Our latest comprehensive market research delivers more than historical retrospectives. It is engineered as a decision-grade intelligence platform, translating complex demand signals, material transitions, and regulatory developments into actionable strategic roadmaps. This article serves as a preview of the analytical depth contained in the full report, designed to demonstrate exactly how the study can operationalize market uncertainty into confident corporate strategy.
Macro Trajectory: A Market Built on Sustained, Compounding Growth
Understanding where the market is headed requires first grounding strategy in verified historical momentum. Between 2020 and 2025, the global anti-decubitus cushions sector demonstrated consistent expansion, climbing from approximately 549.96 million USD to 737.71 million USD. That trajectory did not plateau at the five-year mark. Looking forward, the market is projected to reach 791.83 million USD in 2026, with growth accelerating across the forecast horizon to close at 1112.91 million USD by 2032.
This expansion translates to a compound annual growth rate of 6.05 percent across the full 2026–2032 forecast period. For strategic planners, this is not merely a growth statistic. It signals a market where incremental gains are sustained, where demand drivers are structural rather than cyclical, and where early-mover advantages in product innovation, distribution architecture, and reimbursement alignment can compound over nearly a decade. The full report unpacks the underlying demand elasticity, substitution patterns, and regional momentum shifts that make this CAGR actionable, while deliberately reserving granular breakdowns for clients who need them for internal modeling and board-level forecasting.
What the Report Delivers: From Market Data to Executable Strategy
A high-quality market study does not simply report what happened. It equips leadership teams to anticipate what will happen next and to allocate resources accordingly. Our anti-decubitus cushions market research is structured around operational utility. Every analytical layer is designed to answer boardroom and strategy-team questions before they become crises.
The report opens with a rigorous demand-side architecture, mapping how clinical requirements, procurement cycles, and end-user behavior converge to shape volume and pricing dynamics. It traces the supply-side ecosystem, examining raw material sourcing, manufacturing constraints, and the transition toward medical-grade materials that balance durability with skin-contact safety. The segmentation analysis isolates how different product architectures and use-case categories perform across the demand spectrum, providing context for product portfolio decisions, pricing architectures, and channel strategy.
Beyond segmentation, the study delivers a comprehensive competitive benchmarking framework. Rather than relying on surface-level revenue estimates, the analysis reconstructs how leading players differentiate themselves through engineering, clinical positioning, and service ecosystems. The report also embeds regulatory and reimbursement intelligence directly into the market dynamics section, ensuring that strategic recommendations account for the policy environment that governs market access, procurement eligibility, and compliance costs.
Clients will find scenario-based modeling, sensitivity analysis around key demand drivers, and strategic implication matrices tailored for product development, market entry, M&A screening, and portfolio optimization. The full version preserves the complete analytical architecture, including calibrated forecasts and cross-referenced data tables, allowing strategy teams to build internal models with confidence.
Competitive Landscape: Engineering Differentiation in a Concentrated Market
Market concentration remains a defining feature of the anti-decubitus cushions sector. The top three players command roughly 35 percent of market share, while the top five extend that footprint to approximately 45 percent. Such concentration does not imply stagnation. In fact, it reflects a market where brand credibility, clinical validation, and engineering maturity carry substantial weight. The full report maps these players in detail, but even a high-level view reveals how competitive advantage is being constructed.
Anti-decubitus Cushions Market
Direct Healthcare Group (DHG)
Headquartered in Caerphilly, Wales, Direct Healthcare Group has anchored its cushion portfolio around clinically differentiated pressure management technologies. Its Dyna-Form Mercury Advance alternating pressure cushion targets very high-risk patient populations, while the Dyna-Tek intelligent air cushion line focuses on dynamic pressure redistribution and proactive ulcer prevention. The strategic lesson here is clear: clinical risk stratification is becoming a product design principle, and manufacturers that align their engineering with specific patient acuity tiers are building defensible positioning.
etac
Based in Kista, Sweden, etac has emphasized precision in pressure redistribution and patient positioning through its Star vertical air-cell seat cushions. Designed for high-risk pressure injury prevention, these products highlight the growing importance of combining pressure management with postural support. Companies that integrate positioning functionality into anti-decubitus design are not only addressing clinical outcomes but also expanding the functional value proposition that procurement teams and clinicians evaluate during purchasing decisions.
Invacare
Invacare, operating from Elyria, Ohio, continues to reinforce its presence through pressure care wheelchair cushions such as the Matrx Flo-tech series, which combine gel and foam inserts to support body contouring and pressure ulcer prevention. This approach underscores the enduring relevance of hybrid material architectures. As raw material specifications evolve, manufacturers capable of balancing comfort, pressure distribution, and long-term durability will maintain a strong competitive foothold, particularly where procurement teams weigh total cost of ownership against clinical performance.
Outdoor Cushions Market
Permobil (ROHO)
Permobil, through its ROHO cushion lineage based in Belleville, Illinois, has built a recognized reputation around air-cell cushion systems, including both custom and standard models. The ROHO platform illustrates how deep specialization in pressure redistribution technology can create strong brand loyalty among clinicians and end-users. In a market where seating stability and pressure distribution performance are governed by rigorous standards, companies that maintain consistent technical validation and product customization capabilities are well positioned to defend premium positioning.
The full report extends this competitive analysis into a structured benchmarking framework that evaluates differentiation vectors, likely strategic moves, and vulnerability zones. Clients gain insight into where incumbents are concentrating their engineering efforts and where white space may exist for targeted product entry or partnership strategies.
Regulatory and Reimbursement Realities: The Invisible Architecture of Market Access
In medical device markets, competitive strategy cannot be separated from regulatory and reimbursement architecture. Anti-decubitus cushions operate within a compliance environment that shapes both market entry and commercial velocity. The report embeds these dynamics directly into its market analysis so that strategic recommendations reflect real-world access conditions rather than idealized demand curves.
Wheelchair cushions fall under FDA device classifications relevant to flotation cushions and wheelchair components. Many products in this category are designated as Class I devices generally exempt from 510(k) premarket notification, yet they still require establishment registration and listing. This regulatory posture lowers certain barriers to market presence while simultaneously elevating the importance of manufacturing discipline, quality systems, and post-market compliance. The full report explains how these requirements affect competitive entry timing, cost structures, and risk management for both established players and new entrants.
On the reimbursement side, pressure-reducing support surfaces, including anti-decubitus cushions, are covered under the Durable Medical Equipment benefit defined in the Social Security Act. This coverage pathway is a critical enabler of patient access and a stabilizing force for demand. However, reimbursement dynamics also influence procurement behavior, prescribing patterns, and the commercial calculus used by manufacturers when setting pricing architecture and service offerings. The study examines how coverage frameworks interact with clinical adoption and procurement cycles, providing context for forecasting and market-entry planning.
Beyond federal classification and coverage, the market is shaped by performance and safety standards. Anti-decubitus cushions must align with flammability requirements such as BS7176:2007 for medium-hazard applications, and they must be launderable to support inspection and hygiene protocols. Furthermore, pressure care cushions are expected to meet ISO 7176 standards for wheelchair seating stability and pressure distribution performance. These standards are not administrative footnotes. They define the technical boundary within which product differentiation is credible. The report treats them as strategic constraints and enablers, showing how compliance readiness influences product roadmaps, supplier selection, and market acceptance.
Material and Engineering Trends: Where Innovation Meets Durability
The technical evolution of anti-decubitus cushions is being driven by the need to reconcile clinical performance with material longevity. Alternating pressure cushions increasingly rely on gel inserts and air cells constructed from medical-grade polyurethane and foam materials. These material choices are not incidental. They directly affect durability, skin-contact safety, pressure redistribution quality, and lifecycle cost.
Strategically, this places material science at the center of product competitiveness. Companies that secure reliable access to medical-grade inputs, optimize foam and air-cell architectures for sustained performance, and design products that can withstand repeated laundering and inspection cycles will gain an advantage in both clinical reputation and total-cost positioning. The research previewed here highlights these dynamics, while the full report drills deeper into material substitution patterns, sourcing considerations, and the implications for manufacturing economics.
Why This Study Matters for 2026 Decision-Making
The 2026–2032 period will reward organizations that can connect macro demand signals to micro strategic actions. A market growing from roughly 791.83 million USD in 2026 toward over 1.1 billion USD by 2032 at a 6.05 percent CAGR is large enough to support multiple competitive strategies, but not large enough to tolerate misallocated investment. Success will depend on knowing where growth is structurally concentrated, how reimbursement and regulation shape access, where incumbents are vulnerable, and how material and engineering choices translate into commercial differentiation.
This research is designed to support exactly those decisions. It helps product leaders evaluate portfolio gaps, enables commercial teams to calibrate pricing and channel strategy, supports executives in assessing partnership or acquisition targets, and gives investors a rigorous framework for evaluating market risk and opportunity. Rather than presenting a static snapshot, the study builds a forward-looking analytical environment in which strategic choices can be stress-tested against plausible market scenarios.
Conclusion: Turn Insight Into Positioning
The anti-decubitus cushions market is not defined by a single breakthrough or a single driver. It is shaped by the interplay of clinical need, reimbursement structure, regulatory standards, material performance, and competitive concentration. Navigating that interplay successfully requires intelligence that is both granular and strategically framed.
This preview offers a view into the structure, scope, and strategic intent of our full market research. The complete report contains the full segmentation architecture, calibrated forecast tables, competitive benchmarking detail, and regulatory and reimbursement context needed to support board-level decisions, product planning, and market-entry strategy. For organizations preparing for the 2026–2032 growth cycle, the difference between reactive positioning and proactive strategy will come down to the quality of the intelligence beneath the decision. The full study is built to provide that foundation.
For detailed analysis of this topic, please visit the official page: Anti-decubitus Cushions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Mixer Market to Reach $344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Intelligence for the Industrial Mixer Market in 2026
In the complex landscape of industrial manufacturing, the humble mixer is often overlooked as a mere utility. Yet, it stands as a critical determinant of process efficiency, product consistency, and ultimately, profitability. As we move through 2026, the Industrial Mixer Market is undergoing a significant transformation driven by supply chain realignments, regulatory shifts, and evolving material requirements. For stakeholders operating in this space, understanding the trajectory of this market is not just an academic exercise—it is a imperative for strategic positioning.
This article serves as an executive overview of our latest comprehensive market research release. While we provide here the macroeconomic trends and competitive frameworks necessary for high-level planning, the complete intelligence required for tactical execution resides within the full report. Our objective is to equip decision-makers with the context needed to appreciate the value of deep-dive data, which is essential for navigating the forecast period from 2026 through 2032.
Market Trajectory and Growth Fundamentals
The industrial mixer sector has demonstrated resilience and consistent expansion over the past half-decade. Drawing on historical data from 2020 through 2025, the market has navigated pandemic-era disruptions to establish a robust growth baseline. Our analysis indicates that the total market revenue, denominated in USD Millions, has climbed steadily, culminating in a valuation of 215.0 million in the base year of 2025. This growth did not happen in a vacuum; it reflects the broader recovery in chemical, food, and pharmaceutical processing capacities globally.
Looking forward, the market is projected to maintain a healthy momentum. The compound annual growth rate (CAGR) during the forecast period is estimated at approximately 6.98 percent. This trajectory suggests a move from a recovery phase to a maturity phase characterized by steady capital expenditure in mixing technology. By 2032, the market size is expected to reach 344.8 million USD. Such figures underscore the sector's stability, but they also mask the volatility that exists beneath the surface. For a detailed breakdown of how these figures are constructed and the assumptions behind the forecast intervals, the full report provides the necessary granular validation.
Primary Report Scope and Coverage
Our research methodology is designed to capture the full spectrum of market activity. To ensure actionable intelligence, the study is segmented across multiple dimensions that matter most to equipment manufacturers, investors, and procurement officers.
- Temporal Coverage: The analysis covers historical performance from 2020 to 2025, providing a five-year baseline for trend analysis, followed by a seven-year forecast window extending to 2032. This long-view approach allows for the identification of secular trends distinct from cyclical fluctuations.
- Segmentation: The market is dissected by type, application, and region. Understanding which mixer technologies dominate specific use cases and where geographical demand is strongest is crucial for market entry or expansion strategies.
- Competitive Intelligence: The report maps the landscape of key players, analyzing market concentration and strategic positioning. With a CR3 of 24.6 percent and a CR5 of 26.2 percent, the market remains relatively fragmented, offering opportunities for consolidation or niche specialization.
While the aggregate numbers provide a pulse, the specific split values across regions and applications reveal the true anatomy of demand. In the full document, we detail the exact revenue contributions of each region and segment, allowing clients to pinpoint high-growth pockets without relying on estimated averages.
Competitive Landscape and Key Players
The competitive environment is characterized by a mix of established U.S. manufacturers leveraging supply chain narratives and international entrants focusing on cost and specialization. Our report profiles key companies that define the current market structure.
United States-Based Manufacturers
Companies headquartered in the Northeast, such as those in Hauppauge, New York, are currently emphasizing domestic manufacturing advantages. One such player, Charles Ross & Son Company, manufactures a broad portfolio including ribbon blenders, planetary mixers, high-shear mixers, and multi-shaft mixers. Their focus spans the food, chemical, pharmaceutical, and battery industries, with a strong offering on U.S.-built options and custom engineering. Another significant entity, INDCO, produces industrial mixers, dispersers, and tank agitators. Their value proposition centers on utilizing domestic raw materials to achieve the shortest lead times, serving the chemical, food, pharmaceutical, and paint industries.
Specialized and International Players
On the other side of the spectrum, Dynamix Agitators, based in the United States, specializes in custom-configured large- and mid-size industrial batch mixers and agitators. Their stronghold lies in mining, oil & gas, chemical, pharmaceutical, and distillery applications, where customization is paramount. Meanwhile, CO-NELE Mixer, headquartered in China, manufactures planetary concrete mixers, intensive mixers, granulators, and refractory mixers. They target construction, chemical, ceramic, and high-performance material processing, representing the competitive pressure from overseas manufacturers offering specialized material processing solutions.
Understanding the strategic moves of these entities is vital. The full report analyzes their market share, product portfolios, and strategic responses to market shifts, providing a benchmark for competitive assessment.
Industrial Mixer Market
Worldwide Industrial Kneader Market
Market Dynamics and Strategic Shifts in 2026
The year 2026 is proving to be a pivotal moment for industrial equipment procurement, largely driven by regulatory and supply chain factors. These dynamics are not merely background noise; they are reshaping the cost-benefit analysis of equipment purchases.
Regulatory Incentives and Supply Chain
One of the most significant developments is the introduction of the One Big Beautiful Bill Act of 2025. This legislation introduces powerful tax incentives for businesses investing in U.S.-made machinery in 2026. Key provisions include full cost expensing for qualifying equipment and Section 179 deductions. This creates a tangible financial advantage for sourcing domestic machinery over imported alternatives during this window. Charles Ross & Son Company highlighted this in a February 2026 analysis, noting that U.S.-built mixing equipment offers distinct advantages amid 2026 supply chain disruptions, tariffs, and regulatory changes.
Raw Material Volatility
Conversely, manufacturing costs remain sensitive to raw material fluctuations. Industrial mixer manufacturing depends heavily on raw materials like stainless steel and alloys. Fluctuations in raw material costs directly impact manufacturing expenses and supply chain volatility. INDCO noted in their June 2026 communications that domestic raw material sourcing is being leveraged to mitigate some of these risks, highlighting the importance of supply chain transparency when selecting vendors.
Compliance and Standards
Finally, compliance remains a barrier to entry and a differentiator. ROSS mixers, for instance, are designed to meet U.S. codes, safety standards, and regulations with compliance and UL-certified control systems for mixing processes. In highly regulated industries like pharmaceuticals and food processing, these certifications are non-negotiable, favoring established players with robust quality assurance frameworks.
Recent Company Developments and Market Signals
Recent corporate activities provide signals of where these companies believe the market is heading. In February 2026, Charles Ross & Son Company published a blog post analyzing the advantages of U.S.-built mixing equipment amid the aforementioned supply chain disruptions and regulatory changes. This move signals a strategy of aligning product offerings with the fiscal incentives available to their clients, effectively turning regulatory compliance into a sales proposition.
On the international front, CO-NELE Mixer showcased advanced planetary concrete mixers and intensive mixers at the UK Concrete Show 2026 in Birmingham, NEC Hall 17, during March 25-27. This presence at a leading concrete equipment exhibition indicates a continued push into the construction and heavy material processing sectors, emphasizing hardware innovation and direct customer engagement in key export markets.
The Value of Comprehensive Market Intelligence
While the trends outlined above provide a clear direction, making informed capital allocation decisions requires more than general observations. It requires precise data on market segmentation, exact regional valuations, and application-specific growth rates.
For example, knowing the total market size is useful, but knowing which region contributes the most to that size and how that share is shifting is what drives expansion strategy. Similarly, understanding that the Chemical Industry is a primary driver is different from knowing the exact revenue value and growth trajectory compared to Food & Beverage or Pharmaceutical sectors. The full report provides these specific percentage splits and value assignments across North America, Europe, Asia Pacific, Latin America, and Mideast & Africa, as well as detailed breakdowns for Solid-Solid, Solid-Liquid, Liquid-Gas, and Liquid-Liquid mixer types.
Furthermore, the report delves into the specific revenue contributions of applications such as Chemical, Food & Beverage, Pharmaceutical, and Others, allowing firms to identify their most lucrative target segments. With the market reaching a forecasted value of 304.05 million in 2030 and 325.44 million in 2031, the timing of entry and investment is critical.
Conclusion and Call to Action
The Industrial Mixer Market in 2026 is defined by a convergence of regulatory incentives, supply chain recalibration, and steady technological demand. The macroeconomic outlook is positive, with clear growth paths visible through 2032. However, the competitive intensity and regional nuances demand a level of detail that general industry knowledge cannot provide.
Our full market research report offers the depth required to validate strategy, optimize pricing, and identify partnership opportunities. It transforms raw data into actionable intelligence, ensuring that your organization is not just reacting to market changes but anticipating them. For access to the complete segmentation data, detailed competitor profiles, and the full financial forecast model, we invite you to engage with the full study. In a market of 344.8 million USD in potential annual revenue by the end of the decade, the cost of incomplete information is far higher than the investment in clarity.
For detailed analysis of this topic, please visit the official page: Industrial Mixer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com