

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Fiber Cement Market Hits $22.45 Billion in 2025, 4.08% CAGR Forecast to 2032

The Fiber Cement Market in 2026 A Strategic Crossroads for Construction and Manufacturing Leaders
The global fiber cement market stands at a decisive inflection point as it moves through the 2026-2032 forecast horizon. An economy that reached 22.45 billion USD in 2025 is not merely expanding; it is restructuring around material innovation, regulatory realignment, and shifting end-use expectations. For executives, procurement leaders, and investors, the question is no longer whether fiber cement will grow, but how capital, capacity, and competitive positioning should be allocated to capture durable advantage. Our latest Fiber Cement Market study translates these macro trajectories into an actionable decision framework, giving leadership teams the precision they need to plan capacity, pricing, distribution, and product architecture through the end of the decade.
This research is built for those who must act, not merely observe. The analysis spans historical performance from 2020 to 2025, establishes a 2025 base year, and projects forward to 2032 with disciplined scenario logic. Total revenue is tracked in USD across a billion-unit scale, reflecting a maturation pathway that moves from 22.59 billion USD in 2026 toward 29.71 billion USD in 2032. That trajectory implies a compound annual growth rate of 4.08 percent, a pace that signals sustained demand while simultaneously exposing the operational friction points that can erode margin if left unmanaged. The study treats this growth as a strategic asset and a risk surface, mapping both the upside and the pressure points that will shape enterprise outcomes over the next seven years.
What makes this intelligence especially valuable in 2026 is its timing. The industry is navigating a convergence of forces that will test supply chain resilience, cost discipline, and product differentiation at the same time. Raw material price volatility for cement and cellulose is reshaping input economics, while labor cost escalation in high-cost states continues to push up total project cost for siding and exterior applications. At the same time, regulatory attention is intensifying, with the United States Environmental Protection Agency issuing guidance on safe use and exposure to fibrous silicate minerals in manufacturing, and the government of British Columbia proposing additional safety measures for fibrous silicate minerals in plants. These developments are not peripheral news; they alter compliance costs, operational standards, and the speed at which new capacity can be brought online. The report integrates these realities into a single operational lens so that leaders can forecast not just demand, but the true cost and feasibility of serving that demand.
Why This Study Matters for 2026 Enterprise Decisions
Strategic planning in 2026 requires more than a top-line growth assumption. It requires a granular view of where value is created and where it leaks. The market’s structure is concentrated enough to reward scale, yet dynamic enough to open opportunities for disciplined regional and product plays. With the top three competitors accounting for 60.0 percent of market share and the top five reaching 70.0 percent, the competitive field is clearly tiered. That concentration changes the logic of entry, expansion, and defense. Organizations must understand which segments carry the greatest margin potential, which geographies offer the most efficient route to volume, and which product forms align with emerging specification trends. This report is designed to answer those questions with a level of clarity that supports capital deployment and go-to-market strategy, without forcing leaders to guess at the underlying segmentation logic.
The study is also timed to support decisions that depend on near-term visibility. Forecasts begin at 22.59 billion USD in 2026 and step upward through 24.18 billion USD in 2027, 24.52 billion USD in 2028, 25.83 billion USD in 2029, and 27.95 billion USD in 2030, before reaching an end-of-horizon range that closes at 29.24 billion USD in 2031 and 29.71 billion USD in 2032. These figures are not presented as abstract numbers. They are used to anchor scenario planning, identify when demand intensifies, and highlight the intervals in which competitors are most likely to adjust capacity, pricing, or distribution. For a procurement director monitoring cellulose and cement cost exposure, that cadence matters. For a regional business unit evaluating whether to expand distribution, it matters even more.
Inside the Report Architecture and Practical Utility
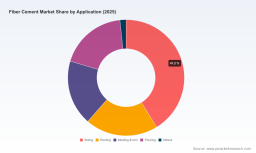
The study is organized to move from market structure to execution, ensuring that insights can be operationalized rather than simply read. It examines the market through multiple lenses, including type, application, and region, so that users can map growth into the specific business lines and territories that matter most to their organization. The type view addresses the product architecture that defines sourcing, formulation, and differentiation strategies. The application view connects demand to functional use cases in siding, roofing, molding and trim, flooring, and other end markets, helping teams understand where specification momentum and replacement cycles are likely to shape volume. The regional view supports distribution planning, plant siting logic, and competitive targeting by showing where demand is accumulating and where saturation or cost pressure may alter the route to profit.
Beyond segmentation, the report translates market structure into competitive strategy. It profiles the organizations that are defining the pace of the industry, from established building-product leaders to regional specialists with strong local execution. The analysis does not stop at corporate description. It examines how each player’s product focus, manufacturing footprint, and market posture position them for the next phase of growth, and it identifies where concentration creates either a defensive moat or an incentive for disruption. This company-level intelligence is especially useful for teams evaluating partnership opportunities, competitive threats, or potential acquisition targets, because it relates each organization’s specific offerings to the larger demand architecture.
The study also integrates a forward-looking set of industry developments that carry direct operational implications. Recent activity shows how fast the competitive and standards environment can change. In February 2025, James Hardie Building Products Inc. unveiled new and expanded Hardie products, including Artisan Trim, at the NAHB International Builders Show, signaling continued product-line broadening in response to specification opportunities. In May 2025, the company announced a three-year exclusive distribution agreement with Davidson Homes for Hardie siding and trim products, an example of how channel control and builder relationships are becoming central to share defense and growth. Later, in October 2025, ICC-ES proposed new criteria for fibre-cement siding complying with ASTM C1186 or ISO 8336 in combustible and noncombustible construction, an indication that the regulatory and testing environment is tightening around material performance and application rules. Each of these events is treated as a strategic signal, not just an industry headline, and the report explains what they imply for product roadmaps, channel strategy, and compliance readiness.
Equally important, the report provides a practical view of the cost and risk environment. It addresses raw material price fluctuations for cement and cellulose that raise production costs, and it places those pressures within the broader context of labor and total project economics. It also reflects the regulatory landscape shaping manufacturing operations, including EPA guidance on safe use and exposure to fibrous silicate minerals and British Columbia’s proposed additional safety measures for plants. These inputs are woven into the analysis so that readers can assess the full stack of operational constraints, from input procurement to worker safety, compliance documentation, and final installed cost. For organizations that must justify capital expenditure or renegotiate supply terms, that integrated view is what turns information into decision support.
Competitive Positioning and the Shape of Industry Leadership
The competitive map in this study is built to show where advantage is durable and where it is contestable. The market’s concentration profile means that a limited number of firms hold substantial influence over pricing expectations, specification penetration, and channel relationships. At the same time, the breadth of profiled organizations indicates that leadership is not monolithic. Different companies compete through different product forms, end-use strengths, and regional reach, which creates a market in which specialization can still outperform undifferentiated scale in the right context.
James Hardie Industries PLC, headquartered in Ireland, continues to anchor the market with a focused offering built around Hardie fiber cement siding and backer boards. Its recent product unveiling and exclusive distribution agreement underscore a strategy that combines product expansion with channel exclusivity, reinforcing brand preference and builder-level pull. ETEX Group, based in Belgium, competes with fiber cement boards and sheets, positioning around building-envelope and construction use cases where board performance and consistency matter. Saint-Gobain, headquartered in France, brings a wider construction-products footprint and offers fiber cement products for construction applications, leveraging scale and technical breadth across multiple building systems. Nichiha Corporation, based in Japan, emphasizes high-performance fiber cement panels and siding, aligning with markets that value precise engineering and exterior durability. Cembrit Holding A/S, from Denmark, focuses on fiber cement siding and exterior products, supporting architectural and weather-exposed applications where finish and long-term performance drive specification decisions.
Fiber Cement Market
Regional specialists and application-focused players round out the competitive landscape and add important nuance to market strategy. Allura USA operates in the United States with fiber cement siding products, while American Fiber Cement Corporation provides boards and sheets for construction-related demand. Elementia Materials contributes fiber cement products for construction from Mexico, and Everest Industries Limited supports board demand from India. CSR Limited extends fiber cement products from Australia, and Plycem Corporation competes in the U.S. market with siding and boards. Swisspearl Group, headquartered in Switzerland, emphasizes fiber cement cladding and siding, aligning with architectural exterior solutions. Together, these organizations illustrate that the market is not only contested by global leaders but also shaped by companies that win through regional density, product specificity, or cost-efficient manufacturing.
This diversity is strategically meaningful. For an incumbent, it highlights the need to protect specification share, strengthen distribution agreements, and reduce exposure to input and compliance cost shocks. For a challenger or regional operator, it suggests that targeted product forms, localized service, and selective channel partnerships can create defensible positions even in a concentrated market. The study connects these competitive realities to the segmentation logic described earlier, allowing readers to see where each company’s strengths intersect with demand pools and where gaps may open for new investment or partnership.
Strategic Implications for Capital, Supply Chain, and Growth Planning
The most valuable use of this research is to convert market direction into internal priorities. In a market projected to expand from 22.59 billion USD in 2026 to 29.71 billion USD in 2032, the organizations that outperform will be those that treat growth as a systems problem. They will align product architecture with specification momentum, build supply chains that can absorb raw material volatility without eroding margin, and prepare for regulatory change as part of operational planning rather than as an afterthought. They will also recognize that construction-sector demand is increasingly shaped by project economics, including labor and material cost dynamics in high-cost regions, which can alter both replacement cycles and new-build adoption.
Because the report keeps its most precise segmentation detail and company-level scenario data inside the full publication, it preserves the analytical tension that makes the study useful. Leaders can see the shape of the market, understand the forces moving it, and identify where strategic action matters most, while reserving the deeper quantitative detail for the moment they are ready to commit capital or revise a commercial plan. That structure is intentional. It allows executives to build confidence in the research rigor and then retrieve the specific numbers, split data, and playbook-level recommendations that support board-level decisions.
Fiber Cement Board Market
For 2026, the strategic takeaway is straightforward. Fiber cement is expanding within a market that is large enough to matter and structured enough to reward disciplined strategy. The firms that will benefit most are those that can read the market not just as a growth curve, but as a map of concentration, regulation, input risk, product form, and application demand. This report provides that map. It gives decision-makers the context to see where the market is heading, the competitive logic to understand who is gaining ground, and the operational grounding to act with confidence.
The full study goes further by delivering the detailed segmentation, regional and application-level revenue context, and company-specific strategic readouts that support precise planning. Those elements are where the research moves from directional insight to executable intelligence. Readers looking to lock in capacity strategy, refine pricing models, prioritize channels, or evaluate competitive exposure will find the complete dataset and scenario framework essential. For teams preparing for the 2026-2032 window, this publication offers both the high-level view needed to set direction and the deeper market intelligence required to execute it.
For detailed analysis of this topic, please visit the official page: Fiber Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com