

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Paint Protection Film Market Report: $655.5M in 2025, 6.4% CAGR to $1.01B by 2032

Navigating the Next Wave of Growth: Strategic Insights into the Paint Protection Film Market
The global automotive aftermarket and surface protection industries are undergoing a phase of rapid evolution, driven by heightened consumer awareness of asset preservation, advancements in polymer technology, and a recovering global vehicle production landscape. As businesses look toward 2026 and beyond, the Paint Protection Film (PPF) market stands out as a critical arena for strategic investment and operational adjustment. PW Consulting's latest in-depth market research offers a comprehensive roadmap for stakeholders aiming to capitalize on the projected expansion of this sector.
This analysis serves as an introduction to the broader strategic intelligence contained within our full report. By examining historical trajectories, growth vectors, and competitive dynamics, we highlight the necessity of precise data-driven decision-making in a market characterized by both robust demand and intricate manufacturing complexities.
Market Trajectory and Financial Outlook
Understanding the macroeconomic flow of the Paint Protection Film industry is the first step toward building a resilient business strategy. Our research tracks revenue trends from 2020 through the base year of 2025, providing a solid foundation for forecasting the period from 2026 to 2032. The market has demonstrated consistent resilience, recovering from global supply chain disruptions to establish a steady upward climb in valuation.
TPU Type Paint Protection Film Market
In 2020, the global market began its recovery phase with a valuation reflecting the initial post-pandemic adjustments. Over the subsequent five years, the industry has consolidated its growth, reaching a significant market size by 2025. Looking forward, the momentum is expected to accelerate. The forecast period indicates a compound annual growth rate (CAGR) that suggests sustained expansion rather than speculative spikes. This growth is underpinned by increasing vehicle ownership in emerging markets and the rising adoption of protective films in high-value automotive segments across developed regions.
Strategic planners must note that while the top-line figures indicate healthy growth, the underlying drivers vary significantly by product type and application vertical. The transition from basic protection to premium, self-healing solutions represents a shift in value capture within the supply chain. Our report dissects these value pools without exposing sensitive segmentation data in this summary, ensuring that the full analysis remains a proprietary asset for our clients.
Technology and Material Dynamics
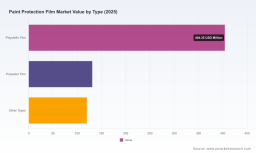
The core of the PPF market lies in material science. The industry has moved beyond simple adhesive films to sophisticated polyurethane-based solutions that offer self-healing properties, hydrophobicity, and exceptional clarity. According to industry market data, polyurethane base films maintain a dominant share in global Paint Protection Film production. This dominance is driven by the material's ability to recover from minor abrasions, thereby extending the aesthetic life of vehicle paint.
Furthermore, TPU films are increasingly recognized as the primary raw material for advanced self-healing and hydrophobic Paint Protection Film. Manufacturers investing in aliphatic TPU technologies are positioning themselves to capture the premium segment of the market, where performance and longevity justify higher price points. The interplay between raw material costs, technological capabilities, and end-user demand creates a complex landscape that requires careful navigation.
Our research details the technical specifications and manufacturing capabilities required to compete at the highest levels. From the USA-based production of aliphatic TPU films to the high-volume manufacturing hubs in Asia, the supply chain is becoming increasingly specialized. Understanding these technological nuances is critical for companies deciding whether to vertically integrate, partner with film manufacturers, or focus solely on distribution and installation.
Key Technical Trends Influencing Strategy
- Self-Healing Capabilities: The demand for films that can recover from stone chips and scratches without visible damage is reshaping product development roadmaps.
- Hydrophobic and Oleophobic Coatings: Enhanced surface energy properties are becoming a key differentiator, reducing maintenance costs for end-users and adding value to installation services.
- Finish Variety: While high gloss remains standard, there is a growing niche for matte and satin finishes, catering to customized automotive aesthetics.
- Installation Efficiency: Pressure-sensitive adhesives and dry-install technologies are being refined to reduce installation time and waste, impacting service center throughput.
Competitive Landscape and Market Concentration
The Paint Protection Film market is characterized by a mix of established multinational corporations and specialized niche manufacturers. Market concentration data indicates a moderately consolidated environment, where a significant portion of revenue is held by key players who have secured strong distribution networks and brand recognition. The CR3 and CR5 metrics highlight the influence of top-tier competitors, yet there remains ample room for innovation-driven entrants.
Geographic diversity in headquarters does not necessarily dictate market reach. Many leading manufacturers based in the United States maintain a global footprint, while powerful manufacturing capacities located in China supply a vast portion of the global demand. This dynamic creates a competitive tension between localized manufacturing benefits, such as faster logistics for North American installers, and cost-effective production scales available in other regions.
Profile of Market Leaders
Our report provides detailed profiles of the entities shaping the industry. These companies are not merely selling film; they are selling comprehensive protection ecosystems.
- LEGEND PPF: With a focus on North American installers, this company manufactures aliphatic TPU-based Paint Protection Film in the USA, emphasizing supply chain localization and support for regional installation networks.
- XPEL Inc.: Known for self-healing Paint Protection Film products, XPEL designs solutions specifically to protect against rock chips, scratches, and scuffs, maintaining a strong brand identity around durability and aesthetic preservation.
- 3M Company: Leveraging its vast industrial portfolio, 3M produces Scotchgard Pro Series Paint Protection Film lines, integrating PPF into a broader suite of automotive protection offerings.
- STEK USA: This manufacturer focuses on hydrophobic and self-healing Paint Protection Film with extreme clarity and depth, offering multiple finishes to cater to diverse consumer preferences.
- UPPF-USA: As a pioneer in advanced Paint Protection Film technology, UPPF-USA maintains control over every product line with in-house manufacturing, a legacy dating back to 1996.
- Pure PPF: Leading the market in bespoke premium colored and clear Paint Protection Film, this company targets the high-end customization segment where personalization is paramount.
- Ceramic Pro: Representing the next evolution in automotive surface protection and durability, Ceramic Pro combines film technology with coating systems to offer comprehensive surface solutions.
- LLumar Films: Their Platinum Paint Protection Film line is often combined with window tinting and ceramic coatings, creating bundled value propositions for installers and consumers.
- TeckWrap International: Specializing in pressure-sensitive adhesive Paint Protection Film, TeckWrap integrates PPF as part of broader automotive film offerings, recently demonstrating dry-install Color Paint Protection Film technology.
- ORAFOL Europe GmbH: Based in Germany, ORAFOL presents an advanced Paint Protection Film range available in high gloss or matte finishes with unmatched clarity, serving the European and global markets.
- Kehui: Located in Shanghai, Kehui positions itself as a global leader in Paint Protection Film manufacturing with a focus on automotive-grade TPU films.
- Sino Vinyl: Based in Guangzhou, this company manufactures High-performance Paint Protection Film to top standards, competing on quality and consistency in the Asian manufacturing sector.
- GSWF: From Zhejiang, GSWF offers Paint Protection Film products as part of high-quality automotive film offerings, targeting both domestic and export markets.
- REEDEE: Based in Guangdong, REEDEE emphasizes Paint Protection Film manufactured to the highest possible standards, focusing on quality control in production.
- Livinyl: Also in Guangdong, Livinyl stands as one of the key manufacturers in China, contributing to the region's significant output in the global PPF supply chain.
Recent Strategic Developments and Industry Context
The competitive landscape is not static. Recent developments indicate that innovation and visibility at major industry events are critical for maintaining market position. Companies are actively showcasing new technologies to gain share and signal technological leadership.
Paint Protection Film Market
For instance, in 2025 and 2026, several key players participated in major exhibitions such as SEMA and Autocosmetica. Ceramic Pro showcased groundbreaking innovations in automotive surface protection including Paint Protection Film at SEMA 2025 with new product lineups and unreleased items. Similarly, LLumar Films participated in the SEMA Show with demonstrations of immersive Paint Protection Film, window film, and ceramic coatings. These events serve as barometers for industry direction, highlighting the convergence of film, coatings, and tinting technologies.
Furthermore, TeckWrap International demonstrated dry-install Color Paint Protection Film technology at Autocosmetica 2026, signaling a shift towards easier installation processes. ORAFOL presented an advanced Paint Protection Film range at the ORAFOL + ISA tradeshow in Orlando. These exhibitions underscore the importance of real-time intelligence gathering. Our report captures these developments to help clients anticipate competitor moves and identify potential partnership opportunities or threats.
Regulatory and Standards Environment
Beyond competition, regulatory frameworks are shaping the market. The industry is seeing increased attention on material standards and environmental compliance. For example, the Bureau of Indian Standards (BIS) issued PPF and polymer standards, alongside UNEP PPF and polymer standards. These regulations impact market entry requirements and product specifications, particularly in regions with stringent quality controls. Companies must ensure their products comply with local and international norms to avoid barriers to trade. Our analysis includes a review of these regulatory dynamics to assist in compliance planning and risk assessment.
Demand Drivers and Application Segments
The growth of the Paint Protection Film market is propelled by diverse application areas, though the automotive sector remains the dominant force. The need to protect vehicle resale value and aesthetics in an environment of increasing traffic density and road debris is a primary driver. However, the utility of PPF extends beyond personal vehicles.
Our research explores the breadth of applications, noting that while Automotive & Transportation leads in revenue contribution, other sectors are emerging. The Electrical & Electronics sector utilizes protective films for sensitive equipment, and various Other Applications present niche opportunities. The versatility of PPF materials allows for adaptation across these verticals, provided manufacturers can tailor properties such as flexibility, adhesion, and clarity to specific use cases.
Strategic focus should be placed on understanding the specific pain points in each application segment. For automotive, it is durability and aesthetics. For electronics, it may be protection against environmental stressors without interfering with functionality. Our full report segments the market to reveal where the highest value growth opportunities lie, helping clients allocate resources efficiently.
Strategic Recommendations for 2026 Decision Makers
As we move through 2026, stakeholders in the Paint Protection Film market must adopt a proactive stance. The convergence of material innovation, competitive pressure, and regulatory changes requires a holistic view of the industry. Below are key strategic areas that our research highlights for consideration:
- Supply Chain Resilience: Given the geographic diversity of manufacturers, companies should evaluate their supply chain risks. Diversifying sources or securing long-term contracts with key TPU and polyurethane film producers can mitigate volatility.
- Technology Investment: Investing in or partnering with companies that possess advanced self-healing and hydrophobic technologies is crucial. The market is shifting towards premium solutions, and legacy products may face margin compression.
- Market Positioning: Understanding the competitive concentration helps in defining positioning. Whether aiming to compete as a premium brand like XPEL or STEK, or as a cost-effective manufacturer leveraging scale, clarity on value proposition is essential.
- Regional Compliance: Keeping abreast of standards such as those issued by BIS and UNEP is necessary for global expansion. Non-compliance can result in significant market access delays.
- Aftermarket Integration: The value of PPF is often realized through installation quality. Building strong relationships with installers or investing in training programs can enhance product reputation and reduce warranty claims.
Conclusion
The Paint Protection Film market is poised for significant growth, driven by technological advancements and a global increase in vehicle protection awareness. However, capturing this growth requires more than just general market knowledge. It demands precise insights into segmentation, competitive moves, and material trends.
PW Consulting's comprehensive report on the Paint Protection Film Market offers the depth required to navigate this complex landscape. From detailed revenue forecasts to granular analysis of key players and raw material dynamics, this research is designed to empower strategic decision-making in 2026 and beyond. The overview provided here scratches the surface of the intelligence available. To unlock the full potential of your strategy with accurate data, segmentation details, and actionable recommendations, we invite you to access the complete study.
Stay ahead of the curve by grounding your decisions in verified, in-depth industry intelligence. The future of surface protection is clear, and the opportunities for those prepared are substantial.
For detailed analysis of this topic, please visit the official page: Paint Protection Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com