

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Dental 3D Printer Market Hits $143.76M in 2025, Projects 6.98% CAGR to 2032
By pmarketresearch, 2026-09-15
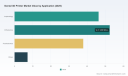
Strategic Horizons in the Dental 3D Printer Market: A 2026 Decision-Maker's Guide
The Inflection Point: Why 2026 Demands Precision Intelligence
The dental technology sector is navigating a transformative phase where digital adoption is no longer optional but existential. For stakeholders operating in orthodontic labs, oral surgery centers, and prosthetic manufacturing, the transition from traditional methodologies to additive manufacturing represents a fundamental shift in workflow efficiency and patient outcomes. However, the pace of innovation has outstripped the ability of many organizations to interpret market signals accurately. This is where PW Consulting's latest Dental 3D Printer Market Research becomes a critical asset for strategic planning.
As we move into 2026, the market is characterized by a complex interplay of technological maturity, regulatory advancements, and evolving reimbursement frameworks. Our analysis indicates that the global revenue generated by this sector is projected to reach approximately 158.83 Million USD in 2026, reflecting a steady trajectory from the 143.76 Million USD recorded in the base year of 2025. This growth is not merely linear; it is underpinned by a Compound Annual Growth Rate (CAGR) of roughly 6.98% over the forecast period extending to 2032. Such figures suggest a robust expansion, yet they mask the nuanced volatility present within specific technology stacks and application verticals.
Decision-makers in 2026 face a bifurcated challenge. First, they must allocate capital towards hardware and material infrastructure that promises longevity amidst rapid obsolescence. Second, they must navigate a regulatory environment that is tightening around biocompatible materials. Our report is designed to dissect these layers, offering a roadmap that transforms raw data into actionable investment theses. We do not simply present growth numbers; we contextualize them against the backdrop of competitive intensity and technological differentiation.
Market Trajectory and Structural Dynamics
Understanding the historical context is vital for projecting future performance. The period from 2020 to 2025 established the foundational demand for digital dentistry. Revenue figures climbed from 98.45 Million USD in 2020 to 133.84 Million USD by 2024, signaling accelerated adoption rates among dental practices and laboratories. The jump to 143.76 Million USD in 2025 consolidates this trend, indicating that digital printing is transitioning from a premium novelty to a standard operational utility.
Looking forward through the forecast period of 2026 to 2032, the market is expected to surpass 224.42 Million USD by the end of the cycle. This upward trajectory is fueled by several key dynamics. Technological advancements in printing speed and resolution are reducing chairside times, making same-day restorations increasingly viable. Furthermore, the integration of automated workflows is lowering the skill barrier for technicians, thereby expanding the addressable market beyond high-volume specialty labs to smaller general practices.
However, growth is not uniformly distributed. The market concentration reveals a moderately fragmented landscape. The top three companies hold a combined share of 24.6%, while the top five control 26.2%. This indicates that while key players dominate specific niches, there is ample room for innovation-driven entrants and regional specialists to capture value. For a corporate strategist, this fragmentation suggests both partnership opportunities and acquisition targets that may not be immediately apparent from surface-level revenue data.
Key structural drivers identified in our deep dive include:
- Regulatory Catalysts: Recent FDA 510(k) clearances for specific resin formulations are unlocking new application areas, particularly in fixed hybrid dentures and temporary restorations, reducing liability risks for adopters.
- Reimbursement Evolution: Advanced reimbursement frameworks in key developed markets are incentivizing the use of digital restorations, directly influencing procurement budgets and ROI calculations for dental practices.
- Workflow Integration: The shift towards open material libraries and interoperable software ecosystems is reducing vendor lock-in, empowering labs to optimize cost structures without sacrificing material biocompatibility.
Competitive Arena: Innovation vs. Scale
The competitive landscape is defined by a tension between established industrial giants and agile specialized innovators. Our analysis covers the strategic positioning of key entities such as SprintRay , Formlabs , Asiga , LuxCreo , 3D Systems , Stratasys , Carbon , and Ackuretta . Each player brings a distinct value proposition to the 2026 marketplace, and understanding these nuances is essential for supply chain negotiation and technology selection.
SprintRay continues to strengthen its chairside presence with systems like the Pro 2 and Midas, specifically targeting the workflow for crowns, bridges, and surgical guides. Their strategic focus on biocompatible resins aligns with the trend towards in-office production. Similarly, Formlabs maintains a strong foothold with its Form 4B SLA printers, appealing to labs requiring versatile capabilities for models and temporary restorations. Their expansion into Premium Teeth Resin demonstrates a commitment to material science as a competitive moat.
In the high-precision segment, Asiga differentiates through its open material library, catering to labs that prioritize restoration quality and flexibility over closed ecosystems. Meanwhile, LuxCreo is pushing the boundary of speed and automation with its iLux Pro system, aiming to streamline the production of clear aligners with FDA-cleared workflows for same-day orthodontic appliances. This focus on automation addresses the growing labor shortage in dental technology sectors.
On the industrial side, 3D Systems and Stratasys leverage broad portfolios. 3D Systems markets the NextDent 5100 and Jetted Denture Solution, emphasizing multi-material capabilities for dentures and guides. Stratasys offers PolyJet multi-material printing with the J5 DentaJet, focusing on realistic anatomical models and complex restorations. Carbon introduces flexible solutions with their FP3D resin for removable partial dentures, addressing comfort and functionality needs. Ackuretta rounds out the competitive field with dedicated manufacturing solutions for restorations and models.
Metal 3D Printer Market
Recent developments highlight the speed of innovation. In mid-2025, 3D Systems achieved full commercial release of their NextDent Jetted Denture Solution for multi-material monolithic dentures, marking a significant step in automation. Shortly after, Carbon announced the full commercial availability of FDA-cleared FP3D resin for flexible removable partial dentures in North America. These milestones are not just product launches; they are indicators of where the market value is shifting—towards materials that offer enhanced mechanical properties and workflow solutions that reduce human intervention.
Regulatory and Reimbursement Pressures Shaping 2026
The regulatory environment is perhaps the most critical variable for risk assessment in 2026. The clearance of specific materials dictates what can be printed, where it can be used, and the liability exposure for the provider. For instance, the FDA 510(k) clearance of SprintRay's OnX Tough 2 resin for fixed hybrid dentures and Formlabs' Premium Teeth Resin for temporary crowns and veneers opens specific revenue streams that were previously restricted or required alternative manufacturing methods. Similarly, the clearance of 3D Systems' NextDent Jetted Denture Solution validates multi-material monolithic denture printing, potentially disrupting traditional denture fabrication lines.
These regulatory wins are compounded by reimbursement dynamics. In North America, advanced reimbursement frameworks for digital restorations are driving the largest share of market activity. This regional advantage creates a halo effect, encouraging adoption in other regions but also highlighting the dependency of market growth on policy stability. Our report provides a granular look at how these regulatory and reimbursement signals interact with technology adoption curves, allowing executives to anticipate compliance costs and reimbursement delays that could impact cash flow.
What Our Full Report Reveals: Beyond the Headlines
While the macro trends provide a comforting narrative of growth, the strategic value of PW Consulting's full report lies in the granular intelligence required to execute on these trends. The overview provided here sets the stage, but the comprehensive document offers the tactical data necessary for board-level decisions. Subscribers to our full research access detailed breakdowns that clarify where capital should be deployed for maximum return.
Specifically, the full edition delivers actionable intelligence on:
- Technology Segmentation: Detailed analysis of how SLA, DLP, LCD, and other printing technologies are allocating market share, allowing you to identify which hardware platforms are gaining traction in specific clinical workflows.
- Application Verticals: Deep dives into how implantology, orthodontics, prosthodontics, and other applications are contributing to revenue growth, helping you align your product offerings or service lines with the highest growth segments.
- Regional Performance: Nuanced insights into how North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa are evolving differently, critical for supply chain localization and market entry strategies.
- Vendor Benchmarking: Comparative assessments of the key players mentioned above, evaluating their R&D pipelines, patent portfolios, and strategic partnerships relative to their market position.
In an environment where 6.98% CAGR represents millions in potential value, guessing is not a strategy. The difference between capturing market share and losing relevance often comes down to understanding the subtle shifts in material science regulations and the specific adoption rates of chairside versus lab-side printing solutions. Our report removes the guesswork.
Conclusion: Aligning Strategy with Market Reality
The Dental 3D Printer Market in 2026 is a landscape of opportunity tempered by complexity. The projected revenue of 158.83 Million USD this year is a testament to the sector's vitality, but it is the underlying dynamics—regulatory clearances, reimbursement shifts, and competitive technological races—that will determine individual company success. As the market matures towards 2032, the ability to adapt to open material ecosystems, leverage automated workflows, and navigate multi-material printing validations will separate leaders from followers.
Dental 3D Printer Market
PW Consulting's research is designed to equip you with the clarity needed to navigate this evolution. By integrating historical performance data with forward-looking scenario analysis, we provide the intelligence necessary to optimize investment portfolios, refine go-to-market strategies, and mitigate regulatory risks. The growth is real, but the path to capturing it requires precision. We invite you to explore the full depth of our findings to ensure your strategic decisions are grounded in comprehensive, expert-validated data.
For detailed analysis of this topic, please visit the official page: Dental 3D Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Bimetallic Bandsaw Blade Market Hits $555M in 2025, Reaching $859.9M by 2032
By pmarketresearch, 2026-09-15
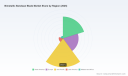
Unlocking Precision: Strategic Insights into the Bimetallic Bandsaw Blade Market Outlook 2026–2032
In the high-stakes environment of industrial metalworking, tool selection is not merely a procurement decision—it is a strategic lever that influences operational efficiency, cost structures, and ultimately, competitive advantage. As we navigate the industrial landscape of 2026, the bimetallic bandsaw blade sector stands at a critical inflection point. Driven by shifting raw material economics, accelerated automation, and stringent energy mandates, the market presents a complex array of opportunities for stakeholders who can look beyond surface-level trends.
PW Consulting is pleased to unveil our latest comprehensive market research study focused on the Global Bimetallic Bandsaw Blade Market. This report is designed specifically for executive decision-makers, procurement strategists, and industry investors who require a granular understanding of the forces shaping this sector. Below, we provide a strategic overview of the market trajectory, the competitive landscape, and the dynamic risks and opportunities that define the landscape for the remainder of the decade.
Market Trajectory and Growth Trajectory
The bimetallic bandsaw blade market has demonstrated resilience and consistent expansion over the past half-decade. Reflecting on the historical performance from 2020 through 2025, the market has maintained a steady upward curve, signaling a fundamental demand shift rather than a temporary spike. The market valuation, measured in USD Million, has grown substantially from its baseline in 2020 to reach an estimated 555.0 million in the base year of 2025.
Looking toward the forecast horizon spanning 2026 to 2032, the momentum shows no signs of abating. The market is projected to reach approximately 596.01 million in 2026, accelerating towards a forecast endpoint of 859.9 million by 2032. This trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 6.5 percent during the forecast period. For corporate planners, this CAGR suggests a mature yet persistent growth environment where market share gains require deliberate strategy rather than passive participation.
Bimetallic Bandsaw Blade Market
Band Saw Blades Market
It is crucial to note that while these top-line figures establish the macro context, the true value lies in understanding the velocity of growth across different vectors. Our full report dissects these figures to reveal where the pressure points lie, helping organizations align their capacity and investment strategies with the highest growth corridors.
Segmentation Dynamics and Operational Implications
Navigating the market requires a nuanced view of product types and application verticals. The landscape is broadly defined by distinct blade technologies, each catering to specific performance requirements. High-speed steel variants continue to hold significant relevance, particularly where hardness and wear resistance are paramount. Simultaneously, carbide-tipped solutions are carving out a substantial niche, driven by demands for extended tool life and reduced downtime in high-volume production settings.
On the application front, the demand is diversified across multiple metal categories. Steel cutting remains a dominant driver of consumption, reflecting the ubiquity of steel in industrial infrastructure and manufacturing. However, the market is not monolithic. Aluminum cutting applications represent a significant volume, benefiting from the lightweighting trends in automotive and aerospace sectors. Cast iron cutting, while more specialized, remains critical for heavy machinery maintenance and foundry operations. Additionally, a range of other specialized applications contributes to the overall demand mix.
For procurement leaders, the strategic implication is clear: a one-size-fits-all inventory approach is inefficient. The interplay between blade type, substrate material, and production volume creates a matrix of cost-performance trade-offs. Our analysis provides the detailed breakdown necessary to optimize inventory mix and reduce total cost of ownership, but we leave the specific allocation percentages to the proprietary sections of our full dataset.
Competitive Landscape: Navigating a Consolidated Arena
The bimetallic bandsaw blade market is characterized by a moderately high degree of concentration, with a handful of established players commanding the majority of the market share. Our analysis indicates that the top three competitors hold a combined market share of approximately 70 percent, while the top five extend this concentration to 75 percent. This consolidation suggests that barriers to entry remain significant, and competitive moats are built on technology, brand reputation, and global distribution networks.
Several key enterprises define the current competitive landscape. Lenox Tools, headquartered in the United States, remains a prominent manufacturer specializing in bimetallic bandsaw blades for metal cutting applications. Similarly, M.K. Morse Company continues to produce bi-metal band saw blades, including their Independence series designed for high-production metal cutting. DoALL Sawing Products operates as both a supplier and manufacturer, focusing on industrial metal sawing requirements.
Geographic diversity is evident among the key players. In Europe, Wikus, based in Germany, manufactures bimetal bandsaw blades featuring their proprietary X3000 modified cutting material for alloyed steel backing. L.S. Starrett Company, another US-based producer, is recognized for high-performance bi-metal bandsaw blades with advanced tooth geometry and geometry optimization. Bahco, hailing from Sweden, specializes in bi-metal and carbide bandsaw blades, including the Sandcut and Sandflex series for production cutting. Eberle, also from Germany, manufactures duoflex VTX bi-metal bandsaw blades tailored for stainless steel, high-speed steel, and cast iron.
Further expansion of the competitive field includes Simonds International LLC, a US provider offering blades for production, general-purpose, and structural steel cutting. In Asia, Bichamp Cutting Technology Co Ltd has emerged as a Chinese producer with a focus on high-performance metal cutting. Honsberg, another German manufacturer, supplies bimetal bandsaw blades for various industrial applications.
Recent activities among these players highlight a focus on innovation and market presence. For instance, throughout 2025, Wikus maintained a strong visibility strategy, participating in trade shows such as Blechexpo 2025 where they highlighted bimetal bandsaw blades and sawing solutions for industrial sheet metal processing. Earlier in the same year, they presented the GENERO bimetal bandsaw blade at the LIGNA trade fair, targeting wood industry applications, and hosted the BDS Band Saw Blade Day 2025 focused on innovation for efficient steel processing. These moves underscore a competitive environment where product diversification and technological demonstration are key tactics.
Strategic Takeaways for Stakeholders
The high concentration levels imply that pricing power may rest with the incumbents, but it also suggests that partnerships and supply chain security are vital. Clients relying on a single source for critical cutting tools face risk exposure. Conversely, the presence of specialized manufacturers like Bichamp indicates potential opportunities for cost optimization or specialized customization in the Asia Pacific region, provided quality and reliability standards are met. Our report delves deeper into the strategic positioning of each key company, analyzing their recent developments and potential market moves.
Industry Dynamics and Macro Forces
Beyond the baseline figures and competitor maps, the market is being reshaped by external macro forces that demand attention. Understanding these dynamics is essential for forecasting demand shifts and identifying emerging risks.
Raw Material Economics. The cost and availability of raw materials directly influence blade pricing and manufacturing viability. In 2025, high-speed steel (HSS) prices showcased interesting trends, with molybdenum-rich grades advancing at a notable CAGR. This movement supports the durability and performance profile of bimetallic blades, but it also introduces cost volatility that procurement teams must hedge against. Understanding the correlation between raw material cycles and finished blade pricing is a core component of our analysis.
Automation and Labor Dynamics. A significant driver reshaping the landscape is the labor environment. Industrial automation labor shortages in manufacturing have accelerated the adoption of automated bandsaw systems utilizing bimetallic blades. As manufacturers seek to mitigate workforce constraints, the demand for blades compatible with high-throughput, automated sawing systems is rising. This shifts the competitive advantage toward suppliers who can offer not just blades, but integrated solutions or blades optimized for automated environments.
Energy Efficiency Mandates. Sustainability and operational costs are converging. Energy efficiency mandates in metal cutting operations favor bimetallic bandsaw blades for reduced energy consumption in high-volume production. Blades that maintain sharpness longer and cut faster reduce machine runtime and energy load. For organizations facing pressure to reduce their carbon footprint or lower utility costs, blade selection becomes a lever for energy management.
- Raw material price volatility, particularly in molybdenum-rich grades, impacts margin structures.
- Labor shortages are acting as a catalyst for automated sawing infrastructure investments.
- Energy efficiency regulations are creating a preference for high-performance, low-consumption blade solutions.
These dynamics are not static. They interact with regional regulations, economic cycles, and technological breakthroughs. Our report synthesizes these factors into actionable scenarios, helping businesses anticipate rather than react.
Inside the Report: Actionable Intelligence for 2026 Decision-Making
PW Consulting's Bimetallic Bandsaw Blade Market report is structured to provide end-to-end intelligence. We move beyond generic descriptions to offer specific, data-backed insights that can be integrated into strategic planning cycles.
Detailed Market Sizing and Forecasts
The report provides a comprehensive view of market size and growth across the 2026 to 2032 forecast period. We analyze the market from multiple angles, ensuring that readers understand both the historical baseline and the projected expansion. This includes a breakdown of revenue streams and volume trends that allow for precise capacity planning.
Deep-Dive Segmentation Analysis
While high-level trends provide direction, successful strategy requires granularity. The report includes detailed segmentation analysis by region, type, and application. We examine how demand differs across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique drivers, from industrial output levels to infrastructure investment cycles. Furthermore, the type and application segments are dissected to reveal which combinations are driving the highest value and which are facing headwinds.
Competitive Benchmarking and Profiles
We provide exhaustive profiles of the key companies shaping the market. Each profile includes a summary of operations, product focus, and recent strategic moves. By benchmarking these players, our clients can identify potential partners, assess competitor threats, and understand the technological benchmarks required to compete. The report also tracks recent developments, such as trade show participations and product launches, to keep clients informed of the latest market activities.
Risk and Opportunity Assessment
A strategy is only as good as its risk assessment. The report integrates industry context noise—such as raw material fluctuations, regulatory shifts, and technological adoption rates—into a cohesive risk framework. We highlight opportunities for market entry, expansion, and diversification, as well as potential pitfalls related to supply chain fragility or shifting demand patterns.
Why This Report Matters for 2026
As enterprises formulate their strategies for 2026 and beyond, the bimetallic bandsaw blade market offers a case study in how industrial tool markets evolve under pressure. The convergence of material science advancements, automation trends, and environmental mandates creates a landscape where traditional procurement models may fall short.
For manufacturers, this research informs production planning and R&D focus. For distributors and retailers, it highlights where to allocate inventory and which partnerships to prioritize. For investors, it maps the growth potential and concentration risks within the sector. The 6.5 percent CAGR projected through 2032 is attractive, but capturing that growth requires insight into the specific segments and regions where that expansion is concentrated.
PW Consulting is committed to delivering intelligence that drives results. This report is the culmination of rigorous data collection, analysis, and industry expertise, designed to empower your organization with the clarity needed to navigate a complex market.
To access the full dataset, detailed segmentation splits, competitive profiling, and scenario analyses, we invite you to explore the complete Bimetallic Bandsaw Blade Market research. The macro trends outlined here are just the beginning; the specific figures, regional breakdowns, and strategic recommendations contained within the full report provide the actionable intelligence necessary to secure a competitive edge in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Bimetallic Bandsaw Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bone Conduction Headphones Market Hits $2,756.76M in 2025, Projected 6.98% CAGR to 2032
By pmarketresearch, 2026-09-15
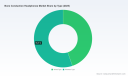
Navigating the Acoustic Horizon: Strategic Intelligence for the Bone Conduction Headphones Market (2026-2032)
The global audio landscape is undergoing a profound structural shift. As consumers and industrial buyers alike demand safer, more comfortable, and contextually aware listening experiences, bone conduction technology has graduated from a niche curiosity to a central pillar of modern personal and professional audio strategy. At PW Consulting, we have meticulously mapped this evolution in our latest comprehensive study, offering a multi-year roadmap that empowers executives, product leaders, and investors to navigate the next growth cycle with precision.
This market intelligence brief is designed not merely as a retrospective of past sales figures, but as a forward-looking compass. By dissecting historical trajectories, projecting multi-phase forecasts, and unpacking the structural dynamics shaping the competitive arena, our analysis delivers the analytical rigor required for decisive action in 2026 and beyond. The following sections outline the strategic architecture of our research, the core growth narratives we have quantified, and the operational insights that will define the next wave of market leadership.
Tracking the Velocity of Market Expansion
Our longitudinal analysis captures a period of sustained acceleration, with the global bone conduction headphones market having demonstrated robust compounding growth throughout the 2020-2025 cycle. Beginning at a baseline of approximately $1,020 million in 2020, market valuations surged through successive years, crossing the $2.7 billion threshold by 2025. This trajectory reflects not only the gradual adoption curve of early adopters but also the catalytic effects of enhanced form factors, specialized use-case development, and broader consumer acceptance of open-ear acoustic architectures.
Looking forward, our forecasting models project this momentum to intensify. The market is anticipated to continue its upward path through 2032, with composite growth rates indicating a CAGR of approximately 6.98 percent across the forecast horizon. Such a trajectory signals a market transitioning from early-stage validation to accelerated mainstream expansion, where the compounding effects of diversified application adoption and geographic penetration will reshape industry benchmarks. Importantly, the structural nature of this growth is not uniformly distributed. It is being driven by specific innovation vectors, shifting consumer preferences, and regulatory and design standards that are actively reshaping procurement and product development strategies.
We deliberately avoid presenting granular, static snapshots of segment performance. Instead, our analysis emphasizes the underlying velocity and relational dynamics between product architectures, end-use environments, and regional adoption patterns. By focusing on the directional forces that will determine 2026 market outcomes, we equip stakeholders with a framework for scenario planning rather than a rigid snapshot that will quickly lose relevance. This approach recognizes that the true value of market intelligence lies not in quoting isolated figures, but in understanding the mechanisms that generate them and the strategic leverage points they reveal.
Strategic Architecture of the Research: What Decision-Makers Will Find Inside
PW Consulting’s report is constructed around the operational realities of market participants. Rather than offering a superficial overview, the study delivers a modular, actionable intelligence framework designed to inform product roadmaps, go-to-market strategies, investment allocation, and competitive positioning. The research architecture is divided into several interconnected analytical layers, each engineered to translate macro-level trends into executable intelligence.
The first layer focuses on market sizing and forecasting, building a granular time-series that tracks revenue evolution across the forecast window while maintaining a disciplined approach to uncertainty. This framework enables readers to stress-test assumptions, identify inflection points, and align internal planning cycles with anticipated demand shifts. Rather than delivering a single deterministic number, our models contextualize growth paths against multiple adoption scenarios, giving leadership the flexibility to adjust positioning as market signals evolve.
Bone Conduction Headphones Market
The second analytical pillar examines product and application segmentation dynamics. We evaluate how different design architectures and end-use environments contribute to value creation, adoption speed, and competitive differentiation. This includes an assessment of how specialized features, durability requirements, and acoustic performance benchmarks are influencing procurement decisions across distinct buyer profiles. The report unpacks the functional priorities driving segment growth and highlights where technological maturity is converging with commercial viability.
Geographic distribution analysis forms the third strategic layer. Here, we map the uneven but deliberate spread of market activity across regions, examining how local infrastructure, consumer behavior, industrial procurement patterns, and regulatory environments shape market dynamics. This regional lens is critical for companies evaluating expansion pathways, localization strategies, and channel development priorities, as the growth narrative is being written differently in each geographic theater.
A dedicated competitive landscape section provides detailed company profiling, strategic mapping, and recent development tracking. Rather than simply listing competitors, we analyze how each player positions itself within the value chain, what innovation vectors they are pursuing, and how recent product launches, certification milestones, and partnership activities signal future competitive intensity. This competitive intelligence is complemented by an assessment of market concentration, highlighting the structural dynamics that determine pricing power, brand influence, and barriers to entry.
Finally, the study integrates an operational environment analysis that addresses the real-world constraints and enablers shaping market execution. This includes an evaluation of manufacturing economics, material specifications, certification requirements, and technical standards that influence cost structures and product viability. By embedding these operational realities into the strategic narrative, we ensure that readers can ground their high-level planning in the practical parameters of production, compliance, and consumer expectations.
Worldwide Neckband Headphones Market
The Competitive Arena: Innovation Leaders, Specialist Players, and the Shifting Value Chain
The bone conduction headphones market is characterized by a concentrated competitive structure at the premium end, alongside a broadening base of specialized manufacturers and OEM-focused producers. Our analysis identifies a cohort of companies that have shaped the market’s evolution through product innovation, brand recognition, and targeted application engineering. Among these, Shokz has established itself as a flagship producer, driving premium positioning through flagship product families and continuous open-ear acoustic refinement. Its recent participation in high-profile industry exhibitions, where newer models earned innovation recognition, underscores the company’s focus on maintaining technological visibility and consumer relevance at the forefront of the category.
Complementing this premium tier is a constellation of specialist firms that have carved out defensible positions by targeting specific performance requirements and end-use environments. H2O Audio and Nank, for example, have concentrated on waterproof, multi-sport, and swimming-optimized designs, emphasizing high ingress protection ratings and activity-specific durability. Suunto’s involvement illustrates how established sports and training brands are integrating bone conduction into broader athletic ecosystems, leveraging battery optimization and training-oriented feature sets. Raycon represents an emerging direction in open-ear design for everyday use, suggesting that consumer accessibility and lifestyle integration are becoming increasingly important axes of competition.
Behind these branded consumer and specialty offerings lies a dense layer of manufacturing and export-oriented companies that play a critical role in the value chain. Entities such as Dongguan Kemi Electronic Technology, Shenzhen Alex Technology, Shenzhen Xinshuoya Electronics, and Dongguan Jiuyin Technology operate across different segments of production, ranging from wireless sport models to hearing aid solutions and OEM device manufacturing. Their presence highlights an important structural reality: the market’s expansion is being supported by a specialized manufacturing base capable of executing diverse technical requirements, from miniaturized acoustic assemblies to waterproof enclosures and certification-compliant electronics. This distributed manufacturing ecosystem not only enables faster product iteration but also influences competitive dynamics by shaping cost structures, supply chain resilience, and the speed at which new specifications can be commercialized.
The competitive dynamics of this market are further shaped by market concentration patterns. The presence of significant concentration at the top tiers of the industry indicates that brand equity, distribution relationships, and innovation cadence are powerful moats. At the same time, the breadth of active manufacturers and exporters suggests that competitive entry remains possible through differentiated engineering, niche application targeting, and strategic OEM partnerships. For incumbents, the strategic challenge lies in sustaining premium positioning while defending against increasingly capable specialists. For new entrants and investors, the opportunity resides in identifying underserved performance requirements and mapping them to efficient manufacturing pathways.
Market Dynamics and Operational Realities Shaping 2026 Strategy
Understanding the competitive landscape is only half the equation. The strategic decisions made in 2026 will be heavily influenced by operational, regulatory, and technical dynamics that define what is commercially feasible and how quickly new capabilities can be deployed. Our research highlights several of these structural factors as central to market strategy.
One critical dynamic concerns manufacturing economics. The specialized components and acoustic engineering required for bone conduction devices result in production costs that are materially higher than those associated with conventional headphone architectures. This cost premium is not a peripheral detail; it is a strategic variable that influences pricing strategy, margin management, and the ability to scale volume segments. Companies that can optimize component selection, streamline assembly processes, and align product tiers with appropriate cost structures will be better positioned to capture both premium and value-oriented demand without sacrificing differentiation.
Regulatory and certification requirements represent another layer of strategic complexity. In key markets such as the European Union, compliance frameworks require specific markings and validation processes, with additional certification pathways necessary for features such as active noise reduction. As these standards become more embedded in procurement expectations, product teams must treat compliance not as an afterthought but as a core element of product definition and market access planning. The companies that can navigate certification pathways efficiently will gain faster route-to-market advantages and stronger credibility with institutional buyers who prioritize validated performance and safety assurances.
Technical specification evolution is also reshaping consumer and enterprise expectations. High ingress protection ratings have become standard expectations for products targeting aquatic, outdoor, and rugged fitness applications, and design benchmarks are increasingly tied to weight efficiency, band materials, and ergonomic comfort. The growing emphasis on lightweight titanium band assemblies and optimized gram weights in active models reflects an industry moving toward a more refined definition of performance, where durability and comfort must coexist with acoustic clarity. These specification trends influence not only product design but also brand positioning, as consumers increasingly evaluate bone conduction devices through the lens of specialized functionality rather than generic audio delivery.
Taken together, these dynamics underscore that market success in 2026 will not be determined solely by innovation ambition, but by the integration of innovation with cost discipline, compliance readiness, and specification alignment. Strategic leaders will be those who can map these operational realities onto clear product and market priorities, ensuring that development resources are directed toward the features, certifications, and use-case configurations that buyers value most.
Why This Intelligence Matters for 2026 Decision-Making
The bone conduction headphones market is no longer a speculative segment; it is a maturing category in which strategic clarity separates sustainable growth from reactive positioning. Our research is designed to provide the analytical depth required for that clarity. By combining multi-year market sizing with segmentation dynamics, competitive profiling, regulatory context, and operational cost considerations, the study offers a comprehensive foundation for product planning, investment prioritization, channel development, and competitive response.
For executives and strategic planners, the report functions as a decision-support system that connects external market trajectories to internal resource allocation. It helps identify where growth is likely to be most durable, which application environments are driving differentiation, and how competitive concentration and manufacturing realities will influence margin and scaling opportunities. For product and engineering leaders, the analysis surfaces the specification and certification trends that will shape development roadmaps and buyer expectations. For investors and market strategists, the study provides a structured lens through which to evaluate segment maturity, competitive intensity, and the strategic positioning of key players.
This introduction provides only a high-level portrait of the intelligence available in the full report. The detailed segmentation breakdowns, forward-looking scenario data, company-specific strategic assessments, and operational benchmarks are structured to support precise, evidence-based planning and are accessible through the complete PW Consulting market research publication. Readers seeking the full depth of forecasts, competitive mapping, and actionable strategic frameworks are encouraged to access the complete study, where the complete analytical architecture, granular market data, and execution-oriented insights are presented in full.
As the bone conduction headphones market continues its trajectory toward broader adoption and more sophisticated differentiation, the organizations that succeed will be those equipped with intelligence that goes beyond surface-level trends. PW Consulting’s research is built for that purpose: to convert complex market movement into strategic advantage, and to ensure that 2026 decisions are informed by the most current, comprehensive, and strategically relevant market intelligence available.
For detailed analysis of this topic, please visit the official page: Bone Conduction Headphones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: POE Market to Hit $3.11B by 2032, 7.6% CAGR Driven by Automotive
By pmarketresearch, 2026-09-15
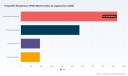
Navigating the Polyolefin Elastomers Market in 2026: Strategic Intelligence for Decision Makers
The global Polyolefin Elastomers (POE) sector is entering a decisive growth window. As demand structures evolve across automotive, packaging, wire and cable, and high-performance specialty applications, the ability to anticipate capacity shifts, competitive repositioning, and material substitution trends will separate resilient market participants from those left competing on price alone. Our newly released Polyolefin Elastomers Market research report is designed as a strategic operating companion for executives, business development leaders, and procurement specialists who need forward-looking intelligence to shape investment, sourcing, and portfolio decisions through 2032 and beyond.
This introduction outlines the scope of the analysis, the structure of the intelligence, and the reasoning behind why a disciplined, data-grounded view of the POE landscape matters in 2026. It is intentionally crafted as a preview: sufficient to demonstrate analytical rigor and commercial relevance, while leaving the segmented numbers, regional breakdowns, and detailed scenario modeling for the full report.
Why POE Deserves Strategic Attention in 2026
Polyolefin elastomers occupy a unique position in the polymer value chain. They combine the processability and cost profile of polyolefins with the flexibility, impact resistance, and toughness associated with elastomeric materials. That blend has made POE increasingly attractive where manufacturers seek to lightweight components, improve durability, reduce dependence on more expensive elastomers, or meet regulatory and performance requirements without sacrificing processing efficiency.
The commercial trajectory of POE reflects that expanding utility. Building on a market that surpassed 1,880 million USD in 2025, the sector is projected to reach approximately 2,024.64 million USD in 2026 and continue its upward path to roughly 3,112 million USD by 2032. This expansion is underpinned by a forecast CAGR of 7.6 percent across the 2026 to 2032 period. Growth of this magnitude is not automatic, nor is it uniformly distributed. It is shaped by plant economics, feedstock dynamics, regional demand patterns, application-specific qualification cycles, and the strategic behavior of leading producers.
Polyolefin Elastomers (POE) Market
For decision makers, the practical question is not whether POE is growing, but where the growth is real, how durable it is, and what it means for capacity planning, product development, customer targeting, and competitive positioning. A high-level headline number can support a narrative; it cannot support a budget, a sourcing strategy, or an M&A thesis. That is the gap this research is built to fill.
PolyOlefin Elastomer (POE) Synthetic Materials Market
What This Report Delivers: A Practical Intelligence Framework
The Polyolefin Elastomers Market study is structured around actionable analysis rather than descriptive overview. It connects market sizing to the operational and strategic levers that actually drive outcomes in polymer businesses: technology choice, end-use adoption, regional competitive intensity, pricing behavior, capacity additions, and the shifting role of key innovators.
Market Sizing and Trajectory Framework
The report anchors its forward view in a consistent historical and forecast structure covering 2020 through 2032. The base year is 2025, with the analysis tracing recent market evolution and then projecting forward across the 2026 to 2032 forecast period. This allows readers to evaluate growth momentum against a credible recent baseline and assess whether accelerating trends are likely to persist, moderate, or intensify.
The quantitative framework is paired with qualitative interpretation so that numbers are never treated in isolation. Growth estimates are examined alongside the forces that could alter them, including changes in downstream demand, feedstock cost environments, plant utilization patterns, and the timing of new capacity coming online. This makes it possible to distinguish between cyclical uplift and structural expansion.
Segmentation Designed for Decision Making
A core strength of the report is its segmentation logic, which is built to support real business questions rather than simply divide the market into categories. The analysis examines the POE landscape by region, by type, and by application, providing a multi-angle view of where value is being created and how demand constructs are evolving.
By region, the study explores how geographic market structures differ in terms of demand intensity, competitive density, and growth opportunity. By type, it differentiates between polyethylene-based POE and polypropylene-based POE, helping readers understand the distinct performance characteristics, application fit, and commercial dynamics associated with each route. By application, it evaluates how POE is used across automotive components, flexible packaging, consumer goods, and other applications, highlighting which demand channels are expanding most meaningfully and why.
We deliberately present segmentation as part of a strategic narrative rather than as a stand-alone data table. The goal is to help users interpret where growth is originating, which segments face differentiation pressure, and where qualification timelines, performance thresholds, or substitution risks could reshape share dynamics.
Competitive Landscape and Strategic Positioning
The report provides a detailed assessment of the companies defining the POE market. It examines global producers with broad manufacturing footprints as well as regional specialists pursuing targeted application advantages. The competitive analysis is not limited to corporate profiles; it evaluates how each player's product offerings, capacity strategy, and technological emphasis shape market structure and competitive tension.
Among the firms covered are The Dow Chemical Company, recognized for its extensive global POE production and its ENGAGE and AFFINITY product families serving automotive, packaging, wire and cable, and specialty applications. The study also assesses ExxonMobil Corporation, whose Vistamaxx platform reflects a strong emphasis on POE for adhesives, medical, and packaging segments, supported by large-scale manufacturing assets. Mitsui Chemicals, Inc. appears as a key international manufacturer supplying high-performance elastomers for automotive, wire and cable, and industrial uses.
Borealis AG is reviewed for its Queo platform and its strong European positioning across packaging, automotive, and medical applications. LG Chem Ltd. is analyzed as a major POE supplier with expanding capacity and a focus on automotive and high-value specialty elastomers. SABIC is included for its POE production through SABIC SK Nexlene Company, notably with FORTIFY encapsulant grades supporting solar and advanced materials applications.
The report also evaluates rapidly scaling participants such as Wanhua Chemical Group Co., Ltd., whose new 200,000 t/yr unit became operational in 2024 and is part of a broader expansion toward 600,000 t/yr capacity. LyondellBasell Industries N.V. is assessed as a global POE manufacturer with multi-region production sites supplying elastomers for wire and cable and industrial applications.
By placing these companies within a unified analytical framework, the report helps readers interpret market concentration, competitive differentiation, and the strategic significance of capacity expansion, product innovation, and application-focused commercialization.
Recent Industry Developments and Structural Signals
The research integrates current industry developments that are relevant to market structure and future competitive dynamics. One notable signal is the preliminary merger review initiated in March 2026 by the South Korea Ministry of Trade, Industry and Resources and the Korea Fair Trade Commission regarding Lotte Chemical's proposed merger with Yeochun NCC. The restructuring is expected to result in a business focused on producing high value-added LDPE and POE for medical use.
Events of this kind matter because they illustrate how the POE market is increasingly tied to broader petrochemical strategy, regional industrial policy, and the pursuit of higher-margin specialty grades. The report examines such developments not as isolated news items, but as indicators of how supply structures, product mix strategies, and competitive boundaries may shift over the forecast horizon.
From Data to Decision: How to Use This Research in 2026
For executives planning capital allocation, product strategy, or market entry, the report is intended to support several practical decisions. These include evaluating where to commit resources, which applications and regions offer the most durable opportunities, how competitive intensity may change as new capacity comes online, and where performance or qualification advantages can protect margin.
The analysis is equally relevant for procurement and supply chain teams. Understanding how POE supply is evolving across type, application, and geography helps organizations anticipate volatility, assess supplier concentration risk, and align sourcing strategies with longer-term availability and cost expectations. The market's concentration profile, with a reported CR3 of 65.0 percent and CR5 of 80.0 percent, underscores the strategic importance of understanding the behavior of leading producers and the implications of their capacity, product, and pricing decisions.
The report also supports scenario thinking. Rather than treating the forecast as a single fixed path, it helps users consider how different demand trajectories, capacity outcomes, and application adoption rates could alter growth and competitive positioning. That flexibility is especially important in a market where regional dynamics, downstream qualification cycles, and feedstock conditions can materially influence results.
A Preview, Not a Replacement: Why the Full Report Matters
This introduction is designed to demonstrate the scope and rigor of the Polyolefin Elastomers Market research while preserving the depth of the full analysis for readers who need it. The report contains the detailed regional and application-level intelligence, segment interpretation, competitive context, and forward-looking assessment required to support serious commercial planning.
For teams evaluating investment priorities, customer strategy, production planning, or competitive response in 2026, the value lies in the combination of structured market data and interpretive analysis. Headline figures establish direction; segmentation, competitive context, and scenario-aware interpretation establish confidence. The full report brings those elements together in a form built for executive use.
If your objective is to move beyond general market awareness and into decision-grade intelligence, the complete Polyolefin Elastomers Market research offers the granularity, context, and strategic framing needed to act with greater clarity in the years ahead.
For detailed analysis of this topic, please visit the official page: Polyolefin Elastomers (POE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Employee Scheduling Software Market Hits $225M in 2025, Poised for 11.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Future of Workforce Optimization
The landscape of employee scheduling software is undergoing a seismic shift, driven by the convergence of artificial intelligence, stringent compliance mandates, and the enduring need for operational resilience. As organizations transition from reactive staffing models to proactive workforce orchestration, the strategic importance of dedicated scheduling technology has never been more pronounced. In response to accelerating market velocity, PW Consulting is pleased to unveil its latest research publication: the Employee Scheduling Software Market analysis, covering the trajectory from 2020 through 2032. This report serves as a definitive guide for executives, HR leaders, and investment strategists seeking to align their technology roadmaps with the next cycle of enterprise growth.
Drawing on a rigorous historical baseline and a forward-looking forecast horizon, this study offers a 360-degree view of the ecosystem. From technological bifurcation to competitive intensity, the following pages dissect the forces reshaping how organizations plan shifts, manage labor costs, and ensure regulatory adherence. The insights herein are curated to empower data-driven decisions that balance cost efficiency with employee experience in an increasingly fluid work environment.
Market Overview and Strategic Trajectory
The global employee scheduling software market has demonstrated remarkable durability and expansion over the past half-decade. Historical data from 2020 to 2025 illustrates a clear and sustained upward trajectory, reflecting the market’s critical role in modern workforce management. As organizations adapt to hybrid work models, fluctuating demand patterns, and evolving labor expectations, the foundational value of scheduling technology has expanded well beyond simple shift assignment. This growth phase has been characterized by a fundamental shift in operational philosophy. Where scheduling was once treated as an administrative task embedded within broader HR systems, it has emerged as a strategic lever capable of unlocking significant productivity, cost, and compliance advantages.
Nurse Scheduling Software Market
Looking ahead, the forecast period from 2026 to 2032 signals continued robust expansion. The market is projected to follow a sustained compound annual growth rate of 11.2 percent, a figure that underscores the accelerating adoption of dedicated workforce orchestration platforms across diverse operational environments. This growth trajectory is not merely a reflection of digital transformation trends; it is a direct response to the operational complexities that modern enterprises face daily. Organizations that recognize scheduling software as a core component of their workforce strategy, rather than a peripheral utility, are consistently better positioned to navigate labor volatility, optimize coverage, and maintain service continuity under unpredictable conditions.
From a macro perspective, the market has progressed from 148.5 million USD in 2020 to a baseline of 225.0 million USD in 2025. The momentum carries forward, with the market projected to reach 250.71 million USD in 2026 and accelerate toward 367.0 million USD by 2032. These figures represent more than operational scale; they signal a structural transformation in how enterprises allocate labor, respond to demand fluctuations, and manage the human capital dimension of service delivery. This steady expansion reflects deepening enterprise reliance on intelligent workforce tools, as well as the maturation of deployment models, vendor ecosystems, and compliance frameworks that together define the modern scheduling landscape.
Technology Architecture and Deployment Evolution
The evolution of deployment models has fundamentally shaped how organizations interact with employee scheduling software. Cloud-based solutions now command the largest share of the technology landscape, reflecting a decisive industry pivot toward scalable, accessible, and continuously updated platforms. Organizations are increasingly drawn to cloud architectures for their ability to streamline implementation, reduce infrastructure overhead, and support distributed workforce operations across multiple sites and time zones. At the same time, on-premises environments continue to serve a meaningful segment of the market, particularly where data sovereignty, legacy system integration, and highly controlled operational environments remain critical considerations. Beyond these core deployment paths, a broader category of solutions reflects the ongoing diversification of the market, as vendors expand the scope of offerings to include integrated time tracking, mobile self-service, and complementary workforce management capabilities.
Alongside deployment evolution, the functional architecture of scheduling platforms is growing more sophisticated. Modern systems are increasingly expected to support real-time coverage adjustments, AI-driven demand forecasting, automated compliance checks, and seamless linkage with payroll and core human capital management processes. This functional convergence is narrowing the gap between scheduling and broader workforce strategy, enabling organizations to treat employee scheduling not as a standalone administrative task, but as a central point of operational control. As a result, procurement and IT leaders are evaluating platforms through a more holistic lens, weighing long-term interoperability, extensibility, and integration potential alongside immediate scheduling performance.
Industry Applications and Operational Impact
The practical value of employee scheduling software is most visible in its application across different organizational scales. Small businesses rely on scheduling technology to bring structure to limited administrative capacity, allowing lean teams to manage shifts, reduce forgotten coverage gaps, and maintain operational consistency without expanding overhead. Mid-size enterprises, often operating across multiple locations or service lines, use scheduling software to introduce visibility, standardize processes, and support growth without proportionally increasing managerial load. Large enterprises apply these tools to coordinate complex labor pools, optimize costly overtime exposure, and align staffing decisions with sophisticated demand forecasts and cross-functional operational priorities.
What unites these diverse application environments is the growing recognition that scheduling performance directly affects labor economics and service quality. Improved scheduling alignment is consistently associated with stronger shift coverage, lower overtime exposure, and more effective alignment between labor supply and operational demand. In fast-paced, shift-based environments, this can translate into measurable reductions in unnecessary labor spend while improving reliability for both employees and customers. At the same time, mobile-first access and employee self-service capabilities empower individuals to participate more actively in schedule management, which can strengthen engagement and reduce administrative friction.
Employee Scheduling Software Market
The operational upside extends to compliance as well. Automated enforcement of meal breaks, rest periods, overtime boundaries, and union or state-specific rules helps organizations reduce legal exposure and operational risk. With labor regulations continuing to evolve, platforms that embed policy guidance and compliance monitoring are increasingly viewed as strategic safeguards rather than optional add-ons. In this context, the scheduling software decision is becoming inseparable from enterprise risk management and operational continuity planning.
Regulatory Landscape and Operational Dynamics
Regulatory pressure remains one of the most powerful external forces shaping the employee scheduling software market. As labor rules, scheduling transparency requirements, and compliance expectations continue to shift across regions and industries, organizations face rising complexity in maintaining adherence without sacrificing operational flexibility. The industry response has been to move compliance from manual oversight to engineered automation. Platforms are increasingly designed to translate regulatory requirements into built-in controls, alerting mechanisms, and policy enforcement logic that reduce the burden on HR, payroll, and operations teams.
Data privacy considerations are equally integral to this dynamic. Enterprise-grade cloud scheduling platforms continue to align with established security and privacy standards, ensuring that workforce data is handled with the rigor required for regulated environments and cross-border operations. For organizations operating in Europe or other privacy-sensitive markets, these safeguards are not optional enhancements but baseline expectations that influence procurement decisions and long-term vendor trust.
Beyond formal regulation, broader operational dynamics are influencing market direction. The integration of workforce expertise, policy guidance, and documentation support into platform ecosystems reflects a maturing market in which vendors are expected to help customers navigate change rather than simply provide tools. This shift is especially relevant in environments where labor laws, union rules, and state-specific mandates create recurring compliance uncertainty. Organizations that select platforms with strong compliance orientation are often better equipped to absorb regulatory change without operational disruption.
Competitive Landscape and Strategic Positioning
The competitive field in employee scheduling software is characterized by a mix of established workforce management incumbents, specialized scheduling vendors, and broader HCM platforms extending into scheduling functionality. Market concentration remains relatively distributed, with the top three players holding approximately 24.6 percent and the top five reaching about 26.2 percent of the overall market, indicating substantial room for differentiation and continued competitive churn. This fragmentation is a strategic advantage for buyers, as it supports a wide spectrum of solution philosophies ranging from enterprise-scale workforce orchestration to industry-specific scheduling tools and SMB-focused mobile platforms.
Leading participants illustrate the diversity of approaches shaping the market. ADP delivers a comprehensive workforce management platform that integrates employee scheduling, time tracking, shift optimization, and compliance support for hourly and frontline workers. UKG brings enterprise-grade scheduling strength through platforms such as UKG Pro and Kronos Workforce Central, with AI forecasting, real-time coverage planning, labor cost optimization, and multi-site shift management at the core of its value proposition. Ceridian Dayforce offers a unified platform connecting scheduling, shift assignment, workforce analytics, and automated compliance for global enterprises. Rippling positions scheduling within an integrated HR and workforce management suite, linking AI demand forecasting and shift planning with payroll and organizational growth.
Specialized players further broaden the competitive canvas. Deputy focuses on shift-based industries with scheduling, time tracking, AI labor forecasting, mobile access, and compliance automation. Connecteam emphasizes app-based scheduling, shift swapping, time tracking, and team communication for small and medium businesses. Homebase combines scheduling and payroll with shift templates, mobile clock-in, labor cost tracking, and compliance alerts. Paychex Flex targets mid-market organizations with scheduling, time and attendance, and integrated payroll. Paycor contributes intelligent HCM capabilities with scheduling, labor cost visibility dashboards, and integrated shift management. When I Work centers on employee self-scheduling, shift management, and real-time reporting. Workday extends advanced scheduling, demand forecasting, and compliance-driven workforce planning within a large enterprise HCM context. TCP Software, through Humanity Schedule and TimeClock Plus, provides dynamic scheduling with automated forecasting, mobile management, and labor optimization. Shiftboard serves mission-critical industries with fatigue management, contingent labor tools, and labor cost reduction features.
Recent industry activity reinforces the pace of innovation. In March 2026, UKG launched 15 Workforce Management APIs designed to support seamless integration with employee scheduling and time-tracking platforms. Initiatives like this highlight a broader market trend in which interoperability is increasingly treated as a competitive differentiator, enabling organizations to build more connected workforce ecosystems rather than isolated point solutions.
Report Scope and Decision-Ready Intelligence
The Employee Scheduling Software Market report is designed as a practical decision-support instrument rather than a high-level survey. It frames the market through a structured methodology that combines historical analysis with forward-looking forecasting, enabling leadership teams to ground strategic choices in evidence rather than assumption. The report traces market evolution across the 2020 to 2025 historical period and extends into a detailed 2026 to 2032 forecast window, providing continuity between past performance and future opportunity.
Beyond macro market sizing and growth outlook, the study examines how technology type, deployment model, application environment, and regional dynamics collectively shape purchasing behavior and solution effectiveness. It provides a structured competitive assessment of major vendors, profiling their capabilities, positioning, and recent strategic moves. This allows readers to compare market participants not only by scale, but by functional emphasis, integration maturity, and target customer fit.
The report also explores the operational and regulatory context that influences adoption. By integrating insight on labor cost impact, compliance automation, data privacy requirements, and integration trends, it equips stakeholders with a multi-layered view of the forces that affect implementation success and long-term platform value. For procurement teams, this means clearer evaluation criteria. For strategy leaders, it means a stronger basis for portfolio planning and vendor selection. For investors and analysts, it means a more precise understanding of where growth is concentrating and why.
Crucially, the full dataset, detailed segmentation, and proprietary company assessments are reserved for the complete report. This introduction is intended to establish analytical credibility while preserving the depth of intelligence that readers will need to act with confidence. The full study provides the range, precision, and benchmarking detail required to translate market signals into concrete investment, procurement, and operational decisions.
Conclusion: Strategic Imperatives for the 2026 Horizon
As organizations move deeper into 2026, employee scheduling software is no longer a tactical utility. It has become an essential enabler of labor efficiency, workforce agility, and regulatory resilience. The market’s projected growth path and expanding functional expectations indicate that companies which treat scheduling as a strategic capability will be better positioned to manage cost pressures, improve coverage quality, and adapt to evolving compliance demands.
For leaders evaluating technology investments, the strategic question has shifted from whether to adopt scheduling software to which platform architecture, integration model, and vendor profile best fits the organization’s scale, industry, and risk environment. The answers depend on a clear reading of market structure, vendor differentiation, and operational impact. PW Consulting’s Employee Scheduling Software Market report offers that reading in a form built for executive decision-making. We invite stakeholders to explore the full research for the complete market intelligence, segmentation precision, and competitive analysis needed to navigate the next phase of workforce optimization with confidence.
For detailed analysis of this topic, please visit the official page: Employee Scheduling Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automated Sortation Market Hits $432M in 2025, Projects 3.99% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Automated Sortation System Market: Strategic Intelligence for 2026 Decision-Makers
The global supply chain ecosystem is undergoing a structural transformation driven by e-commerce acceleration, labor constraints, and the imperative for operational precision. At the center of this shift lies the automated sortation system market, a critical enabler of modern distribution, parcel handling, and intralogistics optimization. For executives, investors, and operations leaders evaluating capital allocation or technology roadmaps in 2026, understanding the trajectory, competitive architecture, and regulatory forces shaping this market is no longer optional—it is foundational to resilient growth.
This introduction previews the depth and strategic utility of PW Consulting’s latest market research on automated sortation systems. Rather than offering surface-level market sizing, the report is engineered to translate macroeconomic signals, competitive maneuvers, and regulatory developments into actionable decision frameworks. Below, we outline the analytical scope, the competitive landscape it maps, and the market dynamics that will define procurement, partnership, and expansion strategies throughout the forecast horizon.
Market Trajectory and the Strategic Imperative for 2026
The automated sortation system market has demonstrated steady, compounding growth over the past half-decade, reflecting the broader digitization of logistics and the scaling of fulfillment networks. Historical revenue patterns from 2020 through 2025 reveal a market that has consistently expanded despite macroeconomic volatility, underpinned by sustained investment in warehouse automation and parcel infrastructure. This momentum carries forward into the forecast period, where the market is projected to continue its upward arc through the early 2030s.
For 2026 specifically, the market reaches a meaningful inflection point. The baseline valuation for the year signals a clear step-up from the prior year’s close, reinforcing the notion that sortation automation is transitioning from a discretionary efficiency play to a core operational requirement. Over the full forecast window extending to 2032, the market is expected to expand at a compound annual growth rate of approximately 4 percent, culminating in a substantially larger revenue base by the end of the period. This trajectory is not merely a numerical projection; it reflects the cumulative effect of throughput demands, labor cost pressures, and the integration of intelligent control systems into sortation workflows.
Importantly, the growth pattern is not uniform across all operational contexts. Different sectors and geographies are experiencing divergent adoption velocities based on infrastructure maturity, regulatory environments, and the urgency of fulfillment speed. The report disentangles these variations without reducing them to simplistic rankings, instead providing a layered view of where demand is consolidating, where whitespace exists, and how implementation complexity shapes procurement timelines.
What the Report Delivers: Analytical Depth and Operational Relevance
PW Consulting’s automated sortation system market research is structured to serve multiple stakeholder groups simultaneously—operations directors evaluating capital projects, strategy teams assessing vendor partnerships, and investors mapping sector exposure. The report integrates quantitative market architecture with qualitative competitive and regulatory analysis, ensuring that data points are always anchored to decision context.
Core Analytical Components
- Market sizing and forward projections spanning historical baselines through the full forecast horizon, with revenue expressed in nominal terms to support budgeting and scenario modeling.
- Segmentation analysis across technology types, end-use applications, and regional markets, enabling readers to isolate the subsegments most relevant to their operational footprint or investment thesis.
- Competitive positioning and firm-level profiling that maps the strategic capabilities, product architectures, and geographic reach of leading participants.
- Recent corporate developments including deployments, partnerships, and integration initiatives that signal where the market is heading in practice, not just in theory.
- Regulatory and operational dynamics covering labor impact, data privacy obligations, safety and traceability requirements, and energy efficiency mandates that increasingly shape procurement criteria.
- Concentration metrics that clarify the degree of market consolidation and the strategic implications for incumbents and entrants alike.
Each section is designed to feed directly into business planning. For example, the segmentation views allow procurement teams to benchmark their internal pipeline against broader demand patterns, while the competitive profiles help evaluate whether a shortlisted vendor’s technology portfolio aligns with projected throughput and flexibility requirements. Similarly, the regulatory and operational dynamics section translates external compliance pressures into practical risk-filtering criteria for project scoping.
Automated Sortation System Market
Competitive Landscape: Architects of the Sortation Ecosystem
The automated sortation system market is characterized by a blend of established intralogistics conglomerates, specialized sortation technology providers, and large industrial firms extending into automation platforms. Market concentration metrics indicate a moderately consolidated environment, where a relatively small group of firms commands a substantial share of industry revenue. This structure has meaningful implications for procurement leverage, integration risk, and the pace of innovation diffusion.
Firm Profiles and Strategic Positioning
Several companies define the technological and commercial contours of this market. Daifuku Co., Ltd., headquartered in Osaka, specializes in tilt-tray and linear parcel sortation systems designed for high-volume logistics and distribution centers, making it a reference point for operators prioritizing throughput stability. Vanderlande Industries B.V., based in the Netherlands, offers loop sorters, sliding shoe sorters, and automated parcel sortation solutions optimized for e-commerce fulfillment—an alignment that reflects the ongoing centrality of parcel velocity in consumer logistics. OKURA YUSOKI CO., LTD., from Tokyo, provides automated parcel sortation systems combining linear and shoe sorter technologies tailored to parcel and postal applications, while Murata Machinery, Ltd., also in Kyoto, focuses on cross-belt and linear sortation systems integrated with high-speed sorting platforms for parcel logistics.
Interroll Holding AG, headquartered in Germany, manufactures roller conveyor and modular automated sortation systems for warehouses and distribution hubs, emphasizing modularity and scalability. The KION Group AG, through its Dematic business, delivers shoe sorters and automated warehouse sortation systems as part of broader intralogistics solutions, positioning the brand at the intersection of material handling and software orchestration. TGW Group, based in Austria, provides comprehensive automated sortation and conveyor systems for parcel and general merchandise handling, supporting operators that require end-to-end line design. Honeywell International Inc., from the United States, offers sliding shoe, push-tray, and cross-belt sorters for high-throughput parcel and retail sortation, bringing a broad automation heritage to the sortation tier. BEUMER Group, in Germany, specializes in cross-belt sorters and pouch-based sortation platforms for parcel distribution, while Fives in Intralogistics, headquartered in Paris, supplies automated sortation and material handling solutions for parcel and e-commerce operations.
Worldwide Warehouse Automated Sorting System Market
Additional participants further deepen the competitive field. SSI SCHAEFER AG delivers modular automated sortation systems integrated with storage and warehouse management, reinforcing the trend toward tightly coupled automation stacks. Siemens AG provides software-driven and AI-integrated sortation platforms for smart factory and logistics applications, reflecting the growing weight of control intelligence in system selection. Mitsubishi Electric Corporation, from Tokyo, offers automated sortation systems with high-speed conveyor and sorter technologies, rounding out a competitive set that spans mechanical throughput, software integration, and sector-specific specialization.
Recent Developments Shaping the Field
Competitive positioning is not static; it is being actively reshaped by deployment activity and strategic partnerships. In early 2026, BoxLogix completed the installation of an in-line automated sortation system for a regional healthcare distribution hub, streamlining parcel receiving and routing across multiple hospitals—an example of how sortation automation is extending into regulated, multi-site distribution environments. Earlier, in February 2025, EuroSort announced a non-exclusive partnership with Körber to integrate its sorting systems with Körber’s VarioPick dynamic picking robot, aiming to enhance automated sortation precision and scalability through combined robotic and sorting workflows. In January 2026, CVS Health partnered with Tompkins Robotics and Bastian Solutions to deploy an integrated AS/RS with a tSort robotic sortation system at a fulfillment facility, illustrating how large-scale retail and pharmacy logistics are converging on sortation-plus-storage architectures.
These developments are more than announcements; they are signals of how the market is consolidating around integrated, higher-precision, and sector-aware solutions. The report places such events in context, helping readers distinguish between one-off deployments and structural shifts in how sortation systems are specified, integrated, and scaled.
Market Dynamics and Regulatory Forces redefining Procurement Criteria
Technology capability alone no longer determines sortation system success. A set of operational and regulatory dynamics is increasingly embedded into project requirements, vendor evaluations, and total cost of ownership calculations. Understanding these forces is essential for 2026 planning, because they influence not only what systems are purchased, but how they are integrated, validated, and governed over their operational life.
Labor Economics and Throughput Expectations
Automated sortation systems have driven a meaningful reduction in post-sort labor requirements through robotic and conveyor-based handling in distribution operations. This shift is reshaping facility economics: where labor availability and wage escalation once dominated site planning, throughput reliability and changeover flexibility are now equally central. For decision-makers, the implication is that sortation investments must be evaluated against a broader operational baseline that includes staffing strategy, training burden, and the ability to reallocate human labor to exception handling and value-added tasks.
Regulatory Compliance and Data Governance
The regulatory environment is adding new layers of complexity to sortation system deployment. The EU AI Act entered into force on 1 August 2024 and became fully applicable on 2 August 2026, directly regulating AI components in automated sortation systems. This matters for any operator integrating AI-driven routing, exception detection, or predictive control into sortation workflows, because compliance responsibilities now extend to the intelligence layer as well as the mechanical infrastructure.
At the same time, the integration of IoT-enabled and AI-driven sortation systems in warehouses requires ongoing compliance with GDPR for data security and traceability in parcel logistics. As sortation platforms become more connected and data-rich, information governance is no longer a back-office concern; it is part of the system architecture. In parallel, pharmaceutical and food-grade applications of automated sortation systems demand enhanced traceability and contamination-prevention standards under current industry regulations, raising the bar for materials, cleaning protocols, and validation processes in sensitive supply chains.
Sustainability and Operational Efficiency
Environmental regulations increasingly mandate energy-efficient designs in automated sortation systems to minimize operational waste and carbon footprint. This trend is pushing vendors and operators alike to consider motor efficiency, idle-state management, regenerative capabilities, and overall system utilization patterns. For 2026 procurement teams, energy performance is becoming a competitive differentiator that intersects with operating cost, regulatory readiness, and corporate sustainability commitments.
These dynamics do not operate in isolation. They converge in the evaluation criteria used to select sortation platforms, define integration scopes, and set performance benchmarks. The report maps these converging pressures so that readers can anticipate where compliance effort, integration complexity, and operating cost will matter most in their specific context.
Why 2026 Is a Decision-Critical Year
The automated sortation system market is not simply growing; it is maturing in ways that reward early, informed action. The combination of steady revenue expansion, a concentrated but pluralistic competitive field, and a regulatory landscape that increasingly touches AI, data, safety, and energy means that 2026 decisions will shape operational competitiveness for years to come.
Several themes make this a pivotal moment:
- Demand is broadening beyond traditional parcel hubs into healthcare distribution, regulated food and pharmaceutical flows, and retail fulfillment models that require higher precision and traceability.
- Integration is becoming the real product , with partnerships and multi-vendor architectures reflecting the reality that sortation rarely operates in isolation from picking, storage, and warehouse management systems.
- Compliance is now part of the technical specification , whether the concern is AI governance, data privacy, contamination control, or energy efficiency. Procurement criteria are expanding accordingly.
- Labor displacement benefits are real but context-dependent , requiring operators to plan not just for reduced post-sort headcount, but for the redesign of exception workflows and skill requirements.
In this environment, generic market awareness is insufficient. Decision-makers need segmented insight, vendor capability mapping, and a clear view of how macroeconomic growth translates into practical opportunities and constraints. That is precisely the function of the full report.
How to Use This Research for Strategic Planning
The report is designed to support multiple planning workflows. Operations leaders can use the segmentation views to align internal capital projects with broader demand patterns and to identify subsegments where adoption is accelerating. Strategy and procurement teams can use the competitive profiles and recent developments to benchmark vendor proposals, assess integration risk, and identify partnership opportunities that extend system capability. Investors and market analysts can use the concentration metrics, growth trajectory, and regulatory overlays to frame sector exposure and evaluate the durability of competitive advantages.
Crucially, the report does not stop at high-level numbers. It connects market sizing to the operational realities that determine whether a sortation investment delivers intended returns: throughput stability, changeover flexibility, compliance readiness, integration complexity, and energy performance. By embedding these considerations within the analytical framework, the research helps readers move from market awareness to decision confidence.
Accessing the Full Intelligence
The overview above highlights the structure, scope, and strategic relevance of the research, but the full value lies in the detailed segmentation data, firm-level profiles, regulatory impact analysis, and scenario-ready projections that support precise planning. To explore the complete market architecture, including the subsegment dynamics and competitive detail necessary for 2026 decision-making, readers are encouraged to access the full report through the source webpage.
In a market defined by compounding growth, integration complexity, and rising compliance expectations, the organizations that act with the most complete intelligence will be best positioned to convert sortation investment into durable operational advantage. This report is built to provide that intelligence—precisely, contextually, and with direct relevance to the choices facing leaders in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Automated Sortation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fresh Meat Packaging Market Hits $4.09B in 2025, Projects 5.12% CAGR Through 2032|PW Consulting
By pmarketresearch, 2026-09-15
Strategic Horizons in Fresh Meat Packaging: Navigating Growth, Regulation, and Material Shifts Through 2032
The fresh meat packaging sector stands at a critical inflection point. Over the past five years, the market has demonstrated steady expansion, moving from a baseline of approximately $3.12 billion in 2020 to a projected $4.36 billion by 2026. This trajectory reflects more than simple population growth or rising protein consumption. It signals a structural transformation in how processors, retailers, and packaging suppliers approach shelf-life preservation, sustainability compliance, and material economics. For executive teams evaluating capital allocation, supplier partnerships, or product portfolio adjustments in 2026, understanding the underlying mechanics of this market is no longer optional. It is a core component of operational resilience and competitive positioning.
Our newly released Fresh Meat Packaging Market research study provides a comprehensive, data-backed roadmap covering the historical period from 2020 through 2025 and extending forward to 2032. The report is designed specifically for strategic planners, procurement leaders, and investor analysts who require actionable intelligence rather than high-level conjecture. What follows is an executive preview of the market architecture, competitive dynamics, and regulatory forces that will define the sector in the coming years. Readers seeking granular segmentation figures, proprietary company-level revenue estimates, and detailed scenario modeling are encouraged to access the full report for complete market intelligence.
Market Trajectory and the Emerging Growth Framework
The historical record from 2020 to 2025 reveals a market that has consistently outperformed flat growth expectations. After navigating pandemic-era supply chain disruptions and inflationary pressures, the sector recovered with renewed momentum, reaching an estimated $4.09 billion in 2025. Forward projections indicate a compound annual growth rate of 5.12 percent across the forecast horizon of 2026 to 2032. By the end of that period, overall market value is positioned to approach the $5.8 billion threshold.
Several structural drivers underpin this trajectory. First, the retail and food service sectors continue to prioritize case-ready and modified-atmosphere packaging formats that reduce handling labor, minimize cross-contamination risk, and extend display life. Second, consumer expectations around transparency, freshness indicators, and sustainable material choices are forcing brands to rethink traditional foam-and-film architectures. Third, regional protein consumption patterns are shifting, with emerging markets expanding their cold-chain infrastructure and developed markets investing in premium, value-added meat formats. These overlapping trends create a favorable demand environment, but they also introduce complexity. Companies that treat packaging as a commodity input rather than a strategic enabler will find themselves exposed to margin compression, compliance risks, and supplier dependency.
The full research study deconstructs these growth drivers across multiple dimensions, including material type evolution, application-specific demand patterns, and regional market maturity curves. Rather than presenting static tables, the analysis maps how each segment is likely to interact with regulatory mandates, raw material volatility, and technological adoption timelines. This integrated view allows decision-makers to stress-test their assumptions against realistic market pathways.
Regulatory Pressures and the Sustainability Imperative
One of the most consequential forces reshaping the fresh meat packaging landscape is the accelerating pace of extended producer responsibility legislation and packaging waste regulations. In the United States, state-level EPR programs for packaging now cover approximately one in five Americans. Jurisdictions such as Oregon, California, Maryland, and Washington have implemented or are finalizing producer fee structures that tie financial obligations directly to recyclability performance and recycled content minimums, with requirements taking effect across the 2025 to 2026 window. California's SB 54, for example, expanded producer responsibility frameworks for packaging categories including fresh meat applications, with fee schedules administered by the Circular Action Alliance.
Across the Atlantic, the European Union's Packaging and Packaging Waste Regulation introduces binding recycled content thresholds for plastic packaging, targeting a minimum of 25 percent by 2025 and 30 percent by 2030. The regulatory framework also mandates design-for-recyclability criteria and reinforces EPR obligations. For fresh meat packaging suppliers, this means that legacy multi-material laminates and non-recyclable foam variants face increasing cost and compliance headwinds. Design teams are being compelled to evaluate mono-material constructions, fiber-based alternatives, and recyclable barrier films with far greater urgency than before.
These regulatory shifts interact directly with raw material economics. Limited availability of PET and PE resins has pushed costs for meat trays and films upward by an estimated 15 to 25 percent, accelerating the commercial evaluation of paper-based and recycled-content alternatives. At the same time, operational cost dynamics within the meat processing sector itself are evolving. Proposed USDA adjustments to swine slaughter line speeds during the 2025 to 2026 period are estimated to generate industry cost savings on the order of $262 million over a decade, which may indirectly free up capital for packaging innovation and automation investments. Together, these regulatory and input-cost forces are compressing the window for incremental change and rewarding companies that can deliver compliant, sustainable solutions at scale.
Competitive Landscape and Strategic Positioning
The fresh meat packaging market exhibits a moderate level of concentration, with the top three players accounting for roughly 46 percent of market share and the top five collectively representing around 52 percent. This concentration reflects the specialized nature of the sector: success requires deep application expertise, regulatory navigation capabilities, and manufacturing footprints that can support case-ready formats, vacuum skin packaging, and sustainable material transitions. The competitive set is anchored by a group of globally positioned companies that are actively reshaping their portfolios in response to consumer, retailer, and regulatory demands.
Amcor plc, headquartered in Zurich, remains a global leader in responsible and recyclable flexible and rigid packaging solutions tailored specifically for fresh meat products, with a strong emphasis on mono-material films and trays. Sealed Air Corporation, based in Charlotte, North Carolina, continues to drive category standards through its Cryovac vacuum skin packaging and preformed tray systems for fresh beef, pork, lamb, and poultry, complemented by automated equipment and shrink tunnel capabilities. Berry Global Group, headquartered in Evansville, Indiana, is advancing next-generation vacuum skin packaging and sustainable flexible solutions that aim to extend shelf life while improving recyclability profiles.
Vacuum Skin Packaging Market
Pactiv Evergreen Inc., operating out of Lake Forest, Illinois, maintains a comprehensive manufacturing base for fresh meat packaging, including foam trays, films, and case-ready solutions serving processors and retailers. Huhtamaki Oyj, based in Helsinki, Finland, supplies sustainable fiber-based and flexible packaging options designed for fresh meat applications, positioning itself at the intersection of material innovation and circular design. Mondi plc, headquartered in Weybridge, United Kingdom, has emerged as a notable innovator in paper-based mono-material recyclable packaging and pulp solutions for fresh meat trays and films. Winpak Ltd, based in Winnipeg, Manitoba, produces heat-sealable membranes, die-cut lids, and flexible packaging for fresh meat and broader food processing operations. Sonoco Products Company, from Hartsville, South Carolina, provides paperboard trays, tubes, and composite packaging suited to fresh meat applications. Coveris Management GmbH, located in Vienna, Austria, has been developing paper-based and flexible sustainable packaging, including its MonoFlex Fibre range for fresh meat. Finally, Edelmann Group, headquartered in Heidenheim, Germany, supplies high-performance packaging solutions and facilities focused on fresh meat products.
Recent corporate activity underscores the strategic intensity in this space. Mondi partnered with Scan Sverige in May 2024 to create recyclable polypropylene-based mono-material food packaging for fresh meat, signaling a collaborative approach to recyclability challenges. That same year, Mondi completed an acquisition of the Hilton Pulp Mill in Alberta, Canada, to strengthen its sustainable paper-based packaging production capacity for North America. Coveris expanded its packaging portfolio with a substantial investment in a new vacuum skin packaging facility in Winsford, UK, in April 2024, and shortly thereafter introduced the MonoFlex Fibre paper-based flexible packaging range in June 2024, a fully recyclable offering designed for fresh meat applications. These moves illustrate a broader industry pattern: companies are not merely adjusting product lines but are reinvesting in manufacturing capability, forming strategic partnerships, and accelerating the commercial rollout of recyclable and fiber-based alternatives.
Report Scope and Practical Analytical Assets
The full Fresh Meat Packaging Market study is structured to support a wide range of strategic use cases, from market entry assessments and competitive benchmarking to supply chain diversification and sustainability roadmap planning. The report combines historical baselines with forward-looking forecasts, enabling teams to align near-term procurement decisions with long-term portfolio strategy. Key analytical components include a detailed market size and growth trajectory analysis, segmentation insights across material types and application categories, regional market evaluations, and a comprehensive competitive profiling section that maps company positioning, recent developments, and strategic intent.
Fresh Meat Packaging Market
Beyond quantitative modeling, the study provides qualitative analysis of the forces shaping supplier-buyer dynamics. This includes an examination of how EPR frameworks and recyclability mandates are altering cost structures, how raw material availability is influencing material substitution timelines, and how automation and case-ready packaging adoption are reshaping operational requirements at the processor and retailer level. The report also incorporates a review of recent corporate developments, partnership activity, and facility investments that signal where competitive advantages are being built. For organizations evaluating supplier negotiations, the profiling section offers a structured view of each major player's capabilities, geographic reach, and innovation focus, helping teams identify alignment points and potential risks.
Implications for 2026 Decision-Making
As organizations plan their 2026 initiatives, several strategic questions will determine whether they capture value or cede ground in the fresh meat packaging market. How will your packaging portfolio adapt to evolving recyclability mandates and recycled content requirements without compromising structural integrity or shelf-life performance? Are your material sourcing strategies resilient enough to withstand continued resin volatility and regional supply constraints? Does your current supplier base offer the innovation velocity and compliance transparency required by retailers and regulators? And finally, are you positioned to leverage sustainable packaging as a differentiation lever in a market where consumers and procurement teams increasingly weigh environmental performance alongside cost and functionality?
The answers to these questions depend on access to reliable, forward-looking market intelligence. The Fresh Meat Packaging Market research study provides the analytical foundation needed to navigate these decisions with confidence. By integrating historical performance data, forecast modeling, regulatory context, and competitive profiling into a single framework, the report enables leaders to move beyond reactive adjustments and toward proactive strategy formulation.
For teams seeking complete segmentation data, company-level market share estimates, regional growth pathways, and detailed scenario analysis, the full report delivers the depth required for rigorous planning. We invite you to access the complete market intelligence to support your 2026 strategic agenda and ensure your organization is positioned to capitalize on the opportunities emerging across the fresh meat packaging sector.
For detailed analysis of this topic, please visit the official page: Fresh Meat Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Parcel Lockers Hit $1.2B in 2025, Forecast 12.5% CAGR to $2.7B by 2032
By pmarketresearch, 2026-09-15
Intelligent Parcel Locker Market: Strategic Imperatives for the 2026 Decision-Maker
The global logistics landscape is undergoing a structural recalibration. As e-commerce penetration deepens across commercial and residential verticals, the final mile has emerged as the most cost-intensive and operationally fragile segment of the supply chain. In this environment, intelligent parcel lockers have transitioned from a peripheral convenience to a core infrastructure asset. PW Consulting's latest market research on the Intelligent Parcel Locker Market is engineered to equip executives, investors, and logistics strategists with the analytical rigor required to navigate the 2026-2032 horizon with confidence.
This report is not a static snapshot of historical numbers. It is a forward-looking strategic instrument designed to decode purchasing behavior, competitive maneuvering, regulatory friction, and technology adoption curves. The following analysis outlines the report's architectural logic, previews the macro-economic trajectory, and demonstrates why institutional decision-makers must treat intelligent locker networks as a board-level priority.
Macro Trajectory: Sizing the Inflection Point
Our methodology constructs a granular baseline that traces the market's evolution from 2020 through 2025, followed by a disciplined forecast window extending to 2032. Over the historical observation period, the global market has progressed from approximately 800 million USD in 2020 to a 2025 baseline of 1.2 billion USD. This 50 percent cumulative expansion reflects sustained capital deployment by postal operators, third-party logistics providers, property developers, and retail integrators seeking to offload delivery friction from human handlers to automated, contactless nodes.
The forward-looking projection indicates that the addressable revenue pool will expand to roughly 1.38 billion USD in 2026 and continue compounding at a rate of 12.5 percent annually. By 2032, the market is positioned to exceed 2.7 billion USD. These figures are anchored in observable adoption signals, including carrier-neutral network growth, real estate integration mandates, and the acceleration of self-service pickup models across urban and suburban geographies. The sustained double-digit trajectory underscores a structural shift rather than a cyclical bump. Enterprises that internalize this growth vector early will secure first-mover advantages in site leasing, carrier partnerships, and software-driven locker fleet orchestration.
Strategic Report Architecture: What Decision-Makers Will Find Inside
Market intelligence loses its value when it cannot be translated into action. PW Consulting's research is organized around operational deployment rather than abstract theorization. The report dissects the intelligent locker ecosystem across multiple analytical dimensions, providing readers with a replicable framework for capital allocation, vendor selection, and geographic prioritization.
The segmentation architecture maps the installed base and revenue attribution across product typologies that reflect distinct use cases and buyer profiles. Modular locker configurations, postal-grade automated nodes, temperature-controlled units engineered for fresh food and specialized logistics, and multi-function laundry or extended-service lockers each present unique total-cost-of-ownership profiles, site requirements, and user-experience considerations. The report isolates the demand characteristics, operational trade-offs, and growth catalysts for each category, enabling category managers to align procurement with specific delivery pain points rather than adopting a one-size-fits-all hardware posture.
Application-level analysis grounds the hardware discussion in real-world deployment environments. High-traffic commercial buildings, residential condos and apartment complexes, retail buy-online-pick-up-in-store augmented ecosystems, academic campuses, and specialty or emerging use cases all exhibit divergent throughput requirements, access-control protocols, and integration complexity. By separating these verticals, the research equips stakeholders with application-specific benchmarks for utilization rates, peak-load management, and return on infrastructure spend.
Geographic coverage is structured to illuminate regional market maturity, regulatory climates, and infrastructure readiness without reducing the narrative to superficial regional summaries. Readers will encounter a comparative lens that connects urban density, last-mile labor economics, carrier network topology, and municipal permitting environments to localized deployment feasibility. This regional framing is critical for multinational operators evaluating where to concentrate capital or how to sequence market entry across diverse regulatory jurisdictions.
Beyond segmentation, the report delivers an actionable competitive intelligence module, a dynamics and regulatory environment scan, and an industry-context synthesis that directly informs operational strategy. These components are described in detail below.
Competitive Landscape: The Players Shaping the Next Phase
The intelligent parcel locker market is characterized by a measured degree of concentration, with the top three participants collectively accounting for approximately a quarter of industry revenue and the top five firms representing roughly thirty-five percent. This structure signals a market in which scale advantages, carrier relationships, and software interoperability differentiate credible platforms from commoditized hardware suppliers. The competitive analysis within the report profiles organizations whose strategic moves define the market's trajectory.
Quadient has established itself as a significant force through its carrier-agnostic Parcel Pending network, an extensive footprint of more than eighteen thousand locations, and a management software layer designed to serve residential, retail, and commercial deployments. Its strategic partnerships, including the activation of additional smart locker capacity across the United Kingdom with Evri and the integration of smart locker points into Scotland's rail network with ScotRail for comprehensive commuter access, illustrate how established operators expand reach by embedding locker nodes into mobility infrastructure and alternative pickup ecosystems.
In Europe, OMNIC contributes to the competitive fabric with indoor and outdoor smart locker series engineered for logistics and e-commerce use cases, including IP-rated protection and solar off-grid configurations. These features reflect an industry-wide emphasis on deployment flexibility and resilience in locations where grid power or fixed connectivity may be constrained. KEBA continues to reinforce its position through partnerships with major postal and parcel operators such as bpost and GLS, supplying automated locker infrastructure that aligns with national and cross-border delivery workflows.
ZHILAI operates with a strong product-development orientation, offering smart locker solutions that span solar-powered, Bluetooth-enabled, and refrigerated models tailored to last-mile delivery and self-service pickup. Such diversification indicates a market trend in which hardware differentiation increasingly hinges on energy independence, connectivity protocols, and specialized climate control for perishable or sensitive goods. Postal Source, positioned in the United States, brings intelligent locker solutions focused on secure package management and streamlined operational workflows, reinforcing the demand for integrated security, inventory visibility, and staff efficiency in institutional and commercial settings.
Beyond profiling incumbents, the report tracks the most consequential recent developments that alter competitive dynamics. Acquisition activity, such as the expansion of smart locker network coverage through the consolidation of courier assets, signals an industry in which geographic density and carrier relationships are actively being bought, built, or partnered. Partnership announcements indicate the acceleration of large-scale deployments across national borders, including multi-thousand-unit rollouts in Canada and sustained capacity expansion in European rail and retail contexts. These events are examined not as isolated press releases but as indicators of consolidation strategy, partnership economics, and the pace at which network effects are being monetized.
Dynamics, Regulatory Environment, and Operational Realities
Technology adoption rarely unfolds in a regulatory vacuum. The intelligent parcel locker market is being shaped by intersecting forces that influence cost structures, deployment timelines, data governance, and operational design. The report synthesizes these forces into a coherent dynamics framework so that executives can anticipate friction and align their strategies accordingly.
Cost pressure on last-mile labor remains a persistent catalyst. Automated self-service access reduces dependency on manual handoffs and repetitive residential drop-off attempts, enabling postal and courier providers to reallocate workforce capacity toward higher-value routing and exception handling. The report evaluates how this labor arbitrage intersects with site economics, carrier co-opetition, and shared-network models, helping operators determine whether to build proprietary locker assets, lease neutral space, or participate in multi-carrier common-pool networks.
Regulatory considerations are equally decisive. Across Europe, universal service providers have expanded parcel locker networks in contexts shaped by net neutrality rules and associated policy objectives aimed at lowering delivery costs and improving consumer convenience. At the same time, data sovereignty requirements mandate secure locker-based data handling for parcel tracking and access, creating compliance obligations that affect software architecture, data residency choices, and vendor selection. Spectrum and wireless regulations further enable real-time IoT notifications, supporting contactless operations and remote monitoring at scale. These regulatory threads are mapped to practical implications for system design, localization, and risk management.
Sustainability and infrastructure efficiency provide a third dynamic pillar. Deploying smart parcel lockers supports sustainable urban logistics by reducing the number of physical delivery trips required in high-density cities. This operational efficiency carries implications for carbon accounting, municipal partnerships, and site-selection logic. The report frames sustainability not as a peripheral narrative but as a cost and reputation lever that can tip the calculus in congested urban markets where delivery density and dwell time directly influence profitability.
How the Intelligence Converts Into Decisions
A market study earns its place on an executive dashboard when it clarifies choices. PW Consulting's research translates structural data into decision paths across several common corporate scenarios.
Worldwide Luggage Storage Locker Market
For logistics and delivery operators, the report clarifies where locker networks can compress cost per parcel, reduce failed-delivery penalty cycles, and extend pickup windows without expanding headcount. It outlines how carrier-agnostic and carrier-specific models differ in monetization, utilization, and partnership leverage, allowing operators to evaluate build-versus-partner trade-offs with greater precision.
For real estate owners and property managers, the analysis defines how smart locker installations can enhance tenant retention, support residential and commercial amenities, and generate ancillary revenue or service-differentiation value. Application-level benchmarks help decision-makers estimate throughput, access control integration, and hardware selection aligned with occupancy profiles and delivery volumes.
For retail and omnichannel operators, the report examines how locker infrastructure can reinforce buy-online-pick-up-in-store strategies by offloading counter congestion, extending retrieval windows, and improving the consistency of order fulfillment handoffs. It situates locker deployment within broader omnichannel cost structures and customer-experience expectations, making it possible to compare locker-based pickup against in-store and curbside alternatives on total operating economics.
For investors and technology vendors, the competitive concentration profile and recent partnership and acquisition activity provide signals about where scale is being accumulated, which geographies are attracting deployment momentum, and what product features are becoming table stakes versus differentiators. This perspective supports portfolio decisions, partnership targeting, and product-roadmap prioritization.
Why 2026 Is a Defining Year for Intelligent Locker Strategy
The convergence of sustained double-digit growth, evolving regulatory frameworks, carrier network experimentation, and application-specific hardware diversification places 2026 at a strategic inflection point. Enterprises that continue to treat parcel lockers as ad hoc hardware purchases risk underutilizing assets, misaligning with carrier expectations, and missing opportunities to embed locker nodes into broader mobility and retail ecosystems. Organizations that approach intelligent lockers as managed infrastructure can convert them into demand-smoothing assets, labor-efficiency tools, and customer-experience differentiators.
PW Consulting's Intelligent Parcel Locker Market research is designed to support that shift from intuition-led deployment to evidence-led strategy. The full study provides the deep segmentation detail, competitive event analysis, regulatory mapping, and forward scenarios required to translate macro momentum into operational plans. Readers seeking complete regional revenue distributions, application-level breakdowns, and company-specific investment signals will find the full dataset and interpretive commentary essential to precise planning.
Intelligent Parcel Locker Market
To access the complete report and integrate its findings into your 2026 planning cycle, visit the PW Consulting report page for the Intelligent Parcel Locker Market. The full research package delivers the comprehensive segmentation, competitive intelligence, and scenario analysis necessary to inform capital allocation, vendor selection, and deployment sequencing with confidence.
For detailed analysis of this topic, please visit the official page: Intelligent Parcel Locker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com