

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Fresh Meat Packaging Market Hits $4.09B in 2025, Projects 5.12% CAGR Through 2032|PW Consulting

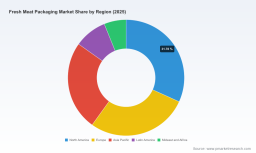
Strategic Horizons in Fresh Meat Packaging: Navigating Growth, Regulation, and Material Shifts Through 2032
The fresh meat packaging sector stands at a critical inflection point. Over the past five years, the market has demonstrated steady expansion, moving from a baseline of approximately $3.12 billion in 2020 to a projected $4.36 billion by 2026. This trajectory reflects more than simple population growth or rising protein consumption. It signals a structural transformation in how processors, retailers, and packaging suppliers approach shelf-life preservation, sustainability compliance, and material economics. For executive teams evaluating capital allocation, supplier partnerships, or product portfolio adjustments in 2026, understanding the underlying mechanics of this market is no longer optional. It is a core component of operational resilience and competitive positioning.
Our newly released Fresh Meat Packaging Market research study provides a comprehensive, data-backed roadmap covering the historical period from 2020 through 2025 and extending forward to 2032. The report is designed specifically for strategic planners, procurement leaders, and investor analysts who require actionable intelligence rather than high-level conjecture. What follows is an executive preview of the market architecture, competitive dynamics, and regulatory forces that will define the sector in the coming years. Readers seeking granular segmentation figures, proprietary company-level revenue estimates, and detailed scenario modeling are encouraged to access the full report for complete market intelligence.
Market Trajectory and the Emerging Growth Framework
The historical record from 2020 to 2025 reveals a market that has consistently outperformed flat growth expectations. After navigating pandemic-era supply chain disruptions and inflationary pressures, the sector recovered with renewed momentum, reaching an estimated $4.09 billion in 2025. Forward projections indicate a compound annual growth rate of 5.12 percent across the forecast horizon of 2026 to 2032. By the end of that period, overall market value is positioned to approach the $5.8 billion threshold.
Several structural drivers underpin this trajectory. First, the retail and food service sectors continue to prioritize case-ready and modified-atmosphere packaging formats that reduce handling labor, minimize cross-contamination risk, and extend display life. Second, consumer expectations around transparency, freshness indicators, and sustainable material choices are forcing brands to rethink traditional foam-and-film architectures. Third, regional protein consumption patterns are shifting, with emerging markets expanding their cold-chain infrastructure and developed markets investing in premium, value-added meat formats. These overlapping trends create a favorable demand environment, but they also introduce complexity. Companies that treat packaging as a commodity input rather than a strategic enabler will find themselves exposed to margin compression, compliance risks, and supplier dependency.
The full research study deconstructs these growth drivers across multiple dimensions, including material type evolution, application-specific demand patterns, and regional market maturity curves. Rather than presenting static tables, the analysis maps how each segment is likely to interact with regulatory mandates, raw material volatility, and technological adoption timelines. This integrated view allows decision-makers to stress-test their assumptions against realistic market pathways.
Regulatory Pressures and the Sustainability Imperative
One of the most consequential forces reshaping the fresh meat packaging landscape is the accelerating pace of extended producer responsibility legislation and packaging waste regulations. In the United States, state-level EPR programs for packaging now cover approximately one in five Americans. Jurisdictions such as Oregon, California, Maryland, and Washington have implemented or are finalizing producer fee structures that tie financial obligations directly to recyclability performance and recycled content minimums, with requirements taking effect across the 2025 to 2026 window. California's SB 54, for example, expanded producer responsibility frameworks for packaging categories including fresh meat applications, with fee schedules administered by the Circular Action Alliance.
Across the Atlantic, the European Union's Packaging and Packaging Waste Regulation introduces binding recycled content thresholds for plastic packaging, targeting a minimum of 25 percent by 2025 and 30 percent by 2030. The regulatory framework also mandates design-for-recyclability criteria and reinforces EPR obligations. For fresh meat packaging suppliers, this means that legacy multi-material laminates and non-recyclable foam variants face increasing cost and compliance headwinds. Design teams are being compelled to evaluate mono-material constructions, fiber-based alternatives, and recyclable barrier films with far greater urgency than before.
These regulatory shifts interact directly with raw material economics. Limited availability of PET and PE resins has pushed costs for meat trays and films upward by an estimated 15 to 25 percent, accelerating the commercial evaluation of paper-based and recycled-content alternatives. At the same time, operational cost dynamics within the meat processing sector itself are evolving. Proposed USDA adjustments to swine slaughter line speeds during the 2025 to 2026 period are estimated to generate industry cost savings on the order of $262 million over a decade, which may indirectly free up capital for packaging innovation and automation investments. Together, these regulatory and input-cost forces are compressing the window for incremental change and rewarding companies that can deliver compliant, sustainable solutions at scale.
Competitive Landscape and Strategic Positioning
The fresh meat packaging market exhibits a moderate level of concentration, with the top three players accounting for roughly 46 percent of market share and the top five collectively representing around 52 percent. This concentration reflects the specialized nature of the sector: success requires deep application expertise, regulatory navigation capabilities, and manufacturing footprints that can support case-ready formats, vacuum skin packaging, and sustainable material transitions. The competitive set is anchored by a group of globally positioned companies that are actively reshaping their portfolios in response to consumer, retailer, and regulatory demands.
Amcor plc, headquartered in Zurich, remains a global leader in responsible and recyclable flexible and rigid packaging solutions tailored specifically for fresh meat products, with a strong emphasis on mono-material films and trays. Sealed Air Corporation, based in Charlotte, North Carolina, continues to drive category standards through its Cryovac vacuum skin packaging and preformed tray systems for fresh beef, pork, lamb, and poultry, complemented by automated equipment and shrink tunnel capabilities. Berry Global Group, headquartered in Evansville, Indiana, is advancing next-generation vacuum skin packaging and sustainable flexible solutions that aim to extend shelf life while improving recyclability profiles.
Vacuum Skin Packaging Market
Pactiv Evergreen Inc., operating out of Lake Forest, Illinois, maintains a comprehensive manufacturing base for fresh meat packaging, including foam trays, films, and case-ready solutions serving processors and retailers. Huhtamaki Oyj, based in Helsinki, Finland, supplies sustainable fiber-based and flexible packaging options designed for fresh meat applications, positioning itself at the intersection of material innovation and circular design. Mondi plc, headquartered in Weybridge, United Kingdom, has emerged as a notable innovator in paper-based mono-material recyclable packaging and pulp solutions for fresh meat trays and films. Winpak Ltd, based in Winnipeg, Manitoba, produces heat-sealable membranes, die-cut lids, and flexible packaging for fresh meat and broader food processing operations. Sonoco Products Company, from Hartsville, South Carolina, provides paperboard trays, tubes, and composite packaging suited to fresh meat applications. Coveris Management GmbH, located in Vienna, Austria, has been developing paper-based and flexible sustainable packaging, including its MonoFlex Fibre range for fresh meat. Finally, Edelmann Group, headquartered in Heidenheim, Germany, supplies high-performance packaging solutions and facilities focused on fresh meat products.
Recent corporate activity underscores the strategic intensity in this space. Mondi partnered with Scan Sverige in May 2024 to create recyclable polypropylene-based mono-material food packaging for fresh meat, signaling a collaborative approach to recyclability challenges. That same year, Mondi completed an acquisition of the Hilton Pulp Mill in Alberta, Canada, to strengthen its sustainable paper-based packaging production capacity for North America. Coveris expanded its packaging portfolio with a substantial investment in a new vacuum skin packaging facility in Winsford, UK, in April 2024, and shortly thereafter introduced the MonoFlex Fibre paper-based flexible packaging range in June 2024, a fully recyclable offering designed for fresh meat applications. These moves illustrate a broader industry pattern: companies are not merely adjusting product lines but are reinvesting in manufacturing capability, forming strategic partnerships, and accelerating the commercial rollout of recyclable and fiber-based alternatives.
Report Scope and Practical Analytical Assets
The full Fresh Meat Packaging Market study is structured to support a wide range of strategic use cases, from market entry assessments and competitive benchmarking to supply chain diversification and sustainability roadmap planning. The report combines historical baselines with forward-looking forecasts, enabling teams to align near-term procurement decisions with long-term portfolio strategy. Key analytical components include a detailed market size and growth trajectory analysis, segmentation insights across material types and application categories, regional market evaluations, and a comprehensive competitive profiling section that maps company positioning, recent developments, and strategic intent.
Fresh Meat Packaging Market
Beyond quantitative modeling, the study provides qualitative analysis of the forces shaping supplier-buyer dynamics. This includes an examination of how EPR frameworks and recyclability mandates are altering cost structures, how raw material availability is influencing material substitution timelines, and how automation and case-ready packaging adoption are reshaping operational requirements at the processor and retailer level. The report also incorporates a review of recent corporate developments, partnership activity, and facility investments that signal where competitive advantages are being built. For organizations evaluating supplier negotiations, the profiling section offers a structured view of each major player's capabilities, geographic reach, and innovation focus, helping teams identify alignment points and potential risks.
Implications for 2026 Decision-Making
As organizations plan their 2026 initiatives, several strategic questions will determine whether they capture value or cede ground in the fresh meat packaging market. How will your packaging portfolio adapt to evolving recyclability mandates and recycled content requirements without compromising structural integrity or shelf-life performance? Are your material sourcing strategies resilient enough to withstand continued resin volatility and regional supply constraints? Does your current supplier base offer the innovation velocity and compliance transparency required by retailers and regulators? And finally, are you positioned to leverage sustainable packaging as a differentiation lever in a market where consumers and procurement teams increasingly weigh environmental performance alongside cost and functionality?
The answers to these questions depend on access to reliable, forward-looking market intelligence. The Fresh Meat Packaging Market research study provides the analytical foundation needed to navigate these decisions with confidence. By integrating historical performance data, forecast modeling, regulatory context, and competitive profiling into a single framework, the report enables leaders to move beyond reactive adjustments and toward proactive strategy formulation.
For teams seeking complete segmentation data, company-level market share estimates, regional growth pathways, and detailed scenario analysis, the full report delivers the depth required for rigorous planning. We invite you to access the complete market intelligence to support your 2026 strategic agenda and ensure your organization is positioned to capitalize on the opportunities emerging across the fresh meat packaging sector.
For detailed analysis of this topic, please visit the official page: Fresh Meat Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com