

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dental 3D Printer Market Hits $143.76M in 2025, Projects 6.98% CAGR to 2032

Strategic Horizons in the Dental 3D Printer Market: A 2026 Decision-Maker's Guide
The Inflection Point: Why 2026 Demands Precision Intelligence
The dental technology sector is navigating a transformative phase where digital adoption is no longer optional but existential. For stakeholders operating in orthodontic labs, oral surgery centers, and prosthetic manufacturing, the transition from traditional methodologies to additive manufacturing represents a fundamental shift in workflow efficiency and patient outcomes. However, the pace of innovation has outstripped the ability of many organizations to interpret market signals accurately. This is where PW Consulting's latest Dental 3D Printer Market Research becomes a critical asset for strategic planning.
As we move into 2026, the market is characterized by a complex interplay of technological maturity, regulatory advancements, and evolving reimbursement frameworks. Our analysis indicates that the global revenue generated by this sector is projected to reach approximately 158.83 Million USD in 2026, reflecting a steady trajectory from the 143.76 Million USD recorded in the base year of 2025. This growth is not merely linear; it is underpinned by a Compound Annual Growth Rate (CAGR) of roughly 6.98% over the forecast period extending to 2032. Such figures suggest a robust expansion, yet they mask the nuanced volatility present within specific technology stacks and application verticals.
Decision-makers in 2026 face a bifurcated challenge. First, they must allocate capital towards hardware and material infrastructure that promises longevity amidst rapid obsolescence. Second, they must navigate a regulatory environment that is tightening around biocompatible materials. Our report is designed to dissect these layers, offering a roadmap that transforms raw data into actionable investment theses. We do not simply present growth numbers; we contextualize them against the backdrop of competitive intensity and technological differentiation.
Market Trajectory and Structural Dynamics
Understanding the historical context is vital for projecting future performance. The period from 2020 to 2025 established the foundational demand for digital dentistry. Revenue figures climbed from 98.45 Million USD in 2020 to 133.84 Million USD by 2024, signaling accelerated adoption rates among dental practices and laboratories. The jump to 143.76 Million USD in 2025 consolidates this trend, indicating that digital printing is transitioning from a premium novelty to a standard operational utility.
Looking forward through the forecast period of 2026 to 2032, the market is expected to surpass 224.42 Million USD by the end of the cycle. This upward trajectory is fueled by several key dynamics. Technological advancements in printing speed and resolution are reducing chairside times, making same-day restorations increasingly viable. Furthermore, the integration of automated workflows is lowering the skill barrier for technicians, thereby expanding the addressable market beyond high-volume specialty labs to smaller general practices.
However, growth is not uniformly distributed. The market concentration reveals a moderately fragmented landscape. The top three companies hold a combined share of 24.6%, while the top five control 26.2%. This indicates that while key players dominate specific niches, there is ample room for innovation-driven entrants and regional specialists to capture value. For a corporate strategist, this fragmentation suggests both partnership opportunities and acquisition targets that may not be immediately apparent from surface-level revenue data.
Key structural drivers identified in our deep dive include:
- Regulatory Catalysts: Recent FDA 510(k) clearances for specific resin formulations are unlocking new application areas, particularly in fixed hybrid dentures and temporary restorations, reducing liability risks for adopters.
- Reimbursement Evolution: Advanced reimbursement frameworks in key developed markets are incentivizing the use of digital restorations, directly influencing procurement budgets and ROI calculations for dental practices.
- Workflow Integration: The shift towards open material libraries and interoperable software ecosystems is reducing vendor lock-in, empowering labs to optimize cost structures without sacrificing material biocompatibility.
Competitive Arena: Innovation vs. Scale
The competitive landscape is defined by a tension between established industrial giants and agile specialized innovators. Our analysis covers the strategic positioning of key entities such as SprintRay , Formlabs , Asiga , LuxCreo , 3D Systems , Stratasys , Carbon , and Ackuretta . Each player brings a distinct value proposition to the 2026 marketplace, and understanding these nuances is essential for supply chain negotiation and technology selection.
SprintRay continues to strengthen its chairside presence with systems like the Pro 2 and Midas, specifically targeting the workflow for crowns, bridges, and surgical guides. Their strategic focus on biocompatible resins aligns with the trend towards in-office production. Similarly, Formlabs maintains a strong foothold with its Form 4B SLA printers, appealing to labs requiring versatile capabilities for models and temporary restorations. Their expansion into Premium Teeth Resin demonstrates a commitment to material science as a competitive moat.
In the high-precision segment, Asiga differentiates through its open material library, catering to labs that prioritize restoration quality and flexibility over closed ecosystems. Meanwhile, LuxCreo is pushing the boundary of speed and automation with its iLux Pro system, aiming to streamline the production of clear aligners with FDA-cleared workflows for same-day orthodontic appliances. This focus on automation addresses the growing labor shortage in dental technology sectors.
On the industrial side, 3D Systems and Stratasys leverage broad portfolios. 3D Systems markets the NextDent 5100 and Jetted Denture Solution, emphasizing multi-material capabilities for dentures and guides. Stratasys offers PolyJet multi-material printing with the J5 DentaJet, focusing on realistic anatomical models and complex restorations. Carbon introduces flexible solutions with their FP3D resin for removable partial dentures, addressing comfort and functionality needs. Ackuretta rounds out the competitive field with dedicated manufacturing solutions for restorations and models.
Metal 3D Printer Market
Recent developments highlight the speed of innovation. In mid-2025, 3D Systems achieved full commercial release of their NextDent Jetted Denture Solution for multi-material monolithic dentures, marking a significant step in automation. Shortly after, Carbon announced the full commercial availability of FDA-cleared FP3D resin for flexible removable partial dentures in North America. These milestones are not just product launches; they are indicators of where the market value is shifting—towards materials that offer enhanced mechanical properties and workflow solutions that reduce human intervention.
Regulatory and Reimbursement Pressures Shaping 2026
The regulatory environment is perhaps the most critical variable for risk assessment in 2026. The clearance of specific materials dictates what can be printed, where it can be used, and the liability exposure for the provider. For instance, the FDA 510(k) clearance of SprintRay's OnX Tough 2 resin for fixed hybrid dentures and Formlabs' Premium Teeth Resin for temporary crowns and veneers opens specific revenue streams that were previously restricted or required alternative manufacturing methods. Similarly, the clearance of 3D Systems' NextDent Jetted Denture Solution validates multi-material monolithic denture printing, potentially disrupting traditional denture fabrication lines.
These regulatory wins are compounded by reimbursement dynamics. In North America, advanced reimbursement frameworks for digital restorations are driving the largest share of market activity. This regional advantage creates a halo effect, encouraging adoption in other regions but also highlighting the dependency of market growth on policy stability. Our report provides a granular look at how these regulatory and reimbursement signals interact with technology adoption curves, allowing executives to anticipate compliance costs and reimbursement delays that could impact cash flow.
What Our Full Report Reveals: Beyond the Headlines
While the macro trends provide a comforting narrative of growth, the strategic value of PW Consulting's full report lies in the granular intelligence required to execute on these trends. The overview provided here sets the stage, but the comprehensive document offers the tactical data necessary for board-level decisions. Subscribers to our full research access detailed breakdowns that clarify where capital should be deployed for maximum return.
Specifically, the full edition delivers actionable intelligence on:
- Technology Segmentation: Detailed analysis of how SLA, DLP, LCD, and other printing technologies are allocating market share, allowing you to identify which hardware platforms are gaining traction in specific clinical workflows.
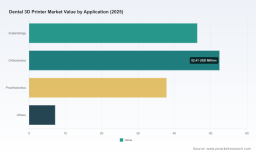
- Application Verticals: Deep dives into how implantology, orthodontics, prosthodontics, and other applications are contributing to revenue growth, helping you align your product offerings or service lines with the highest growth segments.
- Regional Performance: Nuanced insights into how North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa are evolving differently, critical for supply chain localization and market entry strategies.
- Vendor Benchmarking: Comparative assessments of the key players mentioned above, evaluating their R&D pipelines, patent portfolios, and strategic partnerships relative to their market position.
In an environment where 6.98% CAGR represents millions in potential value, guessing is not a strategy. The difference between capturing market share and losing relevance often comes down to understanding the subtle shifts in material science regulations and the specific adoption rates of chairside versus lab-side printing solutions. Our report removes the guesswork.
Conclusion: Aligning Strategy with Market Reality
The Dental 3D Printer Market in 2026 is a landscape of opportunity tempered by complexity. The projected revenue of 158.83 Million USD this year is a testament to the sector's vitality, but it is the underlying dynamics—regulatory clearances, reimbursement shifts, and competitive technological races—that will determine individual company success. As the market matures towards 2032, the ability to adapt to open material ecosystems, leverage automated workflows, and navigate multi-material printing validations will separate leaders from followers.
Dental 3D Printer Market
PW Consulting's research is designed to equip you with the clarity needed to navigate this evolution. By integrating historical performance data with forward-looking scenario analysis, we provide the intelligence necessary to optimize investment portfolios, refine go-to-market strategies, and mitigate regulatory risks. The growth is real, but the path to capturing it requires precision. We invite you to explore the full depth of our findings to ensure your strategic decisions are grounded in comprehensive, expert-validated data.
For detailed analysis of this topic, please visit the official page: Dental 3D Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com