

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Anti-Decubitus Cushions Market Hits USD 737.71M in 2025, Expands at 6.05% CAGR to 2032

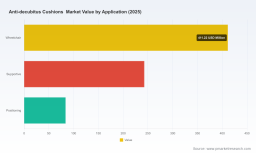
Navigating the Next Wave: Strategic Intelligence for the Anti-decubitus Cushions Market (2026–2032)
The global landscape for pressure injury prevention is undergoing a structural shift. As healthcare systems worldwide grapple with aging demographics, prolonged hospitalization costs, and an increasing emphasis on patient mobility, the anti-decubitus cushions market has emerged as a critical intersection of medical device innovation, reimbursement policy, and material science. For executives, investors, and product strategists, the period from 2026 through 2032 represents a decisive window where competitive positioning, regulatory navigation, and supply chain resilience will separate market leaders from followers.
Our latest comprehensive market research delivers more than historical retrospectives. It is engineered as a decision-grade intelligence platform, translating complex demand signals, material transitions, and regulatory developments into actionable strategic roadmaps. This article serves as a preview of the analytical depth contained in the full report, designed to demonstrate exactly how the study can operationalize market uncertainty into confident corporate strategy.
Macro Trajectory: A Market Built on Sustained, Compounding Growth
Understanding where the market is headed requires first grounding strategy in verified historical momentum. Between 2020 and 2025, the global anti-decubitus cushions sector demonstrated consistent expansion, climbing from approximately 549.96 million USD to 737.71 million USD. That trajectory did not plateau at the five-year mark. Looking forward, the market is projected to reach 791.83 million USD in 2026, with growth accelerating across the forecast horizon to close at 1112.91 million USD by 2032.
This expansion translates to a compound annual growth rate of 6.05 percent across the full 2026–2032 forecast period. For strategic planners, this is not merely a growth statistic. It signals a market where incremental gains are sustained, where demand drivers are structural rather than cyclical, and where early-mover advantages in product innovation, distribution architecture, and reimbursement alignment can compound over nearly a decade. The full report unpacks the underlying demand elasticity, substitution patterns, and regional momentum shifts that make this CAGR actionable, while deliberately reserving granular breakdowns for clients who need them for internal modeling and board-level forecasting.
What the Report Delivers: From Market Data to Executable Strategy
A high-quality market study does not simply report what happened. It equips leadership teams to anticipate what will happen next and to allocate resources accordingly. Our anti-decubitus cushions market research is structured around operational utility. Every analytical layer is designed to answer boardroom and strategy-team questions before they become crises.
The report opens with a rigorous demand-side architecture, mapping how clinical requirements, procurement cycles, and end-user behavior converge to shape volume and pricing dynamics. It traces the supply-side ecosystem, examining raw material sourcing, manufacturing constraints, and the transition toward medical-grade materials that balance durability with skin-contact safety. The segmentation analysis isolates how different product architectures and use-case categories perform across the demand spectrum, providing context for product portfolio decisions, pricing architectures, and channel strategy.
Beyond segmentation, the study delivers a comprehensive competitive benchmarking framework. Rather than relying on surface-level revenue estimates, the analysis reconstructs how leading players differentiate themselves through engineering, clinical positioning, and service ecosystems. The report also embeds regulatory and reimbursement intelligence directly into the market dynamics section, ensuring that strategic recommendations account for the policy environment that governs market access, procurement eligibility, and compliance costs.
Clients will find scenario-based modeling, sensitivity analysis around key demand drivers, and strategic implication matrices tailored for product development, market entry, M&A screening, and portfolio optimization. The full version preserves the complete analytical architecture, including calibrated forecasts and cross-referenced data tables, allowing strategy teams to build internal models with confidence.
Competitive Landscape: Engineering Differentiation in a Concentrated Market
Market concentration remains a defining feature of the anti-decubitus cushions sector. The top three players command roughly 35 percent of market share, while the top five extend that footprint to approximately 45 percent. Such concentration does not imply stagnation. In fact, it reflects a market where brand credibility, clinical validation, and engineering maturity carry substantial weight. The full report maps these players in detail, but even a high-level view reveals how competitive advantage is being constructed.
Anti-decubitus Cushions Market
Direct Healthcare Group (DHG)
Headquartered in Caerphilly, Wales, Direct Healthcare Group has anchored its cushion portfolio around clinically differentiated pressure management technologies. Its Dyna-Form Mercury Advance alternating pressure cushion targets very high-risk patient populations, while the Dyna-Tek intelligent air cushion line focuses on dynamic pressure redistribution and proactive ulcer prevention. The strategic lesson here is clear: clinical risk stratification is becoming a product design principle, and manufacturers that align their engineering with specific patient acuity tiers are building defensible positioning.
etac
Based in Kista, Sweden, etac has emphasized precision in pressure redistribution and patient positioning through its Star vertical air-cell seat cushions. Designed for high-risk pressure injury prevention, these products highlight the growing importance of combining pressure management with postural support. Companies that integrate positioning functionality into anti-decubitus design are not only addressing clinical outcomes but also expanding the functional value proposition that procurement teams and clinicians evaluate during purchasing decisions.
Invacare
Invacare, operating from Elyria, Ohio, continues to reinforce its presence through pressure care wheelchair cushions such as the Matrx Flo-tech series, which combine gel and foam inserts to support body contouring and pressure ulcer prevention. This approach underscores the enduring relevance of hybrid material architectures. As raw material specifications evolve, manufacturers capable of balancing comfort, pressure distribution, and long-term durability will maintain a strong competitive foothold, particularly where procurement teams weigh total cost of ownership against clinical performance.
Outdoor Cushions Market
Permobil (ROHO)
Permobil, through its ROHO cushion lineage based in Belleville, Illinois, has built a recognized reputation around air-cell cushion systems, including both custom and standard models. The ROHO platform illustrates how deep specialization in pressure redistribution technology can create strong brand loyalty among clinicians and end-users. In a market where seating stability and pressure distribution performance are governed by rigorous standards, companies that maintain consistent technical validation and product customization capabilities are well positioned to defend premium positioning.
The full report extends this competitive analysis into a structured benchmarking framework that evaluates differentiation vectors, likely strategic moves, and vulnerability zones. Clients gain insight into where incumbents are concentrating their engineering efforts and where white space may exist for targeted product entry or partnership strategies.
Regulatory and Reimbursement Realities: The Invisible Architecture of Market Access
In medical device markets, competitive strategy cannot be separated from regulatory and reimbursement architecture. Anti-decubitus cushions operate within a compliance environment that shapes both market entry and commercial velocity. The report embeds these dynamics directly into its market analysis so that strategic recommendations reflect real-world access conditions rather than idealized demand curves.
Wheelchair cushions fall under FDA device classifications relevant to flotation cushions and wheelchair components. Many products in this category are designated as Class I devices generally exempt from 510(k) premarket notification, yet they still require establishment registration and listing. This regulatory posture lowers certain barriers to market presence while simultaneously elevating the importance of manufacturing discipline, quality systems, and post-market compliance. The full report explains how these requirements affect competitive entry timing, cost structures, and risk management for both established players and new entrants.
On the reimbursement side, pressure-reducing support surfaces, including anti-decubitus cushions, are covered under the Durable Medical Equipment benefit defined in the Social Security Act. This coverage pathway is a critical enabler of patient access and a stabilizing force for demand. However, reimbursement dynamics also influence procurement behavior, prescribing patterns, and the commercial calculus used by manufacturers when setting pricing architecture and service offerings. The study examines how coverage frameworks interact with clinical adoption and procurement cycles, providing context for forecasting and market-entry planning.
Beyond federal classification and coverage, the market is shaped by performance and safety standards. Anti-decubitus cushions must align with flammability requirements such as BS7176:2007 for medium-hazard applications, and they must be launderable to support inspection and hygiene protocols. Furthermore, pressure care cushions are expected to meet ISO 7176 standards for wheelchair seating stability and pressure distribution performance. These standards are not administrative footnotes. They define the technical boundary within which product differentiation is credible. The report treats them as strategic constraints and enablers, showing how compliance readiness influences product roadmaps, supplier selection, and market acceptance.
Material and Engineering Trends: Where Innovation Meets Durability
The technical evolution of anti-decubitus cushions is being driven by the need to reconcile clinical performance with material longevity. Alternating pressure cushions increasingly rely on gel inserts and air cells constructed from medical-grade polyurethane and foam materials. These material choices are not incidental. They directly affect durability, skin-contact safety, pressure redistribution quality, and lifecycle cost.
Strategically, this places material science at the center of product competitiveness. Companies that secure reliable access to medical-grade inputs, optimize foam and air-cell architectures for sustained performance, and design products that can withstand repeated laundering and inspection cycles will gain an advantage in both clinical reputation and total-cost positioning. The research previewed here highlights these dynamics, while the full report drills deeper into material substitution patterns, sourcing considerations, and the implications for manufacturing economics.
Why This Study Matters for 2026 Decision-Making
The 2026–2032 period will reward organizations that can connect macro demand signals to micro strategic actions. A market growing from roughly 791.83 million USD in 2026 toward over 1.1 billion USD by 2032 at a 6.05 percent CAGR is large enough to support multiple competitive strategies, but not large enough to tolerate misallocated investment. Success will depend on knowing where growth is structurally concentrated, how reimbursement and regulation shape access, where incumbents are vulnerable, and how material and engineering choices translate into commercial differentiation.
This research is designed to support exactly those decisions. It helps product leaders evaluate portfolio gaps, enables commercial teams to calibrate pricing and channel strategy, supports executives in assessing partnership or acquisition targets, and gives investors a rigorous framework for evaluating market risk and opportunity. Rather than presenting a static snapshot, the study builds a forward-looking analytical environment in which strategic choices can be stress-tested against plausible market scenarios.
Conclusion: Turn Insight Into Positioning
The anti-decubitus cushions market is not defined by a single breakthrough or a single driver. It is shaped by the interplay of clinical need, reimbursement structure, regulatory standards, material performance, and competitive concentration. Navigating that interplay successfully requires intelligence that is both granular and strategically framed.
This preview offers a view into the structure, scope, and strategic intent of our full market research. The complete report contains the full segmentation architecture, calibrated forecast tables, competitive benchmarking detail, and regulatory and reimbursement context needed to support board-level decisions, product planning, and market-entry strategy. For organizations preparing for the 2026–2032 growth cycle, the difference between reactive positioning and proactive strategy will come down to the quality of the intelligence beneath the decision. The full study is built to provide that foundation.
For detailed analysis of this topic, please visit the official page: Anti-decubitus Cushions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com