

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Infrared Lens Market Hits $192.35M in 2025, Projected to Reach $315.68M by 2032 at 7.52% CAGR

Navigating the Infrared Lens Market: Strategic Intelligence for the 2026 Decision Cycle
The infrared (IR) lens market is undergoing a period of structural transformation. Between 2020 and 2025, global revenue expanded from approximately 138.45 million USD to 192.35 million USD, reflecting a steady compound annual growth trajectory that analysts project will sustain a 7.52 percent CAGR through 2032. By the end of the forecast window, the market is expected to surpass 315.68 million USD. These figures, drawn from PW Consulting’s latest infrared lens market research, are more than historical markers. They signal a maturing supply chain, shifting material dependencies, and an intensifying competitive landscape that demands precise, forward-looking strategy.
For executives, procurement leaders, and R&D directors operating in 2026, the question is no longer whether infrared optics will continue to expand, but how to position organizations within a market defined by material scarcity, geopolitical realignment, and rapid product iteration. This article outlines the strategic architecture of our newly released market study, explains why its analytical framework is built for immediate enterprise decision-making, and previews the competitive and operational dynamics that will shape capital allocation, sourcing strategy, and product roadmaps over the next six years.
Why 2026 Demands a More Granular Market Lens
The 2025-to-2026 inflection point is particularly consequential. Forecast data places 2026 revenue at 208.75 million USD, with incremental growth accelerating through 2027 and 2028 before settling into a more measured climb toward 2032. This trajectory masks underlying volatility. Two structural forces are reshaping how infrared optics are sourced, designed, and deployed: raw material supply constraints and regulatory-driven sourcing requirements.
Germanium supply chain disruptions have already translated into extended lead times and pricing adjustments across the IR optics sector. At the same time, export controls on critical materials originating from China have introduced new risk vectors for defense, industrial, and automotive manufacturers. In response, domestic production of alternative materials, including chalcogenide glass, has gained momentum in the United States, creating a parallel supply pathway that reduces reliance on constrained import channels. These dynamics are not peripheral. They directly affect cost structures, time-to-market, and contractual flexibility.
Meanwhile, procurement standards tied to U.S. defense programs increasingly require NDAA-compliant domestic sourcing for infrared lens assemblies. Organizations that have built their supply chains around legacy international suppliers are now confronting compliance gaps that can delay program execution or disqualify bids entirely. The intersection of material scarcity, regulatory compliance, and domestic capacity expansion means that 2026 purchasing and engineering decisions must be informed by more than unit pricing. They require a comprehensive view of supplier resilience, material substitution pathways, and regional production footprints.
Our infrared lens market research is structured to translate these macro-level pressures into actionable intelligence. Rather than presenting static market snapshots, the study maps how supply chain architecture, material innovation, and regulatory frameworks are interacting to redefine competitive advantage.
What the Research Delivers: Operational Intelligence Over Headline Figures
A market study earns its place in the executive workflow when it bridges high-level trends with executable insights. PW Consulting’s infrared lens market report is built around that principle. The analysis begins with historical performance from 2020 through 2025 and extends into a forecast period running from 2026 to 2032, allowing decision-makers to evaluate both retrospective momentum and forward exposure. All figures are denominated in USD and measured in millions, providing a consistent baseline for financial modeling and scenario planning.
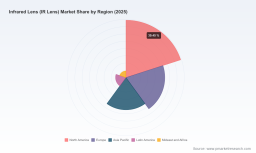
Beyond aggregate revenue and CAGR, the report dissects the market across three operational dimensions: type, application, and region. The type breakdown examines the relative positioning of germanium, silicon, and other materials, highlighting how performance requirements and cost constraints are influencing material adoption. The application analysis isolates demand drivers across thermal imaging, night vision, and other use cases, revealing where volume growth is being generated and which segments are experiencing the most intense pricing or specification pressure. The regional assessment maps revenue distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing context for where production capacity, end-user demand, and regulatory environments are converging.
Critically, none of these breakdowns are presented as static percentages or isolated figures. Each segmentation layer is evaluated against supply-side constraints, technological substitution trends, and end-market procurement behavior. This approach ensures that readers understand not just where revenue is concentrated, but why it is concentrated there, what could disrupt that concentration, and how to build strategy around both continuity and change.
Infrared Lens (IR Lens) Market
The report also integrates a competitive landscape assessment that goes beyond company profiles. It evaluates how vertically integrated manufacturers, specialty material producers, and subsystem integrators are positioning themselves across defense, surveillance, automotive, medical, and industrial applications. The analysis considers product portfolio breadth, material strategy, geographic manufacturing presence, and recent commercial activity, allowing readers to benchmark their own capabilities against the firms that are actively shaping market direction.
Competitive Positioning and the 2026 Vendor Landscape
The infrared lens market is characterized by a moderately concentrated competitive structure. CR3 concentration sits at 41.2 percent, while CR5 reaches 58.5 percent, indicating that a relatively small group of established players commands a substantial share of revenue, but that meaningful opportunity remains for specialized and regionally focused manufacturers. The companies that dominate this landscape do so through different strategic levers: vertical integration, material science differentiation, application-specific engineering, and defense-oriented compliance readiness.
LightPath Technologies continues to emphasize vertically integrated production of custom IR lenses and assemblies, with a particular focus on germanium alternatives and mid- to long-wave infrared solutions for defense, surveillance, and thermal imaging. Its strategy reflects a broader industry tilt toward reducing exposure to constrained raw material channels while maintaining performance standards required by high-stakes applications. Umicore has built its presence on high-performance LWIR lenses using proprietary germanium and GASIR chalcogenide glasses, supplying both raw materials and finished assemblies across automotive, medical, and security markets. The company’s integration across material production and assembly illustrates how controlling the upstream supply chain can compress costs and improve delivery reliability.
Tamron has positioned itself around precision optics for uncooled IR lenses, targeting automotive, surveillance, and security applications where volume production and consistency matter as much as optical performance. Ophir Optronics Solutions remains focused on precision IR optics, including continuous zoom lenses spanning MWIR, SWIR, and LWIR bands for defense, security, and industrial use. Its recent product catalog release in 2026 underscores an ongoing push to expand specification flexibility for systems integrators who need adaptive optical configurations. Beijing Lenstech and Kunming Full-wave Infrared Technology represent the growing capability base in China, developing precision IR lenses and uncooled components for thermal imaging and industrial applications, with a notable orientation toward military and civilian thermal systems.
On the defense and high-performance subsystem side, Raytheon and Teledyne FLIR illustrate how EO/IR integration is becoming a strategic differentiator. Raytheon supplies lens assemblies and sub-systems for missile seekers, infrared search and track, and space applications, where performance tolerances and reliability requirements are exceptionally demanding. Teledyne FLIR operates as an OEM provider of custom MWIR/LWIR assemblies and continuous zoom lenses for thermal imaging across defense, automotive, and uncrewed systems, and its 2026 announcement of a new LWIR camera module designed for high-volume production highlights the market’s shift toward scalable, supply-continuous architectures. Edmund Optics and Resolve Optics round out the landscape by serving both stock and custom demand across germanium, zinc selenide, sapphire, silicon, and other substrates, supporting thermal imaging, spectroscopy, CO2 laser, and broader industrial applications.
These profiles are not presented in isolation. The research situates each company within broader supply chain dynamics, material substitution pathways, and application-specific procurement behavior, allowing readers to assess which vendors are best positioned to support particular program requirements, sourcing strategies, or partnership models.
Infrared Detector Market
Recent Developments That Are Reshaping Sourcing and Design Decisions
The market’s direction is being influenced not only by long-term forecasts but by recent product and technology milestones. In early 2026, Flinders University published work on a repairable polymer-based infrared lens using sulfur and organic co-monomers as a sustainable germanium alternative for thermal imaging. While still reflective of academic and applied research momentum, this development signals a continuing interest in material substitution that could, over time, alter cost structures and supply dependencies for specific thermal imaging applications.
At the same time, commercial product activity is accelerating. Ophir Optronics Solutions released its 2026 IR optics catalog, introducing new SWIR and MWIR zoom lenses that expand specification options for systems requiring adaptive field-of-view and resolution profiles. Teledyne FLIR OEM followed with an announcement of a new LWIR camera module optimized for high-volume production and supply continuity, a move that speaks directly to the manufacturing and procurement priorities of organizations seeking predictable availability and scalable integration.
These developments matter because they illustrate the market’s dual trajectory: one thread focused on material innovation and sustainability, another on production scalability and supply assurance. For enterprise planners, the implication is that sourcing strategies cannot be static. Material alternatives, catalog-level specification expansion, and module-level production design are all becoming relevant variables in procurement, product architecture, and risk management decisions.
Strategic Takeaways for the 2026 Decision Cycle
The infrared lens market is expanding, but expansion alone does not guarantee strategic advantage. The firms that will navigate 2026 successfully are those that treat market growth as a backdrop against which sourcing resilience, material strategy, and compliance readiness must be actively managed. Several implications emerge clearly from the current landscape.
- Supply chain diversification is no longer optional. Germanium constraints and export control risks are reshaping lead times, pricing, and program feasibility. Organizations need visibility into alternative material pathways, domestic production capacity, and supplier-level compliance posture.
- Material substitution is moving from research interest to commercial consideration. Chalcogenide glass production and polymer-based lens research are expanding the set of options available for specific thermal imaging and industrial applications. Decision-makers should evaluate where substitution is technically viable, economically justified, and supply-secure.
- Compliance and sourcing origin are becoming competitive requirements. NDAA-aligned domestic sourcing expectations are influencing procurement eligibility for U.S. defense programs. Vendor selection must now account for regulatory alignment as well as optical performance and cost.
- Vertical integration and scalable module design are emerging as differentiators. Companies that control raw material and assembly processes, or that engineer for high-volume production continuity, are better positioned to manage cost and availability pressure across demanding application cycles.
- Competitive concentration creates both risk and opportunity. With CR3 at 41.2 percent and CR5 at 58.5 percent, a small group of players exercises substantial market influence, yet segmentation across materials, applications, and regions leaves room for specialized positioning and targeted partnerships.
These takeaways are not abstract. They directly inform capital planning, supplier qualification, R&D prioritization, and regional sourcing strategy. The full market research study translates each of these themes into structured analysis, enabling organizations to benchmark their exposure, identify vulnerabilities, and prioritize the moves that will matter most over the 2026-to-2032 horizon.
Access the Full Intelligence: Why the Complete Report Matters
The outline above provides the strategic frame, but the detailed segmentation values, competitor positioning matrices, application-level demand drivers, regional revenue distribution, and supply-chain risk mappings are essential for precise decision-making. Those elements are intentionally withheld from this preview so that readers can assess the depth of the full study before committing to the complete dataset and analysis.
The complete infrared lens market research offers a consolidated view of historical performance, forecast trajectory, segmentation dynamics, competitive profiles, recent product and technology developments, and the operational implications of material and regulatory shifts. It is designed for teams that need to align procurement, engineering, and strategy around a single, coherent market picture rather than fragmented data points.
For organizations planning 2026 sourcing strategies, evaluating vendor partnerships, or shaping product roadmaps for thermal imaging, night vision, and adjacent infrared applications, the full report provides the granularity required to move from directional awareness to executable strategy. The market is growing, the competitive structure is evolving, and the firms that act on detailed intelligence will be best positioned to capture value while managing the supply, compliance, and material risks that define this phase of the infrared lens market.
For detailed analysis of this topic, please visit the official page: Infrared Lens (IR Lens) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com