

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Subsea Umbilical Market Hits USD 1,450M in 2025, Expanding at 4.82% CAGR to 2032
By pmarketresearch, 2026-09-16
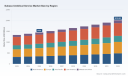
Strategic Intelligence for the Deep: Navigating the 2026 Subsea Umbilical Service Market
The offshore energy sector stands at a critical inflection point. As operators balance the imperative for reliable production with the realities of volatile material costs and evolving regulatory frameworks, the subsea umbilical segment has emerged as a linchpin of project economics. In 2026, decisions made today regarding umbilical procurement, service partnerships, and capital allocation will echo across asset lifecycles for decades. PW Consulting is pleased to introduce our latest comprehensive research study, the Subsea Umbilical Service Market report, a definitive intelligence product designed to equip executives, procurement leaders, and investors with the clarity needed to navigate this complex landscape.
This article previews the strategic architecture of our analysis. It demonstrates the depth of our methodology and highlights the actionable intelligence contained within the full report, while preserving the proprietary granular data that our clients rely on for competitive advantage. The complete market intelligence, including precise segmentation breakdowns and forward-looking forecasts, is available exclusively through our detailed publication.
The Macro Arc: From Baseline to 2032 Projection
Any robust strategic framework begins with a rigorous understanding of the total addressable market and its trajectory. Our research establishes a clear baseline rooted in historical performance while projecting a sustained growth path through the end of the decade. The subsea umbilical services sector has demonstrated resilience and steady expansion over the historical window, reflecting the ongoing necessity of subsea infrastructure for offshore production. This momentum carries firmly into the forecast period, driven by a combination of deepwater field development and the increasing complexity of tie-back projects that rely on robust umbilical systems for control and monitoring.
Our analysis centers on a market that has been maturing steadily, with the total market size reflecting the cumulative value of installation, inspection, monitoring, maintenance, and repair activities across the global offshore footprint. As we move past the base year and into the forecast horizon, the sector is projected to experience a compound annual growth rate of 4.82%, a figure that signals moderate but reliable expansion. This trajectory underscores a market that is not defined by speculative bubbles but by disciplined, engineering-driven demand tied to long-cycle capital projects. The forecast model extends through the early 2030s, mapping a clear path of incremental value creation that aligns with global offshore energy development plans.
For strategic decision-makers, this macro view is only the starting point. The true value of our research lies in deconstructing this aggregate growth into the drivers, constraints, and competitive pressures that will shape outcomes at the segment and project level. The full report unpacks these dynamics with precision, enabling stakeholders to calibrate their strategies to the specific forces acting on their portfolios.
Market Composition: Segmentation, Concentration, and Structural Dynamics
The subsea umbilical service ecosystem is multifaceted, spanning distinct service categories, water-depth regimes, and geographic demand centers. Understanding how value is distributed across these dimensions is essential for identifying growth pockets, assessing competition, and evaluating supply-chain exposure. Our segmentation analysis provides a comprehensive map of the market structure, offering insights into where revenue concentration resides and which service lines are driving activity.
Service segmentation reveals a market anchored by maintenance and repair activities, reflecting the operational reality that installed subsea infrastructure requires continuous lifecycle support. Installation represents a substantial share of market activity, tied to the front-end capital deployment of new fields and major expansions. Inspection and monitoring services form another critical pillar, driven by the industry’s emphasis on asset integrity and remote performance assessment. Each service line carries distinct competitive dynamics, pricing sensitivities, and technical barriers, all of which are examined in detail within the report.
Water-depth segmentation further illuminates the market’s technical gradient. Shallow-water operations maintain a steady presence, but the greatest strategic attention is increasingly directed toward deep-water and ultra-deep-water environments. These deeper regimes demand specialized engineering, advanced materials, and rigorous qualification processes, raising the stakes for both operators and service providers. The interplay between water-depth categories and service requirements creates a complex value chain where performance reliability and cost efficiency must be carefully balanced.
Geographic distribution adds another layer of nuance. Demand is spread across multiple regions, with each area presenting a distinct blend of mature basins, emerging opportunities, and regional project pipelines. The full research publication provides a granular regional map that highlights where activity is concentrated and how regional dynamics influence service demand, logistics, and competitive positioning. This geographic intelligence is critical for firms evaluating market entry, capacity allocation, and partnership strategies.
Market concentration remains a defining characteristic of the competitive landscape. The sector exhibits a moderate-to-high degree of consolidation, with a limited number of players commanding a significant share of total market value. This concentration shapes pricing power, bid dynamics, and the pace of innovation, making competitive intelligence a vital component of any go-to-market or investment strategy. Our report analyzes these concentration patterns and their implications with a level of detail designed to inform both commercial positioning and risk assessment.
Competitive Landscape: The Strategic Posture of Leading Players
The subsea umbilical services market is contested by a group of capable, globally positioned companies, each bringing distinct capabilities in design, manufacturing, installation, and lifecycle support. Our research profiles the key participants shaping this landscape, offering an assessment of their strategic focus, operational strengths, and recent moves that signal their market intent.
JDR Cable Systems operates as a leading provider of subsea control umbilicals and associated services, with a strong manufacturing and testing footprint supporting offshore oil and gas projects. The company’s recent contract awards highlight its active pursuit of international opportunities, including hydraulic control umbilical supply for offshore developments in Australia and testing services for platforms in the Middle East. These moves reflect a strategy centered on leveraging manufacturing capability and technical service expertise across multiple regions.
TechnipFMC stands as a prominent force in subsea umbilical solutions, combining design, engineering, manufacturing, and full lifecycle services across facilities in the United Kingdom, the United States, and Angola. Its integrated capabilities position it to address complex project requirements from concept through operation, reinforcing its relevance for operators seeking end-to-end solutions.
Oceaneering International contributes a broad service portfolio encompassing manufacturing, installation, repair, maintenance, and refurbishment for both thermoplastic and steel tube umbilicals. Its recent contract activity, including a significant electro-hydraulic steel tube dynamic umbilical supply for a Gulf of Mexico project, underscores the ongoing demand for robust, high-performance umbilical systems in challenging environments.
Aker Solutions specializes in complete subsea solutions, integrating umbilical design, manufacturing, and integrated services within a broader subsea offering. This holistic approach aligns with operator preferences for coordinated delivery and system-level optimization.
Prysmian Group emphasizes SURF solutions that incorporate subsea umbilicals, focusing on high-performance cables engineered for deepwater and demanding operating conditions. Its material and cable expertise adds a distinct dimension to the competitive field.
OneSubsea, operating under SLB, provides robust subsea umbilical systems that link surface and seafloor equipment, delivering control and power capabilities with full service support. Its connection to a larger technology and services ecosystem enhances its value proposition for integrated subsea developments.
Subsea 7 brings engineering, procurement, and offshore installation expertise to umbilical projects as part of broader SURF efforts. Its ability to manage large-scale offshore operations makes it a key participant in capital-intensive installations.
Nexans contributes subsea umbilical manufacturing and related cabling solutions and services for offshore energy, reinforcing its role in the wider subsea infrastructure supply chain.
Umbilicals International focuses on the design and manufacture of high-performance cable, hose, and umbilical systems tailored for harsh subsea environments, offering specialized product capabilities that address demanding application requirements.
Worldwide Umbilical Cable Market
Together, these companies define a competitive arena in which technical differentiation, manufacturing capacity, installation expertise, and service reliability all play decisive roles. Our report assesses the strategic positioning of each major player, examining how recent contract awards and service expansions are reshaping the competitive balance. The complete analysis provides a detailed map of market shares, capability benchmarks, and strategic implications that can inform partnership selection, bid strategy, and competitive planning.
Operational Intelligence: What the Full Report Delivers
The Subsea Umbilical Service Market report is built to serve as a practical decision-support tool rather than a static market overview. It integrates demand-side drivers, supply-side constraints, competitive activity, and forward-looking projections into a coherent framework that can be applied directly to commercial planning and investment evaluation.
The report includes a thorough examination of service segmentation, water-depth segmentation, and regional demand patterns, allowing users to identify the segments most relevant to their strategic objectives. It also provides a structured assessment of market concentration and competitive dynamics, helping stakeholders understand where incumbency advantages exist and where new entrants or expansion strategies may find traction.
Beyond segmentation and competition, the research incorporates an operational lens on the factors influencing project execution and cost structures. Material inputs, qualification requirements, and compliance obligations are evaluated as part of the broader market dynamics, giving readers a clearer picture of the forces that shape pricing, lead times, and service delivery. This operational context is particularly valuable for organizations seeking to anticipate supply-chain pressures or optimize procurement strategies in a market where material performance and regulatory adherence are closely linked.
The forecast component of the report extends the analysis beyond the current year, offering a projected path of market development that aligns with the longer cycle of offshore projects. By linking historical trends to forward estimates, the research supports scenarios for capacity planning, revenue modeling, and portfolio prioritization. The full report presents these projections within a detailed analytical structure that can be tailored to internal planning processes.
Industry Dynamics and the 2026 Decision Environment
The strategic value of this research is amplified by the broader industry context in which subsea umbilical services are embedded. Several intersecting dynamics are shaping the 2026 decision environment and will continue to influence project planning and commercial strategy in the period ahead.
One significant factor is the pressure on raw material inputs. The use of high-grade steel and advanced polymers in steel tube umbilicals creates supply-chain sensitivity and contributes to capital expenditure considerations for subsea projects. At the same time, specialized materials such as nickel alloys, titanium, and polymer composites are employed to achieve advantages in weight, flexibility, and performance for dynamic systems, reinforcing the technical premium associated with higher-specification umbilicals. These material realities affect both cost structures and product differentiation, making material strategy a relevant element of competitive positioning.
Regulatory and standards-driven requirements also play a central role. Subsea umbilical projects are subject to stringent offshore safety and environmental expectations, which in turn drive qualification, testing, and certification processes. Compliance is not merely a procedural requirement; it is a determinant of project schedules, vendor eligibility, and risk exposure. Our report addresses how these requirements shape market behavior and create barriers that reward established technical credentials and rigorous quality systems.
Demand-side dynamics remain anchored in the expansion of deepwater oil and gas developments and the continued reliance on tie-back projects that connect new discoveries to existing infrastructure. These project types generate sustained demand for subsea umbilical services, including installation and maintenance, reinforcing the importance of lifecycle service capability. The interplay between field development plans, infrastructure constraints, and service capacity creates a market environment in which project timing, regional activity, and service specialization all influence competitive outcomes.
Taken together, these dynamics define a market that rewards informed, scenario-aware decision-making. Organizations that understand the link between material costs, regulatory burdens, deepwater project pipelines, and service competition are better positioned to manage risk, capture value, and align their strategies with the pace of market development. The full research publication provides the integrated perspective needed to navigate these intersecting forces with confidence.
A Strategic Imperative for 2026 and Beyond
The Subsea Umbilical Service Market is not a sector defined by sudden disruption; it is a market shaped by engineering rigor, long project cycles, and the steady accumulation of operational experience. Yet within that steady framework, there are meaningful differences in competitive positioning, regional opportunity, service specialization, and cost exposure. Identifying and acting on those differences is the core challenge for executives operating in this space.
Subsea Umbilical Service Market
Our research is designed to meet that challenge. It combines market sizing and forecasting with a detailed examination of segmentation, concentration, competitive activity, and industry dynamics, offering a multi-layered view of the market that supports both strategic planning and tactical execution. By linking historical performance to a disciplined forecast through the early 2030s, the report provides a forward-looking foundation for decisions about capacity, partnerships, procurement, and market focus.
The preview presented here illustrates the scope and analytical depth of the study. However, the full strategic value of the research lies in the complete dataset, the detailed segmentation analysis, the competitive benchmarks, and the forward projections that are only available in the full report. For organizations seeking to make informed decisions in 2026, access to this level of intelligence is not merely beneficial; it is a strategic necessity. We invite you to explore the complete publication to gain the comprehensive market intelligence required to act with precision in an increasingly complex subsea environment.
For detailed analysis of this topic, please visit the official page: Subsea Umbilical Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerospace Glass Cockpit Market Hits $4.85B in 2025, Projected $6.92B by 2032 at 5.19% CAGR
By pmarketresearch, 2026-09-16
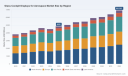
Global Aerospace Glass Cockpit Displays: Strategic Market Intelligence for 2026 Decision-Makers
The aviation industry is currently undergoing a profound technological transformation, driven by the relentless adoption of glass cockpit architecture across all flight regimes. As legacy analog instrumentation gives way to advanced digital interfaces, the market for aerospace glass cockpit displays has established itself as a critical nexus of avionics innovation, supply chain complexity, and strategic investment. For executives, procurement leaders, and technology strategists operating within the aerospace sector, understanding the trajectory of this market is no longer optional—it is a prerequisite for informed decision-making. This article serves as a strategic preview of our latest comprehensive research, Worldwide Glass Cockpit Displays for Aerospace Market , designed to equip stakeholders with the macroscopic intelligence required to navigate the opportunities and risks defining the 2026 to 2032 forecast period.
The transition toward integrated digital flight decks is accelerating, fueled by demands for enhanced situational awareness, reduced pilot workload, and improved safety margins. However, this transition is not occurring in a vacuum. Current industry data highlights significant headwinds and structural shifts that are reshaping bandwidth for growth. For instance, recent supply chain analysis indicates that global semiconductor shortages have historically impacted display panel availability, delaying aircraft deliveries and retrofit programs by an average of six to nine months as of 2025 data. Furthermore, tariff policies imposed in 2025 have introduced new friction into global supply chains for avionics components. These geopolitical and logistical pressures are prompting accelerated localization of critical subassembly production closer to major aircraft assembly hubs to mitigate lead-time volatility. Simultaneously, cost structures remain under intense scrutiny; display modules account for a significant portion of total cockpit display cost, with driver chips, PCBs, and structural components making up a combined majority of expenses, while raw materials exceed sixty percent of total costs. These dynamics underscore the necessity of a report that goes beyond surface-level growth projections to examine the underlying mechanics of the market.
Market Trajectory and Growth Outlook
Our analysis frames the market using a robust historical baseline spanning from 2020 through 2025, projecting forward into the forecast period ending in 2032. The data reveals a resilient upward trajectory despite the aforementioned supply chain disruptions. The market generated revenue of approximately 4,850 USD Million in 2025, reflecting recovery and growth following fluctuations observed in the mid-2020s. Moving into the forecast horizon, the market is expected to expand, with revenue projections reaching nearly 6,916 USD Million by 2032.
This growth is underpinned by a compound annual growth rate that signals steady expansion for industry participants. The forecast period suggests a CAGR of 5.19 percent, indicating a market that is maturing but still possesses significant capacity for value creation. This trajectory is critical for capacity planning and investment allocation. For stakeholders evaluating long-term portfolio positioning, the inflection points between 2026 and 2028 show incremental gains, while the period toward 2032 suggests an acceleration in value capture as next-generation platforms enter service and retrofit cycles deepen. The historical data from 2020 to 2025 also provides a stress-tested view of market resilience, showing how the industry navigated the post-pandemic recovery and supply chain constraints to reach the 2025 baseline.
Unit economics also play a pivotal role in understanding the market scale. Global cockpit display unit sales reached 309,000 units in 2025, with an average price of USD 20,493 per unit. These metrics offer a high-level view of volume and pricing power, helping organizations benchmark their own product strategies against market averages without revealing sensitive granular breakdowns. Understanding the interplay between unit volume and average selling price is essential for modeling revenue streams and assessing the potential impact of cost pressures on margins.
Segmentation and Application Dynamics
The market is composed of diverse aircraft platforms and display technologies, each presenting unique value propositions and adoption curves. Our research dissects the market landscape across multiple dimensions, including aircraft type and display technology, to provide a holistic view of where value is being generated. In terms of aircraft platforms, the ecosystem encompasses commercial aviation, military operations, general aviation, and helicopter operations. Each segment faces distinct operational requirements and procurement cycles.
The commercial aviation sector remains a cornerstone of demand, driven by fleet modernization programs and new aircraft deliveries. Military aircraft continue to represent a substantial portion of the market, fueled by defense modernization initiatives and the need for advanced situational awareness in complex threat environments. General aviation and helicopters also contribute significantly, with increasing adoption of avionics upgrades in existing fleets to extend operational life and enhance safety capabilities. While specific regional revenue splits are detailed in the full report, it is noteworthy that the global market distribution reflects the concentration of aircraft manufacturing and operational hubs across North America, Europe, Asia Pacific, and emerging regions in the Middle East, Africa, and Latin America.
From a technology perspective, the market is segmented into primary flight displays, multi-function displays, and engine instrument and crew alerting systems. Primary flight displays remain central to flight safety, providing critical attitude, airspeed, and altitude information. Multi-function displays offer flexibility and information density, supporting navigation, systems management, and communication tasks. Engine instrument and crew alerting systems are vital for monitoring aircraft health and ensuring timely crew response to anomalies. The integration of these display types into cohesive glass cockpit architectures is a key trend, with manufacturers increasingly offering integrated suites that reduce weight, wiring complexity, and maintenance overhead. The report provides a detailed mapping of these technology segments to aircraft platforms, enabling stakeholders to identify cross-selling opportunities and technology migration paths.
Competitive Landscape and Strategic Positioning
The competitive environment for glass cockpit displays is characterized by a mix of established aerospace giants, specialized avionics manufacturers, and emerging innovators. Market concentration analysis indicates that the top three companies hold a combined market share of 58.4 percent, while the top five players account for 72.15 percent of the market. This concentration suggests a landscape where scale, certification capabilities, and long-term customer relationships are significant barriers to entry, yet also highlights the importance of niche players who can offer specialized solutions or cost-effective alternatives.
Collins Aerospace (RTX) continues to be a dominant force, providing integrated cockpit solutions that include large-format LCD displays and Flight2 integrated avionics. Their portfolio spans advanced displays for both military and commercial aircraft, with notable retrofit capabilities for platforms like the Boeing 757 and 767, as well as Pro Line 21 systems that deliver crystal-clear LCDs for enhanced situational awareness. Honeywell Aerospace remains a critical supplier of cockpit and flight displays, offering a range of LCD units such as the CMA-6800, DU-1080, DU-1310, and DU-875. Their focus on Primus Elite upgrades and multi-function displays for business aviation, commercial helicopters, and Primus Epic platforms underscores their commitment to improving visibility and operational flexibility across diverse aircraft types.
Thales Group offers sophisticated cockpit interactive display units, including the FlytX tactile large display flight deck systems. These systems feature customizable tactile interfaces and are supplied to major airframe manufacturers including Airbus, ATR, Bombardier, Dassault, and Airbus Helicopters, positioning Thales at the forefront of next-generation flight deck ergonomics. Garmin Ltd. delivers comprehensive glass flight deck solutions, including the G1000 NXi, G5000, G3000H, and TXi touchscreen displays. Their G3X Touch systems support Part 23 turbine, defense, advanced air mobility, helicopters, and general aviation retrofit and forward-fit applications, demonstrating their broad reach across civilian and specialized aviation sectors.
Aspen Avionics specializes in Evolution Flight Display systems, such as the EFD1000 Pro MAX, targeting fixed-wing aircraft, helicopters, and Class III aircraft. Their focus on affordable, certified glass cockpit solutions makes them a key player in the general aviation segment. ScioTeq manufactures rugged DAL-A certified video displays and display computers, including the RDU-3068 and RDU-4208 series, which are utilized in civil and defense applications ranging from trainers to air-to-air refueling and next-gen avionics. Astronautics Corporation of America provides diversified smart displays with embedded processing, supporting civil and military transports, trainers, fighters, helicopters, and special mission aircraft. Elbit Systems Ltd. supplies advanced cockpit display systems and avionics for military and commercial aerospace applications, while Mercury Systems offers custom rugged safety-certifiable active matrix LCD modules up to DAL-A for primary and multi-function displays.
Recent developments in the competitive landscape have been dynamic. In March 2026, ScioTeq and Kongsberg Defence & Aerospace signed a Letter of Intent for collaboration on resilient European air defense initiatives involving avionics displays. Similarly, ScioTeq was selected to provide a certified visualization and control solution using the RDU-3068 and PU-5200 display computer for an Air-to-Air Refueling system. In February 2026, ScioTeq's RDU-3068 advanced display was selected as the PFD and MFD for the PC-7 MKX Smart Basic Trainer aircraft, highlighting the penetration of specialized display technologies into training platforms. Additionally, Nighthawk Flight Systems unveiled Guardian, a new modular glass cockpit system for Part 23 aircraft with certification expected in July 2026 and plans for expansion to Part 27 rotorcraft. These events illustrate the active innovation cycle and the strategic partnerships shaping the market's evolution.
Strategic Imperatives for 2026 and Beyond
For enterprise leaders, the insights contained in the Worldwide Glass Cockpit Displays for Aerospace Market report translate into actionable strategic imperatives. First, supply chain resilience must be a top priority. With raw materials constituting over sixty percent of total costs and semiconductor constraints historically causing delivery delays of six to nine months, organizations must evaluate supplier diversification, inventory buffering strategies, and the feasibility of localized assembly as suggested by recent tariff-induced friction.
Second, segmentation strategy requires precision. The distinct growth profiles of commercial, military, general aviation, and helicopter segments necessitate tailored go-to-market approaches. Companies must assess which combination of display types—primary, multi-function, or alerting systems—aligns best with their target audience's operational needs and certification timelines. The report's detailed mapping of these segments allows for the identification of underserved niches and potential consolidation opportunities.
Third, competitive positioning must account for market concentration. With the top five players controlling nearly three-quarters of the market, new entrants or smaller players must define clear value propositions, whether through cost efficiency, specialized certification capabilities, or innovation in display ergonomics and tactile interfaces as seen with Thales and Nighthawk. Monitoring the recent contract awards and product launches of key competitors provides early warning signals of shifting alliances and technology preferences.
Worldwide Glass Cockpit Displays for Aerospace Market
Finally, investment in next-generation capabilities is essential. The demand for DAL-A certified rugged displays, tactile interfaces, and modular systems indicates a market trend toward higher integration and safety-critical performance. Organizations should align their R&D roadmaps with these technological vectors to capture long-term value as the market approaches the 2032 horizon.
Worldwide Aircraft Windows Market
Conclusion and Access to Full Intelligence
The aerospace glass cockpit displays market is poised for sustained growth, driven by technological advancement, fleet modernization, and evolving operational requirements. However, realizing the value of this growth requires a nuanced understanding of supply chain dynamics, segmentation nuances, and competitive moats. The information provided here offers a high-level strategic overview, highlighting the macroeconomic trajectory, key industry players, and recent developments that define the current landscape.
To move from broad awareness to precise decision-making, stakeholders require the granular data, detailed forecasts, and exhaustive segmentation analysis available in our full market research. The complete report includes specific regional revenue breakdowns, aircraft type splits, display technology shares, and comprehensive company profiles that are essential for crafting detailed business plans and investment theses. We invite you to access the full Worldwide Glass Cockpit Displays for Aerospace Market research to unlock the complete intelligence package and ensure your organization is strategically positioned for the opportunities of 2026 and the decade beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Cockpit Displays for Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Chromium Salt Market to Hit $4.25 Billion by 2032, Growing at 3.15% CAGR
By pmarketresearch, 2026-09-16
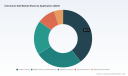
Navigating the Chromium Salt Landscape: Strategic Imperatives for 2026 and Beyond
The worldwide chromium salt market stands at a critical inflection point as it enters 2026. With a historical revenue trajectory that saw the market grow from approximately USD 2.81 billion in 2020 to an estimated USD 3.42 billion in 2025, the sector has demonstrated resilience amid fluctuating raw material costs, evolving regulatory frameworks, and shifting industrial demand patterns. Projections extending through 2032 indicate a steady expansion path, anchored by a compound annual growth rate of 3.15 percent, which would lift market value to roughly USD 4.25 billion by the end of the forecast period. For executives, procurement leaders, and strategic planners, this growth narrative is not merely a macroeconomic signal. It is a call to recalibrate supply chain architectures, anticipate regulatory headwinds, and position portfolios against the structural shifts reshaping chromium chemistry applications across multiple end-use sectors.
Worldwide Chromium Salt Market
PW Consulting latest Worldwide Chromium Salt Market study is designed to translate this complexity into executable intelligence. The report does not simply present top-line figures; it deconstructs the mechanics of growth, maps the competitive fault lines, and equips decision-makers with the granular visibility required to act decisively in a market where concentration, capacity dynamics, and compliance risk intersect.
Macro Foundations: Reading the Numbers Strategically
The historical record from 2020 through 2025 reveals a market that has navigated volatility without losing its long-term upward orientation. After reaching a near-term peak in 2024 at USD 3.47 billion, the 2025 figure of USD 3.42 billion reflects a modest consolidation that analysts attribute to a combination of inventory normalization, price moderation in certain chemical intermediates, and cautious downstream purchasing across key industrial verticals. Looking forward, the forecast window from 2026 to 2032 outlines a market that regains momentum, with annual revenues climbing from an estimated USD 3.54 billion in 2026 to USD 4.25 billion in 2032. This trajectory is not linear; it is shaped by periodic capacity additions, raw material availability cycles, and the pace at which downstream industries adopt alternative chemistries or reformulate existing processes.
For 2026 planning, the strategic implication is clear. Growth will be earned through structural advantages rather than broad market tailwinds alone. Firms that understand where demand is structurally sticky, where substitution risk is real, and how regional supply dynamics affect landed costs will be best positioned to capture value. The study unpacks these dynamics without oversimplifying them, offering a calibrated view of how volume, price, and mix interact across the forecast horizon.
The Anatomy of Demand: Sector-Level Forces at Play
Chromium salts permeate a diverse set of industrial applications, each with distinct growth drivers, cost sensitivities, and regulatory exposure. Leather tanning remains a foundational demand pocket, supported by continued processing needs in established markets and selective growth in emerging manufacturing hubs. Metal finishing and electroplating constitute another significant pillar, where chromium-based compounds are valued for corrosion resistance, aesthetic finish, and functional performance in automotive, aerospace, and industrial equipment supply chains. Pigments and dyes represent a more specialized but stable demand stream, while wood preservation and refractories-and-others categories reflect niche but durable consumption patterns tied to infrastructure, construction, and industrial maintenance cycles.
What matters for strategy is not the relative size of each application in isolation, but the interplay between them. Some segments are increasingly scrutinized under environmental and occupational health regulations, prompting reformulation efforts and process changes that can reshape procurement specifications over time. Other segments are benefiting from capacity expansions and downstream investment that sustain volume growth even as price competition intensifies. The report provides a detailed application-level mapping that links demand behavior to operational planning, helping clients anticipate where specification changes, supplier diversification, or alternate chemistry adoption may alter sourcing strategies in the coming years.
Geography, Supply Concentration, and the Raw Material Backdrop
The geographic distribution of chromium salt demand and supply is inseparable from the broader chromium value chain. Chromite ore availability, processing capacity, and logistics infrastructure all influence the cost base and reliability of supply for downstream salt producers. In 2025, global chromite ore mine production was estimated to have risen by roughly 3 percent year-over-year, with South Africa continuing to dominate output. This concentration matters because it creates both pricing leverage and vulnerability: any disruption in key producing regions can ripple through the value chain, affecting intermediate chemistry costs and, ultimately, the economics of chromium salt manufacturing.
Sodium Dichromate Market
Early 2026 market observations point to upward pressure on chrome ore prices, with South African concentrate quotations holding in a range that reflects tight availability and steady demand from ferrochrome and chemical processing sectors. These raw material conditions set the tone for the operating environment in which chromium salt producers must manage margins, negotiate contracts, and decide on inventory positioning. The study integrates these upstream signals into its market analysis, ensuring that forecasts and strategic recommendations are grounded in the cost realities that shape producer behavior and buyer negotiations.
At the same time, regional demand patterns are evolving. Asia Pacific remains a central axis of activity, supported by manufacturing scale, chemical processing depth, and expanding industrial consumption. Europe and North America continue to represent mature but high-value demand environments, where regulatory compliance, quality expectations, and specialty grade requirements often command different pricing and service dynamics than bulk-oriented markets. Latin America and the Middle East and Africa contribute more targeted demand pockets, often linked to specific industrial clusters, infrastructure projects, or regional processing capabilities. The report examines these regional nuances in a way that supports market entry decisions, export-import strategy, and supplier selection without reducing complex local conditions to oversimplified rankings.
Regulatory Momentum: The Chromium VI Question
No discussion of chromium salt strategy in 2026 is complete without addressing the regulatory trajectory surrounding hexavalent chromium. European Union institutions have been advancing discussions that could lead to a horizontal restriction on certain Cr(VI) compounds, with updated Q&A documents from the European Commission in December 2025 signaling accelerated movement toward potential legal entry between end-2027 and beginning-2028. Earlier in 2025, ECHA concluded that an EU-wide restriction on select hexavalent chromium substances is justified based on occupational health risks, reinforcing the regulatory direction.
These developments do not merely affect compliance documentation. They influence product design, customer specifications, substitution timelines, and the relative attractiveness of different chromium salt grades and derivatives. For companies operating in or supplying into European markets, the timeline creates both risk and opportunity: risk for products and processes that face tighter use conditions, and opportunity for those that can offer compliant alternatives, demonstrate robust stewardship, or support customers through transition pathways. The study evaluates the regulatory landscape with enough depth to help clients model scenario impacts, prioritize portfolio adjustments, and align commercial messaging with the compliance expectations of downstream buyers.
Competitive Chessboard: Who Shapes the Market and How
The worldwide chromium salt market is characterized by a mix of large-scale producers, regional specialists, and high-purity or specialty-focused suppliers. Consolidated presence is notable, with the top three competitors collectively accounting for an estimated 48.5 percent of market revenue and the top five reaching approximately 62.35 percent. This concentration means that a relatively small number of players exert meaningful influence over pricing norms, capacity availability, and product standards in key segments.
Among the globally active names, Lanxess AG remains a major producer of chromium salts and chrome chemicals, with a portfolio that includes basic chrome sulfate for leather tanning and other industrial uses. In India, Vishnu Chemicals Limited has built a leading position in chromium chemicals, with significant sodium dichromate capacity and a clear expansion trajectory; the company has outlined plans to increase sodium dichromate capacity from 80ktpa toward 100ktpa by the first half of fiscal 2026, reflecting confidence in downstream demand and derivative growth. In China, Hubei Zhenhua Chemical stands out as a major chromium salt producer and one of the world largest manufacturers of chromium chemicals, with ongoing capacity expansions and acquisition activity that extend its footprint across the value chain. In late 2025, the company advanced price adjustments on metal chromium and moved forward with restructuring and acquisition efforts that add meaningful chromium salt capacity, signaling a push to strengthen scale and integration.
Turkey contribution is represented by Soda Sanayii A.S., which has brought new production lines for chromium chemicals into the market, while Japan supply-side presence includes Nippon Chemical Industrial Co., Ltd., a manufacturer of chromium compounds and related specialty chemicals. In the United Kingdom context, Elementis plc formerly held a leading position in sodium dichromate, chromic acid, and chrome sulfate across the Americas before divesting its chromium business in 2023, an episode that illustrates how portfolio strategy and asset reallocation continue to reshape the competitive map. Other notable participants include American Elements, which supplies high-purity chromium salts for research, electronics, and industrial applications; Merck KGaA, a global source of laboratory and high-purity chromium reagents; Sichuan Yinhe Chemical, with a recognized presence in bulk chromium chemicals; and regional producers such as MidUral Group in Russia, Aktyubinsk Chromium Chemicals Plant in Kazakhstan, Oxkem Ltd in the United Kingdom, and Chemetall GmbH, associated with BASF, which supplies chromium-based surface treatment chemicals and salts.
Capacity dynamics remain a critical competitive variable. In the United States, plans have emerged for a new chromium metal plant in New Castle, Pennsylvania, targeting a startup in the first quarter of 2026 with capacity up to 6,500 MT per year, potentially positioning it as the first U.S. producer of its kind. While this development sits upstream of chromium salt production, it signals how regional supply chain autonomy, cost management, and strategic resilience are driving investment decisions that can indirectly influence the broader chromium ecosystem. The report analyzes these competitive moves in a structured way, linking capacity announcements, pricing behavior, M&A activity, and product portfolio shifts to their likely effects on market equilibrium and buyer options.
What the Study Delivers: Operational Intelligence, Not Just Headlines
PW Consulting Worldwide Chromium Salt Market study is built to serve as a working document for strategy, sales, procurement, and investment teams. It goes beyond aggregate market sizing to provide a structured, decision-ready view of the market architecture. The report includes detailed segmentation analysis across type, application, and region, enabling clients to isolate the pockets of growth, the segments facing substitution or regulatory pressure, and the geographies where supply-demand balances are tightening or loosening.
The study also examines market concentration and competitive positioning with enough granularity to support benchmarking, partnership evaluation, and competitive response planning. Company profiles, recent developments, and capacity-related developments are contextualized within the larger market logic, helping readers distinguish between one-off events and structural trends. Raw material dynamics are integrated into the analysis so that forecasts and strategic commentary reflect the cost environment that producers and buyers actually face. Regulatory developments are assessed not as abstract policy news but as variables that can alter specification requirements, product viability, and regional demand patterns over the forecast period.
Importantly, the report is designed to support scenario thinking. Because the chromium salt market is influenced by commodity cycles, regulatory timing, and capacity lead times, a single-point forecast is insufficient for robust planning. The study provides the analytical framework needed to test assumptions about price direction, volume growth, regional availability, and compliance-driven demand shift, giving teams a more reliable basis for budgeting, sourcing, and investment prioritization.
Why This Study Matters for 2026 Decisions
As organizations move into 2026, the cost of ambiguity in the chromium salt market is rising. Raw material conditions are dynamic, regulatory timelines are narrowing, and competitive capacity actions are altering the supply landscape. In this environment, decisions about supplier relationships, inventory strategy, product mix, and geographic focus need to be informed by evidence that connects market structure to operational consequences.
The PW Consulting study is intended to reduce that ambiguity. It helps clients answer practical questions: Where is demand most resilient, and where is it most exposed to substitution or regulation? Which competitors are expanding, consolidating, or exiting, and what does that mean for supply security and pricing? How should procurement teams think about contract timing in a market where raw material availability and regional concentration create both risk and negotiation leverage? Which application segments offer the strongest growth logic, and which require a more cautious, transition-aware approach?
By combining macro trajectory, segmentation insight, competitive intelligence, and regulatory context in a single integrated analysis, the report aims to give decision-makers a clearer line of sight from market data to strategic action. That clarity is especially valuable when preparing for periods of change, whether those changes come from new capacity entering the market, shifting compliance requirements, or evolving downstream demand patterns.
Looking Ahead: Positioning for the Rest of the Decade
The forecast period through 2032 suggests a market that grows at a measured but persistent pace, reaching an estimated USD 4.25 billion by the end of the window. Yet the path to that outcome will be shaped by decisions made now. Capacity expansions, raw material availability, regulatory finalization, and downstream reformulation efforts will all influence which companies capture share, which applications remain core, and which regions become more or less central to the market architecture.
For executives and analysts who need to move beyond general market narratives and into specific, evidence-based planning, the Worldwide Chromium Salt Market study offers a comprehensive foundation. It is designed to support the next round of strategic choices with the depth, structure, and commercial relevance required to act confidently in a market where the details determine the outcome.
To access the full segmentation detail, competitive benchmarking, regional analyses, and scenario-based forecasts that underpin this outlook, we invite you to explore the complete study on the PW Consulting website. The report provides the full intelligence architecture behind the trends summarized here, enabling teams to translate market visibility into operational advantage throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Chromium Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Worldwide Anorectal Manometry Devices Market to Reach $339.21 Million by 2030
By pmarketresearch, 2026-09-16
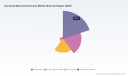
Strategic Outlook: The Worldwide Anorectal Manometry Devices Market (2026–2032)
Setting the Stage for Precision GI Diagnostics
As gastrointestinal motility disorders continue to present diagnostic challenges across global healthcare systems, anorectal manometry has emerged as a critical tool for evaluating pelvic floor function, defecatory disorders, and fecal incontinence. The clinical imperative for standardized, high-fidelity pressure mapping is now intersecting with a rapidly evolving regulatory landscape, updated reimbursement frameworks, and the commercialization of portable and disposable diagnostic platforms. This confluence of clinical, regulatory, and technological forces is reshaping procurement strategies, product positioning, and capital allocation for manufacturers and end-user institutions alike.
Our latest Worldwide Anorectal Manometry Devices Market study is designed for executives who need to navigate this complexity with quantitative rigor and scenario-ready strategic frameworks. Rather than offering static snapshots, the analysis is structured to inform 2026 operational decisions, pipeline prioritization, pricing strategies, and market-entry timing. The market's growth trajectory reflects a maturation from conventional diagnostic setups toward high-resolution, software-integrated, and increasingly decentralized testing environments. Understanding where value is created—and where margin pressure, regulatory friction, or reimbursement shifts may emerge—requires a market intelligence foundation that goes beyond aggregated sizing.
Market Trajectory and Growth Architecture
The global anorectal manometry devices market has demonstrated consistent expansion across the historical review period, driven by rising disease awareness, broader adoption of standardized manometry protocols, and incremental replacement cycles in hospital-based gastroenterology departments. Current baseline sizing reflects a market that has already crossed a meaningful adoption threshold, with forward estimates indicating continued value expansion through the end of the forecast horizon. The overall market is projected to advance from mid-2020s levels toward an estimated trajectory that underscores both volume-driven growth and the premiumization effect associated with higher-resolution, software-enabled systems.
At the core of this outlook is a forecast-period CAGR of approximately 5.95%, signaling a market that is not merely expanding in absolute terms but also experiencing structural shifts in product mix and purchasing behavior. Revenue growth is being shaped by several concurrent dynamics: the transition from legacy systems to high-resolution platforms, increasing procedure volumes in specialized pelvic floor centers, and the gradual penetration of portable, office-based diagnostic devices into ambulatory care settings. These forces create a growth profile that is less dependent on single-market volume spikes and more tied to workflow modernization across a diversified end-user base.
Importantly, the 2026–2032 forecast window captures a phase in which reimbursement realignment, regulatory clarity, and protocol standardization are likely to influence purchasing cadence more directly than in prior years. The market's growth path is therefore best interpreted not as a single linear curve, but as a composite of differing adoption speeds across product categories, clinical settings, and geographic adoption corridors. For strategists, this means that top-line potential must be assessed alongside the operational realities of which segments are scaling fastest, which are constrained by procurement complexity, and where competitive crowding may compress pricing leverage.
Segmentation Logic, Competitive Positioning, and Value Migration
The market's internal architecture is defined by a clear divergence between high-resolution platforms and legacy alternatives. High-resolution manometry systems represent the dominant share of market value, reflecting their alignment with contemporary diagnostic protocols and their perceived clinical utility in capturing detailed pressure topographs for the rectum and anal sphincter. Conventional systems remain part of the landscape, particularly in cost-sensitive procurement environments or facilities with existing installed bases, but their relative contribution is increasingly shaped by replacement cycles rather than greenfield adoption. Solid-state systems add another layer of differentiation, offering specialized sensing characteristics that appeal to specific diagnostic workflows and institutional preferences.
Worldwide Anorectal Manometry Devices Market
End-user demand is similarly stratified. Hospitals continue to anchor the largest portion of device utilization, given their role in complex diagnostic workups, surgical evaluation, and multidisciplinary pelvic floor programs. Diagnostic centers contribute a substantial secondary demand pool, often driven by higher-throughput testing models and focused GI assessment services. Specialty clinics represent a strategically important growth vector, particularly as office-based diagnostics and biofeedback therapy models expand the scope of where and how manometry is performed. Each of these end-user environments carries different procurement cycles, evaluation criteria, clinical priorities, and service expectations, meaning that competitive advantage increasingly depends on matching product architecture to workflow realities rather than competing solely on sensor count or hardware specifications.
On the competitive front, the landscape is populated by specialists and broader gastrointestinal technology vendors whose product strategies reflect differing philosophies around clinical precision, portability, disposability, and software integration. Laborie Medical Technologies has advanced a strong high-resolution portfolio, including both fixed and compact system configurations, alongside what is recognized as the first disposable high-resolution anorectal manometry catheter designed for measuring static and dynamic pressures in the lower GI tract, aligned with IAWG protocol and London classification. Medtronic continues to emphasize advanced pressure sensing architectures, including three-dimensional probe designs offering extensive measurement points for assessment of rectal and anal sphincter pressures. Medspira has positioned its portable platform for office-based diagnostics and pelvic floor biofeedback therapy, with a design emphasis on expedited procedures and minimized patient contact. Diversatek Healthcare supports pelvic floor evaluation through high-resolution probes with multidirectional and circumferential capabilities, paired with dedicated software and support for EMG and balloon expulsion testing.
In parallel, regional and specialized manufacturers such as Alacer Biomédica, THD Lab, The Prometheus Group, HC Italia, and Medica S.p.A. illustrate how product differentiation can be built around channel count, exam-time efficiency, portability, ambulatory recording, and combined modalities like simultaneous surface electromyography. This breadth of approaches underscores an important strategic reality: the market is no longer defined by a single winning technical paradigm, but by multiple viable combinations of clinical accuracy, operational convenience, and total cost of ownership. Companies that can align their offerings with the right clinical justification, regulatory basis, and reimbursement pathway are better positioned to capture sustained share in a fragmented but consolidating environment.
Recent commercial and regulatory milestones reinforce the pace of change. In early 2025, FDA 510(k) clearance was granted to the Fecobionics Anorectal System as substantially equivalent to a recognized portable anorectal manometry device, signaling continued regulatory acceptance for novel portable approaches to pelvic floor evaluation in patients with constipation or fecal incontinence. This follows earlier clearance activity and product introductions from Laborie, including the launch of a compact system and the first disposable HRAM catheter aimed at enhanced diagnostics of defecatory disorders and pelvic floor dysfunction, as well as separate FDA clearance events for its anorectal catheter as a Class II device. These developments are not isolated product announcements; they represent the visible edge of a broader shift toward streamlined procedure workflows, improved infection-control economics, and broader access to standardized manometry outside traditional hospital environments.
Regulatory, Reimbursement, and Standards-Driven Dynamics
The operational environment for anorectal manometry devices is being shaped by a set of overlapping external forces that directly affect market access, adoption timing, and commercial risk. In the United States, anorectal manometry devices are regulated as Class II gastrointestinal motility monitoring systems under 21 CFR 876.1725 with product code KLA, requiring 510(k) clearance for marketing. This regulatory pathway creates a defined but non-trivial barrier to entry and influences the speed at which new probe designs, software configurations, or portable systems can reach procurement-eligible status. For manufacturers, clearance strategy and predicate selection can become as important as hardware performance in determining time-to-market.
Reimbursement dynamics add further nuance. Effective January 1, 2026, CPT codes 91120 and 91122 for anorectal manometry are deleted and replaced by new Category I codes: 91125 for anorectal manometry with rectal sensation and rectal balloon expulsion test, when performed, and 91124 for rectal sensation, tone, and compliance study. This coding transition matters because it can alter documentation requirements, billing workflows, and reimbursement certainty across different care settings. For providers, the change may affect how procedures are coded and justified; for device manufacturers, it can influence the value proposition of systems that support specific test components, streamline coding-aligned documentation, or integrate protocols that map cleanly to the updated code structure.
Standards adoption is another structural driver. High-resolution anorectal manometry systems increasingly incorporate the International Anorectal Physiology Working Group protocol and London classification for measurement and analysis. As clinical expectations converge around these frameworks, devices that natively support standardized interpretation, consistent pressure mapping, and reproducible reporting gain a practical advantage in environments where diagnostic comparability and clinical confidence matter. The combination of regulatory classification, updated reimbursement codes, and protocol standardization means that competitive differentiation will increasingly depend on how well a product is aligned with the real-world administrative and clinical requirements of the testing environment—not merely on technical feature lists.
What the Study Delivers for 2026 Decision-Making
This market research is built to support concrete strategic choices rather than abstract trend commentary. It translates macro growth signals into actionable intelligence across product planning, competitive positioning, geographic expansion, and end-user targeting. The study brings together quantitative market structure, company-level competitive context, recent regulatory and product developments, and the administrative forces shaping adoption. It is designed to help leadership teams answer questions that directly influence near-term action:
- Where is demand and value creation concentrated across product types, end users, and major geographic regions, and how are those concentrations likely to evolve?
- Which product architectures and workflow features are most closely associated with adoption momentum in hospital, diagnostic center, and specialty clinic settings?
- How do recent FDA clearances and product introductions change the competitive baseline, and where do they open opportunities for follow-on innovation or market exit from less defensible positions?
- How do reimbursement code changes and regulatory classification requirements affect commercial planning, pricing logic, and service/enablement requirements?
- Where can manufacturers and distributors anticipate margin pressure, procurement complexity, or adoption barriers, and what strategic responses are available?
The analysis is structured to be portable across internal use cases. Commercial teams can use it to refine segmentation assumptions, prioritize territories, and sharpen value propositions. Product and R&D leaders can benchmark device capabilities against the prevailing competitive set and identify gaps in protocol alignment, portability, disposability, or software functionality. Corporate development and investor-facing teams can use the market structure and concentration data to assess demand durability, competitive dynamics, and the relative defensibility of different business models. Given the degree of concentration observed in the broader competitive environment, understanding who holds share, where that share is derived from, and how quickly new entrants or novel device types can gain traction is central to planning with confidence.
Worldwide Proctoscope Market
Accessing the Full Intelligence Set
The narrative above captures the strategic logic and market architecture behind the Worldwide Anorectal Manometry Devices Market report, but the operational value lies in the deeper quantitative and company-level detail that supports scenario planning and decision execution. The full study provides the specific market sizing evolution, segmentation structures, concentration metrics, competitive company profiles, recent regulatory and product developments, and reimbursement and standards context needed to convert insight into action. For teams preparing 2026 strategies, the complete dataset offers the precision required to validate assumptions, compare end-market opportunities, and align product and commercial roadmaps with the realities of a market that is expanding while also becoming more regulated, more standardized, and more workflow-dependent.
If your objective is to move from directional awareness to executable strategy, the full report provides the structured intelligence necessary to assess where growth will be captured, which competitive positions are most defensible, and how external dynamics will shape adoption across the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Anorectal Manometry Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Titanium Chloride Market to Hit $21.5B by 2032, Growing at 4.8% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Titanium Chloride Market: Navigating Growth, Volatility, and Competitive Shifts Through 2032
Executive Overview
The global titanium chloride market stands at a critical inflection point. As the foundational intermediate for titanium sponge production, chloride-process titanium dioxide, and advanced Ziegler-Natta catalysts, titanium tetrachloride (TiCl4) demand is tightly coupled to downstream materials cycles, regulatory evolution, and regional capacity restructuring. Our latest Worldwide Titanium Chloride Market research report delivers a comprehensive, data-grounded assessment designed specifically for executive decision-makers navigating the 2026–2032 horizon.
Between 2020 and 2025, the market expanded from approximately 12,150 million USD to 15,510 million USD, reflecting sustained industrial demand and incremental capacity additions across key producing regions. The trajectory is projected to continue through the forecast window, with the market expected to reach roughly 21,534 million USD by 2032 at a compound annual growth rate of 4.8 percent. These macro indicators are more than backward-looking statistics; they form the analytical backbone of a deeper investigation into supply chain resilience, pricing dynamics, competitive positioning, and regional risk exposure. This article outlines the strategic architecture of the research and explains why it should serve as a core input for capital allocation, procurement planning, and competitive strategy in 2026.
Worldwide Titanium Chloride Market
Zirconium Oxychloride Market
Why This Research Matters for 2026 Decision-Making
Market intelligence loses value when it remains abstract. The strategic function of this report is to translate market-scale trends into operational foresight. Several structural forces are actively reshaping how titanium chloride is produced, priced, and distributed, and each carries direct implications for procurement leaders, plant planners, and corporate development teams.
- Capacity additions in Asia have altered the regional supply baseline, while environmental enforcement and feedstock volatility continue to influence marginal production economics.
- Downstream titanium dioxide manufacturers are adjusting procurement strategies in response to chloride-process technology investments, export trade measures, and shifting feedstock contracts.
- Titanium sponge producers face a high input intensity relationship with TiCl4, meaning small changes in intermediate availability or pricing can cascade into broader cost structures.
- Maintenance cycles, logistics constraints, and energy costs are increasingly interacting to create short-term supply tightening, particularly in higher-cost operating environments.
The 2026 edition of this report is structured to help organizations separate signal from noise. Rather than presenting a static snapshot, the analysis integrates historical trajectory, forward projections, and company-level activity to support scenario planning. Executives evaluating new production investments, long-term offtake agreements, or market entry strategies can use the research to benchmark margin exposure, assess competitive moats, and identify where operational flexibility will matter most.
Market Trajectory and Structural Dynamics
The headline growth figures frame an industry that is expanding, but not uniformly. Over the historical period, revenue progression reflects both volume growth and shifting value capture across grades, end uses, and geographies. The forecast period through 2032 indicates continuing expansion, though the pace will be influenced by downstream demand elasticity, regulatory pressure on pollution-intensive processes, and the economics of chloride versus alternative production routes.
One of the most operationally relevant themes is the interaction between raw material costs and intermediate pricing. Titanium slag availability, chlorine gas pricing, and procurement patterns for ilmenite all feed directly into TiCl4 production economics. Recent market signals show firmer input procurement by titanium dioxide producers and price levels in certain regions reaching multi-year highs, underscoring the need for scenario-based procurement strategies rather than static budgeting. At the same time, the relationship between TiCl4 consumption and downstream output remains material: titanium sponge production in major manufacturing centers typically requires substantial TiCl4 input per ton of finished metal, which amplifies the strategic importance of intermediate supply security.
Trade policy and environmental regulation add another layer of complexity. Anti-dumping measures on certain titanium dioxide imports have ripple effects across the broader titanium chemicals value chain, altering demand patterns for intermediates and influencing where capacity is most competitive. In parallel, increasingly frequent environmental inspections targeting pollution reduction continue to affect production from titanium slag-based routes in key manufacturing regions. These constraints do not merely raise compliance costs; they influence which assets can flex output quickly, which operations face downtime risk, and how regional price dispersion evolves during periods of tight supply.
The report also examines market concentration and competitive structure. The industry is not fully fragmented; a meaningful share of value is captured by firms with integrated chloride-process operations, large pigment portfolios, or dedicated titanium metal capabilities. Understanding concentration dynamics helps buyers and investors evaluate bargaining power, substitution risk, and the likelihood of supply consolidation under stress conditions.
Competitive Landscape: Who Shapes the Market and How
Competitive advantage in titanium chloride increasingly derives from integration, technology access, and geographic positioning. The strongest players typically combine intermediate production with downstream titanium dioxide or titanium metal operations, allowing them to balance merchant sales with internal consumption and to manage feedstock flexibility more effectively. The report profiles the companies that are most actively shaping supply, technology, and regional capacity trends.
- Tronox Holdings plc operates as one of the largest global suppliers of titanium chemicals, including TiCl4 and derivatives, with production tied to both merchant sales and internal use in pigments and titanium sponge. Its footprint illustrates how integrated chloride chemistry supports broader titanium product portfolios.
- The Chemours Company is a major global producer of TiCl4 as a key intermediate in chloride-process titanium dioxide production, with large-scale facilities that leverage proprietary chloride technology and broad feedstock flexibility. Operational continuity at such sites can significantly affect regional supply conditions.
- Toho Titanium Co., Ltd. produces and sells titanium tetrachloride as part of its chemicals business, supporting titanium sponge production via the Kroll process and other titanium metal products. Its role highlights the linkage between intermediate supply and advanced metal manufacturing.
- OSAKA Titanium Technologies Co., Ltd. manufactures titanium tetrachloride under strict quality control for titanium sponge and other high-purity applications, with distribution adjusted to different transport requirements. This orientation emphasizes quality and application specificity in a market where grade differentiation matters.
- Ishihara Sangyo Kaisha, Ltd. (ISK) produces titanium tetrachloride as a main raw material for chloride-process titanium dioxide manufacturing, reinforcing the strategic importance of upstream intermediates in pigment supply chains.
- LB Group (Lomon Billions) operates significant chloride-process TiO2 capacity supported by dedicated titanium tetrachloride production, including a substantial capacity addition that reflects ongoing investment in chloride-based value chains.
- Kronos Worldwide, Inc. is a leading producer of TiO2 via chloride process requiring substantial TiCl4 volumes as an intermediate, positioning the company deeply within the global titanium chemicals value chain.
- Venator Materials PLC produces titanium tetrachloride for pigments and other applications as part of its titanium dioxide operations, linking intermediate chemistry directly to pigment market strategy.
- American Elements manufactures and distributes titanium tetrachloride for bulk industrial and research use, with production supporting advanced materials applications. Its presence broadens the market beyond mainstream pigment and sponge routes.
- CITIC Titanium Industry Co., Ltd. is a Chinese producer involved in titanium tetrachloride for chloride-process TiO2, with ongoing capacity expansions in high-purity grades, illustrating continued investment in differentiated product segments.
Recent company-level and market-level developments reinforce why competitive monitoring must be continuous rather than periodic. In mid-2025, several producers faced tightening supply conditions across North America and Europe during the third quarter, driven by scheduled maintenance, elevated energy costs, and logistics disruptions. The resulting price pressure was especially pronounced in Europe, where feedstock costs and export demand compounded the impact. Those episodes demonstrate how quickly regional availability can shift even in a structurally growing market.
Operational diplomacy can be just as important as capacity. In mid-2025, regulatory developments in Mexico allowed the resumption of normal operations at a major titanium dioxide facility dependent on TiCl4 production, showing how environmental and utility constraints can temporarily reshape regional supply expectations. Meanwhile, capacity expansion announcements in China have highlighted the continued push to support chloride-process titanium dioxide demand with dedicated intermediate production. Each event alters short-term availability and influences long-term competitive positioning.
Inside the Report: What Decision-Makers Will Find
This research is designed as a decision toolkit rather than a descriptive summary. It combines quantitative market modeling with qualitative analysis of competitive behavior, regulatory exposure, and downstream demand linkages. The objective is to provide a usable framework for pricing strategy, capacity planning, supplier evaluation, and investment prioritization.
The report includes detailed historical reconstruction and forward projection, enabling readers to trace how the market evolved from 2020 through the base year and how growth is expected to unfold across the forecast window. It analyzes segmentation by region, type, and application to clarify where value is concentrated and how demand drivers differ across end markets. Rather than reducing the industry to a single average, the segmentation analysis helps identify which segments are most exposed to feedstock volatility, which rely on high-purity specifications, and which are shaped by cyclical pigment or catalyst demand.
Competitive profiling is integrated with recent developments to show not only who the major participants are, but how their recent actions affect supply conditions. The report examines operational resumption events, capacity additions, and market-wide supply tightening to help readers interpret near-term risk. It also contextualizes raw material procurement trends and regulatory actions that influence production economics, making it easier to connect external disruptions with internal planning assumptions.
A central strength of the study is its emphasis on actionable interpretation. The analysis supports questions such as:
- Where are supply constraints most likely to emerge during maintenance-heavy periods or energy-cost spikes?
- Which downstream applications create the most stable demand anchors for titanium chloride?
- How do regional trade measures alter procurement geography and supplier qualification strategies?
- What does market concentration imply for negotiation leverage, substitution options, and long-term contracting?
How to Use This Intelligence Strategically
For procurement and supply chain leaders, the report provides a basis for building more resilient TiCl4 sourcing strategies. By understanding where capacity is expanding, where environmental and energy pressures are intensifying, and how regional tightening events have unfolded, teams can structure contracts, inventory buffers, and supplier diversification plans with greater confidence. For pricing and commercial teams, the analysis helps frame negotiation positions around feedstock sensitivity, grade differentiation, and regional availability dispersion.
For strategy and corporate development teams, the research supports evaluation of market entry, partnership, and capacity investment options. Because titanium chloride sits between raw material processing and high-value downstream products, the economics of any expansion or acquisition depend heavily on integration benefits, technology access, and exposure to regulatory or trade shocks. The report’s competitive and segmentation structure helps decision-makers test whether a proposed move aligns with structural demand or merely chases cyclical pricing.
For investors and advisors, the report offers a disciplined way to assess which participants are most likely to benefit from continued chloride-process adoption, which operations face greater disruption risk, and how market concentration may shape future margin distributions. The inclusion of recent operational and market events ensures that analysis is anchored in current conditions rather than outdated assumptions.
Conclusion: Turning Market Scale into Strategic Advantage
The worldwide titanium chloride market is expanding, but growth alone does not guarantee commercial advantage. Success in 2026 and beyond will depend on how well organizations interpret the interaction of capacity dynamics, feedstock costs, regulatory pressure, trade policy, and competitive behavior. Our Worldwide Titanium Chloride Market report is built to support that interpretation with structured data, company-level intelligence, and forward-looking analysis through 2032.
This article has provided a high-level view of the strategic logic behind the research and the market forces it examines. The full study goes further, offering detailed market sizing, segmentation mechanics, competitive profiling, recent development tracking, and scenario-ready insights that cannot be fully captured in a short briefing. For teams that need to move from general awareness to specific planning parameters, the complete report is the necessary next step.
For detailed analysis of this topic, please visit the official page: Worldwide Titanium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Veterinary API Market Hits $7.2B in 2025, Forecast 7.15% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Global Veterinary API Manufacturing Landscape: Strategic Imperatives for 2026 and Beyond
The global animal health industry is entering a critical inflection point. As veterinary care standards rise across both companion and livestock sectors, the demand for high-quality Active Pharmaceutical Ingredients has become a cornerstone of therapeutic innovation and supply chain resilience. For executives, investors, and supply chain strategists, understanding the trajectory of the veterinary API manufacturing market is no longer optional—it is a strategic necessity. Our newly released Worldwide Veterinary API Manufacturing Market study provides the comprehensive intelligence required to navigate this evolving terrain, with a particular focus on how macroeconomic tailwinds, regulatory shifts, and competitive realignments will shape enterprise decision-making throughout the 2026–2032 forecast horizon.
Market Trajectory and the 2026 Decision Window
The veterinary API manufacturing sector has demonstrated consistent structural growth over the past half-decade, expanding from a baseline of approximately USD 5,100 million in 2020 to an estimated USD 7,200 million in 2025. This trajectory reflects more than incremental expansion; it signals a maturing ecosystem where pharmaceutical-grade precision, regulatory compliance, and scalable production capacity are increasingly intertwined. Looking ahead, the market is projected to reach a range exceeding USD 11,600 million by the close of 2032, underpinned by a compound annual growth rate of 7.15 percent. These figures frame the 2026 decision window as a pivotal moment for capital allocation, manufacturing footprint optimization, and partnership strategy.
For corporate planners, the near-term forecast carries distinct operational implications. The 2026–2028 period is expected to sustain steady revenue progression, driven by sustained demand for anti-infective therapies, parasiticides, and biological formulations across multiple animal species. However, growth alone does not dictate strategy. The real value of forward-looking intelligence lies in identifying where capacity constraints, regulatory bottlenecks, and geographic supply dependencies will intersect with corporate objectives. Companies that align their 2026 investment pipelines with validated demand signals and supply chain risk assessments will be better positioned to capture margin resilience and market share as the cycle advances toward the end of the decade.
Veterinary Drug Market
Our analysis situates these macro trends within a broader operational context, examining how shifting procurement patterns, evolving quality standards, and geopolitical trade dynamics are altering the cost structures and lead times that define modern veterinary API procurement. The study is designed to equip decision-makers with the analytical frameworks needed to evaluate sourcing strategies, assess manufacturing partnerships, and forecast capacity requirements before market conditions tighten.
Structural Drivers Shaping the Forecast Period
Several interconnected forces are accelerating the transition from routine production to strategically calibrated manufacturing. First, the global push toward standardized animal health protocols has elevated the baseline requirement for pharmaceutical-grade consistency, pushing manufacturers to invest in advanced synthesis capabilities and rigorous quality assurance infrastructure. Second, the growing complexity of formulation requirements across species—from ruminants and poultry to companion animals—has increased the demand for specialized active ingredients that cannot be efficiently sourced through fragmented or unverified supply networks.
Third, the regulatory environment continues to evolve at a pace that directly impacts manufacturing compliance and product availability. Monitoring bodies such as the U.S. Food and Drug Administration have highlighted recurring supply disruptions in critical antimicrobial ingredients, underscoring how dependent downstream formulations remain on stable upstream production. At the same time, international standards increasingly emphasize antimicrobial stewardship, residue management, and export-quality compliance, raising the operational bar for manufacturers seeking to serve regulated markets.
Fourth, geopolitical and trade developments have introduced a new layer of cost and continuity risk. With a significant share of veterinary active ingredients historically routed through specific overseas production hubs, any shift in tariff policy, logistics friction, or export control can quickly affect landed costs and supply reliability. These dynamics are not abstract; they are actively reshaping sourcing models, prompting manufacturers and buyers alike to reassess geographic concentration, redundancy planning, and long-term contract structures.
What This Study Delivers for Enterprise Strategy
The Worldwide Veterinary API Manufacturing Market report is structured to translate high-level trends into actionable intelligence. It provides a detailed examination of market sizing, growth trajectories, and segmentation patterns across the core dimensions that matter most to manufacturing and procurement leaders. Rather than presenting isolated statistics, the study weaves together demand-side drivers, production technology pathways, and competitive positioning to show how the ecosystem functions as an integrated system.
Readers will find a systematic breakdown of the principal active ingredient categories that anchor veterinary pharmaceutical portfolios, alongside an evaluation of the synthesis approaches that define production economics, scalability, and regulatory readiness. The analysis extends to regional manufacturing distribution, highlighting where production capacity is concentrated, where supply dependencies create vulnerability, and where emerging hubs are gaining relevance in global procurement strategies. By contextualizing these structural elements within the forecast period, the report enables clients to model scenarios, stress-test sourcing assumptions, and identify where strategic flexibility will yield the greatest commercial advantage.
Beyond market structure, the study incorporates a focused competitive assessment of the organizations shaping the field. This includes an evaluation of multinational animal health leaders with integrated API development capabilities, specialized manufacturers serving specific therapeutic categories, and contract development and manufacturing organizations expanding their veterinary capacity to meet global demand. The competitive lens is not limited to corporate profiles; it examines how facility investments, technology partnerships, and site acquisitions are altering supply network reliability and production readiness. Recent industry developments—including dedicated facility commissioning, strategic technology licensing agreements, and contract manufacturing site acquisitions—are analyzed as indicators of where capacity is being built, where innovation is being embedded, and where supply security is being prioritized.
To ensure operational relevance, the report also integrates key industry context across regulation, raw material availability, logistics, and trade policy. These inputs are mapped to the segments and regions they affect most, giving clients a clearer picture of the constraints and opportunities that will influence pricing, lead times, and formulation planning through 2032.
Competitive Realignment and Supply Network Resilience
The competitive landscape in veterinary API manufacturing is defined by a blend of established animal health enterprises and specialized production organizations, each pursuing distinct strategic advantages. At one end of the spectrum, global animal health leaders maintain in-house or tightly controlled API capabilities that support broad therapeutic portfolios spanning parasiticides, anti-infectives, vaccines, and biologicals for both livestock and companion animals. These organizations benefit from vertical integration, extensive regulatory experience, and the ability to align API supply with finished product pipelines.
At the same time, a robust tier of specialized manufacturers and CDMO-style operators has gained prominence by focusing on production efficiency, regulatory-grade quality systems, and flexible supply arrangements. Companies operating from established pharmaceutical manufacturing regions are expanding dedicated veterinary API capacity, investing in compliance infrastructure, and positioning themselves as reliable nodes within multinational supply chains. This specialization matters because veterinary formulations often require consistent batch quality, species-specific compliance, and the ability to support both generic and differentiated product pipelines.
Worldwide Veterinary API Manufacturing Market
Recent corporate activity reflects a clear emphasis on capacity assurance and technology access. Facility expansion and the commissioning of dedicated veterinary API production units signal growing confidence in long-term demand, while also addressing the need for modernized infrastructure that can satisfy tightening quality and sustainability expectations. In parallel, partnerships aimed at accessing advanced development platforms and the acquisition of contract manufacturing sites illustrate how organizations are fortifying supply continuity for critical farm animal and companion animal products. These moves are not isolated; they represent a broader pattern of structural reinforcement as buyers and producers alike respond to the reality that API availability can directly influence therapeutic access and commercial performance.
Navigating Concentration, Cost, and Continuity Risks
Market concentration remains an important strategic consideration. A meaningful share of revenue is held by a relatively compact group of leading participants, which shapes pricing dynamics, partnership leverage, and the bargaining power of downstream formulators. Understanding where concentration exerts pressure—and where fragmented supply offers flexibility—is essential for procurement strategy, contract negotiation, and multi-sourcing design.
Cost and continuity risks are equally central to 2026 planning. Regulatory oversight of antimicrobial supply, periodic ingredient shortages, and production delays tied to overseas manufacturing have already demonstrated how quickly availability can become a constraint. When combined with trade policy shifts affecting pharmaceutical inputs, these factors can raise production expenses and complicate inventory planning. The result is a market environment in which resilience is increasingly valued alongside efficiency. Organizations that diversify qualified sourcing channels, align manufacturing partnerships with compliance capability, and anticipate regulatory pacing will be better equipped to manage volatility without sacrificing product quality or therapeutic reliability.
Strategic Takeaways for 2026 Planning
The veterinary API manufacturing market is entering a phase where growth, regulation, and supply chain architecture will jointly determine competitive outcomes. For leadership teams preparing 2026 strategic plans, several priorities stand out. First, capacity strategy must be evaluated not only against projected volume but also against the quality, compliance, and continuity standards that regulated markets increasingly require. Second, sourcing models should be stress-tested against concentration risk, logistics variability, and shifting trade conditions to ensure that cost optimization does not inadvertently create exposure. Third, partnership selection should account for technological readiness, production flexibility, and the ability to support both current portfolios and emerging therapeutic categories.
Our Worldwide Veterinary API Manufacturing Market study is designed to support these decisions with rigorous market sizing, segmentation analysis, competitive intelligence, and scenario-ready context. It provides the evidentiary foundation necessary to move from reactive procurement to proactive market positioning. For organizations seeking to secure supply advantage, evaluate entry or expansion opportunities, and align manufacturing strategy with the realities of a maturing global animal health sector, the full report delivers the depth required to act with confidence.
The complete analysis, including detailed segmentation data, regional manufacturing profiles, and granular competitive assessments, is available through the full market research release. Accessing the complete study enables decision-makers to translate these directional insights into precise, executable strategies for the 2026–2032 cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Veterinary API Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fire System Aircraft Market to Hit $3,044.52M by 2032, 4.85% CAGR
By pmarketresearch, 2026-09-16
Unlocking Strategic Value in the Global Fire System Aircraft Market: A 2026 Outlook
As the aviation industry navigates a period of unprecedented transformation, the integration of advanced fire protection systems has evolved from a regulatory necessity to a critical competitive differentiator. At PW Consulting, we have meticulously compiled our latest Worldwide Fire System Aircraft Market research to provide stakeholders with the actionable intelligence required to navigate this complex landscape. This study is not merely a collection of statistics; it is a strategic compass designed to guide investment decisions, product development roadmaps, and supply chain optimizations throughout the forecast period extending to 2032.
Worldwide Fire System Design Market
The market has demonstrated resilience and steady growth over the past half-decade. Historical data from 2020 through 2025 reveals a consistent upward trajectory in revenue, driven by aging fleet replacements, heightened safety regulations, and the expansion of global air travel networks. Building on this foundation, the market is projected to reach substantial valuation milestones by the end of the forecast horizon. With a compound annual growth rate of 4.85 percent across the forecast period of 2026 to 2032, the industry presents a compelling opportunity for stakeholders who can align their strategies with emerging technological and regulatory shifts. Understanding the magnitude of this growth is essential, but recognizing the underlying drivers is where true strategic advantage lies.
The Operational Core: What This Research Delivers
Our comprehensive analysis goes beyond top-line figures to dissect the operational mechanics of the market. The report provides a granular examination of the two primary system categories that define the industry landscape. We analyze the market share and growth potential of fire suppression and extinguishing systems versus fire detection and warning systems. While both segments are critical, their growth trajectories differ based on technological adoption rates and regulatory mandates. By understanding the distinct value propositions of each system type, manufacturers and investors can allocate resources more effectively.
Furthermore, the study segments the market by aircraft type, offering insights into the specific demands of narrow-body, wide-body, military, and regional or general aviation platforms. Each aircraft category presents unique engineering challenges and safety requirements. For instance, the density of installations in narrow-body aircraft contrasts sharply with the specialized suppression needs of military platforms. Our analysis illuminates these differences, helping partners tailor their solutions to the specific pain points of each segment. Additionally, the report breaks down revenue distributions across key geographic regions, highlighting where infrastructure development and regulatory enforcement are creating the most fertile ground for market expansion.
Beyond segmentation, the research delves into the qualitative dynamics shaping the industry. We examine the supply chain intricacies, from raw material sourcing for specialized agents to the manufacturing of high-pressure vessels and pyrotechnic cartridges. Our team has evaluated the production capabilities and technological readiness of major players to provide a clear picture of supply-side resilience. This is crucial for organizations seeking to mitigate risk in an era where supply chain disruptions can have cascading effects on aircraft maintenance schedules and operational readiness.
Competitive Landscape and Dominant Forces
The market structure is characterized by a mix of established aerospace giants and specialized niche manufacturers. Our analysis indicates a moderate to high level of market concentration, with the top three players holding a significant portion of the market share, while the top five collectively command an even larger share of total revenue. This concentration suggests that economies of scale and entrenched relationships with Original Equipment Manufacturers (OEMs) play a vital role in sustaining market position. However, the presence of agile, specialized firms indicates that innovation and certification speed remain powerful levers for market entry and growth.
Collins Aerospace (RTX) stands as a paramount example of integrated capability, providing a broad range of advanced fire detection and suppression systems for commercial and military aircraft. Their ability to cover automatic fire and explosion suppression for occupied spaces, cargo bays, and engine areas positions them as a central partner for major airframe manufacturers. Similarly, Meggitt PLC has established a reputation for designing and manufacturing fire suppression systems fitted on virtually every civil and military aircraft, leveraging in-house development for specific threat zones including engine, APU, and cargo applications. These entrenched players set the standard for reliability and certification compliance.
On the component and specialized manufacturing side, AMERON (AMETEK MRO) operates as a leading OEM manufacturer of aircraft fire suppression systems, components, high-pressure vessels, and pyrotechnic cartridges for engine, APU, cargo, and lavatory applications across commercial and military platforms. Their focus on critical hardware underscores the importance of the supply chain beneath the system integrators. Ventura Aerospace Inc. distinguishes itself by developing FAA-certified fire suppression systems specifically for Class E cargo compartments on aircraft such as MD-11F, MD-10F, and 777F, with modular designs adaptable to various fixed-wing platforms. This specialization highlights the opportunity for targeted solutions in cargo safety, a sector under increasing scrutiny.
The portable extinguisher market also sees dynamic activity. H3R Aviation supplies portable Halon and Halotron fire extinguishers and mounting options for fixed- and rotary-wing aircraft of all types and sizes. Amerex Corporation manufactures portable and fixed fire extinguishers for aviation applications, with ongoing innovation in aircraft fire safety products. These companies are often at the forefront of responding to regulatory changes regarding portable agent specifications. Meanwhile, Parker Aerospace offers ATA Chapter 26 fire protection systems with high accuracy, reliability, and low maintenance for aircraft safety, emphasizing the operational cost benefits of robust design.
Innovation in agents and specialized services is represented by companies like Hazard Control Technologies (HCT), which provides specialized aircraft fire suppression services and agents, including F-500 EA encapsulator technology qualified under FAA AC 150/5210-6E for aviation hazards including lithium-ion battery fires. Perimeter Solutions supplies SOLBERG and AUXQUIMIA Class B fluorine-free and AFFF firefighting foam concentrates, including AVIGARD line certified for ICAO aviation applications, addressing the environmental shift in chemical agents. Finally, PacSci EMC supplies energetic components and fire extinguishing cartridges qualified for commercial and military aircraft fire suppression systems, supporting FAA Airworthiness approvals, ensuring that the mechanical execution of suppression systems meets rigorous standards.
Regulatory Waves and Technological Shifts
No strategic analysis of this market is complete without a deep dive into the regulatory environment, which is currently undergoing significant turmoil and transformation. The phase-out of Halon-based systems is the single most impactful dynamic shaping the near-term market. The EU Ozone Regulation sets end-dates for halon use in existing fleets, with a key deadline of 31 December 2025 for portable Halon 1211 extinguishers in cabins and crew compartments on EASA-registered aircraft. This regulatory cliff creates an immediate demand for replacement solutions and retrofitting services.
In response to these mandates, EASA and the European Commission published the Halon replacement in the aviation industry guide 2025 to support compliance with EU Ozone Regulation on halon phase-out for portable extinguishers and onboard systems. This guidance serves as a critical roadmap for operators and manufacturers alike. Furthermore, ICAO has introduced cut-off dates after which Halon 1301-based fire extinguishing systems should no longer be used for new-type certified aircraft, including cargo compartments. These international standards reinforce the global trend away from ozone-depleting substances, forcing a structural shift in product portfolios.
The transition is not just about compliance; it is about performance and environmental stewardship. The transition to fluorine-free foam concentrates (SFFF/AR-SFFF) and clean agents such as Novec 1230 or 2-BTP/CO2 blends is accelerating for aviation applications due to environmental regulations and halon phase-out. Manufacturers who can validate the efficacy of these new agents under extreme aviation conditions will capture significant market share. This shift is complemented by evolving safety standards for emerging technologies. FAA and EASA continue to enforce enhanced fire protection requirements for lithium battery fires in cargo compartments and electronic device storage under updated airworthiness standards. As the electrification of aircraft components and the transport of lithium-ion batteries increase, the ability to suppress thermal runaway events becomes a premium capability.
Recent industry developments underscore the speed of this adaptation. In October 2025, H3R Aviation introduced Halotron BRx extinguishers as a Halon 1211 replacement for portable aircraft fire extinguishers ahead of regulatory deadlines, demonstrating proactive product lifecycle management. Concurrently, SAE International released new standards for powerplant fire protection systems, updating and supplementing FAA Advisory Circular 20-135 guidance, which will influence design requirements for engine fire protection for years to come. By December 2025, the deadline for European-registered aircraft to no longer carry Halon 1211 portable fire extinguishers marks a hard stop that will trigger a surge in replacement orders.
Strategic Implications for 2026 and Beyond
For decision-makers planning their moves in 2026, the implications of this research are clear. The convergence of steady market growth, regulatory pressure, and technological innovation creates a high-stakes environment. Companies must balance the immediate revenue opportunity presented by Halon replacement mandates with the long-term investment required for next-generation suppression agents and detection technologies. Partnerships between system integrators and agent suppliers will become increasingly vital to ensure certification speed and operational reliability.
Supply chain resilience is another critical focal point. With specific requirements for high-pressure vessels, pyrotechnic cartridges, and specialized foam concentrates, the ability to secure qualified components will differentiate successful market participants from those facing bottlenecks. The market concentration data suggests that while large players dominate, there is ample room for specialized firms to thrive by addressing niche requirements, such as cargo compartment specific solutions or lithium-ion battery fire suppression. Understanding the distinct growth profiles of narrow-body versus wide-body aircraft, as well as the persistent demand in military and general aviation sectors, allows for targeted portfolio strategy.
Worldwide Fire System Aircraft Market
The geographic dimension of the market also warrants attention. While historical revenue data shows strong performance across North America, Europe, and Asia Pacific, the rate of regulatory adoption and fleet modernization varies by region. Strategic market entry or expansion plans must account for these regional nuances rather than applying a one-size-fits-all approach. The research provides the necessary regional breakdowns to inform localized strategies without exposing the specific numerical allocations that would require a full report download to verify.
Conclusion: The Path to Informed Action
The Worldwide Fire System Aircraft Market is at a pivotal juncture. The data confirms a robust growth trajectory over the coming years, but the real value lies in understanding the forces that will shape that growth. Regulatory deadlines are acting as catalysts, environmental concerns are driving chemical innovation, and evolving safety standards for batteries and powerplants are redefining system requirements. Our latest research publication captures these complexities in a structured, actionable format.
We invite industry leaders, investors, and strategic planners to leverage this intelligence to fortify their 2026 decision-making processes. The complete report offers the detailed segmentation data, competitive profiling, and regional analysis necessary to build a resilient strategy. By accessing the full study, stakeholders can move beyond general trends to specific, data-backed plans that align with the realities of the market. The future of aviation fire safety is being written now, and those with the deepest insights will be best positioned to lead.
For detailed analysis of this topic, please visit the official page: Worldwide Fire System Aircraft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Paroxetine Market to Hit $1,074.88M by 2032, 4.12% CAGR
By pmarketresearch, 2026-09-16
Navigating the Paroxetine Market: Strategic Intelligence for 2026 and Beyond
The global pharmaceutical landscape for central nervous system therapeutics continues to evolve at a complex pace, shaped by shifting clinical guidelines, evolving pricing architectures, and persistent supply chain realignments. Among these therapeutic categories, paroxetine remains a cornerstone intervention for mood and anxiety disorders, with a market trajectory that demands precise, forward-looking intelligence. As organizations prepare for strategic planning cycles in 2026, understanding the structural dynamics, competitive positioning, and macroeconomic tailwinds of the worldwide paroxetine sector is no longer optional—it is a critical prerequisite for informed capital allocation, portfolio optimization, and market entry or expansion decisions.
Our newly released Worldwide Paroxetine Market research study delivers a comprehensive, multi-dimensional assessment of this therapeutic space. Designed for executive leadership, commercial strategy teams, and investment analysts, the report bridges historical performance with forward-looking projections, equipping stakeholders with the analytical rigor required to navigate an environment defined by biosimilar-style generic competition, regional regulatory divergence, and tightening margin structures. Below, we outline the core strategic value proposition of this research and preview the operational intelligence it contains.
Worldwide Paroxetine Market
Macro Trajectory and Forecast Architecture
The paroxetine market has demonstrated consistent, albeit moderate, growth over the past half-decade, reflecting steady clinical adoption across established indications and the gradual expansion of accessible treatment pathways in emerging economies. Historical revenue data from 2020 through 2025 reveals a market that has matured beyond its initial generic proliferation phase and entered a stabilization period, where volume growth is increasingly balanced by disciplined pricing dynamics and formulation differentiation. Base-year revenue positioning in 2025 anchors the analysis, providing a reliable foundation for forward extrapolation.
Paracetamol Market
Looking ahead, the forecast horizon spanning 2026 through 2032 maps a clear growth continuum, with compound annual growth projections signaling a measured but sustained expansion trajectory. The market is expected to scale meaningfully across the forecast window, supported by persistent demand for first-line and adjunctive psychiatric therapies, broadening access in price-sensitive regions, and incremental formulation innovations that extend product lifecycles. While exact segmentation-level figures remain reserved for the full dataset, the overarching revenue curve points to a market that will cross significant valuation thresholds by the end of the decade, creating both opportunity and competitive intensity for active participants.
For strategic planners, this macro trajectory carries immediate implications. Organizations must evaluate whether their current market exposure aligns with projected regional demand shifts, assess the margin resilience of their product portfolios against anticipated pricing pressures, and determine the optimal timing for capacity investments or partnership structuring. The report translates these high-level trends into actionable scenario frameworks, allowing decision-makers to stress-test their strategies against multiple demand and pricing environments.
Competitive Landscape and Strategic Positioning
The paroxetine market is characterized by a concentrated yet highly fragmented competitive ecosystem, where branded legacy formulations coexist alongside a robust pipeline of generic alternatives. Major multinational pharmaceutical entities maintain strong commercial footprints through established branded portfolios, focusing on controlled-release architectures, brand equity preservation, and targeted physician engagement. Simultaneously, a cohort of globally integrated generic manufacturers has capitalized on the post-patent expiration environment, scaling production capabilities, securing regulatory clearances across multiple jurisdictions, and competing aggressively on price, supply reliability, and formulation breadth.
Industry concentration metrics underscore this dual dynamic. The market exhibits moderate concentration at the top tier, with leading participants commanding a meaningful share of total revenue, while the broader field remains highly competitive, particularly within the generic segment. This structure creates distinct strategic pathways: branded players must defend market share through clinical differentiation, specialty formulations, and value-based contracting, while generic manufacturers must optimize manufacturing efficiency, maintain stringent bioequivalence standards, and navigate increasingly complex procurement negotiations with distributors and pharmacy networks.
Recent regulatory and commercial milestones further illustrate the competitive velocity of this space. During the latter half of 2023 and into 2024, multiple manufacturers secured pivotal regulatory clearances for paroxetine hydrochloride and paroxetine mesylate formulations across key markets, expanding the availability of therapeutically equivalent alternatives and intensifying price competition in mature markets. These approvals reflect a broader trend of regulatory streamlining and heightened generic entry, which continuously reshapes supply availability and wholesale pricing architectures. For commercial teams, monitoring these approval timelines, understanding their downstream pricing implications, and aligning inventory or distribution strategies accordingly is essential to maintaining competitive agility.
The strategic depth of our analysis extends well beyond entity-level descriptions. The report evaluates competitive moats, examines supply chain dependencies, maps formulation-specific market penetration patterns, and assesses how recent regulatory events are likely to influence pricing trajectories and market share redistribution over the forecast period. Decision-makers gain a clear view of where competition is most intense, where differentiation remains viable, and how legacy product portfolios may need to be repositioned to sustain profitability.
Market Dynamics Shaping Operational Strategy
Several structural forces are actively redefining how the paroxetine market operates, and each carries direct implications for supply chain management, pricing strategy, and market access planning.
- Patent Landscape Evolution: The expiration of foundational intellectual property protections for core paroxetine formulations years ago fundamentally transformed market architecture, enabling widespread generic entry and initiating prolonged price erosion cycles. While this shift has improved patient access and reduced acquisition costs, it has also compressed margins and elevated the importance of manufacturing scale, regulatory compliance, and supply chain resilience. Organizations must continuously evaluate whether their cost structures can withstand ongoing pricing pressure while preserving service-level commitments to downstream partners.
- Essential Medicine Designation and Demand Stability: Inclusion of paroxetine on authoritative essential medicine listings reinforces its clinical indispensability and supports sustained demand visibility across both developed and developing healthcare systems. This designation provides a degree of commercial predictability that can inform long-term capacity planning, inventory positioning, and partnership structuring, particularly in regions where public procurement and formulary inclusion drive volume.
- API Sourcing and Geographic Concentration: The active pharmaceutical ingredient supply chain exhibits pronounced geographic concentration, with a substantial majority of production originating from a limited set of manufacturing hubs. While this concentration has enabled cost efficiencies and scalable output, it also introduces vulnerability to regulatory shifts, logistical disruptions, and geopolitical considerations. Strategic buyers and manufacturers alike must assess supplier diversification options, evaluate dual-sourcing feasibility, and model the financial and operational impact of potential supply interruptions.
- Supply Stabilization and Procurement Dynamics: Resolution of recent supply constraints in key markets has restored baseline availability and reduced acute procurement friction, but it has also recalibrated buyer expectations around reliability and pricing transparency. As inventory levels normalize, procurement teams are increasingly focused on total cost of ownership, contract flexibility, and supplier performance metrics rather than mere availability. Organizations that institutionalize these evaluation criteria will be better positioned to secure favorable terms amid competitive sourcing environments.
- Pricing Architecture and Margin Management: Intense generic competition has compressed unit economics in mature markets, with wholesale pricing settling at levels that demand operational efficiency and scale-driven cost advantages. Sustaining profitability in this environment requires disciplined procurement, optimized manufacturing yields, strategic bundling or contractual arrangements, and proactive engagement with distribution partners. The report provides analytical frameworks to evaluate pricing sensitivity, model margin scenarios, and identify where formulation differentiation or market-specific positioning can preserve value.
What the Full Research Delivers
While the macro trajectory, competitive dynamics, and structural forces outlined above establish the strategic backdrop, the complete Worldwide Paroxetine Market study translates this context into a granular, execution-ready intelligence package. The report is structured to support cross-functional decision-making, offering both high-level strategic synthesis and detailed operational segmentation.
Key components of the research include:
- Historical Performance Reconstruction: A year-by-year analysis tracing revenue evolution, demand patterns, and pricing behavior across the base period, enabling stakeholders to identify inflection points, validate internal forecasts, and benchmark organizational performance against market-wide trends.
- Forward Forecast Modeling: Multi-year projections extending through the end of the decade, constructed using rigorous demand-driver analysis, regulatory pathway assessment, and pricing trajectory modeling. These forecasts are designed to support capacity planning, investment prioritization, and scenario-based strategic planning.
- Segmentation and Application Mapping: Detailed breakdowns that illuminate how demand distributes across therapeutic applications, formulation types, and regional markets. These analyses help commercial teams identify high-growth pockets, evaluate formulary positioning opportunities, and tailor market access strategies to local prescribing behaviors and reimbursement environments.
- Competitive Intelligence and Benchmarking: Entity-level profiles that examine commercial positioning, formulation portfolios, regulatory footprints, and strategic initiatives. The analysis highlights competitive advantages, vulnerability points, and likely market share movement, enabling organizations to calibrate their own strategic responses with precision.
- Strategic Recommendations and Decision Frameworks: Actionable guidance tailored to distinct stakeholder objectives, whether the priority is market entry, portfolio expansion, supply chain optimization, pricing strategy refinement, or partnership evaluation. Each recommendation is grounded in the underlying data architecture and designed for direct integration into planning workflows.
The full dataset preserves the analytical granularity required for operational execution, including region-specific demand dynamics, formulation-level market sizing, application-level revenue distribution, and proprietary concentration metrics. These elements are deliberately reserved for the complete report to ensure that stakeholders who require execution-grade intelligence can access the full analytical architecture without compromise.
Why 2026 Decision-Making Depends on This Intelligence
As organizations finalize their strategic roadmaps for 2026, the paroxetine market presents a familiar paradox: stable clinical demand coexists with relentless competitive and pricing pressure, while regulatory and supply chain variables continue to introduce ambiguity. Navigating this environment successfully requires more than high-level trend awareness. It demands precise visibility into where growth is concentrating, how competitive positions are shifting, which formulation and regional segments offer the most favorable risk-reward profiles, and how pricing and procurement dynamics are likely to evolve as generic penetration deepens and supply chains recalibrate.
The Worldwide Paroxetine Market research study is built to meet this requirement. By integrating historical performance, forward-looking forecasts, competitive benchmarking, and structural market analysis into a single cohesive framework, the report equips executives, commercial leaders, and investment professionals with the evidence base needed to make confident, timely decisions. Whether the objective is to defend existing market position, identify high-potential expansion avenues, optimize supply chain resilience, or refine pricing and procurement strategies, the research provides the analytical foundation necessary to act with precision.
For teams preparing for 2026 planning cycles, the strategic window to align market intelligence with execution planning is narrow. Access the complete Worldwide Paroxetine Market study to unlock full segmentation data, detailed competitor analysis, scenario-modeling tools, and the operational insights required to translate market structure into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Paroxetine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com