

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Reports Worldwide Anorectal Manometry Devices Market to Reach $339.21 Million by 2030

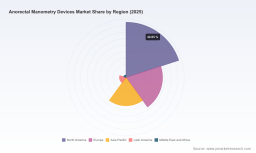
Strategic Outlook: The Worldwide Anorectal Manometry Devices Market (2026–2032)
Setting the Stage for Precision GI Diagnostics
As gastrointestinal motility disorders continue to present diagnostic challenges across global healthcare systems, anorectal manometry has emerged as a critical tool for evaluating pelvic floor function, defecatory disorders, and fecal incontinence. The clinical imperative for standardized, high-fidelity pressure mapping is now intersecting with a rapidly evolving regulatory landscape, updated reimbursement frameworks, and the commercialization of portable and disposable diagnostic platforms. This confluence of clinical, regulatory, and technological forces is reshaping procurement strategies, product positioning, and capital allocation for manufacturers and end-user institutions alike.
Our latest Worldwide Anorectal Manometry Devices Market study is designed for executives who need to navigate this complexity with quantitative rigor and scenario-ready strategic frameworks. Rather than offering static snapshots, the analysis is structured to inform 2026 operational decisions, pipeline prioritization, pricing strategies, and market-entry timing. The market's growth trajectory reflects a maturation from conventional diagnostic setups toward high-resolution, software-integrated, and increasingly decentralized testing environments. Understanding where value is created—and where margin pressure, regulatory friction, or reimbursement shifts may emerge—requires a market intelligence foundation that goes beyond aggregated sizing.
Market Trajectory and Growth Architecture
The global anorectal manometry devices market has demonstrated consistent expansion across the historical review period, driven by rising disease awareness, broader adoption of standardized manometry protocols, and incremental replacement cycles in hospital-based gastroenterology departments. Current baseline sizing reflects a market that has already crossed a meaningful adoption threshold, with forward estimates indicating continued value expansion through the end of the forecast horizon. The overall market is projected to advance from mid-2020s levels toward an estimated trajectory that underscores both volume-driven growth and the premiumization effect associated with higher-resolution, software-enabled systems.
At the core of this outlook is a forecast-period CAGR of approximately 5.95%, signaling a market that is not merely expanding in absolute terms but also experiencing structural shifts in product mix and purchasing behavior. Revenue growth is being shaped by several concurrent dynamics: the transition from legacy systems to high-resolution platforms, increasing procedure volumes in specialized pelvic floor centers, and the gradual penetration of portable, office-based diagnostic devices into ambulatory care settings. These forces create a growth profile that is less dependent on single-market volume spikes and more tied to workflow modernization across a diversified end-user base.
Importantly, the 2026–2032 forecast window captures a phase in which reimbursement realignment, regulatory clarity, and protocol standardization are likely to influence purchasing cadence more directly than in prior years. The market's growth path is therefore best interpreted not as a single linear curve, but as a composite of differing adoption speeds across product categories, clinical settings, and geographic adoption corridors. For strategists, this means that top-line potential must be assessed alongside the operational realities of which segments are scaling fastest, which are constrained by procurement complexity, and where competitive crowding may compress pricing leverage.
Segmentation Logic, Competitive Positioning, and Value Migration
The market's internal architecture is defined by a clear divergence between high-resolution platforms and legacy alternatives. High-resolution manometry systems represent the dominant share of market value, reflecting their alignment with contemporary diagnostic protocols and their perceived clinical utility in capturing detailed pressure topographs for the rectum and anal sphincter. Conventional systems remain part of the landscape, particularly in cost-sensitive procurement environments or facilities with existing installed bases, but their relative contribution is increasingly shaped by replacement cycles rather than greenfield adoption. Solid-state systems add another layer of differentiation, offering specialized sensing characteristics that appeal to specific diagnostic workflows and institutional preferences.
Worldwide Anorectal Manometry Devices Market
End-user demand is similarly stratified. Hospitals continue to anchor the largest portion of device utilization, given their role in complex diagnostic workups, surgical evaluation, and multidisciplinary pelvic floor programs. Diagnostic centers contribute a substantial secondary demand pool, often driven by higher-throughput testing models and focused GI assessment services. Specialty clinics represent a strategically important growth vector, particularly as office-based diagnostics and biofeedback therapy models expand the scope of where and how manometry is performed. Each of these end-user environments carries different procurement cycles, evaluation criteria, clinical priorities, and service expectations, meaning that competitive advantage increasingly depends on matching product architecture to workflow realities rather than competing solely on sensor count or hardware specifications.
On the competitive front, the landscape is populated by specialists and broader gastrointestinal technology vendors whose product strategies reflect differing philosophies around clinical precision, portability, disposability, and software integration. Laborie Medical Technologies has advanced a strong high-resolution portfolio, including both fixed and compact system configurations, alongside what is recognized as the first disposable high-resolution anorectal manometry catheter designed for measuring static and dynamic pressures in the lower GI tract, aligned with IAWG protocol and London classification. Medtronic continues to emphasize advanced pressure sensing architectures, including three-dimensional probe designs offering extensive measurement points for assessment of rectal and anal sphincter pressures. Medspira has positioned its portable platform for office-based diagnostics and pelvic floor biofeedback therapy, with a design emphasis on expedited procedures and minimized patient contact. Diversatek Healthcare supports pelvic floor evaluation through high-resolution probes with multidirectional and circumferential capabilities, paired with dedicated software and support for EMG and balloon expulsion testing.
In parallel, regional and specialized manufacturers such as Alacer Biomédica, THD Lab, The Prometheus Group, HC Italia, and Medica S.p.A. illustrate how product differentiation can be built around channel count, exam-time efficiency, portability, ambulatory recording, and combined modalities like simultaneous surface electromyography. This breadth of approaches underscores an important strategic reality: the market is no longer defined by a single winning technical paradigm, but by multiple viable combinations of clinical accuracy, operational convenience, and total cost of ownership. Companies that can align their offerings with the right clinical justification, regulatory basis, and reimbursement pathway are better positioned to capture sustained share in a fragmented but consolidating environment.
Recent commercial and regulatory milestones reinforce the pace of change. In early 2025, FDA 510(k) clearance was granted to the Fecobionics Anorectal System as substantially equivalent to a recognized portable anorectal manometry device, signaling continued regulatory acceptance for novel portable approaches to pelvic floor evaluation in patients with constipation or fecal incontinence. This follows earlier clearance activity and product introductions from Laborie, including the launch of a compact system and the first disposable HRAM catheter aimed at enhanced diagnostics of defecatory disorders and pelvic floor dysfunction, as well as separate FDA clearance events for its anorectal catheter as a Class II device. These developments are not isolated product announcements; they represent the visible edge of a broader shift toward streamlined procedure workflows, improved infection-control economics, and broader access to standardized manometry outside traditional hospital environments.
Regulatory, Reimbursement, and Standards-Driven Dynamics
The operational environment for anorectal manometry devices is being shaped by a set of overlapping external forces that directly affect market access, adoption timing, and commercial risk. In the United States, anorectal manometry devices are regulated as Class II gastrointestinal motility monitoring systems under 21 CFR 876.1725 with product code KLA, requiring 510(k) clearance for marketing. This regulatory pathway creates a defined but non-trivial barrier to entry and influences the speed at which new probe designs, software configurations, or portable systems can reach procurement-eligible status. For manufacturers, clearance strategy and predicate selection can become as important as hardware performance in determining time-to-market.
Reimbursement dynamics add further nuance. Effective January 1, 2026, CPT codes 91120 and 91122 for anorectal manometry are deleted and replaced by new Category I codes: 91125 for anorectal manometry with rectal sensation and rectal balloon expulsion test, when performed, and 91124 for rectal sensation, tone, and compliance study. This coding transition matters because it can alter documentation requirements, billing workflows, and reimbursement certainty across different care settings. For providers, the change may affect how procedures are coded and justified; for device manufacturers, it can influence the value proposition of systems that support specific test components, streamline coding-aligned documentation, or integrate protocols that map cleanly to the updated code structure.
Standards adoption is another structural driver. High-resolution anorectal manometry systems increasingly incorporate the International Anorectal Physiology Working Group protocol and London classification for measurement and analysis. As clinical expectations converge around these frameworks, devices that natively support standardized interpretation, consistent pressure mapping, and reproducible reporting gain a practical advantage in environments where diagnostic comparability and clinical confidence matter. The combination of regulatory classification, updated reimbursement codes, and protocol standardization means that competitive differentiation will increasingly depend on how well a product is aligned with the real-world administrative and clinical requirements of the testing environment—not merely on technical feature lists.
What the Study Delivers for 2026 Decision-Making
This market research is built to support concrete strategic choices rather than abstract trend commentary. It translates macro growth signals into actionable intelligence across product planning, competitive positioning, geographic expansion, and end-user targeting. The study brings together quantitative market structure, company-level competitive context, recent regulatory and product developments, and the administrative forces shaping adoption. It is designed to help leadership teams answer questions that directly influence near-term action:
- Where is demand and value creation concentrated across product types, end users, and major geographic regions, and how are those concentrations likely to evolve?
- Which product architectures and workflow features are most closely associated with adoption momentum in hospital, diagnostic center, and specialty clinic settings?
- How do recent FDA clearances and product introductions change the competitive baseline, and where do they open opportunities for follow-on innovation or market exit from less defensible positions?
- How do reimbursement code changes and regulatory classification requirements affect commercial planning, pricing logic, and service/enablement requirements?
- Where can manufacturers and distributors anticipate margin pressure, procurement complexity, or adoption barriers, and what strategic responses are available?
The analysis is structured to be portable across internal use cases. Commercial teams can use it to refine segmentation assumptions, prioritize territories, and sharpen value propositions. Product and R&D leaders can benchmark device capabilities against the prevailing competitive set and identify gaps in protocol alignment, portability, disposability, or software functionality. Corporate development and investor-facing teams can use the market structure and concentration data to assess demand durability, competitive dynamics, and the relative defensibility of different business models. Given the degree of concentration observed in the broader competitive environment, understanding who holds share, where that share is derived from, and how quickly new entrants or novel device types can gain traction is central to planning with confidence.
Worldwide Proctoscope Market
Accessing the Full Intelligence Set
The narrative above captures the strategic logic and market architecture behind the Worldwide Anorectal Manometry Devices Market report, but the operational value lies in the deeper quantitative and company-level detail that supports scenario planning and decision execution. The full study provides the specific market sizing evolution, segmentation structures, concentration metrics, competitive company profiles, recent regulatory and product developments, and reimbursement and standards context needed to convert insight into action. For teams preparing 2026 strategies, the complete dataset offers the precision required to validate assumptions, compare end-market opportunities, and align product and commercial roadmaps with the realities of a market that is expanding while also becoming more regulated, more standardized, and more workflow-dependent.
If your objective is to move from directional awareness to executable strategy, the full report provides the structured intelligence necessary to assess where growth will be captured, which competitive positions are most defensible, and how external dynamics will shape adoption across the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Anorectal Manometry Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com