

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Chromium Salt Market to Hit $4.25 Billion by 2032, Growing at 3.15% CAGR

Navigating the Chromium Salt Landscape: Strategic Imperatives for 2026 and Beyond
The worldwide chromium salt market stands at a critical inflection point as it enters 2026. With a historical revenue trajectory that saw the market grow from approximately USD 2.81 billion in 2020 to an estimated USD 3.42 billion in 2025, the sector has demonstrated resilience amid fluctuating raw material costs, evolving regulatory frameworks, and shifting industrial demand patterns. Projections extending through 2032 indicate a steady expansion path, anchored by a compound annual growth rate of 3.15 percent, which would lift market value to roughly USD 4.25 billion by the end of the forecast period. For executives, procurement leaders, and strategic planners, this growth narrative is not merely a macroeconomic signal. It is a call to recalibrate supply chain architectures, anticipate regulatory headwinds, and position portfolios against the structural shifts reshaping chromium chemistry applications across multiple end-use sectors.
Worldwide Chromium Salt Market
PW Consulting latest Worldwide Chromium Salt Market study is designed to translate this complexity into executable intelligence. The report does not simply present top-line figures; it deconstructs the mechanics of growth, maps the competitive fault lines, and equips decision-makers with the granular visibility required to act decisively in a market where concentration, capacity dynamics, and compliance risk intersect.
Macro Foundations: Reading the Numbers Strategically
The historical record from 2020 through 2025 reveals a market that has navigated volatility without losing its long-term upward orientation. After reaching a near-term peak in 2024 at USD 3.47 billion, the 2025 figure of USD 3.42 billion reflects a modest consolidation that analysts attribute to a combination of inventory normalization, price moderation in certain chemical intermediates, and cautious downstream purchasing across key industrial verticals. Looking forward, the forecast window from 2026 to 2032 outlines a market that regains momentum, with annual revenues climbing from an estimated USD 3.54 billion in 2026 to USD 4.25 billion in 2032. This trajectory is not linear; it is shaped by periodic capacity additions, raw material availability cycles, and the pace at which downstream industries adopt alternative chemistries or reformulate existing processes.
For 2026 planning, the strategic implication is clear. Growth will be earned through structural advantages rather than broad market tailwinds alone. Firms that understand where demand is structurally sticky, where substitution risk is real, and how regional supply dynamics affect landed costs will be best positioned to capture value. The study unpacks these dynamics without oversimplifying them, offering a calibrated view of how volume, price, and mix interact across the forecast horizon.
The Anatomy of Demand: Sector-Level Forces at Play
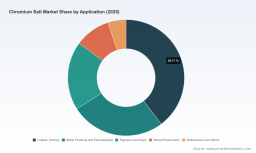
Chromium salts permeate a diverse set of industrial applications, each with distinct growth drivers, cost sensitivities, and regulatory exposure. Leather tanning remains a foundational demand pocket, supported by continued processing needs in established markets and selective growth in emerging manufacturing hubs. Metal finishing and electroplating constitute another significant pillar, where chromium-based compounds are valued for corrosion resistance, aesthetic finish, and functional performance in automotive, aerospace, and industrial equipment supply chains. Pigments and dyes represent a more specialized but stable demand stream, while wood preservation and refractories-and-others categories reflect niche but durable consumption patterns tied to infrastructure, construction, and industrial maintenance cycles.
What matters for strategy is not the relative size of each application in isolation, but the interplay between them. Some segments are increasingly scrutinized under environmental and occupational health regulations, prompting reformulation efforts and process changes that can reshape procurement specifications over time. Other segments are benefiting from capacity expansions and downstream investment that sustain volume growth even as price competition intensifies. The report provides a detailed application-level mapping that links demand behavior to operational planning, helping clients anticipate where specification changes, supplier diversification, or alternate chemistry adoption may alter sourcing strategies in the coming years.
Geography, Supply Concentration, and the Raw Material Backdrop
The geographic distribution of chromium salt demand and supply is inseparable from the broader chromium value chain. Chromite ore availability, processing capacity, and logistics infrastructure all influence the cost base and reliability of supply for downstream salt producers. In 2025, global chromite ore mine production was estimated to have risen by roughly 3 percent year-over-year, with South Africa continuing to dominate output. This concentration matters because it creates both pricing leverage and vulnerability: any disruption in key producing regions can ripple through the value chain, affecting intermediate chemistry costs and, ultimately, the economics of chromium salt manufacturing.
Sodium Dichromate Market
Early 2026 market observations point to upward pressure on chrome ore prices, with South African concentrate quotations holding in a range that reflects tight availability and steady demand from ferrochrome and chemical processing sectors. These raw material conditions set the tone for the operating environment in which chromium salt producers must manage margins, negotiate contracts, and decide on inventory positioning. The study integrates these upstream signals into its market analysis, ensuring that forecasts and strategic recommendations are grounded in the cost realities that shape producer behavior and buyer negotiations.
At the same time, regional demand patterns are evolving. Asia Pacific remains a central axis of activity, supported by manufacturing scale, chemical processing depth, and expanding industrial consumption. Europe and North America continue to represent mature but high-value demand environments, where regulatory compliance, quality expectations, and specialty grade requirements often command different pricing and service dynamics than bulk-oriented markets. Latin America and the Middle East and Africa contribute more targeted demand pockets, often linked to specific industrial clusters, infrastructure projects, or regional processing capabilities. The report examines these regional nuances in a way that supports market entry decisions, export-import strategy, and supplier selection without reducing complex local conditions to oversimplified rankings.
Regulatory Momentum: The Chromium VI Question
No discussion of chromium salt strategy in 2026 is complete without addressing the regulatory trajectory surrounding hexavalent chromium. European Union institutions have been advancing discussions that could lead to a horizontal restriction on certain Cr(VI) compounds, with updated Q&A documents from the European Commission in December 2025 signaling accelerated movement toward potential legal entry between end-2027 and beginning-2028. Earlier in 2025, ECHA concluded that an EU-wide restriction on select hexavalent chromium substances is justified based on occupational health risks, reinforcing the regulatory direction.
These developments do not merely affect compliance documentation. They influence product design, customer specifications, substitution timelines, and the relative attractiveness of different chromium salt grades and derivatives. For companies operating in or supplying into European markets, the timeline creates both risk and opportunity: risk for products and processes that face tighter use conditions, and opportunity for those that can offer compliant alternatives, demonstrate robust stewardship, or support customers through transition pathways. The study evaluates the regulatory landscape with enough depth to help clients model scenario impacts, prioritize portfolio adjustments, and align commercial messaging with the compliance expectations of downstream buyers.
Competitive Chessboard: Who Shapes the Market and How
The worldwide chromium salt market is characterized by a mix of large-scale producers, regional specialists, and high-purity or specialty-focused suppliers. Consolidated presence is notable, with the top three competitors collectively accounting for an estimated 48.5 percent of market revenue and the top five reaching approximately 62.35 percent. This concentration means that a relatively small number of players exert meaningful influence over pricing norms, capacity availability, and product standards in key segments.
Among the globally active names, Lanxess AG remains a major producer of chromium salts and chrome chemicals, with a portfolio that includes basic chrome sulfate for leather tanning and other industrial uses. In India, Vishnu Chemicals Limited has built a leading position in chromium chemicals, with significant sodium dichromate capacity and a clear expansion trajectory; the company has outlined plans to increase sodium dichromate capacity from 80ktpa toward 100ktpa by the first half of fiscal 2026, reflecting confidence in downstream demand and derivative growth. In China, Hubei Zhenhua Chemical stands out as a major chromium salt producer and one of the world largest manufacturers of chromium chemicals, with ongoing capacity expansions and acquisition activity that extend its footprint across the value chain. In late 2025, the company advanced price adjustments on metal chromium and moved forward with restructuring and acquisition efforts that add meaningful chromium salt capacity, signaling a push to strengthen scale and integration.
Turkey contribution is represented by Soda Sanayii A.S., which has brought new production lines for chromium chemicals into the market, while Japan supply-side presence includes Nippon Chemical Industrial Co., Ltd., a manufacturer of chromium compounds and related specialty chemicals. In the United Kingdom context, Elementis plc formerly held a leading position in sodium dichromate, chromic acid, and chrome sulfate across the Americas before divesting its chromium business in 2023, an episode that illustrates how portfolio strategy and asset reallocation continue to reshape the competitive map. Other notable participants include American Elements, which supplies high-purity chromium salts for research, electronics, and industrial applications; Merck KGaA, a global source of laboratory and high-purity chromium reagents; Sichuan Yinhe Chemical, with a recognized presence in bulk chromium chemicals; and regional producers such as MidUral Group in Russia, Aktyubinsk Chromium Chemicals Plant in Kazakhstan, Oxkem Ltd in the United Kingdom, and Chemetall GmbH, associated with BASF, which supplies chromium-based surface treatment chemicals and salts.
Capacity dynamics remain a critical competitive variable. In the United States, plans have emerged for a new chromium metal plant in New Castle, Pennsylvania, targeting a startup in the first quarter of 2026 with capacity up to 6,500 MT per year, potentially positioning it as the first U.S. producer of its kind. While this development sits upstream of chromium salt production, it signals how regional supply chain autonomy, cost management, and strategic resilience are driving investment decisions that can indirectly influence the broader chromium ecosystem. The report analyzes these competitive moves in a structured way, linking capacity announcements, pricing behavior, M&A activity, and product portfolio shifts to their likely effects on market equilibrium and buyer options.
What the Study Delivers: Operational Intelligence, Not Just Headlines
PW Consulting Worldwide Chromium Salt Market study is built to serve as a working document for strategy, sales, procurement, and investment teams. It goes beyond aggregate market sizing to provide a structured, decision-ready view of the market architecture. The report includes detailed segmentation analysis across type, application, and region, enabling clients to isolate the pockets of growth, the segments facing substitution or regulatory pressure, and the geographies where supply-demand balances are tightening or loosening.
The study also examines market concentration and competitive positioning with enough granularity to support benchmarking, partnership evaluation, and competitive response planning. Company profiles, recent developments, and capacity-related developments are contextualized within the larger market logic, helping readers distinguish between one-off events and structural trends. Raw material dynamics are integrated into the analysis so that forecasts and strategic commentary reflect the cost environment that producers and buyers actually face. Regulatory developments are assessed not as abstract policy news but as variables that can alter specification requirements, product viability, and regional demand patterns over the forecast period.
Importantly, the report is designed to support scenario thinking. Because the chromium salt market is influenced by commodity cycles, regulatory timing, and capacity lead times, a single-point forecast is insufficient for robust planning. The study provides the analytical framework needed to test assumptions about price direction, volume growth, regional availability, and compliance-driven demand shift, giving teams a more reliable basis for budgeting, sourcing, and investment prioritization.
Why This Study Matters for 2026 Decisions
As organizations move into 2026, the cost of ambiguity in the chromium salt market is rising. Raw material conditions are dynamic, regulatory timelines are narrowing, and competitive capacity actions are altering the supply landscape. In this environment, decisions about supplier relationships, inventory strategy, product mix, and geographic focus need to be informed by evidence that connects market structure to operational consequences.
The PW Consulting study is intended to reduce that ambiguity. It helps clients answer practical questions: Where is demand most resilient, and where is it most exposed to substitution or regulation? Which competitors are expanding, consolidating, or exiting, and what does that mean for supply security and pricing? How should procurement teams think about contract timing in a market where raw material availability and regional concentration create both risk and negotiation leverage? Which application segments offer the strongest growth logic, and which require a more cautious, transition-aware approach?
By combining macro trajectory, segmentation insight, competitive intelligence, and regulatory context in a single integrated analysis, the report aims to give decision-makers a clearer line of sight from market data to strategic action. That clarity is especially valuable when preparing for periods of change, whether those changes come from new capacity entering the market, shifting compliance requirements, or evolving downstream demand patterns.
Looking Ahead: Positioning for the Rest of the Decade
The forecast period through 2032 suggests a market that grows at a measured but persistent pace, reaching an estimated USD 4.25 billion by the end of the window. Yet the path to that outcome will be shaped by decisions made now. Capacity expansions, raw material availability, regulatory finalization, and downstream reformulation efforts will all influence which companies capture share, which applications remain core, and which regions become more or less central to the market architecture.
For executives and analysts who need to move beyond general market narratives and into specific, evidence-based planning, the Worldwide Chromium Salt Market study offers a comprehensive foundation. It is designed to support the next round of strategic choices with the depth, structure, and commercial relevance required to act confidently in a market where the details determine the outcome.
To access the full segmentation detail, competitive benchmarking, regional analyses, and scenario-based forecasts that underpin this outlook, we invite you to explore the complete study on the PW Consulting website. The report provides the full intelligence architecture behind the trends summarized here, enabling teams to translate market visibility into operational advantage throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Chromium Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com