

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aerospace Glass Cockpit Market Hits $4.85B in 2025, Projected $6.92B by 2032 at 5.19% CAGR

Global Aerospace Glass Cockpit Displays: Strategic Market Intelligence for 2026 Decision-Makers
The aviation industry is currently undergoing a profound technological transformation, driven by the relentless adoption of glass cockpit architecture across all flight regimes. As legacy analog instrumentation gives way to advanced digital interfaces, the market for aerospace glass cockpit displays has established itself as a critical nexus of avionics innovation, supply chain complexity, and strategic investment. For executives, procurement leaders, and technology strategists operating within the aerospace sector, understanding the trajectory of this market is no longer optional—it is a prerequisite for informed decision-making. This article serves as a strategic preview of our latest comprehensive research, Worldwide Glass Cockpit Displays for Aerospace Market , designed to equip stakeholders with the macroscopic intelligence required to navigate the opportunities and risks defining the 2026 to 2032 forecast period.
The transition toward integrated digital flight decks is accelerating, fueled by demands for enhanced situational awareness, reduced pilot workload, and improved safety margins. However, this transition is not occurring in a vacuum. Current industry data highlights significant headwinds and structural shifts that are reshaping bandwidth for growth. For instance, recent supply chain analysis indicates that global semiconductor shortages have historically impacted display panel availability, delaying aircraft deliveries and retrofit programs by an average of six to nine months as of 2025 data. Furthermore, tariff policies imposed in 2025 have introduced new friction into global supply chains for avionics components. These geopolitical and logistical pressures are prompting accelerated localization of critical subassembly production closer to major aircraft assembly hubs to mitigate lead-time volatility. Simultaneously, cost structures remain under intense scrutiny; display modules account for a significant portion of total cockpit display cost, with driver chips, PCBs, and structural components making up a combined majority of expenses, while raw materials exceed sixty percent of total costs. These dynamics underscore the necessity of a report that goes beyond surface-level growth projections to examine the underlying mechanics of the market.
Market Trajectory and Growth Outlook
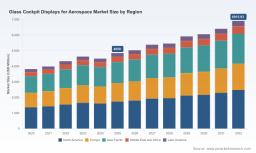
Our analysis frames the market using a robust historical baseline spanning from 2020 through 2025, projecting forward into the forecast period ending in 2032. The data reveals a resilient upward trajectory despite the aforementioned supply chain disruptions. The market generated revenue of approximately 4,850 USD Million in 2025, reflecting recovery and growth following fluctuations observed in the mid-2020s. Moving into the forecast horizon, the market is expected to expand, with revenue projections reaching nearly 6,916 USD Million by 2032.
This growth is underpinned by a compound annual growth rate that signals steady expansion for industry participants. The forecast period suggests a CAGR of 5.19 percent, indicating a market that is maturing but still possesses significant capacity for value creation. This trajectory is critical for capacity planning and investment allocation. For stakeholders evaluating long-term portfolio positioning, the inflection points between 2026 and 2028 show incremental gains, while the period toward 2032 suggests an acceleration in value capture as next-generation platforms enter service and retrofit cycles deepen. The historical data from 2020 to 2025 also provides a stress-tested view of market resilience, showing how the industry navigated the post-pandemic recovery and supply chain constraints to reach the 2025 baseline.
Unit economics also play a pivotal role in understanding the market scale. Global cockpit display unit sales reached 309,000 units in 2025, with an average price of USD 20,493 per unit. These metrics offer a high-level view of volume and pricing power, helping organizations benchmark their own product strategies against market averages without revealing sensitive granular breakdowns. Understanding the interplay between unit volume and average selling price is essential for modeling revenue streams and assessing the potential impact of cost pressures on margins.
Segmentation and Application Dynamics
The market is composed of diverse aircraft platforms and display technologies, each presenting unique value propositions and adoption curves. Our research dissects the market landscape across multiple dimensions, including aircraft type and display technology, to provide a holistic view of where value is being generated. In terms of aircraft platforms, the ecosystem encompasses commercial aviation, military operations, general aviation, and helicopter operations. Each segment faces distinct operational requirements and procurement cycles.
The commercial aviation sector remains a cornerstone of demand, driven by fleet modernization programs and new aircraft deliveries. Military aircraft continue to represent a substantial portion of the market, fueled by defense modernization initiatives and the need for advanced situational awareness in complex threat environments. General aviation and helicopters also contribute significantly, with increasing adoption of avionics upgrades in existing fleets to extend operational life and enhance safety capabilities. While specific regional revenue splits are detailed in the full report, it is noteworthy that the global market distribution reflects the concentration of aircraft manufacturing and operational hubs across North America, Europe, Asia Pacific, and emerging regions in the Middle East, Africa, and Latin America.
From a technology perspective, the market is segmented into primary flight displays, multi-function displays, and engine instrument and crew alerting systems. Primary flight displays remain central to flight safety, providing critical attitude, airspeed, and altitude information. Multi-function displays offer flexibility and information density, supporting navigation, systems management, and communication tasks. Engine instrument and crew alerting systems are vital for monitoring aircraft health and ensuring timely crew response to anomalies. The integration of these display types into cohesive glass cockpit architectures is a key trend, with manufacturers increasingly offering integrated suites that reduce weight, wiring complexity, and maintenance overhead. The report provides a detailed mapping of these technology segments to aircraft platforms, enabling stakeholders to identify cross-selling opportunities and technology migration paths.
Competitive Landscape and Strategic Positioning
The competitive environment for glass cockpit displays is characterized by a mix of established aerospace giants, specialized avionics manufacturers, and emerging innovators. Market concentration analysis indicates that the top three companies hold a combined market share of 58.4 percent, while the top five players account for 72.15 percent of the market. This concentration suggests a landscape where scale, certification capabilities, and long-term customer relationships are significant barriers to entry, yet also highlights the importance of niche players who can offer specialized solutions or cost-effective alternatives.
Collins Aerospace (RTX) continues to be a dominant force, providing integrated cockpit solutions that include large-format LCD displays and Flight2 integrated avionics. Their portfolio spans advanced displays for both military and commercial aircraft, with notable retrofit capabilities for platforms like the Boeing 757 and 767, as well as Pro Line 21 systems that deliver crystal-clear LCDs for enhanced situational awareness. Honeywell Aerospace remains a critical supplier of cockpit and flight displays, offering a range of LCD units such as the CMA-6800, DU-1080, DU-1310, and DU-875. Their focus on Primus Elite upgrades and multi-function displays for business aviation, commercial helicopters, and Primus Epic platforms underscores their commitment to improving visibility and operational flexibility across diverse aircraft types.
Thales Group offers sophisticated cockpit interactive display units, including the FlytX tactile large display flight deck systems. These systems feature customizable tactile interfaces and are supplied to major airframe manufacturers including Airbus, ATR, Bombardier, Dassault, and Airbus Helicopters, positioning Thales at the forefront of next-generation flight deck ergonomics. Garmin Ltd. delivers comprehensive glass flight deck solutions, including the G1000 NXi, G5000, G3000H, and TXi touchscreen displays. Their G3X Touch systems support Part 23 turbine, defense, advanced air mobility, helicopters, and general aviation retrofit and forward-fit applications, demonstrating their broad reach across civilian and specialized aviation sectors.
Aspen Avionics specializes in Evolution Flight Display systems, such as the EFD1000 Pro MAX, targeting fixed-wing aircraft, helicopters, and Class III aircraft. Their focus on affordable, certified glass cockpit solutions makes them a key player in the general aviation segment. ScioTeq manufactures rugged DAL-A certified video displays and display computers, including the RDU-3068 and RDU-4208 series, which are utilized in civil and defense applications ranging from trainers to air-to-air refueling and next-gen avionics. Astronautics Corporation of America provides diversified smart displays with embedded processing, supporting civil and military transports, trainers, fighters, helicopters, and special mission aircraft. Elbit Systems Ltd. supplies advanced cockpit display systems and avionics for military and commercial aerospace applications, while Mercury Systems offers custom rugged safety-certifiable active matrix LCD modules up to DAL-A for primary and multi-function displays.
Recent developments in the competitive landscape have been dynamic. In March 2026, ScioTeq and Kongsberg Defence & Aerospace signed a Letter of Intent for collaboration on resilient European air defense initiatives involving avionics displays. Similarly, ScioTeq was selected to provide a certified visualization and control solution using the RDU-3068 and PU-5200 display computer for an Air-to-Air Refueling system. In February 2026, ScioTeq's RDU-3068 advanced display was selected as the PFD and MFD for the PC-7 MKX Smart Basic Trainer aircraft, highlighting the penetration of specialized display technologies into training platforms. Additionally, Nighthawk Flight Systems unveiled Guardian, a new modular glass cockpit system for Part 23 aircraft with certification expected in July 2026 and plans for expansion to Part 27 rotorcraft. These events illustrate the active innovation cycle and the strategic partnerships shaping the market's evolution.
Strategic Imperatives for 2026 and Beyond
For enterprise leaders, the insights contained in the Worldwide Glass Cockpit Displays for Aerospace Market report translate into actionable strategic imperatives. First, supply chain resilience must be a top priority. With raw materials constituting over sixty percent of total costs and semiconductor constraints historically causing delivery delays of six to nine months, organizations must evaluate supplier diversification, inventory buffering strategies, and the feasibility of localized assembly as suggested by recent tariff-induced friction.
Second, segmentation strategy requires precision. The distinct growth profiles of commercial, military, general aviation, and helicopter segments necessitate tailored go-to-market approaches. Companies must assess which combination of display types—primary, multi-function, or alerting systems—aligns best with their target audience's operational needs and certification timelines. The report's detailed mapping of these segments allows for the identification of underserved niches and potential consolidation opportunities.
Third, competitive positioning must account for market concentration. With the top five players controlling nearly three-quarters of the market, new entrants or smaller players must define clear value propositions, whether through cost efficiency, specialized certification capabilities, or innovation in display ergonomics and tactile interfaces as seen with Thales and Nighthawk. Monitoring the recent contract awards and product launches of key competitors provides early warning signals of shifting alliances and technology preferences.
Worldwide Glass Cockpit Displays for Aerospace Market
Finally, investment in next-generation capabilities is essential. The demand for DAL-A certified rugged displays, tactile interfaces, and modular systems indicates a market trend toward higher integration and safety-critical performance. Organizations should align their R&D roadmaps with these technological vectors to capture long-term value as the market approaches the 2032 horizon.
Worldwide Aircraft Windows Market
Conclusion and Access to Full Intelligence
The aerospace glass cockpit displays market is poised for sustained growth, driven by technological advancement, fleet modernization, and evolving operational requirements. However, realizing the value of this growth requires a nuanced understanding of supply chain dynamics, segmentation nuances, and competitive moats. The information provided here offers a high-level strategic overview, highlighting the macroeconomic trajectory, key industry players, and recent developments that define the current landscape.
To move from broad awareness to precise decision-making, stakeholders require the granular data, detailed forecasts, and exhaustive segmentation analysis available in our full market research. The complete report includes specific regional revenue breakdowns, aircraft type splits, display technology shares, and comprehensive company profiles that are essential for crafting detailed business plans and investment theses. We invite you to access the full Worldwide Glass Cockpit Displays for Aerospace Market research to unlock the complete intelligence package and ensure your organization is strategically positioned for the opportunities of 2026 and the decade beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Cockpit Displays for Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com