

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: N-Allylamine Market Hits $52.4M in 2025, Expands to $74.3M by 2032 with 5.12% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence in the Global N-Allylamine Market: Navigating Growth Trajectories Through 2032
Executive Overview
The global chemical supply chain continues to evolve under the pressure of regulatory tightening, pharmaceutical pipeline expansion, and advanced material demand. Within this landscape, N-Allylamine (CAS 107-11-9) has emerged as a critical intermediate whose consumption patterns offer a reliable barometer for downstream industrial health. This analysis introduces PW Consulting's comprehensive Worldwide N-Allylamine Market research, a foundational intelligence asset designed to equip executive leadership, procurement directors, and strategy teams with the structural clarity needed to make high-stakes decisions in 2026 and beyond.
The study is built on a rigorous historical baseline spanning 2020 through 2025, with a forward-looking forecast horizon extending to 2032. By anchoring strategic conversations in quantified market behavior rather than anecdotal industry noise, the report enables organizations to calibrate capacity planning, evaluate supplier resilience, and anticipate pricing architecture shifts before they materialize in quarterly earnings.
Macro Market Trajectory: A Decade of Structural Expansion
Over the historical evaluation window, the worldwide N-Allylamine market has demonstrated consistent revenue growth, transitioning from a baseline of approximately 40.96 million USD in 2020 to an estimated 52.4 million USD by 2025. This progression reflects steady absorption across chemical synthesis verticals, supported by incremental capacity expansions and shifting formulation requirements in high-value end-use sectors.
The forecast period projects continued upward momentum, with the market expected to reach 57.5 million USD in 2026 and advance toward 74.32 million USD by 2032. This expansion is underpinned by a compound annual growth rate of 5.12 percent across the 2026 to 2032 forecast window. While the trajectory indicates durable demand, it also reveals the kind of nuanced inflection points that only granular, multi-variable analysis can properly contextualize. Year-over-year transitions are rarely linear; regulatory adjustments, feedstock availability, and regional capacity utilization all introduce volatility that executives must parse with precision.
The revenue architecture captured in this study is deliberately structured to move decision-makers beyond headline figures. Instead of treating market size as a static number, the analysis decomposes growth drivers into actionable intelligence layers, allowing teams to model scenario-based outcomes for procurement timing, inventory buffering, and partnership structuring.
The 2026 Decision Lens: Why This Research Matters Now
As organizations enter 2026, strategic planning cycles are increasingly shaped by three overlapping imperatives: supply chain redundancy, regulatory compliance readiness, and margin preservation amid fluctuating input costs. N-Allylamine sits at the intersection of these pressures. It serves as a functional building block in pharmaceutical intermediate synthesis, water treatment chemical formulations, polymer development, and agrochemical production. Any disruption or pricing recalibration in this molecule cascades quickly into downstream cost structures.
PW Consulting's research is engineered to convert this complexity into executable strategy. Rather than offering generic commentary, the report maps the structural forces that will define procurement and investment choices throughout the forecast horizon. Executive teams will gain visibility into how purity specifications are reshaping buyer preferences, how regional capacity distributions are influencing logistics risk, and how application-specific demand cycles are likely to evolve under diverging regulatory frameworks.
The strategic value of the study lies in its operational granularity. It is designed not merely to inform leadership about where the market has been, but to equip cross-functional teams with the frameworks needed to evaluate supplier contracts, assess geographic sourcing trade-offs, and align R&D roadmaps with realistic supply availability.
What the Report Delivers: Actionable Intelligence Architecture
The research package is structured to support multiple internal use cases, from board-level market entry evaluations to tactical procurement scheduling. The analytical framework encompasses several core deliverables:
- Historical and forecast revenue mapping that traces market evolution from 2020 through 2032, enabling trend validation and forward modeling
- Demand segmentation analysis that disaggregates consumption behavior across purity thresholds and application categories, highlighting where specification upgrades are driving commercial trade-offs
- Regional market distribution profiling that outlines how geographic absorption patterns differ across major economic zones, providing context for sourcing diversification and logistics strategy
- Competitive positioning evaluation that examines supplier capabilities, product grade availability, and channel reach across established global and regional manufacturers
- Strategic scenario guidance that helps organizations interpret growth variability and prepare for demand cyclicality without relying on static point estimates
Each section is built to function independently or as part of an integrated decision-support workflow. Procurement teams can isolate specification-driven demand behaviors, while strategy groups can leverage regional distribution insights to evaluate nearshoring, dual-sourcing, or capacity commitment options. The report's consistency of methodology ensures that disparate internal stakeholders are working from a single, defensible analytical baseline.
Competitive Landscape and Supplier Ecosystem Dynamics
The global N-Allylamine supply environment is defined by a mix of specialized chemical manufacturers, broad-line laboratory suppliers, and regional fine-chemical producers. Market concentration metrics indicate a moderately consolidated landscape, with the top three firms representing a significant share of reported revenue and the top five collectively accounting for the majority of market activity. This concentration has meaningful implications for pricing negotiation leverage, supply continuity planning, and qualification lead times for new procurement relationships.
Tokyo Chemical Industry Co., Ltd. (TCI), headquartered in Tokyo, Japan, maintains an established role in supplying high-purity N-Allylamine for organic synthesis, pharmaceutical intermediates, and polymer-related applications across international markets. Its product positioning emphasizes consistent grade availability for research and industrial-scale synthesis alike.
Merck KGaA, operating through Sigma-Aldrich, provides N-Allylamine at high purity levels in both laboratory and bulk quantities, supporting chemical research, fine chemical production, and broader industrial synthesis requirements. The firm's distribution infrastructure and quality documentation frameworks make it a reference point for buyers with stringent compliance and traceability expectations.
Thermo Fisher Scientific Inc., through its Alfa Aesar portfolio based in Waltham, Massachusetts, offers N-Allylamine at 99 percent purity for laboratory-scale reactions and smaller industrial applications, particularly within pharmaceutical and agrochemical workflows. Its channel reach supports buyers who require responsive availability for R&D and pilot-scale operations.
Capot Chemical Co., Ltd., based in Hangzhou, Zhejiang, China, manufactures and exports N-Allylamine as a fine chemical intermediate targeting global pharmaceutical, agrochemical, and epoxy resin markets. Its production orientation reflects the growing role of regional fine-chemical exporters in fulfilling specification-driven demand across multiple downstream verticals.
The interplay among these suppliers illustrates a broader market reality: procurement strategies must account for differences in scale readiness, purity certification, documentation depth, and geographic fulfillment capability. PW Consulting's analysis dissects these supplier profiles within the context of end-use demand behavior, helping organizations distinguish between nominal product availability and commercially viable supply partnerships.
Structural Demand Layers: Applications and Purity Specifications
One of the most strategically relevant dimensions of the N-Allylamine market is the way demand separates across purity thresholds and application categories. In practice, buyers do not purchase a uniform commodity; they select grades that correspond to specific synthesis tolerances, regulatory documentation needs, and formulation performance targets.
Purity specification is a decisive commercial variable. Higher-purity material typically commands differentiated sourcing considerations, particularly when used in pharmaceutical intermediate pathways or advanced polymer synthesis where impurity thresholds are tightly controlled. Lower-purity grades occupy distinct volume-driven use cases where cost efficiency and bulk availability take priority. The market's composition across these purity segments reflects a bifurcated buyer base, each with its own procurement cadence, supplier qualification standards, and sensitivity to supply continuity.
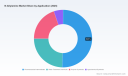
Application-side demand similarly exhibits specialized behavior. Pharmaceutical intermediates represent a substantial share of consumption, driven by ongoing pipeline activity and the need for reliable intermediate supply in regulated manufacturing environments. Water treatment chemicals form another important consumption channel, where operational scale and formulation consistency influence purchasing patterns. Polymer synthesis and agrochemical synthesis contribute additional demand layers, each responding to different innovation cycles and regional production priorities. Smaller application categories further diversify the market footprint, reinforcing the need for a multi-segment analytical lens rather than a single aggregated view.
Worldwide N-Allylamine Market
Because the report refrains from flattening these distinctions into oversimplified aggregates, organizations can identify where specification upgrades, volume shifts, or regional demand migration are likely to alter sourcing requirements. This level of structural clarity is essential when evaluating whether to lock in long-term supply agreements, diversify grade portfolios, or realign manufacturing inputs with forecast demand behavior.
Geographic Distribution and Regional Sourcing Considerations
Regional absorption patterns play a central role in shaping both pricing dynamics and logistics strategy. The market's geographic distribution reveals uneven concentration across major economic zones, reflecting differences in industrial base maturity, chemical manufacturing ecosystem depth, and end-use demand intensity. Asia Pacific represents the largest regional share of market activity, consistent with the scale of fine-chemical production and downstream manufacturing demand located in the region. North America and Europe maintain meaningful consumption footprints, supported by pharmaceutical, research, and specialty chemical applications that prioritize documented purity and compliance-ready supply chains. Latin America and the Middle East and Africa collectively account for smaller shares, though these regions can present evolving opportunities tied to industrial expansion and infrastructure-driven chemical demand.
For procurement leaders, regional distribution is not simply a demographic statistic. It directly affects lead-time planning, freight cost exposure, tariff considerations, and supplier redundancy design. PW Consulting's regional analysis translates these geographic patterns into procurement-relevant insights, allowing organizations to evaluate whether current sourcing maps align with risk tolerance and volume commitments.
Allyl Alcohol Market
Conclusion: Converting Market Intelligence into 2026 Strategy
The Worldwide N-Allylamine Market research from PW Consulting is designed to serve as a decision-grade intelligence asset, not a static market summary. By integrating historical performance, forecast trajectories, purity-driven segmentation, application-specific demand behavior, regional distribution patterns, and competitive supplier dynamics, the study provides a comprehensive foundation for strategic action in 2026 and throughout the forecast period to 2032.
Organizations that rely on aggregate market headlines alone risk misaligning procurement timing, underestimating specification-driven supply constraints, or overlooking regional sourcing trade-offs. A structured, methodology-consistent view of the market enables executive teams to make procurement, investment, and partnership decisions with greater confidence and fewer assumptions.
To access the complete segmentation breakdowns, regional revenue architecture, supplier profiling details, and scenario-based interpretive guidance, readers are encouraged to consult the full PW Consulting market research release. The complete report provides the multi-layered dataset and strategic frameworks necessary to translate market intelligence into executable 2026 planning.
For detailed analysis of this topic, please visit the official page: Worldwide N-Allylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Tissue Sectioning Market to Hit $1,305.28M by 2032, Growing at 6.42% CAGR, Says PW Consulting
By pmarketresearch, 2026-09-16
Navigating the Precision Frontier: Strategic Insights for the Global Tissue Sectioning Market in 2026
In the evolving landscape of histopathology, diagnostics, and life sciences research, the precision of tissue preparation remains a cornerstone of reliable outcomes. As laboratories and pharmaceutical enterprises face mounting pressures to accelerate workflows, reduce reagent consumption, and integrate digital pathology platforms, the tissue sectioning equipment segment stands at a pivotal inflection point. Our latest Worldwide Tissue Sectioning Market study has been engineered to serve as a decision-grade intelligence asset for executives, procurement leaders, and R&D strategists who must navigate the 2026–2032 horizon with clarity. Rather than relying on fragmented vendor claims or outdated benchmarks, this report consolidates multi-year trajectory analysis, competitive positioning, and regulatory-technological crosscurrents into a single strategic reference layer.
Why 2026 Demands a Hard Look at Sectioning Infrastructure
The global tissue sectioning market has expanded from approximately 610.15 million USD in 2020 to 845.5 million USD in the base year of 2025. This trajectory reflects more than a simple growth curve; it mirrors a structural shift in how laboratories allocate capital, how diagnostic workflows are redesigned, and how equipment vendors are being held accountable for throughput, reproducibility, and integration readiness. With a forecast period spanning 2026 through 2032 and a compound annual growth rate of 6.42 percent, the market is entering a phase where incremental procurement decisions can either lock organizations into efficiency bottlenecks or create long-term operational advantages. The 2026 forecast reading of 871.87 million USD and the subsequent step-up to 955.38 million USD by 2027 highlight a continued expansion that is neither uniform nor accidental. Growth is being reshaped by evolving end-user requirements, product-type substitution dynamics, and the gradual but unmistakable penetration of automation into workflows that historically favored manual or semi-automatic instruments.
For strategic planners, the critical implication is that 2026 is not a year for hedging behind legacy replacement cycles. It is a year for reassessing equipment roadmaps against throughput targets, digital pathology compatibility, consumable cost structures, and compliance exposure. Organizations that treat tissue sectioning as a purely mechanical procurement category risk underpricing the operational value of precision, reliability, and workflow integration. Those that map their capital allocation to the market’s actual growth drivers will be positioned to capture margin-preserving efficiencies while maintaining diagnostic integrity.
What the Research Delivers: From Macro Trajectory to Operational Decisions
This study is structured to give leadership teams more than headline figures. It translates the market’s total revenue evolution into a decision framework that can be applied directly to capital planning, vendor evaluation, and regional deployment strategies. The report covers the full 2020–2025 historical window and extends forecasting through 2032, allowing readers to distinguish short-term procurement inflection points from durable structural trends. All financial data is presented in USD, with revenue measured in millions, enabling direct comparison across internal budgeting cycles and external market benchmarks.
Beyond aggregate sizing, the analysis disaggregates the market across product types, end-user environments, and regional demand distributions. This segmentation is not developed as a static slice-and-dice exercise; instead, it is used to surface the relative capital intensity, replacement cadence, and workflow relevance associated with different categories of sectioning equipment. The report also addresses market concentration dynamics, offering context on how a consolidated share base shapes pricing behavior, service competition, and the strategic maneuvering room available to emerging and mid-tier participants. Readers will find that the concentration pattern in this market influences far more than vendor negotiations; it affects lead times for service, the predictability of consumable supply, and the incentive structure for innovation.
Competitive Landscape: Ten-Plus Players, Distinct Positions, and a Consolidating Center of Gravity
The market is anchored by a cohort of established manufacturers whose portfolios span microtomes, cryostats, and tissue sectioning systems, each aligned to a different mix of clinical diagnostics, research, and pharmaceutical applications. Thermo Fisher Scientific Inc., headquartered in Waltham, MA, brings a comprehensive portfolio of microtomes, cryostats, and tissue sectioning systems that span both automated and manual solutions for high-precision histology. This breadth positions the company to serve dual demand streams: clinical diagnostics where consistency and service coverage matter, and research applications where instrument flexibility is paramount.
Leica Biosystems Nussloch GmbH, based in Germany, specializes in advanced histology equipment including rotary microtomes and cryostats such as the CM1950, alongside automated tissue sectioning platforms designed for clinical and research pathology workflows. Its emphasis on workflow continuity and platform integration reflects the broader industry shift toward instruments that fit into digitalized diagnostic pipelines rather than operating as standalone mechanical devices. Sakura Finetek USA, Inc., in Torrance, CA, focuses its Tissue-Tek series on automated microtomes, cryostats, and embedding systems optimized for high-throughput tissue sectioning in pathology laboratories, making it a particularly relevant comparator for organizations prioritizing throughput and lab-scale standardization.
Epredia, headquartered in Portsmouth, NH, supplies cryostats, microtomes, and related consumables oriented toward precision diagnostics, digital pathology integration, and tissue sectioning for cancer diagnostics. Its positioning underscores a growing recognition that consumables and instrument ecosystems must be evaluated together, especially in environments where slide quality, reproducibility, and downstream molecular workflows are tightly coupled. Diapath S.p.A., in Martinengo, Italy, manufactures manual, semi-automatic, and automatic microtomes along with consumables tailored for histopathology tissue sectioning, giving it a presence across multiple automation tiers. SLEE medical GmbH, in Mainz, Germany, develops high-quality cryostats and microtomes emphasizing precision and reliability, while MEDITE GmbH, in Burgdorf, Germany, offers microtomes, cryostats, and tissue processing equipment for medical and research tissue sectioning needs.
The supplier field extends beyond these core players. RMC Boeckeler, in Tucson, AZ, produces ultramicrotomes and tissue sectioning instruments primarily for electron microscopy and advanced research applications, addressing a niche that demands extreme precision and specialized operational expertise. Bright Instrument Company Ltd, in Huntingdon, UK, specializes in cryostats and microtomes for immunology, pathology, and quality control laboratories, reflecting a channel where sectioning accuracy intersects with regulated testing workflows. MICROS Produktions- und Handelsgesellschaft m.b.H., based in Austria, manufactures a range of microtomes for industrial and laboratory tissue sectioning, offering another perspective on the spread between clinical and broader laboratory use cases. In the Asia-Pacific supply landscape, RWD Life Science Co., Ltd., in Shenzhen, China, provides Minux series semi-automatic and automatic rotary microtomes and cryostats for histopathology tissue sectioning, while Jinhua YIDI Medical Appliance Co., Ltd., in Jinhua, China, produces rotary microtomes and related equipment for laboratory tissue sectioning applications. These regional participants illustrate how local manufacturing presence, cost structures, and application focus can influence procurement geography, though their strategic relevance depends heavily on service infrastructure, total cost of ownership, and workflow alignment.
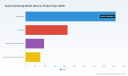
Worldwide Tissue Sectioning Market
Recent developments reinforce that competitive positioning is increasingly defined by platform integration rather than blade-quality claims alone. In January 2025, Leica Biosystems formed a strategic investment with Indica Labs to co-develop a combined scanner-AI platform supporting enhanced digital pathology workflows that integrate with tissue sectioning processes. This move signals a competitive logic in which sectioning equipment is being evaluated as part of a digitized continuum, not as an isolated instrument. In April 2025, Guardant Health launched Guardant360 Tissue, a DNA-RNA multiomics panel requiring 40 percent fewer slides, highlighting laboratory demand for optimized tissue sectioning efficiency in biopsy workflows. Even when the innovation originates outside the sectioning equipment category itself, it reshapes the value equation for sectioning precision, slide economy, and downstream consumable planning.
Market Dynamics and External Currents That Will Shape 2026 Decisions
Several structural forces are shaping how organizations should interpret equipment choices this year. First, regulatory classification continues to frame procurement and compliance planning. Microtomes and cryostats are classified by the FDA as tissue processing equipment under product code IDP for pathology applications. This classification anchors expectations around performance standards, documentation, and post-market oversight, and it matters for laboratories that operate under stringent quality systems or supply instruments into regulated environments. It is not simply a labeling detail; it affects vendor accountability, service expectations, and risk management for institutions that depend on sectioning consistency for downstream diagnosis.
Second, the recent Class 2 device recall issued for specific Leica microtome and cryostat models in October 2024 serves as a reminder that equipment reliability cannot be abstracted into marketing language. Recall events influence service planning, backup capacity considerations, and the weight that procurement teams place on vendor quality systems and field-support responsiveness. For strategic readers, the practical lesson is that instrument selection must account for the operational resilience of the full device lifecycle, including repair logistics, replacement part availability, and the vendor’s ability to manage corrective actions without disrupting diagnostic throughput.
Third, consumable and material science developments are increasingly relevant to total operating cost and section quality. Specialty steel such as Alleima 13C26 martensitic stainless steel is recommended for microtome blades due to its fine microstructure and edge retention properties critical for precise tissue sectioning. This kind of technical guidance illustrates why blade material, cutting consistency, and consumable quality deserve as much analytical attention as the capital instrument itself. In high-volume environments, blade performance directly influences section integrity, rework, and downstream interpretation, which means blade economics should be modeled alongside instrument economics rather than treated as a minor consumable line.
Strategic Interpretation for 2026 Planning
Taken together, the market’s trajectory, competitive structure, and external dynamics point to several decision themes for 2026. Organizations should evaluate equipment choices against throughput requirements, automation readiness, and digital integration needs, rather than treating microtomes and cryostats as interchangeable replacements. Procurement teams should weigh the balance between established multi-product vendors and specialists whose strengths lie in particular workflow niches, especially when service coverage and consumable ecosystems differ materially across suppliers. Buyers should also consider how downstream assay efficiency, including slide-reduction innovations, can alter the operational value of sectioning precision and influence consumable demand over time.
Microtomes Market
From a capital-structuring perspective, the concentration pattern in this market means that vendor selection can affect more than unit pricing. It can shape service predictability, upgrade pathways, and the feasibility of harmonizing equipment strategies across sites. For research and academic users, flexibility and application breadth may dominate; for hospitals and diagnostic laboratories, reliability, integration, and workflow standardization often carry greater weight; and for pharmaceutical and biotechnology companies, alignment with high-throughput and multiomics-compatible processes can drive differentiated equipment strategies. The report examines these distinctions without forcing every organization into the same playbook, recognizing that best-fit procurement depends on local workflow design and compliance context.
Closing the Intelligence Gap
This Worldwide Tissue Sectioning Market research is designed to convert market complexity into actionable strategy. It maps the growth arc from 2020 through 2032, situates consolidation patterns within competitive behavior, and ties regulatory, material, and workflow developments to real procurement consequences. The report’s segmentation analysis, end-user differentiation, and regional demand distributions are developed to support practical scenario planning, but the full depth of that segmentation and the detailed revenue splits are reserved for the complete study. To understand exactly how the 6.42 percent CAGR, the historical 2020–2025 base, and the 2026–2032 forecast translate into your organization’s equipment roadmap, capital sequencing, and vendor comparison, the complete dataset and interpretive framework should be consulted directly.
For executives preparing 2026 investment decisions, the practical value lies not only in knowing where the market is moving, but in understanding which segments, vendors, and workflow pressures matter most for your operating environment. The complete research offering provides that level of specificity, giving strategy and operations teams a grounded basis for procurement timing, supplier evaluation, and long-range equipment planning.
For detailed analysis of this topic, please visit the official page: Worldwide Tissue Sectioning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insight: Worldwide Dermabrasion and Microneedling Market to Hit $1.876B by 2032, CAGR 8.5%
By pmarketresearch, 2026-09-16
Navigating the Resurfacing Renaissance: Strategic Insights for the 2026 Dermabrasion and Microneedling Market
The global landscape for skin resurfacing is undergoing a transformative shift, driven by an aging population, rising aesthetic consciousness, and rapid technological innovation. For stakeholders operating within the medical aesthetics sector, understanding the trajectory of the Worldwide Dermabrasion and Microneedling Market is no longer optional—it is a strategic imperative. This analysis serves as an introduction to our comprehensive market research report, designed to equip executives, investors, and product leaders with the intelligence needed to navigate the complexities of the 2026 fiscal year and beyond.
As we move through the mid-2020s, the convergence of procedural demand and device sophistication has created a fertile environment for growth. However, this growth is not uniform. It is fragmented by regulatory hurdles, reimbursement variances, and shifting competitive dynamics. Our latest study dissects these layers, offering a roadmap for capitalizing on emerging opportunities while mitigating operational risks.
Microneedling Cartridges Market
Market Trajectory and Macroeconomic Context
The financial magnitude of this sector underscores its importance within the broader aesthetic industry. According to our longitudinal analysis, the market has demonstrated robust resilience and expansion over the past half-decade. Valued at over 710 million USD in 2020, the industry has consistently climbed, surpassing the 1 billion USD milestone in 2024. Projections for 2026 indicate the market value will reach approximately 1127 million USD, reflecting a steady acceleration in adoption rates across both clinical and consumer segments.
Looking further ahead, our forecast period extends to 2032, where we anticipate the market will push toward the 1.8 billion USD mark. This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 8.5 percent during the 2026 to 2032 forecast window. This rate suggests that the sector will significantly outpace general medical device market averages, highlighting the premium placed on non-invasive and minimally invasive skin rejuvenation technologies.
Several macroeconomic and social drivers fuel this momentum. Increasing disposable incomes in emerging economies allow greater access to elective aesthetic procedures. Simultaneously, demographic shifts in developed regions are prompting older populations to seek treatments that offer significant cosmetic improvement with reduced downtime. The demand for treatments that bridge the gap between topical skincare and surgical intervention is central to this expansion, positioning both dermabrasion and microneedling technologies as critical components of modern dermatological portfolios.
Strategic Segmentation and Application Analysis
Our research provides a granular breakdown of the market structure to help firms identify where value is being generated. The industry is primarily bifurcated by technology type, with microneedling devices commanding a significant portion of the revenue share due to their versatility and expanding indications. Dermabrasion devices, while historically foundational, continue to hold relevance in specific surgical contexts, though their growth dynamics differ from the newer energy-based microneedling platforms.
End-user segmentation further illuminates the path to market. Dermatology clinics remain the dominant channel for procedural volume, leveraging specialized expertise to drive premium pricing. Hospitals contribute a substantial share, particularly where skin resurfacing is integrated into broader reconstructive or therapeutic plans. However, a notable shift is occurring within home use settings. The rise of consumer-grade devices indicates a blurring line between professional and personal care, opening new revenue streams for manufacturers who can ensure safety and efficacy in non-clinical environments.
Confidence in this growth is supported by market concentration metrics. Our data indicates a CR3 concentration of approximately 38.45 percent and a CR5 concentration of 52.12 percent. This suggests a moderately competitive landscape where top-tier players hold significant sway, yet there remains ample room for innovation and market entry by specialized firms. Understanding the balance between established dominance and niche opportunity is vital for strategic planning.
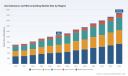
Worldwide Dermabrasion and Microneedling Market
Regulatory Framework and Operational Dynamics
Navigating the regulatory environment is one of the most critical challenges for participants in this market. The classification of devices dictates the path to market and influences operational costs. Microneedling devices for aesthetic use are typically classified as Class II medical devices under 21 CFR 878.4430. This classification requires 510(k) premarket notification with special controls, ensuring that safety and effectiveness are demonstrated before widespread commercialization. Compliance with these standards is not merely a legal requirement but a competitive differentiator that builds trust with practitioners and patients alike.
Conversely, dermabrasion devices often fall under Class I classifications, either manual or motorized, and are generally exempt from 510(k) premarket notification, subject to specific limitations outlined in 21 CFR 878.9. While this lowers the barrier to entry for traditional dermabrasion tools, it also intensifies competition on price and distribution efficiency. However, recent safety communications from regulatory bodies have highlighted potential risks associated with certain radiofrequency (RF) microneedling uses, including burns and nerve injuries, particularly when unregulated devices or unlicensed operators are involved. This heightened scrutiny emphasizes the need for rigorous training and adherence to safety protocols.
Reimbursement policies add another layer of complexity. Current procedural terminology (CPT) codes 15780-15783 are utilized for dermabrasion procedures, applicable in contexts involving skin resurfacing. However, many microneedling and aesthetic procedures often fall under unlisted codes or are categorized as cosmetic treatments with limited insurance coverage. This dynamic requires businesses to develop flexible pricing models and clearly communicate value propositions to patients who are often paying out-of-pocket. Understanding the nuances of billing and payer policies is essential for maintaining healthy cash flows in clinical settings.
Competitive Landscape and Key Corporate Movements
The competitive arena is populated by a diverse mix of established medical device giants and specialized aesthetic innovators. Key players shaping the market include Crown Aesthetics (Revance), which has established a strong position with the SkinPen Precision, recognized as the first FDA-cleared microneedling device for improving facial acne scars and neck wrinkles. Candela Medical continues to expand its portfolio with RF microneedling devices and hydro-infusion systems, catering to high-demand aesthetic clinics. Lumenis and Cynosure provide complementary aesthetic devices supporting skin resurfacing, while Cutera and Alma Lasers offer laser and energy-based platforms essential for comprehensive skin treatment regimens.
Regional players are also making significant impacts. Lutronic from South Korea manufactures RF microneedling and energy-based devices that are gaining traction globally. InMode offers minimally invasive aesthetic platforms, while DermapenWorld specializes in professional microneedling pens. On the surgical instrument side, Stryker, CONMED Corporation, and MicroAire Surgical Instruments supply devices applicable to dermabrasion procedures, ensuring the traditional segment remains robust. Furthermore, Dermalogica has entered the medical device space with the FDA-cleared PRO Pen Microneedling System, and Emage Medical provides FDA-cleared devices including CytoPen and Cyto-RF systems.
Recent corporate developments underscore the pace of innovation. In a notable move, Dermalogica officially launched the FDA-cleared PRO Pen Microneedling System in April 2026. This launch marks the company's first foray into FDA-cleared medical devices for improving facial acne scars in adults. This follows regulatory clearance received in September 2025, with US distribution beginning in 2026. Such moves signal a trend where skincare brands are bridging into medical device territory, intensifying competition and raising the bar for product efficacy and regulatory compliance.
Technological Drivers and Future Outlook
Innovation remains the primary engine for market differentiation. The industry is witnessing a shift toward devices that offer enhanced precision, reduced patient discomfort, and faster recovery times. Radiofrequency microneedling, in particular, is evolving to deliver controlled thermal energy at varying depths, optimizing collagen induction while minimizing epidermal damage. Manufacturers are increasingly focusing on user experience, integrating intuitive interfaces and disposable components to streamline clinic operations and reduce cross-contamination risks.
The intersection of technology and consumer preference is also driving demand for combination therapies. Practitioners are seeking platforms that can address multiple concerns—such as texture, tone, and laxity—in a single session. This demand encourages companies to develop modular systems or bundled offerings that maximize treatment value. Additionally, the rise of teledermatology and digital consultation tools is influencing how devices are marketed and prescribed, requiring companies to adapt their go-to-market strategies for a hybrid care model.
Conclusion: The Imperative for Actionable Intelligence
For enterprises operating in the Worldwide Dermabrasion and Microneedling Market, the margin for error is narrowing. The combination of strong growth projections, evolving regulatory standards, and aggressive competition demands a data-informed approach to strategy. Whether assessing market entry opportunities, optimizing product portfolios, or refining pricing strategies, reliance on outdated or aggregated data can lead to suboptimal decisions.
Our full market research report delves deeper into these dynamics, offering detailed revenue forecasts, segmented analysis, and strategic recommendations tailored to specific business models. We provide the granular data necessary to validate assumptions and uncover hidden risks. For stakeholders ready to secure their position in this expanding sector, accessing comprehensive intelligence is the first step toward sustainable growth. We invite you to explore the complete findings and leverage these insights to drive your strategic agenda in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Dermabrasion and Microneedling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vinca Alkaloids Market to Hit $1,262M by 2032 CAGR 5.8%
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Global Vinca Alkaloids Drug Market
In the complex landscape of oncology therapeutics, vinca alkaloids remain a cornerstone of chemotherapy regimens despite the emergence of novel targeted therapies. As we move further into 2026, pharmaceutical companies, investors, and supply chain stakeholders face critical decisions regarding capacity, sourcing, and competitive positioning within this specialized market. The Worldwide Vinca Alkaloids Drugs Market research report by PW Consulting offers a comprehensive roadmap for navigating these challenges. This strategic overview highlights the macroeconomic trajectory and the operational imperatives revealed by our latest analysis, providing senior leadership with the context needed to drive informed decision-making.
Platinum Based Cancer Drug Market
The market has demonstrated resilience and steady growth over the past half-decade. Our analysis indicates that the global market revenue reached approximately 850.5 million USD in 2025. Looking ahead, the forecast period from 2026 to 2032 suggests a consistent upward trajectory, with the market projected to exceed 1.2 billion USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.8 percent. For strategic planners, this growth rate signals a mature yet expanding market where incremental gains are vital. The historical data from 2020 through 2025 shows a consistent climb, reflecting the enduring reliance on these compounds in treating various malignancies despite patent expiries and generic competition.
Market Concentration and Competitive Dynamics
Understanding the competitive landscape is essential for identifying partnership opportunities and assessing market entry barriers. The vinca alkaloids market is moderately consolidated. Our data reveals a CR3 of 42.15 percent and a CR5 of 61.8 percent. This concentration level suggests that while key incumbents hold significant sway, there is ample room for specialized manufacturers and regional players to carve out niches. The ecosystem includes major multinational pharmaceutical corporations alongside specialized active pharmaceutical ingredient (API) manufacturers, particularly in Europe and Asia.
Key players such as Pierre Fabre and Minakem represent significant strength in the European sector. Pierre Fabre maintains a strong position as a producer of vinorelbine for oncology indications including breast and lung cancer. Meanwhile, Minakem has solidified its status as a leading European manufacturer of vinca alkaloid APIs. Notably, recent regulatory validations have confirmed Minakem as the sole manufacturer in Europe for certain vinorelbine products with validated CEP. This type of regulatory moat is critical for supply chain security.
In the United States, legacy providers like Eli Lilly and Company and Pfizer Inc. continue to influence market dynamics. Eli Lilly remains a long-term provider of vincristine and vinblastine for leukemia and lymphoma, while Pfizer acts as a key supplier of vincristine sulfate formulations. The generic sector is robust, with companies like Teva Pharmaceutical Industries Ltd. and Hikma Pharmaceuticals PLC offering alternative formulations. Additionally, the market sees significant participation from Chinese manufacturers such as Qilu Pharmaceutical and Hainan Yueyang Biotechnology, who are increasingly integrated into the global supply chain for vinca alkaloid compounds. Other notable entities include Fresenius Kabi in Germany and Vinkem in India, highlighting the geographically diverse nature of production.
Strategic Supply Chain Vulnerabilities and Opportunities
A core component of our 2026 analysis focuses on the supply chain dynamics that dictate profitability and availability. Unlike fully synthetic drugs, vinca alkaloids such as vinblastine and vincristine rely on extraction from Catharanthus roseus, commonly known as the Madagascar periwinkle. This botanical origin introduces inherent vulnerabilities. The extraction process is low-yielding; it requires approximately 500 kg and 2,000 kg of dried leaves respectively to obtain just 1 g of product. This inefficiency makes the supply chain sensitive to agricultural conditions.
Climate variability affecting Catharanthus roseus cultivation and geopolitical factors in raw material transportation have led to periodic supply shortages. Sector analysis from 2025 indicates that these disruptions can cause price fluctuations exceeding 25 percent for some APIs. For procurement leaders and supply chain managers, understanding these volatility drivers is crucial for hedging strategies and inventory management. Our report delves deep into regional supply risks, examining how manufacturers in North America, Europe, and Asia Pacific are mitigating these risks through vertical integration or diversified sourcing.
Furthermore, research into synthetic or microbial production routes for vinca alkaloid precursors like vindoline and catharanthine is ongoing. While plant extraction remains the standard, the industry is watching these technological developments closely as potential long-term solutions to supply constraints. Our market research evaluates the commercial readiness of these alternatives and their potential impact on market pricing structures over the forecast period.
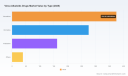
Worldwide Vinca Alkaloids Drugs Market
Regulatory Tailwinds and Combination Therapies
Regulatory approvals continue to validate the clinical utility of vinca alkaloids in modern oncology. Despite being established components with long-past patent expiration, these drugs remain integral to standard chemotherapy regimens. A significant recent development occurred in March 2026, when the FDA approved nivolumab (Opdivo) in combination with doxorubicin, vinblastine, and dacarbazine (AVD) for previously untreated stage III or IV classical Hodgkin lymphoma in adult and pediatric patients aged 12 and older. Such combination approvals reinforce the demand stability for vinca alkaloids, particularly vinblastine.
Alongside clinical demand, regulatory compliance remains a key differentiator. The validation of Certificates of European Pharmacopoeia (CEP) is a critical milestone for manufacturers seeking to access European markets. These regulatory hurdles create barriers to entry that protect established players while raising the standard for new entrants. Our report provides detailed insights into the regulatory landscape across key regions, helping stakeholders assess the compliance costs and timelines associated with market participation.
Segmentation Insights: Type and Application
While the aggregate market figures provide a high-level view, the true strategic value lies in understanding the segmentation driving this growth. The market is diversified across several product types and clinical applications. Vinorelbine, vincristine, and vinblastine constitute the primary segments, each serving different therapeutic needs and exhibiting distinct growth patterns. Vinorelbine, for instance, is heavily utilized in breast and lung cancer treatments, areas where demand continues to evolve with changing oncology guidelines.
In terms of application, the demand is distributed across lymphomas, leukemia, non-small cell lung cancer, breast cancer, and other indications. The reliance on these drugs across multiple cancer types provides a hedge against downturns in any single therapeutic area. For example, while the market for breast cancer formulations is significant, the volume driven by leukemia and lymphoma regimens ensures a baseline demand that supports the overall market stability. Our report breaks down these segments to identify which specific indications offer the highest margin potential and which regions are seeing the fastest adoption rates for specific formulations.
Geographical Distribution and Regional Strategies
Geographically, the market exhibits distinct characteristics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America remains a dominant force, driven by high healthcare expenditure and established oncology infrastructure. Europe follows closely, supported by stringent regulatory standards and a strong manufacturing base for APIs. The Asia Pacific region represents an area of significant interest due to growing healthcare access and the concentration of API manufacturing capabilities.
Latin America and the Middle East and Africa, while smaller in terms of current revenue contribution, present emerging opportunities as healthcare systems expand. Understanding the nuances of these regional markets is vital for companies looking to expand their footprint. Our analysis covers the specific dynamics in each region, from reimbursement landscapes to the presence of local generic manufacturers, without revealing the specific revenue splits that constitute our proprietary intelligence.
Why This Research Matters for 2026 Decision Making
In an environment characterized by supply chain fragility and competitive pressure from generics, data-driven strategy is not optional. The Worldwide Vinca Alkaloids Drugs Market report is designed to equip stakeholders with the actionable intelligence needed to navigate this complexity. Whether you are evaluating a potential partnership, assessing capacity expansion, or entering a new regional market, the granular data provided in the full study is essential.
We invite industry leaders to access the complete Worldwide Vinca Alkaloids Drugs Market research to gain full visibility into the segmentation splits, detailed competitor profiles, and forward-looking forecasts. The summary provided here outlines the strategic landscape, but the full report delivers the specific metrics required to build robust business cases. With a projected market size exceeding 1.2 billion USD by 2032 and a steady CAGR of 5.8 percent, the opportunity for strategic positioning is clear. However, capturing that value requires precise intelligence on which specific segments are driving growth and where supply risks are most acute.
PW Consulting remains committed to providing the highest quality market intelligence to support the pharmaceutical industry. As the landscape evolves with new combination therapies and potential shifts in manufacturing technology, staying informed is the best defense against uncertainty. We encourage you to review the full methodology and data tables available on our website to ensure your 2026 planning is built on a foundation of accurate, verified market data.
For detailed analysis of this topic, please visit the official page: Worldwide Vinca Alkaloids Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Heated Wiper Fluid Market Hits $192.4M in 2025, Projects 6.5% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Thermal Edge: Strategic Intelligence for the Heated Wiper Fluid Market, 2026–2032
As automotive electrification accelerates and climate extremes intensify, the heated windshield wiper fluid segment has evolved from a niche cold-climate accessory into a strategically relevant component of vehicle thermal and safety architecture. For executives, product planners, and supply chain leaders, the decisions made in 2026 will shape competitive positioning through the end of the decade. Our latest Worldwide Heated Wiper Fluid Market research is engineered to convert structural industry shifts into actionable commercial intelligence, framing a market that reached approximately 192.4 million USD in 2025 and is projected to cross the 299 million USD threshold by 2032, translating to a compound annual growth rate of 6.5 percent across the 2026–2032 forecast horizon.
This is not a retrospective snapshot. The base year 2025 embeds five years of historical trajectory (2020–2025) that illuminate how supply chain normalization, OEM thermal-management re-architecting, and expanding aftermarket channel maturity have compounded into today’s demand profile. From 142.15 million USD in 2020, the market progressed through 150.19 million USD in 2021, 162.5 million USD in 2022, 177.02 million USD in 2023, and 185.0 million USD in 2024 before reaching the current 192.4 million USD baseline. The forecast sequence—197.09 million USD in 2026, 218.79 million USD in 2027, 241.62 million USD in 2028, 247.71 million USD in 2029, 262.56 million USD in 2030, 274.86 million USD in 2031, and 299.01 million USD in 2032—reveals an inflection pattern where early-period growth gives way to accelerated expansion as regional adoption broadens and integration complexity increases. For leadership teams, the message is clear: the next twelve months are the decisive window to align sourcing, product development, and channel strategy before the forecast curve steepens.
Why 2026 Demands a Different Strategic Lens
The 2026 decision cycle carries structural weight that prior years did not. Three forces converge. First, component sourcing has become a constrained equation: the PTC heating elements required for heated washer systems now compete for supply with electric-vehicle battery thermal management modules and seat-heating arrays, meaning procurement strategies that worked in a standalone fluid-market context no longer suffice. Second, regulatory attention has sharpened around both safety and formulation standards, with historical recall episodes underscoring electrical-module vulnerabilities and contemporary petitions advocating standardized winter-grade washer fluids to mitigate cold-weather safety gaps. Third, the aftermarket is professionalizing at a pace that rewards early movers who can deliver validated thermal performance without compromising installation repeatability or fluid compatibility. The research is built to help organizations navigate these overlapping pressures with calibrated evidence rather than directional assumption.
Inside the Report: Operational Intelligence for Commercial Execution
Our worldwide heated wiper fluid study is structured as a working document for strategy, not a static market summary. The analytical framework is organized around the decision points that actually drive P&L outcomes: segmentation by type, by application, and by region, each mapped to demand drivers, mix-shift trajectories, and substitution dynamics. The report examines the split between on-demand heating architectures and continuous heating systems, clarifying where consumer and fleet expectations diverge on energy draw, activation latency, and total cost of ownership. It also dissects the application landscape across passenger cars, light commercial vehicles, and heavy commercial vehicles, revealing how duty-cycle differences, uptime requirements, and procurement cycles create distinct margin and volume logic within each segment.
Regional demand architecture is analyzed through a lens of market maturity, climate-driven penetration, OEM-package penetration, and aftermarket channel density, without reducing the story to a single headline number. Instead, the research provides the comparative structure executives need to evaluate where to prioritize inventory, where to invest in localized formulation or distribution partnerships, and where regulatory or competitive intensity compresses pricing power. The concentration analysis—anchored by a top-three combined share of 42.15 percent and a top-five combined share of 58.4 percent—frames the axis of competition: a market that is meaningfully consolidated at the top yet still open enough to reward differentiated technology, channel reach, and formulation expertise.
Beyond segmentation, the study integrates supply-side realism. Heated wiper fluid formulations typically rely on methanol-blended winter chemistries engineered for low-temperature freeze protection, introducing toxic, flammable, and hazardous-waste considerations that affect blending, logistics, and end-of-life handling. The report addresses how these material constraints shape manufacturing footprints, compliance costs, and aftermarket substitution behavior. On the hardware side, it maps the interplay between fluid chemistry and heating-element performance, providing the cross-functional context needed for product managers who must simultaneously optimize thermal output, fluid compatibility, and system durability.
Competitive Landscape: Specialized Leaders and Converging Supply Chains
The competitive field in heated wiper fluid is defined by companies operating at the intersection of fluid chemistry, thermal hardware, and vehicle-package integration. The research includes detailed profiles of the participants shaping both OEM specification and aftermarket replacement demand, capturing capability sets, go-to-market posture, and where each player is investing next.
Valeo S.A. exemplifies the integrated-system approach, offering heated wiper and washer functionality through platforms such as AquaBlade that span OEM and aftermarket channels and are purpose-built to mitigate freezing effects in severe climates. In April 2025, Valeo Service expanded availability of heated AquaBlade premium wiper blades, broadening part-number coverage for cold-climate service applications. Kautex Textron GmbH & Co. KG and Denso Corporation round out the hardware integration dimension, supplying fluid-management and washer-system components that support heated washer fluid architectures at the vehicle level. Their relevance extends beyond discrete parts: as OEMs rebalance thermal budgets across cabin, battery, and wash systems, the firms that can deliver compactly integrated heating and fluid-handling solutions gain specification leverage.
On the fluid-supply side, Recochem Inc., CCI Corporation (Genuine Chemistry), and China Hong Wipers represent the formulation and OEM-supply axis. Recochem operates as a global automotive-fluid manufacturer with temperature-protection formulations suited to heated systems, while CCI Corporation serves as an OEM washer-fluid supplier to major automotive, heavy-equipment, and powersports manufacturers, including a 2025 AAPEX presence that reinforced its role in the global genuine-chemistry supply chain. China Hong Wipers occupies a distinct export-oriented position, supplying heated washer fluid systems and heater components across global aftermarket and OEM channels.
Heated Windshields Market
The aftermarket landscape adds a second competitive layer. SPLASH Products Inc. (Factory Motor Parts) manufactures winter and de-icing washer formulations with U.S.-based production for aftermarket distribution, and Old World Industries (OWI) serves commercial and automotive markets through washer-fluid brands such as Blue Mountain. Specialized heated-system aftermarket players—including AlphaTherm via its Donmar/HotShot lineage and HydroBlast (Kleinn)—have pushed thermal-performance expectations upward, with aftermarket heaters engineered to raise fluid temperature to approximately 132°F for frost and snow removal. These offerings matter strategically because they set performance benchmarks that OEM packages must either meet or explicitly differentiate against.
Worldwide Heated Wiper Fluid Market
One of the most telling competitive signals comes from the broader OEM trajectory. In May 2023, Ford Motor Company filed a patent for a heated windshield washer bottle system designed to warm fluid electrically for improved cold-weather performance in future vehicles. That filing is not simply a product hint; it signals where thermal-management architecture is heading and why fluid, container, and heating-module design are increasingly inseparable in the product roadmap.
The Dynamics That Will Shape Margin, Mix, and Risk Through 2032
The market’s trajectory is not driven by demand alone. Several structural dynamics will determine which participants convert growth into durable advantage.
Historical safety experience remains a cautionary reference point. General Motors previously issued recalls for 2006–2008 model-year vehicles equipped with heated windshield washer fluid systems due to short-circuit risks in the heating module that could lead to overheating, smoke, or fire. That episode contributed to broader OEM caution, and GM subsequently discontinued factory heated windshield washer fluid systems on many models following recalls tied to fire-hazard concerns in the heating module. The strategic implication is not that heated systems are unviable; it is that validation rigor, electrical integration discipline, and failure-mode design now function as competitive prerequisites rather than optional engineering polish.
Regulatory and standardization pressure is building on the fluid side as well. U.S. FMVSS 104 governs windshield wiping and washing systems, and recent policy attention has included a 2019 petition seeking standardized winter-specification washer fluid year-round to address safety concerns arising when summer formulations are used in cold conditions. These discussions matter because they can alter formulation defaults, testing expectations, and aftermarket substitution behavior, especially in markets where temperature variability makes fluid-grade consistency a safety and usability issue.
Material and component constraints add another dimension. Methanol-based winter blends provide freeze protection but introduce toxicity, flammability, and hazardous-waste considerations that influence handling, distribution, and reclamation economics. At the same time, the PTC heating elements that underpin heated washer systems compete with supply allocated to EV battery thermal management and seat-heating applications. For procurement and product-strategy teams, that means cost modeling and supply security must be evaluated within a wider thermal-component ecosystem, not in isolation. The research embeds these constraints into sourcing scenarios so that plans reflect practical availability and compliance exposure rather than idealized input assumptions.
How to Use This Research in 2026 Decision-Making
The most valuable use of this study is as a cross-functional alignment tool. For product and engineering leaders, it frames the trade-space between on-demand and continuous heating architectures, the implications of fluid chemistry on system performance, and the increasing need to treat washer-fluid heating as part of a broader thermal-management strategy. For commercial and channel teams, it maps where regional demand is consolidating around climate exposure, OEM penetration, and aftermarket density, enabling more precise inventory allocation and go-to-market sequencing. For procurement and supply chain leaders, it situates component availability and formulation compliance within realistic constraints, including the PTC element supply contest and hazardous-material handling requirements. For corporate strategy and M&A teams, the concentration profile and participant capabilities provide a basis for evaluating where consolidation pressure may intensify and where differentiated specialty players can sustain premium positioning.
The study is also designed to shorten the distance between analysis and execution. Rather than presenting market potential as a single abstract figure, it organizes the intelligence around the operational questions that determine whether a market entry, capacity decision, or channel investment will hold up under competitive and regulatory scrutiny. The 2026–2032 forecast sequence is used not as a forecast to be read passively, but as a planning scaffold for scenario-building around adoption pace, mix evolution, and the timing of competitive responses from both integrated suppliers and specialized aftermarket players.
Closing Perspective
The worldwide heated wiper fluid market is entering a phase in which growth and complexity reinforce each other. Demand is expanding, but the winners will be determined by how effectively organizations manage the technical, regulatory, and supply-chain subtleties that surround that expansion. This research is built to give decision-makers the evidentiary foundation to act with confidence in 2026 and to prepare for the acceleration projected through 2032. The full segmentation architecture, company-level strategic assessments, comparative regional analysis, and forecast detail contained in the complete study provide the granularity required to convert high-level momentum into executable advantage. For leadership teams ready to move from market awareness to structured positioning, the full report offers the complete intelligence set needed to make those choices with precision.
For detailed analysis of this topic, please visit the official page: Worldwide Heated Wiper Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart-connected Wallets Market to Reach $729.18 Million by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Connected Era: Inside the Worldwide Smart-connected Wallets Market Outlook
As financial security and personal convenience converge, the smart-connected wallet has evolved from a novelty accessory into a critical node in the broader ecosystem of digital identity and asset management. For enterprise leaders, investors, and product strategists, understanding the trajectory of this market is no longer optional—it is a prerequisite for informed decision-making in 2026 and beyond. PW Consulting presents this executive summary to contextualize the findings of our latest Worldwide Smart-connected Wallets Market research, offering a strategic lens through which to view the opportunities and risks defining this sector.
The transition from passive leather goods to active digital interfaces represents a fundamental shift in consumer behavior. This report is designed to decode that shift, providing a robust framework for assessing market viability, competitive positioning, and regulatory exposure. The following analysis highlights the macro-economic trajectory, the evolving competitive landscape, and the operational complexities that will shape the industry over the coming forecast period.
Macro-Economic Trajectory and Growth Vectors
The financial architecture of the smart-connected wallet market demonstrates resilient growth despite broader economic fluctuations. Our analysis tracks revenue performance from the historical baseline of 2020 through the forecasted horizon of 2032. The data indicates a consistent upward trend in market valuation, driven by increasing consumer adoption of tracking technologies and heightened security awareness.
Starting from a foundational valuation in the early 2020s, the market has expanded steadily, reflecting the gradual integration of Bluetooth tracking and RFID security into mainstream consumer accessories. By the base year of 2025, the market had achieved significant momentum, setting the stage for accelerated expansion in the forecast period. Looking ahead to 2032, the projected revenue trajectory suggests a substantial increase in total market size, underscoring the long-term viability of smart wallet solutions as a distinct product category.
The Compound Annual Growth Rate (CAGR) recorded over the forecast period points to a healthy expansion rate that outpaces many traditional consumer accessory segments. This growth is not merely nominal; it reflects a deepening penetration of technology-enabled security features into everyday carry items. For stakeholders, this macro view confirms that the sector is moving beyond early adoption phases into a period of sustained scaling. However, realizing value in this environment requires navigating specific segmentation dynamics and regional variances that are detailed within the full research document.
Competitive Landscape and Strategic Positioning
The marketplace is characterized by a diverse array of players ranging from established leather goods manufacturers to specialized technology firms focusing on security and tracking integration. The competitive intensity is moderated by a moderate level of market concentration, indicating that while key players hold significant share, there remains ample room for disruption and niche specialization. Our analysis identifies several core companies that are setting the pace for innovation and market presence.
Key Market Participants
Understanding the strategic moves of leading entities is crucial for benchmarking and competitive analysis. The following organizations represent the forefront of product development and market penetration:
- Ekster (Netherlands): Positions itself in the premium segment with leather smart wallets featuring integrated rechargeable Bluetooth trackers compatible with Apple Find My and Android. Their focus on RFID protection and slim cardholder designs targets consumers seeking a blend of aesthetics and high-tech security.
- iWallet Corporation (United States): Develops biometric and GPS-enabled smart wallets, including models with fingerprint security and NFC capabilities. Beyond hardware, they provide consulting in the smart wallet sector, signaling a diversified business model. Recent activities include the unveiling of the iClutch designed with advanced security features and an announcement of the flagship iWallet 2.0 set for the 2025 holiday season, incorporating aerospace-grade materials.
- Bellroy (Australia): Produces minimalist smart wallets with RFID blocking and tracking integration options as part of their premium leather accessory line, appealing to a design-conscious demographic.
- Dango Products (United States): Manufactures durable smart wallets incorporating RFID protection and modular tracking features, emphasizing longevity and customization.
- Arista Vault (India): Specializes in secure smart vault-style wallets with advanced RFID and tracking capabilities, addressing security-first use cases.
- Groove Life (United States): Offers the Groove Wallet Trace with Apple Find My technology for location tracking in a minimalist design, focusing on seamless integration with existing ecosystems.
- The Ridge (United States): Known for metal minimalist wallets with optional tracking card integrations for smart connectivity, leveraging durable materials.
- Nomad (United States) & Innway: Provide complementary technologies such as card trackers compatible with smart wallets for Bluetooth-based location monitoring and wireless tracking cards designed for integration into smart connected wallets.
Recent developments highlight the velocity of innovation. Alongside iWallet Corporation's hardware launches, the sector saw Claw Wallet launch an AI Agent Security Wallet infrastructure in April 2025 for securing on-chain assets in autonomous DeFi transactions. This divergence between physical security and digital asset infrastructure suggests the market definition may be expanding to encompass broader digital identity solutions.
Regional Distribution and Technology Adoption
The market is not uniform; geographic and technological segmentation plays a pivotal role in strategic planning. Revenue distribution analysis reveals distinct patterns across major global regions. North America, Europe, and Asia Pacific each present unique value pools, influenced by local consumer preferences, adoption rates of tracking technology, and retail infrastructure. While specific regional revenue figures are reserved for the detailed report, it is evident that North America and Asia Pacific represent significant centers of gravity for market activity.
Technological segmentation further delineates the market structure. The landscape is currently dominated by solutions that integrate Bluetooth tracking enabled features, reflecting the primary consumer demand for location security. RFID blocking only solutions maintain a substantial presence, catering to users prioritizing data privacy over active tracking. Meanwhile, biometric security technologies represent a growing niche, aligning with broader trends in authentication and personal security. The interplay between these technology stacks defines product differentiation strategies for manufacturers.
Distribution channels also reflect evolving consumer habits. Online retail channels command a significant portion of revenue, leveraging the ability to showcase tech-enabled features through digital marketing and direct-to-consumer models. Offline retail remains relevant, particularly for premium leather goods where tactile experience influences purchasing decisions. The balance between these channels is shifting, and understanding the specific revenue split is essential for optimizing go-to-market strategies.
Regulatory Dynamics and Risk Factors
Strategic planning in the smart-connected wallet sector must account for an increasingly complex regulatory environment. Data security and privacy regulations are particularly pertinent given the nature of connected devices that handle location data and potentially personal authentication information.
A critical development occurred in early 2025 when the U.S. Department of Justice finalized rules under the Data Security Program. Effective April 2025, these rules prohibit or restrict certain bulk sensitive personal data transactions with countries of concern, including China and Russia. For manufacturers of connected wallets, this has direct implications for data-handling devices and the supply chain infrastructure supporting cloud connectivity. Companies must ensure compliance not only in hardware production but in the data flows generated by their tracking and security features.
Additionally, the regulatory landscape regarding internet services continues to evolve. In 2025, a U.S. court ruling determined that Internet companies should not be regulated like utilities, shifting net neutrality oversight decisions to Congress and state legislatures. While this primarily affects service providers, it introduces volatility in the connectivity infrastructure that smart wallets rely upon for tracking and app integration. These dynamics create a backdrop of regulatory uncertainty that requires continuous monitoring and adaptive compliance strategies.
Report Scope and Operational Utility
To navigate this complex environment, executives require granular data and actionable frameworks. This research report is constructed to serve as a comprehensive operational tool. It goes beyond high-level summaries to provide the specific intelligence needed for quota setting, investment allocation, and product roadmap planning.
The scope of the analysis covers a detailed historical review from 2020 to 2025, establishing a reliable baseline for trend analysis. The forecast period extends from 2026 to 2032, allowing for long-term strategic modeling. Key components of the full report include:
- Segmentation Analysis: Deep dives into revenue splits by region, technology type, and distribution channel. This allows clients to identify high-growth pockets and optimize resource allocation without relying on aggregated averages that mask local opportunities.
- Competitive Benchmarking: Detailed profiles of key companies including product portfolios, headquarters, and strategic focus. This facilitates competitive positioning and helps identify gaps in the current market offering.
- Market Concentration Metrics: Analysis of CR3 and CR5 percentages to understand market power dynamics and the potential for consolidation or entry barriers.
- Regulatory Impact Assessment: Contextualization of legal frameworks affecting data security and connectivity, helping firms mitigate compliance risk.
By integrating these elements, the report enables stakeholders to answer critical questions: Which technology stack offers the best margin potential? How should distribution channels be weighted in different regions? What are the compliance implications of integrating specific tracking features?
Worldwide Smart-connected Wallets Market
Strategic Imperatives for 2026
As the market moves into the 2026 forecast year, the strategic imperative shifts from mere participation to optimized positioning. The growth trajectory suggests continued expansion, but the competitive field is maturing. Companies that rely solely on basic RFID protection may find themselves outpaced by integrated tracking and biometric solutions. Conversely, high-tech solutions must navigate the regulatory complexities of data handling to ensure sustainable growth.
The divergence in product offerings—from minimalist metal wallets to AI-enabled security infrastructures—indicates that segmentation will become increasingly nuanced. Success will depend on aligning product features with specific consumer security needs and regional regulatory standards. Furthermore, the balance between online and offline distribution will require careful calibration based on the specific value proposition of the hardware.
Worldwide Smart Carry-on Bags Market
For investors and corporate strategists, the key takeaway is that the smart-connected wallet market is a high-potential sector with distinct structural drivers. However, realizing this potential requires access to precise data that accounts for regional variances, technological splits, and competitive moves. General market trends provide direction, but specific revenue splits and segmentation data provide the map.
Conclusion
The Worldwide Smart-connected Wallets Market is entering a phase of defined growth supported by technological innovation and heightened security awareness. The macro-economic indicators confirm a positive outlook through 2032, but the path to capturing value is paved with specific strategic choices regarding technology, geography, and compliance.
This executive overview illustrates the depth of insight available in the full PW Consulting market research. To access the complete data sets, including exact regional revenue figures, technology segmentation percentages, and detailed competitive financial profiles, stakeholders are invited to explore the full report. This comprehensive intelligence is designed to empower decision-makers with the clarity needed to lead in the connected economy.
The detailed segmentation data, including specific revenue contributions by North America, Europe, Asia Pacific, and Rest of World, along with precise breakdowns by Bluetooth Tracking, RFID Blocking, and Biometric Security, are critical for finalizing investment theses and product strategies. These specifics, alongside the full analysis of distribution channel dynamics between Online and Offline Retail, are available in the complete study. We encourage you to secure the full report to ensure your 2026 planning is supported by the most accurate and actionable market intelligence available.
For detailed analysis of this topic, please visit the official page: Worldwide Smart-connected Wallets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Proctoscope Market Hits $245.5M in 2025, Projected 5.48% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Future of anorectal Diagnostics: Strategic Insights from the Worldwide Proctoscope Market Outlook 2026-2032
Introduction
The global healthcare landscape is undergoing a profound transformation, driven by aging populations, increasing prevalence of colorectal disorders, and a renewed focus on procedural efficiency and infection control. Within this shifting environment, the proctoscope market stands as a critical yet often overlooked segment of the broader endoscopic device industry. For strategic leaders, investors, and product development teams, understanding the nuanced trajectories of this market is no longer optional—it is essential for capitalizing on emerging opportunities and mitigating competitive risks.
PW Consulting has just released its comprehensive Worldwide Proctoscope Market research report, offering a granular, data-driven analysis of market dynamics, competitive positioning, and growth vectors through 2032. This article serves as a strategic primer, distilling the report's core findings and illustrating how precise market intelligence can shape decisions in 2026 and beyond. It is designed to provide a clear view of the landscape while inviting you to dive deeper into the full dataset, where actionable segmentation and proprietary forecasts reside.
Macro Market Trajectory: Sustained Growth Anchored by Clinical Demand
The worldwide proctoscope market has demonstrated consistent expansion over the past half-decade, reflecting steady adoption across diagnostic and therapeutic pathways. Historical revenue streams from 2020 through 2025 reveal a market that has weathered supply chain pressures and procedural backlogs to maintain upward momentum, culminating in a stable 2025 baseline. Looking forward, the forecast period from 2026 to 2032 projects a compelling compound annual growth rate of 5.48 percent.
This growth trajectory is not uniform; it is shaped by evolving clinical protocols, reimbursement structures, and the ongoing tension between single-use convenience and reusable durability. As healthcare systems optimize capital expenditure and operational workflows, procurement teams are increasingly weighing total cost of ownership, sterilization compliance, and patient throughput. The market's projected expansion through 2032 signals a maturing ecosystem where innovation in optics, ergonomics, and material science will dictate market share consolidation and new entry strategies. Readers seeking the exact milestone valuations for each forecast year and the precise inflection points will find those detailed projections within the full report.
Structural Breakdown: How Segmentation Drives Decision-Making
Effective market strategy begins with understanding how the proctoscope landscape fractures across product architectures, clinical environments, and geographic territories. The report dissects these dimensions to reveal where value is created, where volume concentrates, and where competitive gaps persist.
Product Architecture: Disposable Versus Reusable Dynamics
The bifurcation between disposable and reusable proctoscopes represents one of the most strategic fault lines in the industry. Disposable systems cater to the growing demand for streamlined infection control, reduced reprocessing labor, and predictable per-procedure costing. Reusable instruments, meanwhile, remain entrenched in high-volume settings where capital investment is amortized over thousands of cycles and where optical fidelity, instrument durability, and sterilization validation are paramount.
The interplay between these two architectures is influenced by regulatory expectations, institutional procurement policies, and the financial calculus of outpatient versus inpatient settings. Material selection, sterilization compatibility, and lifecycle economics all factor into purchasing decisions. The report maps the revenue distribution across these categories and examines the shifting procurement preferences that are reshaping product roadmaps. Specific revenue allocations and growth rates for each product segment are detailed in the full dataset to support precise portfolio planning.
Clinical Applications: Where Procedures Drive Volume
Proctoscopes are deployed across a spectrum of care settings, each with distinct operational rhythms, reimbursement profiles, and adoption behaviors. Hospitals continue to anchor a significant share of procedural volume, leveraging integrated endoscopy suites and standardized sterilization workflows. Ambulatory surgical centers and specialized clinics are expanding their footprint, driven by the migration of lower-acuity anorectal procedures to outpatient environments and the push for same-day diagnostic efficiency.
Understanding the relative weight of these application channels is critical for manufacturers targeting distribution partnerships, service networks, and pricing strategies. The report quantifies how each setting contributes to overall market demand and outlines the procurement characteristics that differentiate them. Detailed breakdowns of application-specific market size and forecast trajectories are available in the complete report.
Geographic Distribution: Regional Market Structures
The worldwide proctoscope market exhibits clear regional asymmetries in terms of installed base, procedural density, regulatory frameworks, and purchasing power. North America remains a dominant revenue center, shaped by high procedural volumes, robust reimbursement pathways, and a mature distributor ecosystem. Europe follows with a substantial footprint, supported by established endoscopic traditions and strong regulatory alignment across member states.
Asia Pacific represents a rapidly evolving territory, where expanding healthcare infrastructure, growing awareness of colorectal screening, and localized manufacturing strategies are altering competitive dynamics. Latin America and the Middle East and Africa contribute more modest but strategically important volumes, often influenced by NGO-supported screening initiatives, medical tourism flows, and import-dependent supply chains. The report provides a structured regional analysis without oversimplifying the local nuances that govern procurement cycles and market entry barriers. Exact regional revenue figures and per-region growth trajectories are disclosed in the full market intelligence package.
Regulatory and Clinical Context: Shaping Product Strategy and Adoption
Proctoscopes operate within a tightly controlled clinical and regulatory environment that directly influences product design, compliance expenditure, and market access. In the United States, proctoscopes are classified as Class I medical devices and are 510(k) exempt under FDA product code FDT, which streamlines market entry relative to higher-class devices while still demanding rigorous quality management and labeling discipline. Internationally, compliance with ISO 13485 for quality management systems and ISO 17665 for steam sterilization validation remains foundational, particularly for reusable instruments intended for autoclave reprocessing up to 134 degrees Celsius.
Reimbursement dynamics further shape utilization patterns. Proctoscopy procedures are reimbursed under CPT codes 45300 through 45321, with average Medicare payments typically ranging between 100 and 250 dollars per procedure. These reimbursement parameters influence procedure volume forecasts, pricing sensitivity, and the attractiveness of specific clinical settings. Meanwhile, infection control standards continue to elevate the importance of high-level disinfection for reusable devices, reinforcing the operational case for single-use alternatives in certain outpatient workflows. The full report integrates these regulatory and reimbursement vectors into scenario models that help strategists anticipate compliance costs and adoption friction.
Competitive Landscape: Strategic Positioning of Market Leaders
The global proctoscope market is characterized by a concentrated group of established manufacturers that compete across product portfolios, geographic reach, and clinical specialization. Market concentration metrics indicate that the top three players capture approximately 32.5 percent of total revenue, while the top five collectively account for roughly 48.2 percent. This concentration suggests a market where scale, brand trust, and distribution depth matter, yet where niche positioning and innovation can still create defensible segments.
Olympus Corporation continues to anchor its presence through rigid proctoscopes such as the A3017A models, supporting anorectal endoscopy within broader gastrointestinal procedure suites. Karl Storz SE & Co. KG offers both reusable and disposable systems, including the 11620 series with integrated optics designed for proctological examinations, reinforcing its reputation for optical quality and modular instrumentation. Richard Wolf GmbH manufactures the 8570 series, emphasizing direct visualization in rectal diagnostics and aligning with institutions that value durable, sterilizable instruments.
Worldwide Proctoscope Market
PENTAX Medical, operating under HOYA Corporation, supplies proctoscopes within its rigid endoscopy portfolio for colorectal applications, leveraging cross-portfolio synergies in endoscopic imaging. Baxter International, through Welch Allyn, produces KleenSpec disposable proctoscopes that address single-use infection control requirements in outpatient settings, appealing to facilities prioritizing workflow simplicity and cross-contamination mitigation. HEINE Optotechnik GmbH & Co. KG contributes illuminated proctoscope sets such as the F 170 with LED technology, focusing on enhanced visualization and clinician ergonomics.
B. Braun Melsungen AG provides stainless steel proctoscopes such as the 720 series for surgical and diagnostic use, reinforcing its broader presence in sterile surgical instrumentation. Wallach Surgical Devices rounds out the competitive field with both disposable and reusable proctoscopes targeting gynecological and proctological procedures, illustrating how adjacent clinical markets can influence product strategy. The report evaluates these companies through a strategic lens, examining product architecture, geographic emphasis, and likely competitive moves. Full competitor profiles, market share modeling, and strategic implications are reserved for the complete analysis.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Making
The Worldwide Proctoscope Market report is structured to support concrete strategic actions rather than abstract market commentary. It combines historical reconstruction, forward-looking modeling, and operational context into a single decision-ready framework. Key components include:
- A detailed revenue timeline spanning historical years through the 2026-2032 forecast horizon, with milestone valuations and compound growth analysis calibrated to the underlying demand drivers.
- Segment-level assessments across product type and application, enabling portfolio mapping, pricing strategy refinement, and identification of high-potential subsegments.
- Regional market structures and procurement characteristics that inform distribution planning, market entry sequencing, and localization decisions.
- Competitive benchmarking that evaluates incumbent positioning, product differentiation levers, and the strategic implications of market concentration.
- Regulatory and reimbursement context integrated into adoption scenarios, helping teams anticipate compliance burdens, sterilization requirements, and reimbursement-driven volume sensitivity.
- Operational and material considerations, including sterilization compatibility, reprocessing workflows, and the trade-offs between disposable convenience and reusable durability.
By synthesizing these elements, the report equips executives and strategy teams with a coherent view of where value is migrating, which customer segments are most price- and performance-sensitive, and how competitive dynamics are likely to evolve. The complete dataset, analytical models, and strategic recommendations are accessible through the full report, where deeper segmentation and proprietary forecasts support scenario planning and investment prioritization.
Laryngoscope Market
Conclusion: Turning Market Intelligence Into Competitive Advantage
As the proctoscope market advances toward 2032, success will depend on more than incremental product updates or broad geographic expansion. It will require a precise understanding of how procedural economics, infection control mandates, reimbursement realities, and competitive concentration shape buyer behavior across hospitals, surgical centers, and clinics. The Worldwide Proctoscope Market research from PW Consulting is designed to convert that complexity into clarity.
For organizations preparing 2026 strategies, the report provides the structural insight needed to prioritize product investments, align distribution strategies, and evaluate competitive threats with confidence. We invite you to explore the complete analysis, where detailed segmentation, forecast tables, and competitor evaluations translate market signals into actionable intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Proctoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cardiac RF Catheter Market Set for 11.18% CAGR, Projected to Hit $7,873.83M by 2032
By pmarketresearch, 2026-09-16
Strategic Horizons in the Worldwide Cardiac Radiofrequency Catheter Market: A 2026 Decision-Maker's Guide
The global cardiac electrophysiology landscape is entering a pivotal growth cycle. As healthcare providers confront rising arrhythmia prevalence and demand for precision ablation technologies, the cardiac radiofrequency catheter market is undergoing structural transformation. Recent market valuation estimates indicate a trajectory that signals both robust commercial opportunity and intensifying competitive complexity. For strategic planners navigating 2026 investment decisions, understanding this ecosystem requires more than surface-level trend observation. It demands a disciplined breakdown of revenue momentum, procedural adoption patterns, and the competitive innovations reshaping clinical workflows. This analysis sets the stage for our newly released Worldwide Cardiac Radiofrequency Catheter Market research, a comprehensive study designed to operationalize high-level market intelligence into executable corporate strategy.
Mapping the 2026 Market Trajectory
Over the historical window from 2020 through the base year of 2025, the worldwide market for cardiac radiofrequency catheters has demonstrated consistent upward momentum. Total revenue expanded steadily across this period, moving from early-cycle valuations in the low thousands of millions to a mature base exceeding the three-thousand-million threshold by 2025. The forward forecast window spanning 2026 to 2032 compounds this trajectory, projecting sustained expansion that reflects both procedural volume growth and the migration toward advanced ablation platforms. At the core of this projection is a compound annual growth rate of approximately 11.18 percent. Such a growth rate places the sector in a favorable position relative to broader medical device categories, driven by continuous refinement in catheter engineering, expanded clinical indications, and the integration of enhanced mapping and navigation capabilities.
This upward arc is not merely a function of numerical expansion. The revenue trajectory encapsulates a broader shift in electrophysiology practice patterns. Hospitals and specialty clinics are increasingly prioritizing single-procedure efficiency, reducing reliance on multiple device workflows, and investing in platforms that can address complex arrhythmia substrates. Consequently, the market's measured acceleration through 2032 reflects an environment where demand for RF catheters remains tightly coupled with institutional procurement strategies, reimbursement frameworks, and the clinical outcomes that define value-based purchasing. For executives and product leaders, this environment rewards early positioning, rigorous competitive benchmarking, and disciplined allocation toward segments with durable adoption curves.
Why Detailed Intelligence Matters for 2026 Execution
Strategic planning in the medical device space requires precision, particularly when capital allocation decisions depend on segment momentum, procurement cycles, and competitive response patterns. While high-level market size indicators communicate broad opportunity, they rarely deliver the granularity required to design pricing strategy, forecast channel demand, or anticipate competitor behavior. That is precisely the gap our latest research addresses. The Worldwide Cardiac Radiofrequency Catheter Market study translates macro-level growth signals into structured, actionable insight, enabling leadership teams to evaluate where value is concentrating and how market mechanics are evolving beneath the headline numbers.
Worldwide Cardiac Radiofrequency Catheter Market
Consider the operational decisions facing a market participant in 2026. Should a product roadmap prioritize irrigated-tip designs given their dominant share of clinical utilization? How are procedural coding frameworks and facility payment structures influencing purchasing thresholds across different care settings? What does the intensifying focus on contact force sensing, impedance feedback, and robotically navigated systems mean for incumbent positioning? The answers to these questions depend on disciplined segmentation, region-specific demand mapping, and a nuanced understanding of how clinical preference translates into revenue distribution. Our report is structured to surface these decision levers without relying on superficial generalizations.
Inside the Report: A Toolkit for Strategic Action
The research is built around practical frameworks rather than abstract overviews. Readers will find a clearly structured examination of market sizing, segmented demand dynamics, and the competitive behaviors shaping the industry's next growth phase. The study delivers:
- A full historical valuation sequence and forecast path, with year-by-year revenue movement that anchors planning assumptions for both near-term budgeting and long-horizon scenario modeling.
- Segmentation analysis across product configuration categories that clarifies how irrigated and non-irrigated solutions distribute across clinical workflows and procurement priorities.
- Application-driven demand mapping covering major arrhythmia treatment indications, enabling teams to align product positioning with the clinical pathways that generate the highest procedure frequency.
- Geographic revenue structure that breaks down where market activity is concentrated, helping commercial leaders prioritize launch sequencing, sales coverage, and partnership strategy.
- An in-depth competitive landscape chronicling the strategies, product architectures, and recent regulatory milestones shaping the positions of leading global manufacturers and emerging challengers.
- Market concentration measurement that quantifies the consolidation of revenue among top players, providing transparency into competitive barriers, pricing power, and the risk of share erosion for newer entrants.
- Regulatory and reimbursement context that ties recent clinical approvals and procedural coding frameworks to commercial viability, ensuring technology investments are evaluated against the practical realities of hospital reimbursement cycles.
This structure is deliberately designed to support a wide range of strategic use cases, including new market entry assessments, product portfolio optimization, partnership evaluation, and investor-facing market storytelling. By embedding segment-level analysis within a cohesive strategic narrative, the report helps decision-makers move from observation to execution.
Competitive Architecture and Recent Innovation Shifts
The competitive environment in cardiac RF ablation is defined by established multinational manufacturers, strong clinical-technology integration, and a series of recent breakthroughs that are altering procedural standards. Medtronic has continued to reinforce its electrophysiology portfolio with dual-energy approaches, including systems that pair high-definition mapping with both pulsed field and radiofrequency capabilities. Its recent regulatory milestones underscore an industry-wide shift toward all-in-one procedural solutions that reduce case complexity and streamline workflow for persistent atrial fibrillation and atrial flutter management.
Boston Scientific remains a central force through its temperature-controlled ablation portfolio, with catheter families built around contact force and impedance sensing capabilities that support consistent lesion formation. Johnson & Johnson MedTech, through its Biosense Webster business, contributes a similarly influential set of therapeutic RF catheters designed to work with advanced mapping navigation platforms, reinforcing integration between visualization and ablation delivery. Abbott maintains a strong position by supplying RF ablation technologies tailored to varied anatomical needs, ensuring that its portfolio aligns with diverse clinical protocols.
The competitive field also includes innovators pursuing differentiated navigation and delivery modalities. Stereotaxis has been advancing robotically navigated magnetic ablation systems, with recent FDA approval enabling broader use of magnetically guided RF catheters in supraventricular tachycardia and more complex cases. MicroPort EP continues to strengthen its presence through 3D navigation-compatible RF ablation platforms focused on drug-refractory symptomatic atrial fibrillation. Biotronik rounds out the competitive set with steerable tip RF catheter designs intended to support procedural efficiency across cardiac ablation cases.
These players are not competing solely on catheter specifications. They are competing on procedural confidence, integration with mapping ecosystems, training support, and the ability to fit into institutional purchasing models that reward predictable outcomes. Recent approvals for robotically navigated and dual-energy platforms illustrate how quickly the competitive frontier is moving. Any company operating in this space must evaluate whether its current product strategy anticipates a market where mapping, navigation, energy delivery, and workflow efficiency are increasingly bundled into a single value proposition.
Regulatory and Reimbursement Signals Shaping Commercial Reality
Product innovation cannot be evaluated in isolation from the regulatory and reimbursement structures that determine adoption speed. The recent approval activity surrounding advanced ablation and mapping systems demonstrates that regulatory pathways are enabling more versatile procedural platforms. At the same time, procedural coding frameworks for intracardiac electrophysiologic procedures continue to support facility payments for mapping and ablation cases within prevailing reimbursement models. This alignment between coding structure and procedural complexity helps sustain hospital willingness to acquire advanced RF catheter platforms, especially when those platforms reduce total case time or expand the range of patients who can be treated in a single session.
Yet reimbursement stability also introduces strategic caution. As procedural payment pathways adapt to evolving device use, manufacturers and providers must closely monitor how coding updates, DRG classification practices, and facility purchasing constraints influence adoption velocity. The latest research addresses these forces directly, connecting regulatory milestones and procedural payment dynamics to practical commercial consequences. This ensures that strategy teams evaluate demand not only in terms of clinical need, but also in terms of payment architecture, procurement timing, and institutional purchasing behavior.
Worldwide 2D Ablation Catheter Market
Market Concentration and the Strategic Stakes Ahead
The worldwide market exhibits a high degree of top-tier concentration, with a substantial share of total revenue captured by a small group of dominant manufacturers. This concentration reflects the strength of established clinical relationships, the advantage of integrated mapping and ablation ecosystems, and the scale required to support global distribution, regulatory compliance, and post-market clinical evidence generation. At the same time, it signals meaningful barriers for new entrants and emphasizes the importance of differentiated technology or highly targeted clinical value propositions.
Concentration also influences pricing dynamics, channel negotiation leverage, and the pace at which innovation is commercialized. Companies operating within this environment must decide whether to compete through incremental enhancement within established workflows, or pursue step-change differentiation that alters procedural expectations. The strategic implications of concentration become especially important when forecasting share movement across 2026 and beyond, as regulatory approvals, procedural adoption, and regional demand patterns interact to reshape the competitive hierarchy.
Positioning for 2026 and Beyond
As management teams build 2026 strategies, the key question is no longer whether the cardiac RF catheter market is expanding, but how to convert expansion into durable advantage. Growth is being shaped by catheter performance improvements, advanced navigation and mapping integration, evolving reimbursement conditions, and a competitive landscape that continues to consolidate around a few high-impact platforms. Companies that treat this moment as a pure revenue opportunity may miss the deeper structural shifts underway. Companies that use detailed market intelligence to align product development, commercial execution, and competitive positioning will be better prepared to secure treatment volume, defend share, and enter adjacent opportunities with clarity.
Our Worldwide Cardiac Radiofrequency Catheter Market research is designed to support exactly that level of decision-making. It provides the segmentation detail, competitive profiles, concentration analysis, and market trajectory context required to move from high-level awareness to concrete strategy. The full study contains the granular regional, application, and product-type breakdowns, along with complete company profiles and development timelines, that underpin robust forecasting and planning. For teams that need accurate, structured intelligence before finalizing strategy, capital plans, or commercial roadmaps, the complete dataset remains the most direct path to confident execution.
For detailed analysis of this topic, please visit the official page: Worldwide Cardiac Radiofrequency Catheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Outdoor Sound Barriers Market to Hit USD 9.11 Billion by 2032
By pmarketresearch, 2026-09-16
Navigating the Acoustic Frontier: Strategic Intelligence for the Global Outdoor Sound Barriers Market 2026–2032
As urbanization accelerates and industrial activity expands across emerging and developed economies, environmental noise has evolved from a nuisance into a measurable public health and regulatory challenge. In response, outdoor sound barriers have transitioned from passive infrastructure components to engineered acoustic solutions that command dedicated market attention. Our newly released Worldwide Outdoor Sound Barriers Market research provides a structured, forward-looking intelligence framework designed specifically for executive decision-makers operating in transportation, industrial, construction, and municipal planning sectors. This report is not a static snapshot. It is a decision architecture built to help organizations anticipate capacity allocation, material selection, compliance exposure, and competitive positioning through 2032.
The global market registered an estimated valuation of US$6,450.0 million in the 2025 base year, building on a compound annual growth trajectory of 5.06 percent across the 2026–2032 forecast horizon. Historical data from 2020 through 2025 reveals a market that has consistently absorbed demand shocks, supply chain recalibration, and shifting procurement cycles while maintaining directional upward momentum. The forecast period projects sustained expansion, with the market reaching a multi-year inflection point as infrastructure renewal programs, noise mitigation mandates, and temporary acoustic deployment models converge. Rather than presenting these figures as isolated metrics, the research embeds them within a layered analytical model that connects macro demand signals to procurement realities, engineering standards, and commercial execution strategies.
For corporate strategists, the value of this study lies in its ability to convert broad market growth into actionable planning parameters. The 5.06 percent CAGR should not be read as a uniform rate of expansion but as a directional compass indicating where investment, inventory planning, and channel development will yield the highest marginal returns. Organizations that treat outdoor acoustic barriers as a commoditized construction input risk misallocating capital and conceding share to competitors who understand the market’s segmentation logic, regional procurement behaviors, and technology adoption curves. This research is designed to close that gap.
Market Structure and Demand Architecture
The report deconstructs the market across three primary analytical dimensions: material type, application vertical, and geographic region. Each dimension is evaluated not merely for its current share but for its momentum, pricing sensitivity, and dependency on external cost drivers. Metal-based barrier systems continue to anchor a substantial portion of absolute demand, supported by highway modernization programs, industrial site expansion, and standardized procurement frameworks. Concrete barrier solutions retain a durable footprint, particularly where permanence, structural load tolerance, and long-life lifecycle expectations outweigh initial material cost considerations. Transparent barrier configurations and wood-composite alternatives represent growing niches shaped by aesthetic integration requirements, residential and commercial site constraints, and retrofit use cases where visual openness or rapid installation is prioritized.
On the application side, the market’s demand architecture is heavily weighted toward ground transportation corridors, where highway noise attenuation remains the central use case and where public-sector procurement cycles dictate volume timing. Industrial and construction deployments form a second major demand pillar, driven by site-sensitive operations, temporary project phasing, and equipment-intensive environments that require flexible acoustic containment. Residential and commercial applications, while smaller in aggregate volume, represent a strategically important segment in which localized noise complaints, municipal compliance programs, and aesthetic considerations shape procurement specifications. The research traces how these application segments interact with material selection, installation methods, and service-life expectations, enabling buyers and suppliers to map demand drivers to realistic commercial scenarios.
Geographically, the market exhibits a mature, diversified structure rather than a single dominant engine. Demand is broadly distributed across developed and developing regions, with distinct procurement rhythms, regulatory intensity, and project pipeline characteristics shaping local performance. The study analyzes regional dynamics in terms of project velocity, infrastructure spending directionality, and adaptation to noise compliance expectations, allowing readers to identify where localized sourcing, partnership models, or export strategies may be most effective. Crucially, the report keeps the focus on decision-relevant patterns rather than isolated percentage breakdowns, preserving full regional and vertical quantification for the complete dataset.
Regulatory Evolution and Cost Dynamics as Strategic Variables
External conditions are reshaping both the technical specification and the commercial economics of outdoor sound barriers. Regulatory frameworks are becoming more precise, more enforceable, and more internationally aligned. Recent updates to noise prediction and propagation modeling standards have raised the bar for engineering accuracy, requiring barrier designs to be validated against more rigorous attenuation calculation methods. Alongside this, new outdoor equipment noise emission regulations and revised reporting requirements are tightening the compliance environment for operators and contractors who must demonstrate measurable noise reduction performance. These developments reinforce demand for barriers that can be specified, documented, and verified with greater confidence, favoring suppliers and systems that provide transparent performance data and repeatable installation outcomes.
Material cost volatility introduces an equally important strategic variable. Steel pricing, which directly influences the economics of metal barrier systems, experienced meaningful upward pressure through 2025 before stabilizing within a range-bound framework. This pricing environment affects procurement timing, contract structuring, and margin management for manufacturers and integrators. The report examines how raw material trajectories interact with lead-time planning, value engineering decisions, and specification substitution logic, helping organizations anticipate cost pressure rather than simply absorb it. For buyers, this means understanding when to lock in specifications, when to evaluate composite or hybrid alternatives, and how to structure tenders that protect performance requirements without overexposing budgets to commodity swings.
These regulatory and cost dynamics are not peripheral concerns. They influence which product categories gain specification share, which installation models become preferred, and which suppliers can sustain competitive positioning through cycles of input inflation and standard tightening. The research places these forces inside a cohesive operating environment analysis, enabling readers to connect external shifts to internal planning assumptions.
Worldwide Rockfall Barrier Market
Competitive Landscape and Commercial Differentiation
The market’s competitive field is defined by a mix of long-established acoustics manufacturers, specialist barrier engineers, and temporary-deploy solutions providers. Each player brings a distinct commercial posture shaped by product architecture, target verticals, and geographic reach. Companies with decades of experience in fully absorptive high-performance barrier walls continue to emphasize noise reduction performance for highways, industrial facilities, oil and gas sites, and commercial infrastructure. Their positioning rests on engineering heritage, repeatability of acoustic outcomes, and project-scale deployment capability.
Other firms compete through turn-key absorptive and reflective wall solutions designed for municipal, residential, and infrastructure mitigation programs. Their value proposition combines engineered performance with integrated project delivery, allowing clients to reduce specification friction and accelerate deployment. A parallel competitive track belongs to manufacturers of temporary and portable acoustic barriers, which serve construction, events, rail, highway, and demolition environments where rapid deployability and flexible hire-or-purchase models matter more than permanence. These players have broadened the market’s tactical applications, creating demand channels that complement fixed installations and enabling noise management during phased project activity.
Additional participants contribute through lightweight panel systems, durable exterior barrier panels, custom noise control configurations, and retrofit fencing solutions designed to absorb sound while preserving structural or aesthetic requirements. Their product ranges extend from high-wind-load outdoor acoustic fencing to sound-absorbing fence inserts that convert existing perimeter structures into functional noise barriers. The presence of these varied offerings underscores a market in which differentiation is increasingly driven by application specificity, installation speed, durability under local environmental conditions, and the clarity of performance documentation.
Recent corporate activity reflects this competitive maturation. Product information updates have reinforced emphasis on measurable decibel reduction for commercial and infrastructure projects. New exterior barrier releases have expanded the options available for outdoor applications requiring durable, visually integrated acoustic screens. Trade show participation and content updates signal continued investment in customer engagement, specification support, and solution visibility across industrial and infrastructure audiences. Rather than treating these moves as isolated announcements, the report contextualizes them within competitive positioning trends, revealing which capabilities are becoming table stakes and which remain genuine differentiators.
Market concentration remains moderate, indicating a field in which scale advantages exist but do not fully dictate outcomes. This structure leaves room for specialist firms, regional integrators, and application-focused suppliers to compete on performance credentials, service responsiveness, and specification alignment. For procurement leaders and market entrants, understanding where concentration applies and where fragmentation persists is essential for shaping sourcing strategy, partnership decisions, and market entry sequencing.
What the Full Study Delivers for 2026 Decision-Making
This summary outlines the strategic terrain. The complete report converts that terrain into a working intelligence asset. Inside the study, readers will find structured analysis connecting demand drivers, material and application segmentation, and regional procurement behavior to practical planning choices. The research evaluates how specification trends, installation approaches, and performance verification expectations are shaping purchasing decisions across transportation, industrial, and commercial use cases. It examines supplier capability mapping, competitive positioning patterns, and the operational factors that distinguish barriers suited to permanent infrastructure from those optimized for temporary deployment or retrofit scenarios.
The full report also integrates regulatory and cost environment analysis with market structure, allowing decision-makers to assess how noise standard evolution, material price behavior, and regional compliance intensity may alter specification priorities and procurement timing. It outlines the application segments and material categories that are gaining momentum, while preserving the detailed quantification and granular comparison tables for the complete dataset. In doing so, it provides a basis for capacity planning, product portfolio decisions, tender design, supplier evaluation, and market expansion sequencing.
For organizations preparing capital allocation, sourcing strategy, or competitive response plans for the 2026–2032 period, the study offers a disciplined reference point. It is built to support scenario evaluation rather than simple forecast reading, helping executives determine where outdoor sound barrier demand is most likely to intensify, where specification risk is highest, and where commercial advantage can be earned through technical credibility and deployment flexibility.
Conclusion
The worldwide outdoor sound barriers market is entering a phase in which growth, regulation, material economics, and competitive differentiation intersect more tightly than in prior cycles. Demand is broadening beyond traditional highway corridors into industrial, construction, and commercial environments, while performance verification and compliance expectations are rising in parallel. Suppliers and buyers alike must navigate this environment with clearer specification logic, more resilient procurement planning, and a better understanding of where acoustic value is actually created and measured.
Worldwide Outdoor Sound Barriers Market
Our worldwide outdoor sound barriers market research is designed to give organizations that understanding. It translates macro growth signals into structured strategic insight, maps the competitive field without reducing it to surface-level rankings, and places regulatory and cost dynamics where they belong: inside the decision process. For a complete view of market sizing, segmentation detail, competitive profiling, and forward indicators through 2032, we invite decision-makers to access the full report and use its complete intelligence set to calibrate strategy with precision.
For detailed analysis of this topic, please visit the official page: Worldwide Outdoor Sound Barriers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Baggage Packaging Service Market to Hit $1.45B by 2032 at 6.51% CAGR
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the Global Baggage Packaging Service Market (2026-2032)
The global travel ecosystem is undergoing a profound transformation, driven by rising passenger volumes, heightened security protocols, and an urgent imperative for sustainability. At the intersection of these forces lies the Worldwide Baggage Packaging Service Market, a critical infrastructure segment that ensures luggage integrity, security compliance, and operational efficiency across international and domestic terminals. PW Consulting's latest comprehensive market research offers a definitive strategic compass for stakeholders preparing to navigate the complexities of this sector through 2032.
Worldwide Packaging Service Market
As enterprises formulate strategies for the 2026 fiscal year and beyond, understanding the macroeconomic trajectory, competitive nuances, and regulatory undercurrents of this market is no longer optional—it is a strategic necessity. This article outlines the core insights within our new report, highlighting how data-driven intelligence can empower decision-makers to capitalize on growth opportunities while mitigating emerging risks.
Executive Summary: A Market in Structured Expansion
The baggage packaging service industry has demonstrated remarkable resilience and consistent growth over the past half-decade. Drawing from extensive historical analysis spanning 2020 through 2025, our research indicates that the global market has expanded from a base of approximately 545.2 million USD to 935.0 million USD, reflecting a compound annual growth rate (CAGR) of 6.51 percent. This trajectory underscores the sector's fundamental alignment with broader trends in global aviation, including increased luggage volumes and the widespread adoption of protective packaging as a standard security and damage-prevention measure.
Looking ahead to the forecast period of 2026 through 2032, the market is projected to continue its upward momentum, reaching an estimated 1,453.93 million USD by 2032. The sustained growth rate reflects robust demand drivers across both international and domestic terminal applications, as well as ongoing innovations in wrapping technologies, materials, and service delivery models. For businesses operating in or adjacent to this space, the report provides a rigorous framework for scenario planning, investment allocation, and competitive positioning.
Decoding the Strategic Content of the Report
PW Consulting's Worldwide Baggage Packaging Service Market report is engineered to deliver actionable intelligence rather than generic market summaries. The analysis is structured to equip executives, investors, and operational leaders with granular insights that can be immediately integrated into strategic planning cycles. Key components of the report include:
- Market Sizing and Trajectory Modeling: Detailed historical and forecast revenue data, segmented by core dimensions that reveal where growth is concentrated and which sub-segments are poised for acceleration.
- Type and Application Landscape: A thorough examination of service modalities, from stretch film wrapping and strapping techniques to carton and box packaging solutions, alongside a breakdown of demand patterns across international terminals and domestic facilities.
- Regional Performance Analysis: An assessment of market dynamics across key geographic corridors, highlighting regional growth velocities, maturity levels, and localized demand drivers that shape pricing and service availability.
- Competitive Intelligence: Comprehensive profiles of leading operators, benchmarking of service offerings, and analysis of strategic maneuvers that are reshaping market share distribution.
- Regulatory and Material Dynamics: An in-depth exploration of how evolving legislation, raw material cost fluctuations, and sustainability mandates are influencing operational strategies and long-term viability.
By integrating these elements into a cohesive analytical narrative, the report enables stakeholders to identify white spaces, anticipate competitive threats, and align operational capabilities with market realities.
Navigating the Competitive Arena
The market exhibits a moderately concentrated structure, with the top three players commanding a combined share of approximately 42.18 percent and the top five entities collectively accounting for 58.45 percent. This concentration suggests a landscape where established players hold significant influence, yet ample room remains for differentiated service models, technological innovation, and regional expansion.
Several companies are defining the competitive frontier through distinct strategic approaches:
- Safe Bag S.p.A. (TraWell): Positioned as a world leader in airport baggage protection and tracing services, this Italian-headquartered firm operates across more than 50 airports globally. Its emphasis on 100 percent recyclable ultra-resistant film wrap, coupled with damage reimbursement options and proprietary wrapping machines, underscores a dual focus on durability and sustainability. The company recently advanced its technology portfolio with the launch of the next-generation SB-3000 automatic wrapping machine platform, which integrates NFC-based digital tracking and achieves a notable reduction in film consumption per bag.
- Secure Wrap: A United States-based provider offering TSA-authorized baggage protection services across multiple countries. Its value proposition centers on tamper-evident wrapping and a customer-centric approach that includes complimentary rewrapping following TSA inspections, reinforcing trust and convenience for travelers navigating security protocols.
- BagWrap: Operating from the United Kingdom, this supplier serves major airports and rail stations across Europe and the Middle East, including London Heathrow and Gatwick. Its focus on ultra-resistant protective film against damage, weather, and germs positions it as a reliable partner for high-traffic transit hubs seeking comprehensive luggage safeguarding.
- TrueStar Group S.p.A. (Wrap and Fly): A major global operator leveraging a franchise model to build an extensive network of airport locations. Known for efficient wrapping equipment and a strong international presence, the franchise approach enables scalable deployment while maintaining operational consistency across diverse markets.
- Seal & Go: A provider of premium baggage wrapping services with a distinct emphasis on sustainable materials. Active across UK, Ireland, and Australian airports, the company recently expanded its biodegradable film wrapping service to all UK airport locations as part of a broader sustainability initiative, aligning with consumer and regulatory expectations for eco-conscious offerings.
- Encalm Enwrap: Based in India, this operator delivers premium biodegradable baggage wrapping services at major airports including Delhi, Hyderabad, and Goa, reflecting a growing regional commitment to environmentally responsible packaging solutions.
- Wrap N' Fly and Excess Baggage Company: These operators contribute additional competitive depth, with Wrap N' Fly active at high-visibility locations such as Orlando International Airport, and Excess Baggage Company providing secure, hygienic luggage wrapping using ultra-resistant film across select UK and European airports.
The report delves deeper into each company's strategic positioning, service differentiation, and potential growth vectors, enabling stakeholders to benchmark against peers and identify partnership or competitive opportunities.
Market Dynamics: Regulations, Materials, and Sustainability Imperatives
Beyond competitive forces, the baggage packaging service market is shaped by a complex interplay of regulatory mandates, raw material economics, and shifting sustainability expectations. These dynamics will play an increasingly central role in shaping operational strategies and investment decisions through the forecast period.
Worldwide Baggage Packaging Service Market
Regulatory Landscape and Extended Producer Responsibility
A significant development influencing the sector is the proliferation of Extended Producer Responsibility (EPR) laws across multiple jurisdictions. In the United States, several states including California, Colorado, Oregon, and Minnesota have implemented or are in the process of implementing EPR legislation for packaging materials. These laws require producers to manage end-of-life costs and reporting obligations, with fees commencing between 2025 and 2027. By 2026, at least seven US states had enacted comprehensive EPR packaging legislation covering plastic films and other consumer packaging materials. For baggage packaging service providers, these regulatory shifts introduce new compliance considerations, potential cost structures, and operational adjustments that must be factored into long-term planning.
Material Trends and Cost Considerations
The industry relies predominantly on stretch film based on low-density polyethylene (LDPE) or linear low-density polyethylene (LLDPE) for protective wrapping. However, material costs and availability remain sensitive to macroeconomic conditions. As of early 2026, the US Producer Price Index for Plastics Packaging Film and Sheet Manufacturing reached 185.768, signaling upward cost pressures that can impact margin dynamics for service operators. Navigating these cost fluctuations requires strategic procurement decisions, efficiency improvements in film utilization, and, where feasible, investments in advanced wrapping equipment that optimize material usage.
Sustainability as a Strategic Imperative
Sustainability is no longer a peripheral concern but a core driver of consumer preference, airport partnerships, and regulatory compliance. Packaging providers are actively transitioning toward 100 percent recyclable or biodegradable films in response to airport and consumer demands. Some operators have committed to achieving 50 percent biodegradable adoption by 2027, reflecting a broader industry pivot toward environmentally responsible solutions. Companies like Safe Bag S.p.A. and Seal & Go are already leading this transition, leveraging recyclable and biodegradable materials to differentiate their offerings and align with the sustainability goals of airport stakeholders. The report analyzes how these sustainability trends are reshaping competitive dynamics, influencing procurement strategies, and creating new value propositions for eco-conscious travelers and terminal operators.
Strategic Recommendations for 2026 Decision-Makers
As organizations prepare for the 2026 operational year and plan for the medium term, several strategic priorities emerge from our analysis:
- Invest in Technology and Efficiency: The adoption of advanced wrapping equipment, digital tracking integration, and film optimization technologies can drive operational efficiency, reduce material costs, and enhance service quality. Companies that prioritize technological upgrading will be better positioned to manage margin pressures and differentiate their offerings.
- Embed Sustainability into Core Operations: The shift toward recyclable and biodegradable materials is accelerating. Operators should evaluate their material portfolios, explore sustainable alternatives, and align service messaging with the environmental expectations of airports, travelers, and regulators. Early movers in biodegradable adoption may capture premium positioning and strengthen partnership ties with sustainability-focused terminals.
- Monitor Regulatory Developments Closely: EPR laws and other packaging-related regulations are evolving rapidly. Proactive compliance planning, cost modeling, and engagement with regulatory frameworks will be essential to avoid operational disruptions and unexpected cost burdens.
- Leverage Regional Diversification: With demand patterns varying across international and domestic terminals and across geographic regions, businesses should assess where their service models align best with local market characteristics. Strategic expansion, partnership development, or service customization may unlock growth in high-potential corridors.
- Benchmark and Learn from Leaders: Understanding the strategies of established players—from franchise-based scaling to technology-driven efficiency and sustainability-focused branding—can inform competitive positioning and reveal opportunities for differentiation.
Conclusion: Turning Intelligence into Action
The Worldwide Baggage Packaging Service Market presents a landscape of sustained growth, evolving competitive dynamics, and increasing regulatory and sustainability complexity. For enterprises operating in this space, the difference between reactive adaptation and proactive strategic advantage lies in access to rigorous, forward-looking intelligence. PW Consulting's latest market research delivers precisely that: a comprehensive, data-rich analysis designed to inform decisions, guide investments, and illuminate the paths to long-term success.
To explore the full depth of our findings, including detailed market sizing, segmentation breakdowns, competitive profiles, and forward-looking scenario analysis, we invite you to access the complete report. Equip your organization with the insights needed to navigate 2026 and beyond with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Baggage Packaging Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com