

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insight: Worldwide Dermabrasion and Microneedling Market to Hit $1.876B by 2032, CAGR 8.5%

Navigating the Resurfacing Renaissance: Strategic Insights for the 2026 Dermabrasion and Microneedling Market
The global landscape for skin resurfacing is undergoing a transformative shift, driven by an aging population, rising aesthetic consciousness, and rapid technological innovation. For stakeholders operating within the medical aesthetics sector, understanding the trajectory of the Worldwide Dermabrasion and Microneedling Market is no longer optional—it is a strategic imperative. This analysis serves as an introduction to our comprehensive market research report, designed to equip executives, investors, and product leaders with the intelligence needed to navigate the complexities of the 2026 fiscal year and beyond.
As we move through the mid-2020s, the convergence of procedural demand and device sophistication has created a fertile environment for growth. However, this growth is not uniform. It is fragmented by regulatory hurdles, reimbursement variances, and shifting competitive dynamics. Our latest study dissects these layers, offering a roadmap for capitalizing on emerging opportunities while mitigating operational risks.
Microneedling Cartridges Market
Market Trajectory and Macroeconomic Context
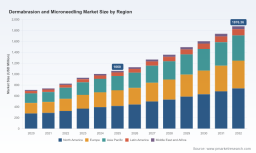
The financial magnitude of this sector underscores its importance within the broader aesthetic industry. According to our longitudinal analysis, the market has demonstrated robust resilience and expansion over the past half-decade. Valued at over 710 million USD in 2020, the industry has consistently climbed, surpassing the 1 billion USD milestone in 2024. Projections for 2026 indicate the market value will reach approximately 1127 million USD, reflecting a steady acceleration in adoption rates across both clinical and consumer segments.
Looking further ahead, our forecast period extends to 2032, where we anticipate the market will push toward the 1.8 billion USD mark. This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 8.5 percent during the 2026 to 2032 forecast window. This rate suggests that the sector will significantly outpace general medical device market averages, highlighting the premium placed on non-invasive and minimally invasive skin rejuvenation technologies.
Several macroeconomic and social drivers fuel this momentum. Increasing disposable incomes in emerging economies allow greater access to elective aesthetic procedures. Simultaneously, demographic shifts in developed regions are prompting older populations to seek treatments that offer significant cosmetic improvement with reduced downtime. The demand for treatments that bridge the gap between topical skincare and surgical intervention is central to this expansion, positioning both dermabrasion and microneedling technologies as critical components of modern dermatological portfolios.
Strategic Segmentation and Application Analysis
Our research provides a granular breakdown of the market structure to help firms identify where value is being generated. The industry is primarily bifurcated by technology type, with microneedling devices commanding a significant portion of the revenue share due to their versatility and expanding indications. Dermabrasion devices, while historically foundational, continue to hold relevance in specific surgical contexts, though their growth dynamics differ from the newer energy-based microneedling platforms.
End-user segmentation further illuminates the path to market. Dermatology clinics remain the dominant channel for procedural volume, leveraging specialized expertise to drive premium pricing. Hospitals contribute a substantial share, particularly where skin resurfacing is integrated into broader reconstructive or therapeutic plans. However, a notable shift is occurring within home use settings. The rise of consumer-grade devices indicates a blurring line between professional and personal care, opening new revenue streams for manufacturers who can ensure safety and efficacy in non-clinical environments.
Confidence in this growth is supported by market concentration metrics. Our data indicates a CR3 concentration of approximately 38.45 percent and a CR5 concentration of 52.12 percent. This suggests a moderately competitive landscape where top-tier players hold significant sway, yet there remains ample room for innovation and market entry by specialized firms. Understanding the balance between established dominance and niche opportunity is vital for strategic planning.
Worldwide Dermabrasion and Microneedling Market
Regulatory Framework and Operational Dynamics
Navigating the regulatory environment is one of the most critical challenges for participants in this market. The classification of devices dictates the path to market and influences operational costs. Microneedling devices for aesthetic use are typically classified as Class II medical devices under 21 CFR 878.4430. This classification requires 510(k) premarket notification with special controls, ensuring that safety and effectiveness are demonstrated before widespread commercialization. Compliance with these standards is not merely a legal requirement but a competitive differentiator that builds trust with practitioners and patients alike.
Conversely, dermabrasion devices often fall under Class I classifications, either manual or motorized, and are generally exempt from 510(k) premarket notification, subject to specific limitations outlined in 21 CFR 878.9. While this lowers the barrier to entry for traditional dermabrasion tools, it also intensifies competition on price and distribution efficiency. However, recent safety communications from regulatory bodies have highlighted potential risks associated with certain radiofrequency (RF) microneedling uses, including burns and nerve injuries, particularly when unregulated devices or unlicensed operators are involved. This heightened scrutiny emphasizes the need for rigorous training and adherence to safety protocols.
Reimbursement policies add another layer of complexity. Current procedural terminology (CPT) codes 15780-15783 are utilized for dermabrasion procedures, applicable in contexts involving skin resurfacing. However, many microneedling and aesthetic procedures often fall under unlisted codes or are categorized as cosmetic treatments with limited insurance coverage. This dynamic requires businesses to develop flexible pricing models and clearly communicate value propositions to patients who are often paying out-of-pocket. Understanding the nuances of billing and payer policies is essential for maintaining healthy cash flows in clinical settings.
Competitive Landscape and Key Corporate Movements
The competitive arena is populated by a diverse mix of established medical device giants and specialized aesthetic innovators. Key players shaping the market include Crown Aesthetics (Revance), which has established a strong position with the SkinPen Precision, recognized as the first FDA-cleared microneedling device for improving facial acne scars and neck wrinkles. Candela Medical continues to expand its portfolio with RF microneedling devices and hydro-infusion systems, catering to high-demand aesthetic clinics. Lumenis and Cynosure provide complementary aesthetic devices supporting skin resurfacing, while Cutera and Alma Lasers offer laser and energy-based platforms essential for comprehensive skin treatment regimens.
Regional players are also making significant impacts. Lutronic from South Korea manufactures RF microneedling and energy-based devices that are gaining traction globally. InMode offers minimally invasive aesthetic platforms, while DermapenWorld specializes in professional microneedling pens. On the surgical instrument side, Stryker, CONMED Corporation, and MicroAire Surgical Instruments supply devices applicable to dermabrasion procedures, ensuring the traditional segment remains robust. Furthermore, Dermalogica has entered the medical device space with the FDA-cleared PRO Pen Microneedling System, and Emage Medical provides FDA-cleared devices including CytoPen and Cyto-RF systems.
Recent corporate developments underscore the pace of innovation. In a notable move, Dermalogica officially launched the FDA-cleared PRO Pen Microneedling System in April 2026. This launch marks the company's first foray into FDA-cleared medical devices for improving facial acne scars in adults. This follows regulatory clearance received in September 2025, with US distribution beginning in 2026. Such moves signal a trend where skincare brands are bridging into medical device territory, intensifying competition and raising the bar for product efficacy and regulatory compliance.
Technological Drivers and Future Outlook
Innovation remains the primary engine for market differentiation. The industry is witnessing a shift toward devices that offer enhanced precision, reduced patient discomfort, and faster recovery times. Radiofrequency microneedling, in particular, is evolving to deliver controlled thermal energy at varying depths, optimizing collagen induction while minimizing epidermal damage. Manufacturers are increasingly focusing on user experience, integrating intuitive interfaces and disposable components to streamline clinic operations and reduce cross-contamination risks.
The intersection of technology and consumer preference is also driving demand for combination therapies. Practitioners are seeking platforms that can address multiple concerns—such as texture, tone, and laxity—in a single session. This demand encourages companies to develop modular systems or bundled offerings that maximize treatment value. Additionally, the rise of teledermatology and digital consultation tools is influencing how devices are marketed and prescribed, requiring companies to adapt their go-to-market strategies for a hybrid care model.
Conclusion: The Imperative for Actionable Intelligence
For enterprises operating in the Worldwide Dermabrasion and Microneedling Market, the margin for error is narrowing. The combination of strong growth projections, evolving regulatory standards, and aggressive competition demands a data-informed approach to strategy. Whether assessing market entry opportunities, optimizing product portfolios, or refining pricing strategies, reliance on outdated or aggregated data can lead to suboptimal decisions.
Our full market research report delves deeper into these dynamics, offering detailed revenue forecasts, segmented analysis, and strategic recommendations tailored to specific business models. We provide the granular data necessary to validate assumptions and uncover hidden risks. For stakeholders ready to secure their position in this expanding sector, accessing comprehensive intelligence is the first step toward sustainable growth. We invite you to explore the complete findings and leverage these insights to drive your strategic agenda in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Dermabrasion and Microneedling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com