

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Outdoor Sound Barriers Market to Hit USD 9.11 Billion by 2032

Navigating the Acoustic Frontier: Strategic Intelligence for the Global Outdoor Sound Barriers Market 2026–2032
As urbanization accelerates and industrial activity expands across emerging and developed economies, environmental noise has evolved from a nuisance into a measurable public health and regulatory challenge. In response, outdoor sound barriers have transitioned from passive infrastructure components to engineered acoustic solutions that command dedicated market attention. Our newly released Worldwide Outdoor Sound Barriers Market research provides a structured, forward-looking intelligence framework designed specifically for executive decision-makers operating in transportation, industrial, construction, and municipal planning sectors. This report is not a static snapshot. It is a decision architecture built to help organizations anticipate capacity allocation, material selection, compliance exposure, and competitive positioning through 2032.
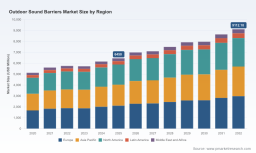
The global market registered an estimated valuation of US$6,450.0 million in the 2025 base year, building on a compound annual growth trajectory of 5.06 percent across the 2026–2032 forecast horizon. Historical data from 2020 through 2025 reveals a market that has consistently absorbed demand shocks, supply chain recalibration, and shifting procurement cycles while maintaining directional upward momentum. The forecast period projects sustained expansion, with the market reaching a multi-year inflection point as infrastructure renewal programs, noise mitigation mandates, and temporary acoustic deployment models converge. Rather than presenting these figures as isolated metrics, the research embeds them within a layered analytical model that connects macro demand signals to procurement realities, engineering standards, and commercial execution strategies.
For corporate strategists, the value of this study lies in its ability to convert broad market growth into actionable planning parameters. The 5.06 percent CAGR should not be read as a uniform rate of expansion but as a directional compass indicating where investment, inventory planning, and channel development will yield the highest marginal returns. Organizations that treat outdoor acoustic barriers as a commoditized construction input risk misallocating capital and conceding share to competitors who understand the market’s segmentation logic, regional procurement behaviors, and technology adoption curves. This research is designed to close that gap.
Market Structure and Demand Architecture
The report deconstructs the market across three primary analytical dimensions: material type, application vertical, and geographic region. Each dimension is evaluated not merely for its current share but for its momentum, pricing sensitivity, and dependency on external cost drivers. Metal-based barrier systems continue to anchor a substantial portion of absolute demand, supported by highway modernization programs, industrial site expansion, and standardized procurement frameworks. Concrete barrier solutions retain a durable footprint, particularly where permanence, structural load tolerance, and long-life lifecycle expectations outweigh initial material cost considerations. Transparent barrier configurations and wood-composite alternatives represent growing niches shaped by aesthetic integration requirements, residential and commercial site constraints, and retrofit use cases where visual openness or rapid installation is prioritized.
On the application side, the market’s demand architecture is heavily weighted toward ground transportation corridors, where highway noise attenuation remains the central use case and where public-sector procurement cycles dictate volume timing. Industrial and construction deployments form a second major demand pillar, driven by site-sensitive operations, temporary project phasing, and equipment-intensive environments that require flexible acoustic containment. Residential and commercial applications, while smaller in aggregate volume, represent a strategically important segment in which localized noise complaints, municipal compliance programs, and aesthetic considerations shape procurement specifications. The research traces how these application segments interact with material selection, installation methods, and service-life expectations, enabling buyers and suppliers to map demand drivers to realistic commercial scenarios.
Geographically, the market exhibits a mature, diversified structure rather than a single dominant engine. Demand is broadly distributed across developed and developing regions, with distinct procurement rhythms, regulatory intensity, and project pipeline characteristics shaping local performance. The study analyzes regional dynamics in terms of project velocity, infrastructure spending directionality, and adaptation to noise compliance expectations, allowing readers to identify where localized sourcing, partnership models, or export strategies may be most effective. Crucially, the report keeps the focus on decision-relevant patterns rather than isolated percentage breakdowns, preserving full regional and vertical quantification for the complete dataset.
Regulatory Evolution and Cost Dynamics as Strategic Variables
External conditions are reshaping both the technical specification and the commercial economics of outdoor sound barriers. Regulatory frameworks are becoming more precise, more enforceable, and more internationally aligned. Recent updates to noise prediction and propagation modeling standards have raised the bar for engineering accuracy, requiring barrier designs to be validated against more rigorous attenuation calculation methods. Alongside this, new outdoor equipment noise emission regulations and revised reporting requirements are tightening the compliance environment for operators and contractors who must demonstrate measurable noise reduction performance. These developments reinforce demand for barriers that can be specified, documented, and verified with greater confidence, favoring suppliers and systems that provide transparent performance data and repeatable installation outcomes.
Material cost volatility introduces an equally important strategic variable. Steel pricing, which directly influences the economics of metal barrier systems, experienced meaningful upward pressure through 2025 before stabilizing within a range-bound framework. This pricing environment affects procurement timing, contract structuring, and margin management for manufacturers and integrators. The report examines how raw material trajectories interact with lead-time planning, value engineering decisions, and specification substitution logic, helping organizations anticipate cost pressure rather than simply absorb it. For buyers, this means understanding when to lock in specifications, when to evaluate composite or hybrid alternatives, and how to structure tenders that protect performance requirements without overexposing budgets to commodity swings.
These regulatory and cost dynamics are not peripheral concerns. They influence which product categories gain specification share, which installation models become preferred, and which suppliers can sustain competitive positioning through cycles of input inflation and standard tightening. The research places these forces inside a cohesive operating environment analysis, enabling readers to connect external shifts to internal planning assumptions.
Worldwide Rockfall Barrier Market
Competitive Landscape and Commercial Differentiation
The market’s competitive field is defined by a mix of long-established acoustics manufacturers, specialist barrier engineers, and temporary-deploy solutions providers. Each player brings a distinct commercial posture shaped by product architecture, target verticals, and geographic reach. Companies with decades of experience in fully absorptive high-performance barrier walls continue to emphasize noise reduction performance for highways, industrial facilities, oil and gas sites, and commercial infrastructure. Their positioning rests on engineering heritage, repeatability of acoustic outcomes, and project-scale deployment capability.
Other firms compete through turn-key absorptive and reflective wall solutions designed for municipal, residential, and infrastructure mitigation programs. Their value proposition combines engineered performance with integrated project delivery, allowing clients to reduce specification friction and accelerate deployment. A parallel competitive track belongs to manufacturers of temporary and portable acoustic barriers, which serve construction, events, rail, highway, and demolition environments where rapid deployability and flexible hire-or-purchase models matter more than permanence. These players have broadened the market’s tactical applications, creating demand channels that complement fixed installations and enabling noise management during phased project activity.
Additional participants contribute through lightweight panel systems, durable exterior barrier panels, custom noise control configurations, and retrofit fencing solutions designed to absorb sound while preserving structural or aesthetic requirements. Their product ranges extend from high-wind-load outdoor acoustic fencing to sound-absorbing fence inserts that convert existing perimeter structures into functional noise barriers. The presence of these varied offerings underscores a market in which differentiation is increasingly driven by application specificity, installation speed, durability under local environmental conditions, and the clarity of performance documentation.
Recent corporate activity reflects this competitive maturation. Product information updates have reinforced emphasis on measurable decibel reduction for commercial and infrastructure projects. New exterior barrier releases have expanded the options available for outdoor applications requiring durable, visually integrated acoustic screens. Trade show participation and content updates signal continued investment in customer engagement, specification support, and solution visibility across industrial and infrastructure audiences. Rather than treating these moves as isolated announcements, the report contextualizes them within competitive positioning trends, revealing which capabilities are becoming table stakes and which remain genuine differentiators.
Market concentration remains moderate, indicating a field in which scale advantages exist but do not fully dictate outcomes. This structure leaves room for specialist firms, regional integrators, and application-focused suppliers to compete on performance credentials, service responsiveness, and specification alignment. For procurement leaders and market entrants, understanding where concentration applies and where fragmentation persists is essential for shaping sourcing strategy, partnership decisions, and market entry sequencing.
What the Full Study Delivers for 2026 Decision-Making
This summary outlines the strategic terrain. The complete report converts that terrain into a working intelligence asset. Inside the study, readers will find structured analysis connecting demand drivers, material and application segmentation, and regional procurement behavior to practical planning choices. The research evaluates how specification trends, installation approaches, and performance verification expectations are shaping purchasing decisions across transportation, industrial, and commercial use cases. It examines supplier capability mapping, competitive positioning patterns, and the operational factors that distinguish barriers suited to permanent infrastructure from those optimized for temporary deployment or retrofit scenarios.
The full report also integrates regulatory and cost environment analysis with market structure, allowing decision-makers to assess how noise standard evolution, material price behavior, and regional compliance intensity may alter specification priorities and procurement timing. It outlines the application segments and material categories that are gaining momentum, while preserving the detailed quantification and granular comparison tables for the complete dataset. In doing so, it provides a basis for capacity planning, product portfolio decisions, tender design, supplier evaluation, and market expansion sequencing.
For organizations preparing capital allocation, sourcing strategy, or competitive response plans for the 2026–2032 period, the study offers a disciplined reference point. It is built to support scenario evaluation rather than simple forecast reading, helping executives determine where outdoor sound barrier demand is most likely to intensify, where specification risk is highest, and where commercial advantage can be earned through technical credibility and deployment flexibility.
Conclusion
The worldwide outdoor sound barriers market is entering a phase in which growth, regulation, material economics, and competitive differentiation intersect more tightly than in prior cycles. Demand is broadening beyond traditional highway corridors into industrial, construction, and commercial environments, while performance verification and compliance expectations are rising in parallel. Suppliers and buyers alike must navigate this environment with clearer specification logic, more resilient procurement planning, and a better understanding of where acoustic value is actually created and measured.
Worldwide Outdoor Sound Barriers Market
Our worldwide outdoor sound barriers market research is designed to give organizations that understanding. It translates macro growth signals into structured strategic insight, maps the competitive field without reducing it to surface-level rankings, and places regulatory and cost dynamics where they belong: inside the decision process. For a complete view of market sizing, segmentation detail, competitive profiling, and forward indicators through 2032, we invite decision-makers to access the full report and use its complete intelligence set to calibrate strategy with precision.
For detailed analysis of this topic, please visit the official page: Worldwide Outdoor Sound Barriers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com