

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Heated Wiper Fluid Market Hits $192.4M in 2025, Projects 6.5% CAGR Through 2032

Navigating the Thermal Edge: Strategic Intelligence for the Heated Wiper Fluid Market, 2026–2032
As automotive electrification accelerates and climate extremes intensify, the heated windshield wiper fluid segment has evolved from a niche cold-climate accessory into a strategically relevant component of vehicle thermal and safety architecture. For executives, product planners, and supply chain leaders, the decisions made in 2026 will shape competitive positioning through the end of the decade. Our latest Worldwide Heated Wiper Fluid Market research is engineered to convert structural industry shifts into actionable commercial intelligence, framing a market that reached approximately 192.4 million USD in 2025 and is projected to cross the 299 million USD threshold by 2032, translating to a compound annual growth rate of 6.5 percent across the 2026–2032 forecast horizon.
This is not a retrospective snapshot. The base year 2025 embeds five years of historical trajectory (2020–2025) that illuminate how supply chain normalization, OEM thermal-management re-architecting, and expanding aftermarket channel maturity have compounded into today’s demand profile. From 142.15 million USD in 2020, the market progressed through 150.19 million USD in 2021, 162.5 million USD in 2022, 177.02 million USD in 2023, and 185.0 million USD in 2024 before reaching the current 192.4 million USD baseline. The forecast sequence—197.09 million USD in 2026, 218.79 million USD in 2027, 241.62 million USD in 2028, 247.71 million USD in 2029, 262.56 million USD in 2030, 274.86 million USD in 2031, and 299.01 million USD in 2032—reveals an inflection pattern where early-period growth gives way to accelerated expansion as regional adoption broadens and integration complexity increases. For leadership teams, the message is clear: the next twelve months are the decisive window to align sourcing, product development, and channel strategy before the forecast curve steepens.
Why 2026 Demands a Different Strategic Lens
The 2026 decision cycle carries structural weight that prior years did not. Three forces converge. First, component sourcing has become a constrained equation: the PTC heating elements required for heated washer systems now compete for supply with electric-vehicle battery thermal management modules and seat-heating arrays, meaning procurement strategies that worked in a standalone fluid-market context no longer suffice. Second, regulatory attention has sharpened around both safety and formulation standards, with historical recall episodes underscoring electrical-module vulnerabilities and contemporary petitions advocating standardized winter-grade washer fluids to mitigate cold-weather safety gaps. Third, the aftermarket is professionalizing at a pace that rewards early movers who can deliver validated thermal performance without compromising installation repeatability or fluid compatibility. The research is built to help organizations navigate these overlapping pressures with calibrated evidence rather than directional assumption.
Inside the Report: Operational Intelligence for Commercial Execution
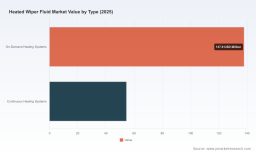
Our worldwide heated wiper fluid study is structured as a working document for strategy, not a static market summary. The analytical framework is organized around the decision points that actually drive P&L outcomes: segmentation by type, by application, and by region, each mapped to demand drivers, mix-shift trajectories, and substitution dynamics. The report examines the split between on-demand heating architectures and continuous heating systems, clarifying where consumer and fleet expectations diverge on energy draw, activation latency, and total cost of ownership. It also dissects the application landscape across passenger cars, light commercial vehicles, and heavy commercial vehicles, revealing how duty-cycle differences, uptime requirements, and procurement cycles create distinct margin and volume logic within each segment.
Regional demand architecture is analyzed through a lens of market maturity, climate-driven penetration, OEM-package penetration, and aftermarket channel density, without reducing the story to a single headline number. Instead, the research provides the comparative structure executives need to evaluate where to prioritize inventory, where to invest in localized formulation or distribution partnerships, and where regulatory or competitive intensity compresses pricing power. The concentration analysis—anchored by a top-three combined share of 42.15 percent and a top-five combined share of 58.4 percent—frames the axis of competition: a market that is meaningfully consolidated at the top yet still open enough to reward differentiated technology, channel reach, and formulation expertise.
Beyond segmentation, the study integrates supply-side realism. Heated wiper fluid formulations typically rely on methanol-blended winter chemistries engineered for low-temperature freeze protection, introducing toxic, flammable, and hazardous-waste considerations that affect blending, logistics, and end-of-life handling. The report addresses how these material constraints shape manufacturing footprints, compliance costs, and aftermarket substitution behavior. On the hardware side, it maps the interplay between fluid chemistry and heating-element performance, providing the cross-functional context needed for product managers who must simultaneously optimize thermal output, fluid compatibility, and system durability.
Competitive Landscape: Specialized Leaders and Converging Supply Chains
The competitive field in heated wiper fluid is defined by companies operating at the intersection of fluid chemistry, thermal hardware, and vehicle-package integration. The research includes detailed profiles of the participants shaping both OEM specification and aftermarket replacement demand, capturing capability sets, go-to-market posture, and where each player is investing next.
Valeo S.A. exemplifies the integrated-system approach, offering heated wiper and washer functionality through platforms such as AquaBlade that span OEM and aftermarket channels and are purpose-built to mitigate freezing effects in severe climates. In April 2025, Valeo Service expanded availability of heated AquaBlade premium wiper blades, broadening part-number coverage for cold-climate service applications. Kautex Textron GmbH & Co. KG and Denso Corporation round out the hardware integration dimension, supplying fluid-management and washer-system components that support heated washer fluid architectures at the vehicle level. Their relevance extends beyond discrete parts: as OEMs rebalance thermal budgets across cabin, battery, and wash systems, the firms that can deliver compactly integrated heating and fluid-handling solutions gain specification leverage.
On the fluid-supply side, Recochem Inc., CCI Corporation (Genuine Chemistry), and China Hong Wipers represent the formulation and OEM-supply axis. Recochem operates as a global automotive-fluid manufacturer with temperature-protection formulations suited to heated systems, while CCI Corporation serves as an OEM washer-fluid supplier to major automotive, heavy-equipment, and powersports manufacturers, including a 2025 AAPEX presence that reinforced its role in the global genuine-chemistry supply chain. China Hong Wipers occupies a distinct export-oriented position, supplying heated washer fluid systems and heater components across global aftermarket and OEM channels.
Heated Windshields Market
The aftermarket landscape adds a second competitive layer. SPLASH Products Inc. (Factory Motor Parts) manufactures winter and de-icing washer formulations with U.S.-based production for aftermarket distribution, and Old World Industries (OWI) serves commercial and automotive markets through washer-fluid brands such as Blue Mountain. Specialized heated-system aftermarket players—including AlphaTherm via its Donmar/HotShot lineage and HydroBlast (Kleinn)—have pushed thermal-performance expectations upward, with aftermarket heaters engineered to raise fluid temperature to approximately 132°F for frost and snow removal. These offerings matter strategically because they set performance benchmarks that OEM packages must either meet or explicitly differentiate against.
Worldwide Heated Wiper Fluid Market
One of the most telling competitive signals comes from the broader OEM trajectory. In May 2023, Ford Motor Company filed a patent for a heated windshield washer bottle system designed to warm fluid electrically for improved cold-weather performance in future vehicles. That filing is not simply a product hint; it signals where thermal-management architecture is heading and why fluid, container, and heating-module design are increasingly inseparable in the product roadmap.
The Dynamics That Will Shape Margin, Mix, and Risk Through 2032
The market’s trajectory is not driven by demand alone. Several structural dynamics will determine which participants convert growth into durable advantage.
Historical safety experience remains a cautionary reference point. General Motors previously issued recalls for 2006–2008 model-year vehicles equipped with heated windshield washer fluid systems due to short-circuit risks in the heating module that could lead to overheating, smoke, or fire. That episode contributed to broader OEM caution, and GM subsequently discontinued factory heated windshield washer fluid systems on many models following recalls tied to fire-hazard concerns in the heating module. The strategic implication is not that heated systems are unviable; it is that validation rigor, electrical integration discipline, and failure-mode design now function as competitive prerequisites rather than optional engineering polish.
Regulatory and standardization pressure is building on the fluid side as well. U.S. FMVSS 104 governs windshield wiping and washing systems, and recent policy attention has included a 2019 petition seeking standardized winter-specification washer fluid year-round to address safety concerns arising when summer formulations are used in cold conditions. These discussions matter because they can alter formulation defaults, testing expectations, and aftermarket substitution behavior, especially in markets where temperature variability makes fluid-grade consistency a safety and usability issue.
Material and component constraints add another dimension. Methanol-based winter blends provide freeze protection but introduce toxicity, flammability, and hazardous-waste considerations that influence handling, distribution, and reclamation economics. At the same time, the PTC heating elements that underpin heated washer systems compete with supply allocated to EV battery thermal management and seat-heating applications. For procurement and product-strategy teams, that means cost modeling and supply security must be evaluated within a wider thermal-component ecosystem, not in isolation. The research embeds these constraints into sourcing scenarios so that plans reflect practical availability and compliance exposure rather than idealized input assumptions.
How to Use This Research in 2026 Decision-Making
The most valuable use of this study is as a cross-functional alignment tool. For product and engineering leaders, it frames the trade-space between on-demand and continuous heating architectures, the implications of fluid chemistry on system performance, and the increasing need to treat washer-fluid heating as part of a broader thermal-management strategy. For commercial and channel teams, it maps where regional demand is consolidating around climate exposure, OEM penetration, and aftermarket density, enabling more precise inventory allocation and go-to-market sequencing. For procurement and supply chain leaders, it situates component availability and formulation compliance within realistic constraints, including the PTC element supply contest and hazardous-material handling requirements. For corporate strategy and M&A teams, the concentration profile and participant capabilities provide a basis for evaluating where consolidation pressure may intensify and where differentiated specialty players can sustain premium positioning.
The study is also designed to shorten the distance between analysis and execution. Rather than presenting market potential as a single abstract figure, it organizes the intelligence around the operational questions that determine whether a market entry, capacity decision, or channel investment will hold up under competitive and regulatory scrutiny. The 2026–2032 forecast sequence is used not as a forecast to be read passively, but as a planning scaffold for scenario-building around adoption pace, mix evolution, and the timing of competitive responses from both integrated suppliers and specialized aftermarket players.
Closing Perspective
The worldwide heated wiper fluid market is entering a phase in which growth and complexity reinforce each other. Demand is expanding, but the winners will be determined by how effectively organizations manage the technical, regulatory, and supply-chain subtleties that surround that expansion. This research is built to give decision-makers the evidentiary foundation to act with confidence in 2026 and to prepare for the acceleration projected through 2032. The full segmentation architecture, company-level strategic assessments, comparative regional analysis, and forecast detail contained in the complete study provide the granularity required to convert high-level momentum into executable advantage. For leadership teams ready to move from market awareness to structured positioning, the full report offers the complete intelligence set needed to make those choices with precision.
For detailed analysis of this topic, please visit the official page: Worldwide Heated Wiper Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com