

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Tissue Sectioning Market to Hit $1,305.28M by 2032, Growing at 6.42% CAGR, Says PW Consulting

Navigating the Precision Frontier: Strategic Insights for the Global Tissue Sectioning Market in 2026
In the evolving landscape of histopathology, diagnostics, and life sciences research, the precision of tissue preparation remains a cornerstone of reliable outcomes. As laboratories and pharmaceutical enterprises face mounting pressures to accelerate workflows, reduce reagent consumption, and integrate digital pathology platforms, the tissue sectioning equipment segment stands at a pivotal inflection point. Our latest Worldwide Tissue Sectioning Market study has been engineered to serve as a decision-grade intelligence asset for executives, procurement leaders, and R&D strategists who must navigate the 2026–2032 horizon with clarity. Rather than relying on fragmented vendor claims or outdated benchmarks, this report consolidates multi-year trajectory analysis, competitive positioning, and regulatory-technological crosscurrents into a single strategic reference layer.
Why 2026 Demands a Hard Look at Sectioning Infrastructure
The global tissue sectioning market has expanded from approximately 610.15 million USD in 2020 to 845.5 million USD in the base year of 2025. This trajectory reflects more than a simple growth curve; it mirrors a structural shift in how laboratories allocate capital, how diagnostic workflows are redesigned, and how equipment vendors are being held accountable for throughput, reproducibility, and integration readiness. With a forecast period spanning 2026 through 2032 and a compound annual growth rate of 6.42 percent, the market is entering a phase where incremental procurement decisions can either lock organizations into efficiency bottlenecks or create long-term operational advantages. The 2026 forecast reading of 871.87 million USD and the subsequent step-up to 955.38 million USD by 2027 highlight a continued expansion that is neither uniform nor accidental. Growth is being reshaped by evolving end-user requirements, product-type substitution dynamics, and the gradual but unmistakable penetration of automation into workflows that historically favored manual or semi-automatic instruments.
For strategic planners, the critical implication is that 2026 is not a year for hedging behind legacy replacement cycles. It is a year for reassessing equipment roadmaps against throughput targets, digital pathology compatibility, consumable cost structures, and compliance exposure. Organizations that treat tissue sectioning as a purely mechanical procurement category risk underpricing the operational value of precision, reliability, and workflow integration. Those that map their capital allocation to the market’s actual growth drivers will be positioned to capture margin-preserving efficiencies while maintaining diagnostic integrity.
What the Research Delivers: From Macro Trajectory to Operational Decisions
This study is structured to give leadership teams more than headline figures. It translates the market’s total revenue evolution into a decision framework that can be applied directly to capital planning, vendor evaluation, and regional deployment strategies. The report covers the full 2020–2025 historical window and extends forecasting through 2032, allowing readers to distinguish short-term procurement inflection points from durable structural trends. All financial data is presented in USD, with revenue measured in millions, enabling direct comparison across internal budgeting cycles and external market benchmarks.
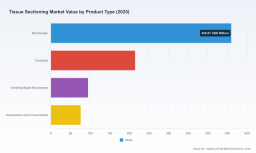
Beyond aggregate sizing, the analysis disaggregates the market across product types, end-user environments, and regional demand distributions. This segmentation is not developed as a static slice-and-dice exercise; instead, it is used to surface the relative capital intensity, replacement cadence, and workflow relevance associated with different categories of sectioning equipment. The report also addresses market concentration dynamics, offering context on how a consolidated share base shapes pricing behavior, service competition, and the strategic maneuvering room available to emerging and mid-tier participants. Readers will find that the concentration pattern in this market influences far more than vendor negotiations; it affects lead times for service, the predictability of consumable supply, and the incentive structure for innovation.
Competitive Landscape: Ten-Plus Players, Distinct Positions, and a Consolidating Center of Gravity
The market is anchored by a cohort of established manufacturers whose portfolios span microtomes, cryostats, and tissue sectioning systems, each aligned to a different mix of clinical diagnostics, research, and pharmaceutical applications. Thermo Fisher Scientific Inc., headquartered in Waltham, MA, brings a comprehensive portfolio of microtomes, cryostats, and tissue sectioning systems that span both automated and manual solutions for high-precision histology. This breadth positions the company to serve dual demand streams: clinical diagnostics where consistency and service coverage matter, and research applications where instrument flexibility is paramount.
Leica Biosystems Nussloch GmbH, based in Germany, specializes in advanced histology equipment including rotary microtomes and cryostats such as the CM1950, alongside automated tissue sectioning platforms designed for clinical and research pathology workflows. Its emphasis on workflow continuity and platform integration reflects the broader industry shift toward instruments that fit into digitalized diagnostic pipelines rather than operating as standalone mechanical devices. Sakura Finetek USA, Inc., in Torrance, CA, focuses its Tissue-Tek series on automated microtomes, cryostats, and embedding systems optimized for high-throughput tissue sectioning in pathology laboratories, making it a particularly relevant comparator for organizations prioritizing throughput and lab-scale standardization.
Epredia, headquartered in Portsmouth, NH, supplies cryostats, microtomes, and related consumables oriented toward precision diagnostics, digital pathology integration, and tissue sectioning for cancer diagnostics. Its positioning underscores a growing recognition that consumables and instrument ecosystems must be evaluated together, especially in environments where slide quality, reproducibility, and downstream molecular workflows are tightly coupled. Diapath S.p.A., in Martinengo, Italy, manufactures manual, semi-automatic, and automatic microtomes along with consumables tailored for histopathology tissue sectioning, giving it a presence across multiple automation tiers. SLEE medical GmbH, in Mainz, Germany, develops high-quality cryostats and microtomes emphasizing precision and reliability, while MEDITE GmbH, in Burgdorf, Germany, offers microtomes, cryostats, and tissue processing equipment for medical and research tissue sectioning needs.
The supplier field extends beyond these core players. RMC Boeckeler, in Tucson, AZ, produces ultramicrotomes and tissue sectioning instruments primarily for electron microscopy and advanced research applications, addressing a niche that demands extreme precision and specialized operational expertise. Bright Instrument Company Ltd, in Huntingdon, UK, specializes in cryostats and microtomes for immunology, pathology, and quality control laboratories, reflecting a channel where sectioning accuracy intersects with regulated testing workflows. MICROS Produktions- und Handelsgesellschaft m.b.H., based in Austria, manufactures a range of microtomes for industrial and laboratory tissue sectioning, offering another perspective on the spread between clinical and broader laboratory use cases. In the Asia-Pacific supply landscape, RWD Life Science Co., Ltd., in Shenzhen, China, provides Minux series semi-automatic and automatic rotary microtomes and cryostats for histopathology tissue sectioning, while Jinhua YIDI Medical Appliance Co., Ltd., in Jinhua, China, produces rotary microtomes and related equipment for laboratory tissue sectioning applications. These regional participants illustrate how local manufacturing presence, cost structures, and application focus can influence procurement geography, though their strategic relevance depends heavily on service infrastructure, total cost of ownership, and workflow alignment.
Worldwide Tissue Sectioning Market
Recent developments reinforce that competitive positioning is increasingly defined by platform integration rather than blade-quality claims alone. In January 2025, Leica Biosystems formed a strategic investment with Indica Labs to co-develop a combined scanner-AI platform supporting enhanced digital pathology workflows that integrate with tissue sectioning processes. This move signals a competitive logic in which sectioning equipment is being evaluated as part of a digitized continuum, not as an isolated instrument. In April 2025, Guardant Health launched Guardant360 Tissue, a DNA-RNA multiomics panel requiring 40 percent fewer slides, highlighting laboratory demand for optimized tissue sectioning efficiency in biopsy workflows. Even when the innovation originates outside the sectioning equipment category itself, it reshapes the value equation for sectioning precision, slide economy, and downstream consumable planning.
Market Dynamics and External Currents That Will Shape 2026 Decisions
Several structural forces are shaping how organizations should interpret equipment choices this year. First, regulatory classification continues to frame procurement and compliance planning. Microtomes and cryostats are classified by the FDA as tissue processing equipment under product code IDP for pathology applications. This classification anchors expectations around performance standards, documentation, and post-market oversight, and it matters for laboratories that operate under stringent quality systems or supply instruments into regulated environments. It is not simply a labeling detail; it affects vendor accountability, service expectations, and risk management for institutions that depend on sectioning consistency for downstream diagnosis.
Second, the recent Class 2 device recall issued for specific Leica microtome and cryostat models in October 2024 serves as a reminder that equipment reliability cannot be abstracted into marketing language. Recall events influence service planning, backup capacity considerations, and the weight that procurement teams place on vendor quality systems and field-support responsiveness. For strategic readers, the practical lesson is that instrument selection must account for the operational resilience of the full device lifecycle, including repair logistics, replacement part availability, and the vendor’s ability to manage corrective actions without disrupting diagnostic throughput.
Third, consumable and material science developments are increasingly relevant to total operating cost and section quality. Specialty steel such as Alleima 13C26 martensitic stainless steel is recommended for microtome blades due to its fine microstructure and edge retention properties critical for precise tissue sectioning. This kind of technical guidance illustrates why blade material, cutting consistency, and consumable quality deserve as much analytical attention as the capital instrument itself. In high-volume environments, blade performance directly influences section integrity, rework, and downstream interpretation, which means blade economics should be modeled alongside instrument economics rather than treated as a minor consumable line.
Strategic Interpretation for 2026 Planning
Taken together, the market’s trajectory, competitive structure, and external dynamics point to several decision themes for 2026. Organizations should evaluate equipment choices against throughput requirements, automation readiness, and digital integration needs, rather than treating microtomes and cryostats as interchangeable replacements. Procurement teams should weigh the balance between established multi-product vendors and specialists whose strengths lie in particular workflow niches, especially when service coverage and consumable ecosystems differ materially across suppliers. Buyers should also consider how downstream assay efficiency, including slide-reduction innovations, can alter the operational value of sectioning precision and influence consumable demand over time.
Microtomes Market
From a capital-structuring perspective, the concentration pattern in this market means that vendor selection can affect more than unit pricing. It can shape service predictability, upgrade pathways, and the feasibility of harmonizing equipment strategies across sites. For research and academic users, flexibility and application breadth may dominate; for hospitals and diagnostic laboratories, reliability, integration, and workflow standardization often carry greater weight; and for pharmaceutical and biotechnology companies, alignment with high-throughput and multiomics-compatible processes can drive differentiated equipment strategies. The report examines these distinctions without forcing every organization into the same playbook, recognizing that best-fit procurement depends on local workflow design and compliance context.
Closing the Intelligence Gap
This Worldwide Tissue Sectioning Market research is designed to convert market complexity into actionable strategy. It maps the growth arc from 2020 through 2032, situates consolidation patterns within competitive behavior, and ties regulatory, material, and workflow developments to real procurement consequences. The report’s segmentation analysis, end-user differentiation, and regional demand distributions are developed to support practical scenario planning, but the full depth of that segmentation and the detailed revenue splits are reserved for the complete study. To understand exactly how the 6.42 percent CAGR, the historical 2020–2025 base, and the 2026–2032 forecast translate into your organization’s equipment roadmap, capital sequencing, and vendor comparison, the complete dataset and interpretive framework should be consulted directly.
For executives preparing 2026 investment decisions, the practical value lies not only in knowing where the market is moving, but in understanding which segments, vendors, and workflow pressures matter most for your operating environment. The complete research offering provides that level of specificity, giving strategy and operations teams a grounded basis for procurement timing, supplier evaluation, and long-range equipment planning.
For detailed analysis of this topic, please visit the official page: Worldwide Tissue Sectioning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com