

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Proctoscope Market Hits $245.5M in 2025, Projected 5.48% CAGR to 2032

Navigating the Future of anorectal Diagnostics: Strategic Insights from the Worldwide Proctoscope Market Outlook 2026-2032
Introduction
The global healthcare landscape is undergoing a profound transformation, driven by aging populations, increasing prevalence of colorectal disorders, and a renewed focus on procedural efficiency and infection control. Within this shifting environment, the proctoscope market stands as a critical yet often overlooked segment of the broader endoscopic device industry. For strategic leaders, investors, and product development teams, understanding the nuanced trajectories of this market is no longer optional—it is essential for capitalizing on emerging opportunities and mitigating competitive risks.
PW Consulting has just released its comprehensive Worldwide Proctoscope Market research report, offering a granular, data-driven analysis of market dynamics, competitive positioning, and growth vectors through 2032. This article serves as a strategic primer, distilling the report's core findings and illustrating how precise market intelligence can shape decisions in 2026 and beyond. It is designed to provide a clear view of the landscape while inviting you to dive deeper into the full dataset, where actionable segmentation and proprietary forecasts reside.
Macro Market Trajectory: Sustained Growth Anchored by Clinical Demand
The worldwide proctoscope market has demonstrated consistent expansion over the past half-decade, reflecting steady adoption across diagnostic and therapeutic pathways. Historical revenue streams from 2020 through 2025 reveal a market that has weathered supply chain pressures and procedural backlogs to maintain upward momentum, culminating in a stable 2025 baseline. Looking forward, the forecast period from 2026 to 2032 projects a compelling compound annual growth rate of 5.48 percent.
This growth trajectory is not uniform; it is shaped by evolving clinical protocols, reimbursement structures, and the ongoing tension between single-use convenience and reusable durability. As healthcare systems optimize capital expenditure and operational workflows, procurement teams are increasingly weighing total cost of ownership, sterilization compliance, and patient throughput. The market's projected expansion through 2032 signals a maturing ecosystem where innovation in optics, ergonomics, and material science will dictate market share consolidation and new entry strategies. Readers seeking the exact milestone valuations for each forecast year and the precise inflection points will find those detailed projections within the full report.
Structural Breakdown: How Segmentation Drives Decision-Making
Effective market strategy begins with understanding how the proctoscope landscape fractures across product architectures, clinical environments, and geographic territories. The report dissects these dimensions to reveal where value is created, where volume concentrates, and where competitive gaps persist.
Product Architecture: Disposable Versus Reusable Dynamics
The bifurcation between disposable and reusable proctoscopes represents one of the most strategic fault lines in the industry. Disposable systems cater to the growing demand for streamlined infection control, reduced reprocessing labor, and predictable per-procedure costing. Reusable instruments, meanwhile, remain entrenched in high-volume settings where capital investment is amortized over thousands of cycles and where optical fidelity, instrument durability, and sterilization validation are paramount.
The interplay between these two architectures is influenced by regulatory expectations, institutional procurement policies, and the financial calculus of outpatient versus inpatient settings. Material selection, sterilization compatibility, and lifecycle economics all factor into purchasing decisions. The report maps the revenue distribution across these categories and examines the shifting procurement preferences that are reshaping product roadmaps. Specific revenue allocations and growth rates for each product segment are detailed in the full dataset to support precise portfolio planning.
Clinical Applications: Where Procedures Drive Volume
Proctoscopes are deployed across a spectrum of care settings, each with distinct operational rhythms, reimbursement profiles, and adoption behaviors. Hospitals continue to anchor a significant share of procedural volume, leveraging integrated endoscopy suites and standardized sterilization workflows. Ambulatory surgical centers and specialized clinics are expanding their footprint, driven by the migration of lower-acuity anorectal procedures to outpatient environments and the push for same-day diagnostic efficiency.
Understanding the relative weight of these application channels is critical for manufacturers targeting distribution partnerships, service networks, and pricing strategies. The report quantifies how each setting contributes to overall market demand and outlines the procurement characteristics that differentiate them. Detailed breakdowns of application-specific market size and forecast trajectories are available in the complete report.
Geographic Distribution: Regional Market Structures
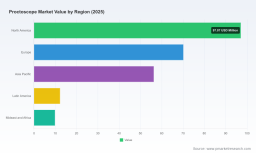
The worldwide proctoscope market exhibits clear regional asymmetries in terms of installed base, procedural density, regulatory frameworks, and purchasing power. North America remains a dominant revenue center, shaped by high procedural volumes, robust reimbursement pathways, and a mature distributor ecosystem. Europe follows with a substantial footprint, supported by established endoscopic traditions and strong regulatory alignment across member states.
Asia Pacific represents a rapidly evolving territory, where expanding healthcare infrastructure, growing awareness of colorectal screening, and localized manufacturing strategies are altering competitive dynamics. Latin America and the Middle East and Africa contribute more modest but strategically important volumes, often influenced by NGO-supported screening initiatives, medical tourism flows, and import-dependent supply chains. The report provides a structured regional analysis without oversimplifying the local nuances that govern procurement cycles and market entry barriers. Exact regional revenue figures and per-region growth trajectories are disclosed in the full market intelligence package.
Regulatory and Clinical Context: Shaping Product Strategy and Adoption
Proctoscopes operate within a tightly controlled clinical and regulatory environment that directly influences product design, compliance expenditure, and market access. In the United States, proctoscopes are classified as Class I medical devices and are 510(k) exempt under FDA product code FDT, which streamlines market entry relative to higher-class devices while still demanding rigorous quality management and labeling discipline. Internationally, compliance with ISO 13485 for quality management systems and ISO 17665 for steam sterilization validation remains foundational, particularly for reusable instruments intended for autoclave reprocessing up to 134 degrees Celsius.
Reimbursement dynamics further shape utilization patterns. Proctoscopy procedures are reimbursed under CPT codes 45300 through 45321, with average Medicare payments typically ranging between 100 and 250 dollars per procedure. These reimbursement parameters influence procedure volume forecasts, pricing sensitivity, and the attractiveness of specific clinical settings. Meanwhile, infection control standards continue to elevate the importance of high-level disinfection for reusable devices, reinforcing the operational case for single-use alternatives in certain outpatient workflows. The full report integrates these regulatory and reimbursement vectors into scenario models that help strategists anticipate compliance costs and adoption friction.
Competitive Landscape: Strategic Positioning of Market Leaders
The global proctoscope market is characterized by a concentrated group of established manufacturers that compete across product portfolios, geographic reach, and clinical specialization. Market concentration metrics indicate that the top three players capture approximately 32.5 percent of total revenue, while the top five collectively account for roughly 48.2 percent. This concentration suggests a market where scale, brand trust, and distribution depth matter, yet where niche positioning and innovation can still create defensible segments.
Olympus Corporation continues to anchor its presence through rigid proctoscopes such as the A3017A models, supporting anorectal endoscopy within broader gastrointestinal procedure suites. Karl Storz SE & Co. KG offers both reusable and disposable systems, including the 11620 series with integrated optics designed for proctological examinations, reinforcing its reputation for optical quality and modular instrumentation. Richard Wolf GmbH manufactures the 8570 series, emphasizing direct visualization in rectal diagnostics and aligning with institutions that value durable, sterilizable instruments.
Worldwide Proctoscope Market
PENTAX Medical, operating under HOYA Corporation, supplies proctoscopes within its rigid endoscopy portfolio for colorectal applications, leveraging cross-portfolio synergies in endoscopic imaging. Baxter International, through Welch Allyn, produces KleenSpec disposable proctoscopes that address single-use infection control requirements in outpatient settings, appealing to facilities prioritizing workflow simplicity and cross-contamination mitigation. HEINE Optotechnik GmbH & Co. KG contributes illuminated proctoscope sets such as the F 170 with LED technology, focusing on enhanced visualization and clinician ergonomics.
B. Braun Melsungen AG provides stainless steel proctoscopes such as the 720 series for surgical and diagnostic use, reinforcing its broader presence in sterile surgical instrumentation. Wallach Surgical Devices rounds out the competitive field with both disposable and reusable proctoscopes targeting gynecological and proctological procedures, illustrating how adjacent clinical markets can influence product strategy. The report evaluates these companies through a strategic lens, examining product architecture, geographic emphasis, and likely competitive moves. Full competitor profiles, market share modeling, and strategic implications are reserved for the complete analysis.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Making
The Worldwide Proctoscope Market report is structured to support concrete strategic actions rather than abstract market commentary. It combines historical reconstruction, forward-looking modeling, and operational context into a single decision-ready framework. Key components include:
- A detailed revenue timeline spanning historical years through the 2026-2032 forecast horizon, with milestone valuations and compound growth analysis calibrated to the underlying demand drivers.
- Segment-level assessments across product type and application, enabling portfolio mapping, pricing strategy refinement, and identification of high-potential subsegments.
- Regional market structures and procurement characteristics that inform distribution planning, market entry sequencing, and localization decisions.
- Competitive benchmarking that evaluates incumbent positioning, product differentiation levers, and the strategic implications of market concentration.
- Regulatory and reimbursement context integrated into adoption scenarios, helping teams anticipate compliance burdens, sterilization requirements, and reimbursement-driven volume sensitivity.
- Operational and material considerations, including sterilization compatibility, reprocessing workflows, and the trade-offs between disposable convenience and reusable durability.
By synthesizing these elements, the report equips executives and strategy teams with a coherent view of where value is migrating, which customer segments are most price- and performance-sensitive, and how competitive dynamics are likely to evolve. The complete dataset, analytical models, and strategic recommendations are accessible through the full report, where deeper segmentation and proprietary forecasts support scenario planning and investment prioritization.
Laryngoscope Market
Conclusion: Turning Market Intelligence Into Competitive Advantage
As the proctoscope market advances toward 2032, success will depend on more than incremental product updates or broad geographic expansion. It will require a precise understanding of how procedural economics, infection control mandates, reimbursement realities, and competitive concentration shape buyer behavior across hospitals, surgical centers, and clinics. The Worldwide Proctoscope Market research from PW Consulting is designed to convert that complexity into clarity.
For organizations preparing 2026 strategies, the report provides the structural insight needed to prioritize product investments, align distribution strategies, and evaluate competitive threats with confidence. We invite you to explore the complete analysis, where detailed segmentation, forecast tables, and competitor evaluations translate market signals into actionable intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Proctoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com