

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
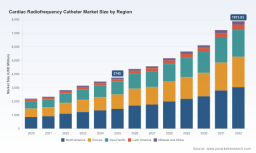
PW Consulting: Global Cardiac RF Catheter Market Set for 11.18% CAGR, Projected to Hit $7,873.83M by 2032

Strategic Horizons in the Worldwide Cardiac Radiofrequency Catheter Market: A 2026 Decision-Maker's Guide
The global cardiac electrophysiology landscape is entering a pivotal growth cycle. As healthcare providers confront rising arrhythmia prevalence and demand for precision ablation technologies, the cardiac radiofrequency catheter market is undergoing structural transformation. Recent market valuation estimates indicate a trajectory that signals both robust commercial opportunity and intensifying competitive complexity. For strategic planners navigating 2026 investment decisions, understanding this ecosystem requires more than surface-level trend observation. It demands a disciplined breakdown of revenue momentum, procedural adoption patterns, and the competitive innovations reshaping clinical workflows. This analysis sets the stage for our newly released Worldwide Cardiac Radiofrequency Catheter Market research, a comprehensive study designed to operationalize high-level market intelligence into executable corporate strategy.
Mapping the 2026 Market Trajectory
Over the historical window from 2020 through the base year of 2025, the worldwide market for cardiac radiofrequency catheters has demonstrated consistent upward momentum. Total revenue expanded steadily across this period, moving from early-cycle valuations in the low thousands of millions to a mature base exceeding the three-thousand-million threshold by 2025. The forward forecast window spanning 2026 to 2032 compounds this trajectory, projecting sustained expansion that reflects both procedural volume growth and the migration toward advanced ablation platforms. At the core of this projection is a compound annual growth rate of approximately 11.18 percent. Such a growth rate places the sector in a favorable position relative to broader medical device categories, driven by continuous refinement in catheter engineering, expanded clinical indications, and the integration of enhanced mapping and navigation capabilities.
This upward arc is not merely a function of numerical expansion. The revenue trajectory encapsulates a broader shift in electrophysiology practice patterns. Hospitals and specialty clinics are increasingly prioritizing single-procedure efficiency, reducing reliance on multiple device workflows, and investing in platforms that can address complex arrhythmia substrates. Consequently, the market's measured acceleration through 2032 reflects an environment where demand for RF catheters remains tightly coupled with institutional procurement strategies, reimbursement frameworks, and the clinical outcomes that define value-based purchasing. For executives and product leaders, this environment rewards early positioning, rigorous competitive benchmarking, and disciplined allocation toward segments with durable adoption curves.
Why Detailed Intelligence Matters for 2026 Execution
Strategic planning in the medical device space requires precision, particularly when capital allocation decisions depend on segment momentum, procurement cycles, and competitive response patterns. While high-level market size indicators communicate broad opportunity, they rarely deliver the granularity required to design pricing strategy, forecast channel demand, or anticipate competitor behavior. That is precisely the gap our latest research addresses. The Worldwide Cardiac Radiofrequency Catheter Market study translates macro-level growth signals into structured, actionable insight, enabling leadership teams to evaluate where value is concentrating and how market mechanics are evolving beneath the headline numbers.
Worldwide Cardiac Radiofrequency Catheter Market
Consider the operational decisions facing a market participant in 2026. Should a product roadmap prioritize irrigated-tip designs given their dominant share of clinical utilization? How are procedural coding frameworks and facility payment structures influencing purchasing thresholds across different care settings? What does the intensifying focus on contact force sensing, impedance feedback, and robotically navigated systems mean for incumbent positioning? The answers to these questions depend on disciplined segmentation, region-specific demand mapping, and a nuanced understanding of how clinical preference translates into revenue distribution. Our report is structured to surface these decision levers without relying on superficial generalizations.
Inside the Report: A Toolkit for Strategic Action
The research is built around practical frameworks rather than abstract overviews. Readers will find a clearly structured examination of market sizing, segmented demand dynamics, and the competitive behaviors shaping the industry's next growth phase. The study delivers:
- A full historical valuation sequence and forecast path, with year-by-year revenue movement that anchors planning assumptions for both near-term budgeting and long-horizon scenario modeling.
- Segmentation analysis across product configuration categories that clarifies how irrigated and non-irrigated solutions distribute across clinical workflows and procurement priorities.
- Application-driven demand mapping covering major arrhythmia treatment indications, enabling teams to align product positioning with the clinical pathways that generate the highest procedure frequency.
- Geographic revenue structure that breaks down where market activity is concentrated, helping commercial leaders prioritize launch sequencing, sales coverage, and partnership strategy.
- An in-depth competitive landscape chronicling the strategies, product architectures, and recent regulatory milestones shaping the positions of leading global manufacturers and emerging challengers.
- Market concentration measurement that quantifies the consolidation of revenue among top players, providing transparency into competitive barriers, pricing power, and the risk of share erosion for newer entrants.
- Regulatory and reimbursement context that ties recent clinical approvals and procedural coding frameworks to commercial viability, ensuring technology investments are evaluated against the practical realities of hospital reimbursement cycles.
This structure is deliberately designed to support a wide range of strategic use cases, including new market entry assessments, product portfolio optimization, partnership evaluation, and investor-facing market storytelling. By embedding segment-level analysis within a cohesive strategic narrative, the report helps decision-makers move from observation to execution.
Competitive Architecture and Recent Innovation Shifts
The competitive environment in cardiac RF ablation is defined by established multinational manufacturers, strong clinical-technology integration, and a series of recent breakthroughs that are altering procedural standards. Medtronic has continued to reinforce its electrophysiology portfolio with dual-energy approaches, including systems that pair high-definition mapping with both pulsed field and radiofrequency capabilities. Its recent regulatory milestones underscore an industry-wide shift toward all-in-one procedural solutions that reduce case complexity and streamline workflow for persistent atrial fibrillation and atrial flutter management.
Boston Scientific remains a central force through its temperature-controlled ablation portfolio, with catheter families built around contact force and impedance sensing capabilities that support consistent lesion formation. Johnson & Johnson MedTech, through its Biosense Webster business, contributes a similarly influential set of therapeutic RF catheters designed to work with advanced mapping navigation platforms, reinforcing integration between visualization and ablation delivery. Abbott maintains a strong position by supplying RF ablation technologies tailored to varied anatomical needs, ensuring that its portfolio aligns with diverse clinical protocols.
The competitive field also includes innovators pursuing differentiated navigation and delivery modalities. Stereotaxis has been advancing robotically navigated magnetic ablation systems, with recent FDA approval enabling broader use of magnetically guided RF catheters in supraventricular tachycardia and more complex cases. MicroPort EP continues to strengthen its presence through 3D navigation-compatible RF ablation platforms focused on drug-refractory symptomatic atrial fibrillation. Biotronik rounds out the competitive set with steerable tip RF catheter designs intended to support procedural efficiency across cardiac ablation cases.
These players are not competing solely on catheter specifications. They are competing on procedural confidence, integration with mapping ecosystems, training support, and the ability to fit into institutional purchasing models that reward predictable outcomes. Recent approvals for robotically navigated and dual-energy platforms illustrate how quickly the competitive frontier is moving. Any company operating in this space must evaluate whether its current product strategy anticipates a market where mapping, navigation, energy delivery, and workflow efficiency are increasingly bundled into a single value proposition.
Regulatory and Reimbursement Signals Shaping Commercial Reality
Product innovation cannot be evaluated in isolation from the regulatory and reimbursement structures that determine adoption speed. The recent approval activity surrounding advanced ablation and mapping systems demonstrates that regulatory pathways are enabling more versatile procedural platforms. At the same time, procedural coding frameworks for intracardiac electrophysiologic procedures continue to support facility payments for mapping and ablation cases within prevailing reimbursement models. This alignment between coding structure and procedural complexity helps sustain hospital willingness to acquire advanced RF catheter platforms, especially when those platforms reduce total case time or expand the range of patients who can be treated in a single session.
Yet reimbursement stability also introduces strategic caution. As procedural payment pathways adapt to evolving device use, manufacturers and providers must closely monitor how coding updates, DRG classification practices, and facility purchasing constraints influence adoption velocity. The latest research addresses these forces directly, connecting regulatory milestones and procedural payment dynamics to practical commercial consequences. This ensures that strategy teams evaluate demand not only in terms of clinical need, but also in terms of payment architecture, procurement timing, and institutional purchasing behavior.
Worldwide 2D Ablation Catheter Market
Market Concentration and the Strategic Stakes Ahead
The worldwide market exhibits a high degree of top-tier concentration, with a substantial share of total revenue captured by a small group of dominant manufacturers. This concentration reflects the strength of established clinical relationships, the advantage of integrated mapping and ablation ecosystems, and the scale required to support global distribution, regulatory compliance, and post-market clinical evidence generation. At the same time, it signals meaningful barriers for new entrants and emphasizes the importance of differentiated technology or highly targeted clinical value propositions.
Concentration also influences pricing dynamics, channel negotiation leverage, and the pace at which innovation is commercialized. Companies operating within this environment must decide whether to compete through incremental enhancement within established workflows, or pursue step-change differentiation that alters procedural expectations. The strategic implications of concentration become especially important when forecasting share movement across 2026 and beyond, as regulatory approvals, procedural adoption, and regional demand patterns interact to reshape the competitive hierarchy.
Positioning for 2026 and Beyond
As management teams build 2026 strategies, the key question is no longer whether the cardiac RF catheter market is expanding, but how to convert expansion into durable advantage. Growth is being shaped by catheter performance improvements, advanced navigation and mapping integration, evolving reimbursement conditions, and a competitive landscape that continues to consolidate around a few high-impact platforms. Companies that treat this moment as a pure revenue opportunity may miss the deeper structural shifts underway. Companies that use detailed market intelligence to align product development, commercial execution, and competitive positioning will be better prepared to secure treatment volume, defend share, and enter adjacent opportunities with clarity.
Our Worldwide Cardiac Radiofrequency Catheter Market research is designed to support exactly that level of decision-making. It provides the segmentation detail, competitive profiles, concentration analysis, and market trajectory context required to move from high-level awareness to concrete strategy. The full study contains the granular regional, application, and product-type breakdowns, along with complete company profiles and development timelines, that underpin robust forecasting and planning. For teams that need accurate, structured intelligence before finalizing strategy, capital plans, or commercial roadmaps, the complete dataset remains the most direct path to confident execution.
For detailed analysis of this topic, please visit the official page: Worldwide Cardiac Radiofrequency Catheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com