

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Worldwide IT Market Hits $5.7B in 2025, Projected to Reach $9.93B by 2032 at 8.25% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Wave: Navigating the Worldwide Information Technology Market in 2026
The global information technology landscape is undergoing a structural transformation that demands more than incremental budgeting or reactive procurement. As organizations move deeper into an AI-augmented, hyperconnected operating environment, the capacity to distinguish durable growth from temporary hype has become a critical strategic competency. PW Consulting’s latest Worldwide Information Technology Market research study provides that distinguishing lens, synthesizing historical performance, forward-looking projections, and competitive intelligence into a single decision-ready framework. For leaders planning capital allocation, capability building, and market positioning throughout 2026 and beyond, this research offers the operational clarity required to act with precision rather than speculation.
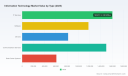
The study opens with a clear macroeconomic baseline: the worldwide IT market has expanded from an estimated 3.92 trillion USD in 2020 to approximately 5.70 trillion USD in 2025, reflecting sustained enterprise digitization, cloud migration, and the emergence of generative AI as a core operational driver. Looking ahead, the forecast period through 2032 projects continued expansion at a measured compound annual growth rate of 8.25 percent, with the market trajectory climbing toward nearly 10 trillion USD by the final projection year. These figures are not abstract indicators; they frame the scale of investment, capability development, and competitive positioning that enterprise leaders must now plan for. The revenue is tracked in USD millions, providing consistent comparability across time horizons, and the growth profile suggests that IT spending will remain a central pillar of corporate strategy rather than a discretionary cost center.
Before executives attempt to translate these top-line trajectories into portfolio decisions, it is essential to understand where momentum is concentrated and how it is flowing through the ecosystem. The research deliberately segments the market across type, application, and geographic dimensions, allowing decision-makers to see how capital and demand are distributed across the value chain without overwhelming them with raw spreadsheets. Rather than treating the IT market as a monolith, the analysis reveals the underlying balance between IT services, software, devices, communications services, and data center systems, each carrying distinct margin profiles, adoption cycles, and competitive dynamics. The same logic applies to end-use verticals, where enterprise deployments, consumer adoption, government and public sector programs, and small and medium business digitization present different buying behaviors, procurement cycles, and resilience factors.
This segmentation foundation matters because 2026 is shaping up as a year of divergence. Recent industry signals indicate that spending on servers, storage, and network equipment is accelerating sharply as service providers expand data center infrastructure to accommodate AI workloads and cloud-native architectures. At the same time, semiconductor revenue is projected to climb to levels not seen in decades, with memory markets experiencing particularly pronounced expansion. These shifts are not isolated technical trends; they represent structural changes in how IT capacity is built, where value is captured, and which vendors are positioned to influence enterprise buying behavior. In parallel, trade exhibitions and analyst forecasts have emphasized robotics enabled by physical AI, digital health innovation, and advanced mobility as reinforcing themes within the broader IT ecosystem, while strategic trends for the year increasingly center on domain-specific language models and AI-powered connectivity across business functions.
Equally important, macro and regulatory conditions are reshaping the operating environment. Tariff policies and geopolitical tensions continue to introduce supply chain uncertainty for IT hardware and semiconductor components, prompting organizations to invest in resilient sourcing strategies and cloud-based visibility tools. AI-driven investment across telecom, fiber, and data centers is also accelerating infrastructure development, making the TMT sector’s physical and digital layers more interdependent than ever. In that context, the strategic question for senior leaders is no longer whether IT will remain a growth engine, but how to allocate resources in a market where innovation cycles, regulatory exposure, and supply-side volatility intersect.
What the Research Delivers: Operational Content for 2026 Decision-Making
PW Consulting’s Worldwide Information Technology Market study is designed to move directly from market structure to actionable planning. The report assembles a comprehensive historical record spanning 2020 through the base year of 2025, then extends forward across a multi-year forecast period through 2032. This dual lens allows organizations to test strategic assumptions against both proven performance patterns and expected transitions in demand. Historical data illuminates how the market absorbed shocks, scaled cloud and services growth, and rebalanced around shifting enterprise priorities. The forecast component, meanwhile, translates those patterns into forward indicators that support budget planning, capacity modeling, and investment prioritization.
Segmentation Analysis That Supports Portfolio Strategy
One of the most valuable components of the research is its segmentation architecture. By disaggregating the market into type, application, and regional dimensions, the study enables leaders to examine how growth is distributed across the IT ecosystem rather than relying on a single aggregate figure. This approach supports more precise questions: Where is incremental spending likely to appear? Which segments are expanding on the back of structural infrastructure demand, and which are being reshaped by software-led transformation or services migration? How does demand differ between large enterprise buyers and smaller commercial entities? Because the report maintains a consistent unit framework in USD millions throughout, readers can compare relative scale without losing sight of absolute investment levels.
The analysis is intentionally built to support segmentation-informed strategy. For technology vendors, this means clearer insight into which product and service categories are most relevant to near-term growth narratives. For enterprise buyers, it means better visibility into where cost, speed, and capability trade-offs are likely to emerge. For investors and advisors, it means a more defensible basis for assessing which parts of the market are consolidating around durable demand and which are subject to faster disruption or substitution.
Competitive Intelligence Grounded in Company Profiles
A market of this size is shaped not only by end-user demand but also by the strategies of a concentrated set of leading firms. The report integrates detailed profiles of core participants across the IT ecosystem, capturing their headquarters, primary capabilities, and strategic positioning. These include organizations spanning cloud platforms, productivity suites, AI tooling, operating systems, semiconductor and data center infrastructure, enterprise databases, business applications, hybrid cloud, IT services, digital transformation consulting, and application development. Each profile is structured to help readers understand not just what a company offers today, but how it is positioned relative to the demand shifts that the forecast anticipates.
Worldwide Information Technology Market
The competitive picture is especially relevant given the market’s concentration profile. The top three firms account for roughly 14.82 percent of overall market share, while the top five firms account for approximately 21.35 percent. That level of concentration does not imply a static landscape; rather, it signals where competitive pressure, ecosystem influence, and partnership leverage are likely to concentrate in 2026. Companies outside the top tier still play essential roles in implementation, services delivery, and regional execution, but large platform players continue to shape pricing expectations, integration norms, and enterprise adoption patterns across cloud, software, and AI-enabled services.
To complement these corporate profiles, the study integrates recent developments that illustrate how market participants are reacting to structural change. Industry output from late 2025 and early 2026 highlights a strong spending environment, with worldwide IT investment projected to grow significantly in 2025 and maintain positive momentum into 2026, driven by AI infrastructure, cloud services, and device refresh cycles. Simultaneously, semiconductor revenue forecasts point to one of the strongest growth intervals in recent history, reinforcing the importance of hardware and data center capacity in the broader IT economy. Analyst commentary and industry events further underscore domain-specific AI, robotics, digital health, and advanced mobility as themes that are becoming embedded in mainstream IT planning rather than remaining peripheral innovation stories.
Why This Research Matters for 2026 Strategy
For executives and strategy teams, the value of this research lies in its ability to connect market scale with operational decision-making. The data does more than confirm that IT continues to grow; it defines the magnitude of that growth, the timeframe over which it is expected to unfold, and the degree of concentration within the competitive field. That combination helps organizations answer a set of core strategic questions: How much capacity should we plan for? Which demand pools should we prioritize? Where do we face the greatest exposure to supply chain or tariff-related disruption? How should we position ourselves relative to dominant platforms and service providers?
The practical applications are broad. A CIO planning a multi-year technology roadmap can use the macro trajectory and segmentation structure to validate investment phasing and align procurement with anticipated demand shifts. A product leader can use the type-based segmentation to identify where service, software, or infrastructure demand is likely to be strongest, and adjust roadmap focus accordingly. A corporate development team can use the competitive profiles and concentration data to assess partnership, acquisition, and ecosystem entry opportunities with a realistic sense of market power distribution. A risk and operations leader can use the latest industry dynamics to anticipate supplier-side volatility and adjust sourcing, inventory, or cloud dependency strategies.
Because the report is built around both history and forecast, it also supports scenario planning. Decision-makers can examine how sensitive their plans are to different adoption speeds, how exposure to specific segments may shift over time, and where the difference between headline growth and segment-level realities is most pronounced. That capacity is especially important in a market where AI infrastructure, data center expansion, and advanced connectivity are reshaping spending priorities faster than traditional budgeting cycles can accommodate.
How the Study Turns Market Complexity into Executive Clarity
PW Consulting’s approach emphasizes clarity without oversimplification. The study preserves the granularity needed for serious planning while organizing the information so that leadership teams can move quickly from market context to internal implications. Historical revenue trends demonstrate how the market has scaled over the last several years; the forward forecast establishes a structured view of expected momentum through the end of the decade and into the early 2030s; segmentation data allows readers to separate broad growth from segment-specific dynamics; and competitive profiles translate market structure into strategic awareness.
This is not a static market description. It is a working base for strategic action in 2026, when IT spending behavior is being reshaped by AI-led infrastructure demand, cloud expansion, hardware refresh cycles, and a more uncertain geopolitical and supply chain environment. Leaders who rely on aggregate narratives alone risk misjudging where growth is concentrated, where costs will move, and where competitive advantage can be built. The research is designed to reduce that risk by providing a structured, evidence-based view of the market as it is today and as it is expected to evolve.
IT Services Market
The full depth of this analysis is available in the complete Worldwide Information Technology Market report, where the underlying segment detail, regional context, company intelligence, and forecast logic are presented in full. For organizations that need to move from high-level awareness to committed investment decisions, the complete study offers the granular intelligence necessary to align strategy with market reality and to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Information Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Battery Software Market Hits $1,127.29M in 2025, Projected 18.24% CAGR to $3,642.24M by 2032
By pmarketresearch, 2026-09-16
Navigating the Battery Manufacturing Software Boom: Strategic Imperatives for 2026 and Beyond
The global battery manufacturing software market is undergoing a transformation that mirrors the electrification of the automotive industry itself. No longer a back-office utility, manufacturing software has become the central nervous system of gigafactory operations, influencing everything from cell yield rates to regulatory compliance. According to our latest research, the worldwide market for battery manufacturing software is projected to expand from an estimated 1,127.29 million USD in 2025 to 3,642.24 million USD by 2032. This trajectory represents a compound annual growth rate of 18.24 percent over the forecast period.
Such figures are not merely indicators of market expansion. They signal a structural shift in how battery producers approach scalability, quality assurance, and operational intelligence. As capital intensity rises and regulatory scrutiny tightens, software platforms that once supported discrete manufacturing processes are being reimagined as integrated digital threads. For executives planning their 2026 investment roadmaps, understanding the architecture, competitive dynamics, and external pressures shaping this market is no longer optional. It is a prerequisite for sustainable growth.
Our comprehensive Worldwide Battery Manufacturing Software Market report is designed to provide the analytical rigor and actionable granularity required to navigate this inflection point. What follows is a strategic overview of the forces driving this market, the competitive landscape defining it, and the practical dimensions our study unpacks for industry leaders.
Market Trajectory and the Case for Strategic Investment
The historical trajectory of the battery manufacturing software market reflects the broader acceleration of electrification. Between 2020 and 2025, the market expanded consistently each year, growing from 510.45 million USD to the aforementioned 1,127.29 million USD. This doubling of market value over a five-year period underscores how quickly software has moved from a supplementary expenditure to a core operational necessity.
Looking ahead, the forecast period from 2026 through 2032 indicates that this momentum will not decelerate. The market is expected to surpass 1,367.57 million USD in 2026 and continue climbing steadily to 1,606.81 million USD in 2027, 1,875.33 million USD in 2028, 2,182.17 million USD in 2029, and 2,669.49 million USD in 2030. By the close of the forecast window in 2032, revenue is projected to reach 3,642.24 million USD. An 18.24 percent CAGR across this horizon suggests that software adoption will remain tightly coupled with production capacity expansion, technological maturation, and the evolving demands of downstream customers.
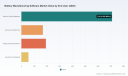
Importantly, these projections are not homogeneous across all solution types or end-user segments. The composition of market value reflects distinct adoption curves for manufacturing execution systems, simulation and design platforms, quality management tools, asset performance management suites, and data analytics and AI offerings. Similarly, the demand profile varies meaningfully across application domains such as electric vehicle batteries, consumer electronics, energy storage systems, and industrial and medical batteries. Our report dissects these structural nuances in detail, enabling decision-makers to align software procurement with their specific operational priorities rather than relying on aggregate market narratives.
External Pressures Redefining Software Requirements
Market growth is being accelerated by a confluence of regulatory, economic, and technical forces that are simultaneously raising the stakes for manufacturing software vendors and end-users. One of the most consequential developments is the emergence of the EU battery passport framework. By 2027, mandatory requirements for carbon footprint declaration and quality component disclosure will apply to large segments of the battery industry. This regulatory shift is not simply a compliance exercise. It is driving a fundamental need for enhanced traceability, data sovereignty, and interoperable data architectures within manufacturing software environments.
Parallel to regulatory evolution, cost structures in battery production are creating new incentives for digitalization. In a baseline 40 GWh per annum lithium-ion battery cell production plant, labor accounts for approximately 6.9 percent of total costs. Research indicates that digitalization solutions encompassing predictive quality, automated traceability, and workflow optimization can reduce required staffing and overall production costs by up to 0.8 percent per use case. While these percentages may appear incremental in isolation, their cumulative impact across multiple production lines and operational domains can materially improve margins in an industry where cost-per-kWh remains a central competitive battleground.
Energy efficiency represents another critical lever. Energy tracking and optimization use cases in battery manufacturing digitalization hold the potential for a 9.5 percent reduction in energy consumption. The electrode production stage, in particular, stands to benefit most from integrated scrap reduction and energy efficiency initiatives. As energy prices remain volatile and sustainability commitments tighten, software platforms capable of delivering granular energy visibility and actionable optimization insights are gaining strategic prominence.
Cybersecurity is equally reshaping vendor selection criteria. Standards such as ISO 21434 and IEC 62443 are increasingly referenced in battery-related systems procurement. Recommendations for end-to-end encryption, including AES-256 and TLS 1.3, alongside secure update mechanisms in connected manufacturing environments, are becoming baseline expectations rather than premium differentiators. In this context, software platforms must demonstrate not only operational functionality but also resilient security architectures that align with evolving compliance mandates.
Geopolitical dynamics add further complexity. US domestic battery manufacturing output grew 359 percent in inflation-adjusted terms from 2020 to 2024, supported by policy actions encouraging onshoring of supply chain elements. This surge amplifies the importance of software integration for traceability, quality assurance, and regulatory reporting, particularly for manufacturers seeking to align with domestic content requirements and localized production incentives.
Competitive Landscape: Differentiated Platforms and Strategic Positioning
The competitive landscape in battery manufacturing software is characterized by a mix of established industrial automation players, specialized software vendors, and emerging analytics-focused firms. Market concentration data indicates that the top three players account for 34.2 percent of the market, while the top five represent 48.15 percent. This distribution reflects a market that is substantial enough to attract broad participation yet fragmented enough to allow differentiated value propositions to thrive.
GE Vernova continues to leverage its Proficy Smart Factory MES software to support diverse battery production processes within a single manufacturing platform. Its offering emphasizes end-to-end production visibility, quality control, traceability, and scalability for gigafactories while aiming to reduce operational technology costs and maintenance burdens. Siemens, meanwhile, integrates battery manufacturing execution systems, quality management systems, and process planning tools into its broader digital thread and smart manufacturing portfolio. Its approach is oriented toward standardization and optimization across battery production workflows.
Rockwell Automation delivers end-to-end MES solutions tailored specifically for EV lithium-ion battery producers. Its focus on integrated automation and manufacturing execution positions it as a relevant partner for organizations prioritizing tightly coupled control and execution architectures. Honeywell has made notable moves in this space, including its June 2024 launch of the Battery Manufacturing Excellence Platform, an AI-powered solution designed to optimize gigafactory operations, improve battery cell yields, reduce material waste, and compress production ramp-up cycles. Public disclosures around this launch highlighted a potential 60 percent reduction in startup material scrap, underscoring the growing emphasis on AI-driven process optimization.
Voltaiq offers an enterprise battery intelligence software platform that extends data analytics and insights from research and development through to giga-scale production. Its value proposition centers on helping manufacturers detect and correct battery issues using existing data streams, thereby improving quality, safety, and efficiency. Energsoft serves a different segment by providing subscription-based predictive battery analytics software aimed at medium-sized companies. Its model focuses on automating data export, storage, and analysis to boost manufacturing yield and streamline workflows in battery production environments.
camLine, operating under the Elisa IndustrIQ umbrella, supplies MES, manufacturing operations management, and AI-powered solutions with a specific emphasis on efficiency, quality control, and end-to-end traceability for battery manufacturing processes. ABB contributes through its Manufacturing Operations Management software, which integrates secure data services, predictive analytics, and collaboration capabilities to deliver end-to-end visibility, including dedicated support for smart production in battery manufacturing. Panasonic Connect expanded the competitive field with its October 2024 launch of Syncora, an end-to-end manufacturing execution system designed to accelerate the digital transformation of EV battery manufacturing. Finally, PDF Solutions provides Exensio Battery, a modular solution set that addresses critical challenges in battery manufacturing through advanced analytics applicable to both semiconductor and battery processes.
Together, these players illustrate the breadth of approaches available to manufacturers. The strategic question is not simply which vendor offers the most features, but which platform architecture best aligns with a company's production scale, data maturity, regional compliance requirements, and integration constraints. Our report evaluates these competitive dynamics with a structured lens, allowing readers to assess fit beyond marketing narratives.
What the Report Covers: Operational Intelligence for Decision-Makers
The Worldwide Battery Manufacturing Software Market study is structured to serve as both a strategic compass and a practical reference for procurement, operations, and technology leadership. Rather than relying on surface-level aggregations, the report provides a detailed exploration of market architecture, adoption patterns, and the operational contexts in which software solutions deliver measurable value.
The analysis begins with a rigorous framing of market size and growth trajectories, contextualized across historical performance and forward-looking projections. It then examines segmentation structures that matter for enterprise planning, including solution type categories and end-user applications. By isolating the distinct demand drivers behind manufacturing execution systems, simulation and design software, quality management systems, asset performance management, and data analytics and AI platforms, the report helps readers understand where investment is concentrating and why.
Worldwide Battery Manufacturing Software Market
A substantial portion of the study is dedicated to competitive profiling. Each of the key companies is assessed for its product strategy, integration approach, target customer profile, and recent market moves. This includes not only incumbents with broad industrial automation portfolios but also specialized vendors whose solutions address niche but increasingly important requirements such as predictive analytics, battery intelligence, and modular process optimization. Recent product launches and strategic announcements are contextualized within broader market trends, enabling readers to distinguish between incremental updates and genuinely transformative offerings.
The report also integrates an assessment of external market dynamics, including regulatory developments, cost structure considerations, energy optimization potential, cybersecurity expectations, and regional manufacturing policy shifts. These factors are examined not as isolated observations but as interconnected forces that shape software selection criteria, implementation timelines, and total cost of ownership. By mapping these dynamics to practical procurement and deployment considerations, the study equips leaders to anticipate compliance requirements, align software capabilities with operational KPIs, and build internal business cases that withstand executive and board-level scrutiny.
Importantly, the report avoids treating the market as a monolith. Where relevant, it highlights the structural differences that emerge across regions, solution types, and end-user applications without overemphasizing any single segment in isolation. This balanced approach ensures that readers can extract insights applicable to a range of strategic scenarios, whether they are scaling gigafactory operations, optimizing existing production lines, or evaluating entry into new battery market segments.
Strategic Recommendations for 2026 Planning
As organizations move into 2026, several strategic priorities should guide battery manufacturing software decisions. First, traceability and data sovereignty must be treated as foundational requirements rather than afterthoughts. With regulatory frameworks such as the EU battery passport approaching, manufacturers should evaluate whether their software platforms can support the granularity, auditability, and data governance necessary for compliance. Solutions that lack robust traceability frameworks may require costly retrofits or integration work later.
Second, AI-enabled optimization should be assessed against measurable operational outcomes. The market is seeing a growing number of platforms that promise yield improvement, scrap reduction, and faster ramp-up cycles. However, the value of these capabilities depends on data quality, integration depth, and change management. Procurement teams should seek evidence of performance in comparable production environments and establish clear baseline metrics before committing to large-scale deployments.
Third, cybersecurity and secure data exchange must be embedded into vendor evaluation criteria from the outset. As manufacturing environments become more connected, the attack surface expands. Software platforms that support recognized security standards and provide secure update mechanisms, encryption, and access controls will reduce long-term risk and simplify compliance reporting.
Fourth, total cost of ownership should be evaluated across labor, energy, and material efficiency dimensions. The potential for digitalization to reduce staffing requirements, lower energy consumption, and minimize scrap represents a multi-dimensional value proposition. Organizations that model these benefits holistically are better positioned to justify investments and prioritize use cases with the highest return potential.
Finally, alignment with regional manufacturing incentives and supply chain strategies is essential. In markets where domestic production is being actively supported through policy mechanisms, software platforms that facilitate traceability, compliance reporting, and integration with localized production workflows can provide strategic advantages beyond their operational functionality.
Accessing the Full Intelligence
The battery manufacturing software market is expanding at a pace that rewards organizations capable of making informed, timely decisions. The aggregate growth trajectory is compelling, but the real strategic value lies in understanding the segmentation dynamics, competitive differentiators, regulatory pressures, and operational use cases that will determine success in specific deployment contexts.
Our Worldwide Battery Manufacturing Software Market report provides the depth, structure, and analytical discipline required to navigate this complexity. It is intended for leaders who need more than headline figures. It offers a comprehensive view of how the market is evolving, who is shaping it, and what practical considerations should inform software strategy in 2026 and beyond.
Battery Design And Manufacturing Software Market
For detailed segmentation breakdowns, competitive assessments, regional analyses, and the full set of market projections, we invite you to explore the complete report. The full intelligence is available through our official research portal, where you can access the complete dataset, methodology documentation, and supporting exhibit materials designed to support executive planning, procurement strategy, and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Battery Manufacturing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Global 2-Cyano-phenothiazine Market to Hit $63.74M by 2032, 5.06% CAGR From $45.12M in 2025
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Global 2-Cyano-phenothiazine Market Landscape
In the rapidly evolving landscape of pharmaceutical intermediates, the 2-Cyano-phenothiazine market stands as a critical nexus for supply chain stability, regulatory compliance, and manufacturing excellence. As we approach 2026, enterprises involved in the synthesis of antipsychotics, specialty chemicals, and advanced pharmaceutical ingredients must rely on data-driven foresight rather than reactive strategies. PW Consulting is proud to unveil our comprehensive Worldwide 2-Cyano-phenothiazine Market Research, a definitive guide designed to empower stakeholders with the actionable intelligence required to thrive in a volatile global chemistry market.
Worldwide 2-Cyano-phenothiazine Market
This market study is not merely a collection of figures; it is a strategic roadmap. By analyzing historical trajectories from 2020 through the base year of 2025 and projecting forward to 2032, we provide a longitudinal view of market health and momentum. For decision-makers, the value lies in understanding the cadence of growth and the underlying forces shaping demand and supply. This article serves as a preview of the depth and rigor contained within the full report, highlighting why this intelligence is indispensable for your 2026 planning cycle.
Market Trajectory and Growth Dynamics
The financial narrative of the 2-Cyano-phenothiazine market over the past five years tells a story of steady expansion and resilience. Our research tracks the revenue trajectory from 2020, when the market was valued at approximately 35.88 million USD, through to a projected valuation of 63.74 million USD by the end of the forecast period in 2032. This progression underscores a compound annual growth rate (CAGR) of roughly 5.06 percent during the forecast window.
For procurement officers and strategic planners, these figures represent more than just growth; they indicate a maturing market with increasing demand density. The upward trend observed from 2020 to 2025 demonstrates consistent annual increments, suggesting robust underlying demand from downstream pharmaceutical applications. Understanding this momentum is crucial for capacity planning and investment timing. Our full report dissects these trends to help you anticipate inflection points, ensuring that your supply agreements and production schedules align with market realities rather than lagging behind them.
Segmentation Insights: Purity, Application, and Regional Nuances
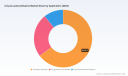
A monolithic view of the market obscures the strategic opportunities hidden within specific segments. Our analysis reveals distinct preferences and volume drivers across purity specifications, application types, and geographic regions. For instance, the market shows a pronounced preference for high-purity grades, specifically those above 99 percent purity, which command a significant share of the total volume compared to the 98 to 99 percent range. This preference signals to manufacturers that quality consistency is a primary driver for customer retention and premium pricing strategies.
In terms of end-use, the synthesis of Periciazine remains a dominant application driver, followed by its use as a Propericiazine intermediate. These pharmaceutical-specific uses highlight the compound's critical role in the production of antipsychotic medications and related therapeutics. Beyond these primary uses, there is a steady niche for other pharmaceutical research applications, indicating that the compound's utility extends into broader R&D pipelines.
Geographically, the market dynamics are heavily influenced by manufacturing hubs in Asia Pacific, which accounts for the largest share of volume, followed by established markets in Europe and North America. Latin America and the Middle East and Africa represent emerging or niche demand centers. However, accessing the precise revenue breakdowns, regional growth rates, and application-specific market sizes for these segments requires a detailed examination of the full dataset. Our report provides these granular insights, allowing you to identify high-potential markets without the noise of aggregated data.
Competitive Landscape: Key Players and Strategic Positioning
The concentration of market power is a defining feature of the 2-Cyano-phenothiazine industry. With a CR3 (concentration ratio of the top three companies) of approximately 62.45 percent and a CR5 of 78.12 percent, the market is moderately consolidated. This structure implies that a handful of key manufacturers wield significant influence over pricing, availability, and supply chain reliability.
Our research profiles several pivotal entities shaping this landscape. Sanjeevan Pharmachem Pvt. Ltd., based in Aurangabad, India, stands out as a manufacturer and exporter adhering to GMP-equivalent facilities and ICH Guidelines, offering 99.0 percent purity with a capacity of approximately 5 MT per annum. Similarly, Anjali Labs, also located in Aurangabad, positions itself as a pioneer producer with KSM approval for both Indian and overseas companies, enforcing a minimum order quantity of 100 kg for export-worthy 25 kg drums.
In the Indian sector, Finocure Laboratories contributes to the supply chain with a focus on Triflupromazine intermediates, maintaining capabilities that meet global standards and authorizing KSM use for international clients. The Chinese manufacturing base is also robust, featuring players such as Jinan Haihang Chemical Co., Ltd., Ningbo Inno Pharmchem, Capot Chemical Co., Ltd. in Hangzhou, and Mikem (Shandong) Biopharmaceutical Science and Technology Co., Ltd. These Chinese suppliers cater to the fine chemicals and organic intermediates segments, with Capot Chemical emphasizing strict moisture control limits of 0.5 percent or less for their product offerings.
Understanding the specific capabilities, capacity constraints, and quality certifications of these competitors is vital for benchmarking your own operations or selecting reliable partners. The full report goes beyond profiles to analyze supply chain vulnerabilities, capacity utilization trends, and the strategic implications of sourcing from these specific regions.
3-Cyano Pyridine Market
Industry Dynamics: Regulatory, Raw Material, and Safety Considerations
The operational environment for 2-Cyano-phenothiazine is shaped by a complex interplay of raw material dependencies and regulatory frameworks. At the upstream level, Phenothiazine (CAS 92-84-2) serves as the core feedstock for the synthesis of 2-cyano-phenothiazine derivatives. Fluctuations in the availability or pricing of this upstream material can have cascading effects on the downstream 2-Cyano-phenothiazine market. Our report integrates supply chain analysis to help you model these risks and secure alternative sourcing strategies where necessary.
Regulatory compliance is another pillar of market stability. 2-Cyano-phenothiazine is classified under transport regulations as environmentally hazardous, requiring adherence to ADR/RID, IMDG, and IATA standards for shipping and handling. This classification necessitates specific packaging precautions and compliance protocols that can impact logistics costs and lead times. Furthermore, the substance is intended strictly for research and pharmaceutical intermediate use, prohibiting direct medicinal or consumer applications. This restriction limits the addressable market to qualified industrial and research entities, reinforcing the need for precise market sizing and targeted marketing strategies.
These dynamics create a barrier to entry that favors established players with the infrastructure to manage compliance and safety efficiently. For new entrants or companies looking to expand their footprint, understanding these regulatory hurdles is as important as understanding the financial metrics. The detailed report includes sections dedicated to navigating these regulatory landscapes, offering FAQs and guidance based on the latest safety data sheets and industry recommendations.
Strategic Value for 2026 Decision-Making
Why does this market research matter for your 2026 strategy? The answer lies in the ability to move from reactive scrambling to proactive positioning. As the market moves from a 2025 base value of 45.12 million USD toward the 2032 horizon, the opportunities for value creation will concentrate in specific segments and regions. Companies that rely on generic market intelligence risk misallocating resources, overpaying for intermediates, or missing out on high-growth application areas.
Our report enables you to:
- Optimize Sourcing Strategies: Leverage detailed supplier profiles and capacity data to negotiate better terms and ensure supply continuity, particularly when dealing with concentrated markets where supplier leverage can be high.
- Target High-Value Segments: Identify which purity grades and application areas offer the best margin potential, avoiding low-value segments that drain resources.
- Mitigate Regulatory Risk: Incorporate compliance requirements into your operational planning to avoid costly delays or non-compliance penalties associated with hazardous material transport and handling.
- Benchmark Performance: Compare your production efficiency, purity standards, and pricing structures against key competitors to identify areas for improvement.
- Forecast with Confidence: Use the historical and forecast data to build robust financial models that account for cyclical trends and long-term growth trajectories.
The preview provided here only scratches the surface of the actionable intelligence available. The full Worldwide 2-Cyano-phenothiazine Market Research contains a wealth of additional data, including precise segmentation breakdowns, detailed competitive analysis matrices, and in-depth regional assessments that are essential for granular strategic planning. We have deliberately withheld these specific figures to preserve the proprietary value of the complete study, which is designed to provide your organization with a competitive edge.
To access the comprehensive data, detailed tables, and strategic recommendations that will drive your 2026 success, we invite you to request the full report. Equip your team with the insights needed to navigate the complexities of the global chemical intermediate market and secure your position in the evolving pharmaceutical supply chain.
PW Consulting – Delivering Clarity in Complexity.
For detailed analysis of this topic, please visit the official page: Worldwide 2-Cyano-phenothiazine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cast Iron Manhole Covers Market to Hit $6,143M by 2032, 4.3% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Underground Infrastructure Sector: Inside the Worldwide Cast Iron Manhole Covers Market Study
Urban resilience begins beneath the surface. While often overlooked, the cast iron manhole cover serves as a critical interface between municipal operations, utility networks, and the daily reality of traffic, drainage, and public safety. For executives tracking infrastructure exposure, materials pricing, and regional project pipelines, understanding the trajectory of this market is no longer a niche exercise. It is a strategic input for capital allocation, supply chain positioning, and competitive forecasting.
Our latest Worldwide Cast Iron Manhole Covers Market research is designed to equip decision-makers with the analytical framework needed to navigate a segment undergoing steady structural expansion, shifting procurement standards, and intensifying competition across foundries and engineering-casting manufacturers. This article previews the strategic architecture of the report, outlines the macro forces that will shape 2026 planning, and clarifies how a detailed segmentation view can sharpen market-entry, sourcing, and pricing decisions.
A Market Defined by Durable Demand and Measured Expansion
Cast iron manhole covers remain a cornerstone of underground access solutions because of their compressive strength, load-bearing reliability, and compatibility with heavy-traffic environments. That functional durability translates into a market that grows through infrastructure renewal, utility upgrades, and the recurring need for compliant fittings in municipal and commercial settings. The global market for cast iron manhole covers has demonstrated a consistent expansion profile, with revenue crossing several billion-dollar thresholds over the past half-decade and continuing to advance through the forecast horizon.
The trajectory framed in the study is anchored in historical data from 2020 through 2025 and extended across a forecast window to 2032. This structure allows readers to compare post-pandemic recovery momentum, observe the inflection points where procurement cycles accelerated, and evaluate how the market compounds over time. The overall growth rate indicated by the analysis points to a compound annual growth rate of 4.3 percent across the forecast period, reflecting the combined influence of sustained municipal spending, utility modernization, and ongoing replacement demand in mature and developing regions alike.
It is worth emphasizing that the market’s resilience is not driven by sudden spikes but by the steady cadence of infrastructure necessity. That makes the sector particularly valuable for planning purposes: the growth is measurable, the product requirement is tied to standards, and the regional distribution reflects where construction activity, maintenance budgets, and export-oriented manufacturing capabilities intersect. For a company evaluating exposure to infrastructure-linked product lines, this is a segment where informed positioning can compound advantage over multiple project cycles.
Why 2026 Is a Decision-Point Year
The beginning of the forecast period is especially relevant because it sits at the convergence of several operational forces. Input costs are fluctuating, capacity utilization in upstream metal sectors is shifting, and regulatory expectations continue to sharpen around load classes, material specifications, and certification requirements. In this environment, companies that rely on generalized assumptions about demand or pricing can misjudge margins, lead times, and competitive positioning.
The research is therefore built to support three classes of strategic action. First, it helps leadership evaluate where demand is structurally concentrated by application type and geographic market, without reducing the analysis to superficial regional rankings. Second, it enables procurement and supply chain teams to connect market-level revenue movement with underlying cost dynamics, such as scrap input trends and foundry capacity behavior. Third, it provides executives with a competitive map that goes beyond brand presence and instead examines manufacturing focus, export footprint, product range breadth, and recent strategic moves that may signal capacity expansion or product-mix evolution.
This is not a static sizing exercise. The report connects top-line market evolution with the operational realities that determine who can serve which projects efficiently, which load and compliance specifications are gaining procurement emphasis, and how manufacturers are differentiating through product design and regional distribution capability.
What the Study Covers: Practical Intelligence, Not Just Aggregate Sizing
A market study earns its value when it can be operationalized. To that end, the worldwide cast iron manhole covers analysis is structured around the details that executives, project developers, and supply chain leaders actually use during planning. The report examines revenue performance across the historical base and forecast timeline, then breaks the market into actionable dimensions so readers can locate their own exposure within the broader landscape.
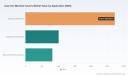
The segmentation architecture includes regional and national-level demand contexts, product-type distinctions, and application categories that matter for procurement strategy. These dimensions are essential because a manhole cover deployed in a municipal roadway is not interchangeable with a utility access point or an industrial facility fitting, even if the underlying material category is similar. Likewise, regional dynamics differ in terms of project sourcing models, standard preference, export orientation, and the competitive intensity of local foundries versus international manufacturers.
The study also investigates the competitive field in depth. Rather than listing companies as isolated profiles, the analysis situates manufacturers within the market’s structure by examining their production orientation, geographic reach, product design emphasis, and recent activities that may affect their ability to win contracts or expand share. This includes attention to firms with strong municipal-project pedigrees, exporters serving multiple continents, Gulf-region producers with municipality-linked demand, and specialized manufacturers offering custom casting configurations. The result is a competitive view that helps readers understand not only who participates, but how they may be positioned to capture demand differently.
Beyond segmentation and company profiling, the report incorporates market-concentration metrics that reveal the degree of fragmentation and consolidation. These indicators are useful for assessing bargaining dynamics, entry barriers, and the likelihood that pricing power will remain distributed or begin to concentrate among a smaller group of high-volume producers. The inclusion of these metrics helps clarify whether a market is defined more by broad participation or by the strategic influence of a handful of scaled players.
Recent Moves That Signal Where the Market Is Heading
Recent corporate activity adds a practical dimension to the forecast. Product development efforts, trade-show participation, and targeted launches can reveal where manufacturers see the greatest opportunities and what kinds of performance demands they expect to dominate procurement conversations. Recent developments captured in the study include product offering updates from manufacturers emphasizing customized round cast iron manhole cover solutions, continued trade-show engagement by exporters showcasing cast iron solutions across international audiences, and specialized product introductions aimed at climate-resilient performance with innovative clamping and hinge systems designed for extreme weather conditions.
These moves matter because they reflect how manufacturers are adapting to procurement priorities that increasingly combine durability, standard compliance, and application-specific resilience. For buyers and investors, such developments can signal which suppliers are investing in design differentiation versus competing primarily on volume and price. For analysts, they provide leading indicators of where future revenue may be won—especially in applications exposed to heavy loads, repeated service cycles, and environmental stress.
Structural Dynamics: Materials, Standards, and Competitive Realities
No forecast for cast iron manhole covers can be separated from the inputs and standards that govern production and procurement. The study integrates current industry context around raw material economics and regulatory expectations so that strategic conclusions remain grounded in operational reality.
On the input side, scrap pricing and foundry-level capacity utilization are recurring variables that influence cost structures and margin stability. Recent data points on cast iron scrap price movement and steel mill capacity utilization highlight the ongoing volatility that manufacturers must manage. These fluctuations do not change the long-term demand story, but they do affect short-to-medium-term pricing, tendering behavior, and the relative competitiveness of regional producers with different sourcing configurations. For a company planning procurement or export strategy, these dynamics are not background noise; they are a direct factor in cost forecasting and sourcing negotiation.
On the regulatory side, compliance standards and certification requirements shape product design, market access, and the credibility of suppliers in public-sector and infrastructure projects. International standards defining load classes and performance requirements for gully tops and manhole tops remain relevant across vehicular and pedestrian environments. At the same time, national certification regimes continue to reinforce quality expectations for cast iron covers and frames in key infrastructure markets. The study discusses how these requirements influence product differentiation and procurement preference, especially in settings where safety, durability, and compliance documentation are procurement prerequisites rather than optional enhancements.
The broader materials context also affirms the continued relevance of cast iron. The segment retains a significant material share in the wider manhole cover category because of its suitability for high-load applications and its compatibility with established installation and maintenance practices. That structural advantage is one reason the market can sustain expansion even as alternative materials and composite solutions evolve in adjacent niches.
Worldwide Cast Iron Manhole Covers Market
What Leaders Should Do With This Intelligence
The purpose of this research is to convert a complex, infrastructure-linked market into clear strategic options. The following priorities emerge naturally from the structure of the study:
- Map demand exposure by application and region to determine where your product mix, certifications, and distribution capabilities are best aligned with near-term procurement cycles.
- Track input-cost volatility and upstream capacity conditions as part of pricing strategy, especially when negotiating long-cycle municipal or utility contracts.
- Use the competitive analysis to distinguish between volume-driven suppliers, export-oriented manufacturers, and firms investing in design or resilience-oriented product features.
- Assess whether market concentration trends will affect entry feasibility, bidding dynamics, or the need for partnership and localization strategies.
- Evaluate regulatory and standards alignment as a precondition for market access in regions where compliance documentation and load-class performance are procurement gatekeepers.
These actions are most effective when supported by the full segmentation view and company-level detail provided in the complete study. The preview above establishes the strategic rationale; the full research delivers the numbers, comparisons, and trend interpretation needed to act on it.
Manhole Covers Market
Why the Complete Report Is Worth the Deep Dive
Executive summaries can indicate direction, but they cannot replace the analytical resolution required for sourcing strategy, regional prioritization, or competitive benchmarking. The full market study provides detailed segmentation data, supplier profiling, concentration metrics, and forward-looking interpretation that together support more decisive planning. It allows teams to move from general awareness of market expansion to specific conclusions about where opportunity is concentrated and which operational factors will determine execution success.
For organizations comparing market-entry options, evaluating supply agreements, or tracking infrastructure-exposed product lines, the study is built to reduce uncertainty and improve forecast credibility. Readers gain a structured view of how the cast iron manhole covers market has evolved, how it is likely to progress through the end of the decade, and which competitive and operational variables will matter most in the next planning cycle.
How to Access the Full Strategic Analysis
The complete Worldwide Cast Iron Manhole Covers Market study is available through the PW Consulting research portal. It provides the detailed segmentation, company-level competitive assessment, historical and forecast revenue trajectory, and the market-concentration context needed to translate infrastructure demand into practical business strategy. For teams preparing for 2026 decisions, the full report offers the depth required to move beyond high-level assumptions and into actionable intelligence.
This market remains defined by durable demand, standards-driven procurement, and competitive positioning shaped by manufacturing capability, export reach, and ongoing product innovation. With the right analytical foundation, those characteristics become manageable variables rather than unknowns. The study is designed to provide precisely that foundation.
For detailed analysis of this topic, please visit the official page: Worldwide Cast Iron Manhole Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ice Silk Sleeves Market Hits $528.5M in 2025, Projected to Reach $809.5M by 2032 with 6.28% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for a Warming World: Inside the Worldwide Ice Silk Sleeves Market Outlook 2026–2032
The global climate trajectory, coupled with the mainstreaming of functional apparel, has transformed ice silk sleeves from a niche accessory into a high-growth commercial category. As summer intensities rise and outdoor lifestyles expand across urban and recreational segments, demand for lightweight, UV-protective, and thermally soothing arm coverings is accelerating. This article introduces PW Consulting’s latest Worldwide Ice Silk Sleeves Market research, a comprehensive strategic assessment designed to equip executives, supply chain leaders, and commercial operators with the analytical architecture needed to navigate the 2026–2032 planning cycle.
Rather than functioning as a static statistical summary, this study is built as an actionable decision-support instrument. It maps demand inflection points, material cost dynamics, regional consumption behaviors, and competitive positioning into a single integrated framework. The analysis draws on five years of historical tracking (2020–2025) and extends forward through a forecast horizon that captures both steady expansion and short-term cyclical adjustments. For organizations evaluating product roadmap priorities, sourcing strategies, or geographic expansion, the report delivers the structural clarity required to move from reactive adaptation to proactive portfolio design.
Macro Trajectory: Sustained Expansion With Built-In Volatility Signals
The overarching market narrative is one of consistent value creation. From a baseline of approximately 390.15 million USD in 2020, the worldwide ice silk sleeves market progressed through successive annual gains, reaching 528.5 million USD by 2025. The 2026 baseline registers around 580.11 million USD, reflecting continued commercial adoption across sports, commuting, and professional use cases. The forecast window then projects a compound annual growth rate of 6.28 percent, guiding the market toward a 2032 valuation above 809 million USD.
This trajectory is not a smooth linear line. The dataset contains year-over-year variations that underscore the influence of seasonal purchasing intensity, inventory cycles, and material pricing fluctuations. Analysts using the report will see how these deviations are contextualized rather than smoothed away, enabling more realistic revenue planning, production scheduling, and promotional calendar design. The inclusion of historical volatility alongside forward estimates ensures that leadership teams can distinguish between structural growth and temporary demand spikes when modeling multi-year scenarios.
Currency consistency across the entire dataset—presented in USD with revenue measured in millions—allows for straightforward benchmarking against broader apparel and accessories categories. Executives can integrate these figures directly into category-level P&L models, market share simulations, and entry-cost assessments without needing to redo currency conversions or unit reconciliations.
Competitive Architecture: Fragmented Leadership and the Rise of Niche Specialists
The competitive structure of the ice silk sleeves market is characterized by a relatively dispersed concentration profile. The combined share of the top three participants sits at 18.45 percent, while the top five hold 24.12 percent. This dispersion signals an environment where scale advantages exist but are not yet decisive enough to lock out agile, design-forward, or channel-specialist players. For new entrants and established brands alike, the implication is clear: differentiation in fabric performance, fit engineering, UV certification messaging, and e-commerce presence can outweigh pure production volume in many commercial contexts.
The report profiles a cross-section of organizations that illustrate the market’s operational diversity. Achiou, operating from China as a manufacturer and exporter, has built visibility through cooling ice silk arm sleeves with UPF 50+ protection, emphasizing nylon-spandex blends designed for sports such as volleyball, cycling, and outdoor activities, with distribution concentrated on major e-commerce platforms. Hikesity, active as an online retailer and brand, focuses on ice silk UV protection sleeves with a UPF50+ rating for everyday and athletic usage, positioning cooling comfort and sun safety as joint value drivers. Body Helix, based in the USA, specializes in UV arm sleeves that leverage ice silk fabric for moisture-wicking and breathable sun protection, catering to pickleball, hiking, and outdoor sports audiences.
Arabella Clothing operates as a sportswear manufacturer that produces UV-protective arm sleeves using ice silk fabric with a cooling sensation, while also supporting custom printing routes—heat-transfer, screen printing, and sublimation—for tailored sports applications. On the manufacturing supply side, Shenzhen Eigday Heating Limited, known through the Day Wolf brand, produces wholesale OEM ice silk cooling sleeves with UV protection for arm and hand coverage, embedded within a broader apparel and sporting goods manufacturing operation with dedicated sewing lines. Yiwu An Jun Outdoor Product Co., Ltd., operating under the ALKINGLINE brand, supplies ice silk sun protection arm sleeves for outdoor sports, cycling, and hiking, and has offered OEM and custom services since 2017 as an outdoor products specialist. Guangzhou Chenquan Technology Co., Ltd. rounds out the profiled set with a manufacturing focus on summer UV protection ice silk arm sleeves for outdoor sports, emphasizing cooling, refreshing, and breathable design language.
Together, these profiles do more than identify competitors; they reveal viable operating models. Some players win through platform-driven scale and efficient SKU proliferation. Others compete via specialized use-case positioning, such as pickleball or golf, or through custom branding services that serve team, club, and promotional buyers. The report analyzes how these models interact with channel economics, inventory timing, and regional consumer expectations, helping decision-makers determine which competitive posture aligns with their capabilities.
Material Realities and Consumer Value Perception
Underpinning the commercial narrative is a material landscape that directly affects margin architecture and product positioning. Ice silk fabric for sun protection sleeves is typically realized through polyester-spandex or nylon-spandex blends. From a sourcing perspective, polyester-based imitation ice silk generally costs approximately 2.1 to 2.5 USD per meter, while nylon-spandex variants range from 3.5 to 5 USD per meter, depending on weight and UV additive specifications. These input differences shape more than unit cost; they influence drape, recovery, perceived cooling quality, and the technical story brands can tell in marketing and packaging.
Consumer-facing value claims are equally important to commercial performance. Ice silk sleeves are positioned as a cooling solution capable of delivering a perceived temperature drop of up to 5 degrees Celsius in summer conditions during outdoor activities such as driving, cycling, and sports. Whether measured through controlled testing or perceived comfort, this thermal sensation has become a core purchase driver, especially in markets where heat management is a daily concern rather than a seasonal novelty.
Performance claims also affect channel trust and compliance storytelling. Common market positions for ice silk arm sleeves include UPF 50+ protection blocking over 98 percent of UVA and UVB rays, with fabrics generally aligned to textile safety standards for skin contact products. The study examines how these claims are communicated, verified, and differentiated across portfolios, helping brands avoid generic messaging and instead build defensible product narratives that resonate with both retail buyers and direct-to-consumer audiences.
Recent Market Dynamics: 2025–2026 Innovation Cadence
The short-term innovation calendar is an important signal for brands planning 2026 assortments. In January 2026, multiple Chinese manufacturers showcased new product catalogs and SKU launches through platforms such as Alibaba, highlighting 2026 model ice silk arm sleeves with extended UV protection, seamless designs, and themed patterns, including football and World Cup motifs intended for sports and outdoor use. This wave underscores the category’s responsiveness to sporting events, visual customization, and the ongoing push toward lighter, more refined construction.
A separate but complementary development emerged in September 2025, when various exporters introduced golf and driving-specific ice silk sun protection sleeves. These launches emphasized lightweight, high-elasticity, and breathable constructions with enhanced UV blocking, reflecting how activity-specific engineering is becoming a standard expectation rather than a premium exception. Together, these developments illustrate a category that is simultaneously standardizing core benefits while fragmenting into use-case-tailored variants. For commercial teams, the strategic question is not whether to follow these trends, but how to sequence product refreshes, inventory commitments, and channel placement so that innovation translates into sell-through rather than markdown pressure.
The report integrates these developments into its forward-looking framework, connecting product-level signals to broader demand patterns. By aligning launch timing with seasonal purchasing peaks and regional preference profiles, the study helps organizations avoid the common trap of designing for innovation alone while neglecting the commercial mechanics required for adoption.
Worldwide Ice Silk Sleeves Market
Report Architecture: What Decision-Makers Can Expect
This market research is structured to move from high-level market definition to operational detail, ensuring that both strategic and tactical teams can extract usable insights. The analysis covers the complete 2020–2025 historical period and the 2026–2032 forecast horizon, with dedicated attention to the forces shaping growth, substitution risks, and demand concentration across usage environments.
- Market definition and boundary conditions, including how ice silk sleeves are positioned relative to broader arm sleeve, sun protection, and cooling apparel categories.
- Demand segmentation by region, material type, and application, presented in a way that supports portfolio planning without reducing the market to oversimplified share tables.
- Competitive profiling that links company-origin strategies, manufacturing postures, and channel approaches to likely market outcomes over the forecast period.
- Material cost context and performance claim analysis, including how input price bands and UV certification narratives influence pricing architecture and consumer perception.
- Recent product and sourcing developments, mapped to seasonal demand logic and event-driven purchase behavior.
- Strategic implications for product roadmapping, sourcing resilience, geographic prioritization, and branding differentiation.
Throughout, the report avoids isolated data dumps. Instead, it connects quantitative indicators to qualitative drivers, helping leadership teams interpret what a growth rate or market valuation actually means for sourcing commitments, SKU breadth, and channel investment. The goal is to provide enough granularity for operational planning while preserving strategic coherence at the portfolio level.
Why The 2026 Edition Matters Now
The 2026 edition is released at a point where the market’s direction is visible but its optimal execution paths remain contested. The category benefits from credible functional appeal—cooling sensation, UV protection, moisture management, and comfort—but it also faces pressure from material cost variability, fast-moving product refreshes, and an increasingly crowded digital shelf. Organizations that treat the market as purely opportunistic risk overcommitting to trends that dissipate; those that treat it as purely technical risk missing the consumer experience and channel dynamics that drive repeat purchase.
The study addresses this tension by pairing market-scale forecasting with competitive and material context. Executives can use it to evaluate whether to scale across multiple applications, concentrate on high-conviction use cases, enter specific regional demand pools, or build OEM and customization capabilities around a core material platform. Marketing and product teams can use it to refine benefit claims, streamline assortment logic, and align visual identity with the cooling-and-protection positioning that has become category-defining. Sourcing and operations teams can use it to anticipate where fabric selection, UV additive requirements, and garment construction choices will most influence cost and performance trade-offs.
Intelligence Designed for Action
PW Consulting’s Worldwide Ice Silk Sleeves Market research is built for organizations that need more than a top-line estimate. It provides a structured view of a category that is expanding on the back of climate adaptation, activity-led apparel demand, and continuous product refinement. The full edition delivers the complete segmentation architecture, the detailed company evaluations, the forecast breakdowns, and the strategic implications that cannot be fully unpacked in an overview format.
For leaders preparing 2026 investment decisions, assortment calendars, and sourcing strategies, the report serves as a reference point for disciplined market entry, expansion, and differentiation. Readers seeking the complete analytical set—including region-by-region demand patterns, material-type evaluations, application-level momentum, and full competitive benchmarking—are encouraged to access the full report through the official PW Consulting market research page. There, the data, context, and executive recommendations are presented in their complete form, enabling teams to translate high-level growth signals into concrete, commercially viable actions.
Worldwide UV Protection Sun Sleeves Market
For detailed analysis of this topic, please visit the official page: Worldwide Ice Silk Sleeves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Integral Waterproofing Compound Market to Hit $6,043.68M by 2032 at 5.28% CAGR
By pmarketresearch, 2026-09-16
Worldwide Integral Waterproofing Compound Market: Strategic Intelligence for the 2026 Decision Cycle
Why This Study Matters Now
As global construction activity rebounds and infrastructure investment accelerates across emerging and mature economies, the integrity of concrete structures has become a central concern for developers, contractors, and asset owners. Water ingress remains one of the most persistent drivers of durability failure, lifecycle cost escalation, and warranty exposure. Integral waterproofing compounds have evolved from niche chemical additives into a core specification item for ready-mix producers, precast manufacturers, and specialty contractors. The Worldwide Integral Waterproofing Compound Market study published by PW Consulting is designed to give executive teams, procurement leaders, and strategy directors a complete operational map of this space as they plan for the 2026 to 2032 horizon.
PVC Compound Market
The research arrives at a moment when material economics, regulatory expectations, and specification practices are shifting simultaneously. Decision-makers need more than a high-level top-line number. They need to understand how pricing structures, admixture compatibility, regional demand patterns, and competitive positioning interact to shape margin potential and market access. This report is built to support those decisions with a disciplined, data-rich framework that can be directly integrated into portfolio planning, commercial strategy, and technology roadmaps.
Worldwide Integral Waterproofing Compound Market
Market Trajectory and the Strategic Message Behind the Numbers
The overarching story of the integral waterproofing compound market is one of steady, value-driven expansion. From a 2020 baseline of approximately 3,254 million USD, the market moved through a series of growth cycles to reach an estimated 4,215 million USD in 2025. The forward trajectory outlined in the study points to a 2026 valuation near 4,628 million USD, with continued expansion toward 6,043 million USD by 2032. This represents a forecast CAGR of 5.28 percent across the 2026 to 2032 period.
These figures are more than historical markers. They reflect a market that is maturing in its technology base while expanding in its addressable application set. The growth path suggests that integral waterproofing is no longer limited to reactive repair or high-risk environments. It is increasingly embedded in standard mix designs for buildings, transport infrastructure, water retention structures, and industrial slabs. For corporate strategists, the implication is clear: the market is large enough to support focused product specialization, but dynamic enough that early positioning in high-growth segments can create durable competitive advantage.
PW Consulting intentionally refrains from releasing isolated regional revenue splits or application-level financial breakdowns in the executive summary. The full report contains that granularity, but the strategic point here is that the aggregate growth narrative is diversified. No single geography or end-use sector carries the entire expansion burden. That diversification reduces concentration risk and creates multiple entry and expansion pathways for manufacturers, distributors, and admixture suppliers. The complete segmentation architecture is available in the paid research, where regional dynamics, application preferences, and type-based demand structures are unpacked with detailed tables and interpretive commentary.
What the Report Delivers: A Practical Toolkit for Commercial and Technical Teams
This study is structured as an operational document rather than a descriptive overview. It brings together market sizing, segmentation logic, competitive assessment, and demand-side context in a single analytical flow. The objective is to help organizations answer concrete questions about where value is being created, which product formats are gaining specification share, and how competitive intensity is shaping pricing and differentiation.
Core Analytical Components
- Total market sizing and five-year forward estimates that connect historical performance with forecast logic, enabling scenario planning for capacity, inventory, and sales target setting.
- Segment-level analysis across product type, application, and regional demand, allowing readers to understand how crystalline, liquid, and powder-based solutions are positioned in different construction environments and supply chains.
- Competitive landscape mapping that profiles major participants, examines their product architectures, geographic reach, and technical specialization, and identifies where market concentration ishighest.
- Supply-side and cost-driver commentary covering raw material exposure, formulation trends, and manufacturing considerations that affect margin resilience and product positioning.
- Regulatory and sustainability context, including the growing influence of low-VOC formulations, bio-based hydrophobic agents, and green building credit requirements on specification choices.
- Practical guidance for assessing investment opportunities, expansion priorities, and product roadmap decisions in a market where performance claims, durability warranties, and admixture compatibility increasingly shape buyer behavior.
The report also integrates qualitative signals that matter for execution. For example, it examines how liquid integral waterproofing formats have gained share in ready-mix environments because of ease of automated dosing and compatibility with supplementary cementitious materials. It considers how crystalline technologies continue to serve applications where long-term permeability reduction and self-healing characteristics are valued. It also addresses the commoditization pressure facing basic hydrophobic powder blends in price-sensitive channels, alongside the premium positioning available for higher-performance crystalline and hybrid systems.
Competitive Landscape: Established Leaders and Emerging Differentiation
The integral waterproofing compound market features a mix of global construction chemical incumbents, specialized admixture manufacturers, and regional players with strong distribution or technical footprints. The study profiles this landscape in depth, but several structural themes are already visible. Market concentration is moderate rather than extreme, with the top three participants representing roughly 28.4 percent of revenue and the top five reaching about 41.65 percent. That level of concentration suggests a market where scale matters, but where technology, localization, and service capability still create room for differentiated positioning.
Major Participants and Their Strategic Postures
- Sika AG, headquartered in Baar, Switzerland, brings a long heritage in integral watertight concrete admixtures and a broad portfolio that spans crystalline permeability-reducing products and watertight concrete systems. Its historical lineage in permeability control gives it a strong technical narrative in demanding infrastructure and commercial projects.
- Kryton International Inc., based in Vancouver, Canada, is closely associated with crystalline concrete waterproofing technology, particularly its internal membrane approach that emphasizes durability and self-healing performance. This focus makes it a reference point in specifications where long-term water protection is a priority.
- Xypex Chemical Corporation, also based in Canada, specializes in integral crystalline waterproofing admixtures designed to integrate into the concrete matrix and reduce dependence on external surface membranes. Its value proposition aligns with projects that require durable, low-maintenance protection.
- The Euclid Chemical Company, located in Cleveland, Ohio, United States, offers powdered integral water repellent blends that form internal barriers against water penetration in concrete and mortar. Its product style suits markets where practical mix integration and cost-effective protection are important.
- Anti-Hydro International, operating in the United States, produces integral waterproofing admixtures with a long usage history in concrete and masonry applications, reinforcing the perception of proven performance in conventional construction settings.
- Pioneer Fibre, with headquarters in Hong Kong and global operations, manufactures integral and crystalline waterproofing systems used in infrastructure work across more than 20 countries, including major bridges and tunnels. Its project footprint underscores the relevance of integral solutions in heavy civil and transport applications.
- Chem Concrete Pty Ltd, based in Australia, focuses on a hybrid integral waterproofing admixture that combines multiple performance mechanisms, including densifiers, repellents, pore blockers, nano-technology elements, and self-healing characteristics. Its patent-pending approach and long-term performance warranties reflect a trend toward multi-mechanism product design.
- BASF SE, through its Construction Chemicals division and MasterLife brand in Ludwigshafen, Germany, supplies integral waterproofing compounds and admixtures that support concrete durability and permeability reduction within a broader chemical portfolio.
- Mapei SpA, headquartered in Milan, Italy, offers integral waterproofing admixtures as part of an extensive concrete admixture portfolio, giving it broader formulation and distribution leverage in construction markets.
- Fosroc International, based in Dubai, UAE, provides integral waterproofing admixtures and construction chemical solutions that address water permeability reduction across diverse project environments.
- Pidilite Industries Ltd., located in Mumbai, India, supplies integral waterproofing compounds and admixtures with a strong presence in Asian construction markets, where rapid urbanization and infrastructure activity sustain demand.
- Penetron International Ltd., based in the United States, specializes in integral crystalline waterproofing systems focused on concrete durability and protection, reinforcing the importance of crystalline technology in performance-led specifications.
The competitive takeaway for strategy teams is not simply who is present, but how different companies are competing. Some participants lean on heritage, global distribution, and broad admixture portfolios. Others compete on crystalline technology leadership, hybrid formulation architecture, or regional proximity and service intensity. The report analyzes these positions in greater detail, including how companies are likely to respond to cost pressure, specification changes, and the need for performance documentation. It also examines where consolidation, partnership, or new product introduction may alter the current balance.
Demand Dynamics, Material Economics, and the Cost Environment
Integral waterproofing demand does not move in isolation. It is shaped by construction cycles, engineering specifications, ready-mix production practices, and the economics of raw material supply. The study integrates these factors to give readers a clearer picture of what drives volume, pricing, and profitability in different parts of the value chain.
Raw Material Exposure and Formulation Economics
Key feedstocks for integral waterproofing compounds include silica sand, Portland cement derivatives, silicone monomers, and specialty polymer emulsions. These inputs are sensitive to energy prices and broader commodity cycles, which means production costs can shift meaningfully over relatively short periods. Historical volatility in silicone prices, including surges of more than 80 percent in certain regional markets during the 2021 to 2023 window, illustrates how quickly input cost pressure can affect manufacturers that do not manage formulation sourcing or pricing mechanisms effectively.
At the same time, product economics vary sharply by format and performance tier. In Asia Pacific markets, commodity hydrophobic powder admixtures can be available at under 1.50 USD per kilogram, while premium crystalline grades may range from 8 to 15 USD per kilogram. That wide spread highlights a market with both price-competitive and value-premium segments. For suppliers, the strategic challenge is to align product architecture, warranty claims, technical support, and distribution strategy with the right price tier. For buyers, the relevant question is when basic water repellency is sufficient and when the performance case justifies higher-grade crystalline or hybrid solutions.
The full report contains the segment-level interpretation that connects these material dynamics to demand behavior, margin potential, and regional pricing patterns. That level of detail is essential for manufacturing strategy, because the same market can support very different business models depending on whether a company is competing in commoditized powder blends or higher-specification crystalline and hybrid systems.
Sustainability, Regulation, and the Shifting Specification Environment
Specification trends are becoming an increasingly important force in integral waterproofing. Green building frameworks and sustainability-oriented procurement practices are encouraging the use of low-VOC and bio-based hydrophobic agents derived from plant fatty acids. These developments are not merely compliance issues; they are becoming part of the value proposition for manufacturers that can document environmental performance while maintaining durability.
LEED and BREEAM credits, among other rating systems, can influence material selection in commercial and institutional projects. As a result, formulation direction is moving toward products that support both water protection and broader sustainability objectives. The study addresses this shift as a strategic opportunity and a risk for companies whose portfolios remain heavily dependent on conventional chemistries without clear sustainability roadmaps. It also explores how performance claims, third-party testing, and warranty structures can strengthen a product's position when specification decisions become more multi-dimensional.
For enterprise strategists, the regulatory and sustainability angle is especially important because it affects both demand creation and competitive differentiation. A product that meets durability expectations and supports green building goals can earn preferential placement in bids, design specifications, and procurement contracts. The report explains how to assess this dynamic across applications and regions, and where sustainability-led differentiation is most likely to translate into commercial gains.
How to Use This Research for 2026 Planning
The Worldwide Integral Waterproofing Compound Market study is designed to be actionable. It supports a range of planning activities, from market entry and expansion assessment to product portfolio review and competitive benchmarking. The following use cases represent the most common ways corporate teams apply this type of analysis:
- Evaluating where to allocate commercial resources by identifying the product formats, applications, and regional contexts most aligned with a company's capabilities and margin targets.
- Assessing competitive vulnerability by understanding where concentration is highest, where specialist players are strongest, and where commodity pressure may compress pricing.
- Informing R&D and product roadmap decisions by linking performance claims, admixture compatibility, warranty strategies, and sustainability requirements to market demand.
- Supporting supply chain and cost planning by integrating raw material exposure, price volatility patterns, and input cost differentials into manufacturing and sourcing strategies.
- Strengthening investor, board, or client communication with a structured market narrative that combines historical performance, forecast direction, and competitive context without relying on unsupported generalizations.
Because the study is built for decision-making rather than passive reading, the full version includes the detailed segmentation tables, competitive profiles, and interpretive sections needed to translate strategy into execution. The executive overview provides confidence that the research is rigorous and market-specific, while the complete document delivers the precision required for internal modeling and planning.
Access the Full Strategic Intelligence
The Worldwide Integral Waterproofing Compound Market study from PW Consulting offers a comprehensive view of a market defined by steady growth, technological diversification, and increasing specification complexity. It combines top-line market direction with segment-level insight, competitive profiling, material economics, and sustainability trends to create a practical foundation for 2026 and beyond. The summary presented here demonstrates the scope and analytical depth of the research, while preserving the detailed regional, application, and financial breakdowns for the full report.
For organizations that need to make informed decisions about product positioning, geographic focus, supply strategy, or competitive response, the complete study provides the granularity required to move from high-level awareness to concrete action. The full report is available through the PW Consulting research portal, where decision-makers can access the complete dataset, segmentation analysis, and competitive intelligence needed to support confident strategy development.
For detailed analysis of this topic, please visit the official page: Worldwide Integral Waterproofing Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Orchard Sprayer Market Hits $631M in 2025, Projects $1B by 2032 at 6.8% CAGR
By pmarketresearch, 2026-09-16
Navigating the Green Shift: Strategic Intelligence for the Worldwide Electrical Orchard Sprayer Market (2026–2032)
The agricultural machinery sector is currently undergoing a profound transformation, driven by the dual imperatives of labor scarcity and environmental sustainability. Within this landscape, the Worldwide Electrical Orchard Sprayer Market stands out as a critical frontier for innovation and capital allocation. As we move into 2026, the transition from traditional diesel-powered equipment to electric and autonomous solutions is no longer a conceptual trend but a measurable shift in procurement strategies across major growing regions. For stakeholders in agribusiness, equipment manufacturing, and investment, understanding the trajectory of this market is essential for long-term resilience and growth.
Our latest comprehensive study, spanning historical analysis from 2020 through base year 2025 and forecasting out to 2032, provides a rigorous examination of this sector. This article serves as a strategic overview, highlighting the macro-economic forces, technological disruptions, and competitive dynamics that define the landscape. While specific quantitative breakdowns are reserved for the full detailed report, the trajectory indicates a robust expansion phase underpinned by technological maturity and regulatory pressure.
Market Trajectory and Growth Dynamics
The global market for electrical orchard sprayers has demonstrated consistent resilience and upward momentum over the past half-decade. Reflecting on the historical period from 2020 to 2025, the industry navigated supply chain challenges while accelerating adoption rates in premium crop segments. The market valuation witnessed a significant climb, moving from approximately $452.18 million in 2020 to an estimated $631.24 million by the base year 2025. This historical performance sets a solid foundation for the forecast period extending from 2026 to 2032.
Projecting forward, the market is poised to breach significant psychological and financial thresholds. Forecasts suggest a steady compound annual growth rate (CAGR) of 6.8%, indicating sustained demand rather than a temporary spike. By 2032, the market revenue is anticipated to approach the $1 billion million mark, reflecting the deep integration of electric technologies into standard orchard management practices. This growth is not merely a function of unit sales but represents a fundamental shift in how orchard operations are engineered, focusing on precision, autonomy, and emission reduction.
Several macro drivers are converging to support this trajectory. First, the global push toward decarbonization in agriculture is prompting governments and large-scale growers to prioritize electric machinery to meet sustainability certifications. Second, the diminishing availability of skilled labor in key horticultural regions is accelerating the adoption of autonomous spraying solutions that can operate with minimal human intervention. Third, the long-term operational cost benefits of electric systems, despite higher upfront capital expenditure, are becoming increasingly attractive as energy prices stabilize and battery technology improves.
Technological Architecture and Product Segmentation
The market is primarily bifurcated by power source and operational technology, each offering distinct value propositions to the end user. The dominant segment currently relies on battery-powered systems, which have benefited from advancements in lithium-ion energy density and cycle life. These systems offer the advantage of zero local emissions and reduced noise pollution, critical for orchards located near residential zones or sensitive ecosystems. Concurrently, a growing niche exists for hybrid electric solutions, which combine the endurance of internal combustion engines with the precision and low-emission benefits of electric drive systems, catering to operations where charging infrastructure remains limited.
Beyond power sources, the functional differentiation lies in the automation level. The industry is moving from simple electric propulsion to integrated autonomous systems. Modern electric sprayers are increasingly equipped with AI-driven weed detection, GPS/LiDAR navigation, and remote monitoring capabilities. This shift transforms the sprayer from a passive tool into an active data collection node within the farm's digital ecosystem. The ability to perform spot-spraying based on real-time weed detection significantly reduces chemical usage, which aligns with both cost-saving objectives and stringent environmental regulations regarding pesticide runoff.
Application areas remain concentrated in high-value specialty crops. Fruit tree orchards and vineyards represent the core demand drivers due to the high economic value of the produce and the necessity for precise chemical application to protect yield quality. Berry orchards also contribute to demand, though at a different scale, often driven by specific disease control requirements that benefit from low-volume, high-precision electric application methods. The versatility of electric platforms allows manufacturers to tailor solutions across these verticals, creating a diversified product portfolio that mitigates sector-specific risks.
Competitive Landscape and Strategic Consolidation
The competitive environment in the electrical orchard sprayer market is characterized by a mix of established agricultural machinery giants and specialized innovators. Market concentration metrics indicate a moderately fragmented landscape, though consolidation activity is intensifying. The top three players hold approximately 32.4% of the market share, while the top five account for roughly 48.75%. This structure suggests that while niche players can thrive through specialization, scale advantages are becoming increasingly important for global distribution and service support.
John Deere, particularly through its integration with GUSS Automation, represents a significant force in this space. The strategic acquisition completed in August 2025 marks a pivotal moment, integrating autonomous electric herbicide sprayer technology directly into one of the world's largest machinery portfolios. Their Electric GUSS unit, featuring Kreisel batteries for full-shift operation and AI weed detection, exemplifies the industry's direction toward autonomy and material efficiency. This move signals a broader strategy to capture value not just in hardware sales but in precision agriculture software and service ecosystems.
In Europe, companies like Nobili S.p.A. in Italy and MDE Machinebouw bv in the Netherlands are focusing on specialized electric architectures. Nobili's approach with dual electric motors for pumps and fan groups targets zero-emission operations in specialty crops, appealing to European markets with strict environmental compliance. MDE focuses on mounted pneumatic electric sprayers with varied capacities, catering to precision requirements in fruit tree applications. Similarly, TRS Sprayers & Equipment in New Zealand is pushing the envelope with the EON1 model, designed to pair with electric tractors for full orchard electrification, highlighting a systems-level approach to orchard energy management.
Worldwide Electrical Orchard Sprayer Market
Hol Spraying Systems (HSS) complements this landscape with towed orchard sprayers that blend hydraulic and electric features, offering flexibility for low-volume or precision spraying needs. More recently, updates from players like KUHN in April 2025 regarding revised tank sizes and simplified operation features indicate that even broader machinery manufacturers are refining their offerings to match the precision and usability demands of electric-compatible workflows. These developments underscore a competitive race to balance battery endurance, spray precision, and operator ease of use.
Operational Context and Regulatory Influences
Adoption of these technologies is heavily influenced by the regulatory and operational context in which they are deployed. Safety standards are becoming more rigorous, particularly concerning autonomous operation in environments where workers and machinery coexist. Advanced systems now incorporate safety protocols that automatically pause spraying when individuals are detected in proximity, aligning with operator safety and precision application standards. This feature is becoming a baseline expectation rather than a premium differentiator in mature markets.
Material availability and energy storage technology also play critical roles. The performance of electric autonomous orchard sprayers is contingent on battery technology advancements. For instance, certain high-capacity battery packs enable continuous operation for extended shifts, which is crucial for large-scale commercial orchards where downtime equates to significant revenue loss. The integration of such energy systems directly impacts the total cost of ownership calculations that growers perform when switching from diesel to electric fleets.
Furthermore, the ability of electric sprayers to support reductions in chemical usage through spot-spraying technologies is a powerful value proposition. Depending on weed pressure, these technologies can achieve substantial material savings, which resonates with both economic goals and sustainability mandates. This dual benefit is accelerating the payback period for electric equipment investments, making them more viable for mid-sized operations that previously found the capital cost prohibitive.
Strategic Implications for 2026 Decision-Makers
For executives and strategists navigating the 2026 landscape, the implications of this market evolution are multifaceted. Procurement strategies must now account for total lifecycle costs, including energy infrastructure requirements at orchard sites. Investing in electric sprayers often necessitates parallel investments in charging stations and grid capacity, which must be factored into capital planning. Companies that delay this transition risk higher operational costs and potential regulatory non-compliance as regions tighten emission standards for agricultural machinery.
From a product development perspective, the convergence of autonomy and electrification suggests that future competitive advantage will lie in software integration and data analytics, not just hardware durability. Manufacturers and service providers need to focus on building ecosystems that allow seamless monitoring and management of multiple units. The ability to remotely monitor operational status and chemical usage data is becoming a key requirement for enterprise-level orchard managers who operate across multiple locations.
Self-Propelled Sprayer Market
Investment capital should also be aware of the regional variations in adoption speeds. While specific market share percentages vary by geography, mature markets with high labor costs and stringent environmental rules are likely to lead in adoption rates. Emerging markets may follow a different trajectory, potentially leveraging hybrid solutions as a bridge technology before fully committing to battery-electric infrastructure. Understanding these nuances requires detailed regional intelligence that goes beyond global aggregates.
Supply chain resilience is another critical consideration. The reliance on specific battery technologies and electronic components introduces new dependency risks distinct from traditional mechanical supply chains. Diversifying suppliers and securing long-term contracts for critical energy components will be essential for manufacturers aiming to maintain production stability during the growth phase projected through 2032.
Conclusion: Accessing Deep-Dive Intelligence
The Worldwide Electrical Orchard Sprayer Market is at an inflection point where technology, regulation, and economics align to drive sustained growth. The data suggests a clear path toward a $1 billion market valuation by the early 2030s, supported by a healthy CAGR and widespread technological adoption. However, capturing value in this environment requires more than just recognizing the trend; it demands granular insight into segmentation, competitive moves, and regional dynamics.
While this overview highlights the strategic contours of the market, the full depth of our research offers the specific data points necessary for precise modeling and decision-making. Our complete report details the exact revenue splits across types and applications, regional performance metrics, and detailed profiles of every key player mentioned herein and their recent strategic developments. For stakeholders ready to commit to data-driven strategies in 2026, accessing this comprehensive intelligence is the next logical step.
To explore the full segmentation analysis, including detailed breakdowns by region, type, and application, as well as the complete competitive landscape and regulatory forecasts, we invite you to review the full Worldwide Electrical Orchard Sprayer Market research report. Equip your organization with the precise intelligence needed to navigate the electric shift in orchard management.
For detailed analysis of this topic, please visit the official page: Worldwide Electrical Orchard Sprayer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global GCB Market to Hit $548 Million by 2032, 6.81% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave of Power Infrastructure: Strategic Insights from the Worldwide Digital Generator Circuit Breaker Market Study
The global energy transition is not merely shifting fuel sources; it is fundamentally rewiring the architecture of power generation and protection. As utilities and independent power producers navigate the dual pressures of decarbonization mandates and grid reliability, Generator Circuit Breakers (GCBs) have emerged as critical guardians of turbine integrity and plant uptime. Our newly released Worldwide Digital Generator Circuit Breaker Market report delivers a comprehensive, data-rich examination of this vital sector, equipping executive teams with the foresight required to optimize capital allocation, technology roadmaps, and competitive positioning through 2032.
A Market in Measured Expansion
The trajectory of the global GCB market reveals a steady, structurally sound growth curve that rewards early strategic alignment. Between 2020 and 2025, the sector expanded from a baseline of approximately $252.14 million to $345.5 million, navigating supply chain recalibrations and macroeconomic volatility without losing momentum. Looking ahead, our baseline forecast places 2026 revenues at roughly $360.3 million, with a projected compound annual growth rate of 6.81 percent carrying the market to $547.57 million by 2032. This expansion is not accidental; it reflects the compounding impact of aging infrastructure replacement cycles, the commissioning of next-generation generation assets, and the accelerating digitization of plant protection systems. For capital planning teams, the message is clear: demand visibility is strong, but capturing it requires differentiated value propositions that transcend commodity pricing wars.
Technology Shifts Reshaping the Asset Base
The technological composition of the GCB landscape is undergoing a quiet but decisive transformation. Traditional SF6-insulated designs continue to hold substantial installed share, yet the market is increasingly tilting toward vacuum-based and air-insulated alternatives. This migration is being driven less by pure performance economics and more by the regulatory and ESG calculus surrounding fluorinated greenhouse gas emissions. Operators are now evaluating lifecycle environmental impacts alongside traditional interrupting capacity and short-circuit withstand metrics, a shift that has accelerated the adoption of vacuum interrupter architectures in both new builds and life-cycle retrofits. The resulting technology mix is fragmenting into distinct application niches, where duty-cycle requirements, generator sizing, and grid code compliance dictate technology selection. Our study dissects these technology pathways, mapping the engineering trade-offs that procurement and engineering teams must weigh when specifying protection systems for diverse generation profiles.
End-User Diversification and Application Realities
GCB demand is not monolithic. The market supply chain interfaces with a heterogeneous end-user base spanning thermal generation, hydropower, nuclear facilities, and emerging integrated gas and renewable platforms. Each segment imposes unique operational stresses and protection philosophies. Thermal and nuclear assets, with their high continuous currents and stringent reliability mandates, demand breakers engineered to specialized duty cycles that far exceed distribution-class specifications. Hydropower installations, meanwhile, require solutions capable of withstanding long mechanical endurance cycles and harsh environmental exposures. As grid architectures incorporate more decentralized and hybrid generation, the protection logic surrounding generator isolation is evolving, pushing manufacturers to deliver smarter, more adaptive interrupting solutions that integrate seamlessly with plant-level control architectures. The report segments these application realities with granular operational context, enabling stakeholders to understand where growth will materialize and which capability gaps represent the greatest commercial opportunity.
Worldwide Digital Generator Circuit Breaker (GCB) Market
Regional Realignment and Infrastructure Investment Cycles
Geographic demand patterns are being rewritten by localized energy security priorities, grid modernization budgets, and the pace of generation fleet turnover. Asia Pacific continues to anchor a substantial share of global activity, reflecting sustained investment in baseload and peaking capacity alongside rapidly expanding transmission infrastructure. Europe’s market is characterized by a emphasis on sustainability-compliant technologies, retrofitting of aging assets, and alignment with regional decarbonization frameworks. North America’s demand profile is shaped by reliability mandates, nuclear fleet extensions, and the ongoing modernization of both fossil and hydro generation assets. Meanwhile, the Middle East and Africa and Latin America represent high-growth frontiers where capacity expansion programs are driving new procurement waves. Our geographic analysis connects these regional narratives to underlying investment cycles, policy environments, and supply-side dynamics, providing a structured lens for market entry, partnership strategy, and localized capacity planning.
The Rise of Digital GCBs: From Interrupting to Intelligence
The defining innovation in the current market cycle is the transition from purely electromechanical interrupting devices to digitally enabled protection assets. These Digital GCBs embed smart monitoring, predictive maintenance capabilities, and communication protocols that transform breakers from passive safety components into active contributors to plant availability. By aggregating health data, enabling on-premise and cloud connectivity, and feeding asset management systems with real-time condition indicators, digital platforms are helping operators move from reactive maintenance to condition-based interventions. This shift carries profound implications for total cost of ownership, spare parts logistics, and overall plant reliability metrics. Our study examines how digitalization is being embedded across the value chain, from sensor integration and health diagnostics to cybersecurity considerations and interoperability with substation automation systems. For OEMs, the digital layer is becoming a differentiator and a recurring revenue frontier; for operators, it represents a pathway to extract more operational certainty from critical protection assets.
Competitive Landscape: Architects of the Next Generation of Protection
The global GCB arena is shaped by a concentrated group of incumbent manufacturers that have built deep engineering heritage, global service networks, and increasingly sophisticated digital portfolios. Market concentration data indicates that a small cohort of players commands a dominant share of deliveries, underscoring the importance of long-term supplier relationships and technology alignment in procurement strategy.
- Hitachi Energy stands as a historically dominant force in GCB technology, with a legacy spanning decades and thousands of field installations across demanding generation environments. The company’s recent strategic emphasis centers on digital integration, sustainability, and lifecycle management, exemplified by dedicated digital GCB platforms that tie into smart monitoring ecosystems for health data aggregation and predictive maintenance. Celebrating seven decades of innovation in early 2025, the firm has reinforced its commitment to enhancing generator protection through lifecycle optimization and connected asset management, positioning digital readiness as a core pillar of its value proposition.
- GE Vernova brings a broad, application-diverse portfolio to the market, with thousands of installations covering power plants across a wide capacity spectrum. Its product philosophy integrates optimized digital cooling solutions and intelligent communication capabilities to support real-time operational adjustments and remote health monitoring. In late 2025, the company updated its service documentation to accentuate maintenance, retrofit, and digital monitoring offerings, signaling an intensifying focus on post-sale value creation and the extension of asset service life.
- Siemens has carved a strong position around vacuum-based GCB systems that emphasize SF6-free operation and extended maintenance intervals, appealing to operators pursuing sustainability targets and reduced operational expenditure. Its portfolio supports generator and transformer protection with an emphasis on reliability, lifecycle efficiency, and compatibility with renewable integration strategies, aligning its technology roadmap with the broader decarbonization agenda.
- Eaton addresses specific segments of the market with medium-voltage generator breaker solutions engineered around rigorous industry duty requirements. Its vacuum-based families are designed to deliver high continuous current carrying capability and robust performance for smaller to medium generator sets, reflecting a focused engineering approach to specialized application duties and compliance-driven design.
Beyond product portfolios, the competitive arena is being reshaped by collaboration models, service bundling, and digital platform ecosystems. Firms are increasingly competing on total lifecycle value rather than unit price alone, integrating health monitoring, retrofit services, and remote diagnostics into long-term service agreements. Our competitive analysis unpacks these positioning strategies, service architectures, and innovation trajectories, offering a structured framework for benchmarking vendor capabilities and identifying partnership opportunities that align with your operational objectives.
Regulatory and Engineering Mandates as Market Catalysts
Market evolution does not occur in a vacuum; it is guided by international standards, safety requirements, and material constraints that define what is technically permissible and commercially viable. International standards such as IEC/IEEE 62271-37-013:2021 establish the performance framework for high-voltage generator circuit-breakers, specifying design expectations for indoor and outdoor installations operating above 1 kV up to 38 kV at 50/60 Hz. These standards reinforce the specialized nature of GCB design, distinguishing generator-duty requirements from distribution-class equipment and ensuring that interrupting performance, short-circuit ratings, and continuous current capabilities are validated under rigorous conditions.
Electronic Circuit Breaker Market
At the same time, engineering specifications anchored in standards such as IEEE C37.013 compel manufacturers and specifiers to approach generator protection as a distinct discipline, with unique duty cycles and reliability expectations. The material dimension adds another layer of strategic importance: the industry’s move away from SF6 toward vacuum interrupter technologies reflects both environmental compliance imperatives and corporate carbon reduction targets, influencing specification decisions across new builds and life-cycle upgrades. The report connects these regulatory and material dynamics to real-world procurement behavior, showing how standards compliance and sustainability preferences are steering technology selection, certification requirements, and service expectations across global markets.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Making
The Worldwide Digital Generator Circuit Breaker Market study is structured to support strategic decision-making at multiple levels, from corporate planning and technology investment to procurement policy and competitive positioning. It combines historical performance analysis with forward-looking forecasts, enabling readers to calibrate expectations against realized market behavior and projected growth corridors. The report provides:
- A structured market size and growth framework covering historical performance and the 2026–2032 forecast horizon, grounded in transparent methodologies and scenario-aware assumptions.
- Technology-based and end-user-based segmentation that clarifies how different application demands and engineering preferences drive volume distribution across the asset base.
- Regional demand mapping that links procurement momentum to infrastructure investment cycles, energy policy trajectories, and fleet renewal timelines.
- A competitive and vendor landscape analysis that evaluates product philosophies, digital service offerings, and lifecycle value propositions across leading manufacturers.
- An examination of the regulatory, standards-based, and material constraints shaping specification behavior and technology adoption.
- Practical strategic implications for operators, OEMs, service providers, and investors seeking to align capabilities with high-probability growth vectors.
Every section is designed to translate data into action. Rather than presenting isolated statistics, the analysis ties market size evolution, technology trends, and competitive moves to concrete executive questions: Which application segments are expanding demand fastest, and what capability gaps do they reveal? How does the digital layer change the economics of ownership and service? Where do standards and sustainability considerations most strongly influence specification decisions? What supplier relationships and partnership models will matter most in a concentrated, high-expertise market?
Strategic Imperatives for the Year Ahead
As 2026 unfolds, three strategic imperatives stand out for organizations operating in or adjacent to the GCB market. First, technology alignment is becoming a strategic differentiator: the shift toward vacuum and air-insulated architectures, combined with embedded digital monitoring, is changing the value calculus of protection assets and rewarding suppliers and operators who can navigate lifecycle environmental performance alongside electrical reliability. Second, digital value capture is moving from pilot to practice: health data aggregation, predictive maintenance, and connected asset management are transitioning from experimental features to core components of service contracts and uptime guarantees, creating new commercial models and new risk dimensions around data integration and cybersecurity. Third, regional nuance matters more than ever: procurement outcomes will increasingly depend on localized investment timing, regulatory expectations, and the maturity of service and retrofit ecosystems, making geographic precision essential for both market entry and supplier selection.
The Worldwide Digital Generator Circuit Breaker Market report is built to help leadership teams navigate these imperatives with confidence. By combining rigorous market sizing, segmentation clarity, competitive intelligence, and forward-looking scenario context, it offers a decision-grade foundation for capacity planning, technology roadmap development, vendor evaluation, and growth strategy. The full study contains the detailed data tables, segmentation breakdowns, regional analyses, and vendor profiles that executives and analysts require to translate market dynamics into executable strategy.
To access the complete forecast models, segmentation depth, and competitive benchmarking, visit the source page for the full Worldwide Digital Generator Circuit Breaker Market research. Obtain the full intelligence set and position your organization to act decisively on the opportunities shaping the next phase of generator protection and digital power infrastructure.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Generator Circuit Breaker (GCB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global IT Infrastructure Outsourcing Market Hits $435.5B in 2025 with 6.74% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Crossroads: Strategic Intelligence for the Global IT Infrastructure Outsourcing Market in 2026
In an era defined by rapid digital transformation, escalating cyber threats, and the convergence of artificial intelligence with core enterprise operations, IT infrastructure outsourcing has evolved from a cost-optimization tactic into a strategic imperative. As organizations worldwide recalibrate their technology stacks, the Worldwide IT Infrastructure Outsourcing Service Market has emerged as a critical battleground for competitive advantage, operational resilience, and regulatory compliance. This foundational industry analysis, grounded in rigorous historical tracking and forward-looking modeling, offers decision-makers a clear lens through which to evaluate one of the most consequential outsourcing segments of the decade.
Drawing on comprehensive data spanning 2020 through 2025 and projecting trends across a seven-year forecast horizon through 2032, the research captures not merely the trajectory of spending but the structural shifts redefining how enterprises consume, manage, and secure technology services. By synthesizing macroeconomic indicators, service-model evolution, and competitive positioning, this report equips executives with the contextual depth required to navigate procurement strategies, vendor selection, and long-term infrastructure roadmaps with confidence.
Worldwide Infrastructure as a Service Market
Historical Trajectory and the Scale of Transformation
The market has exhibited remarkable resilience and sustained growth throughout the tracking period. Starting from a baseline in 2020, the global revenue generated by IT infrastructure outsourcing services has expanded consistently, reflecting heightened enterprise dependency on outsourced operations amid cloud migration acceleration, legacy system modernization, and post-pandemic operational recalibrations. By the most recent measurement year, the market had crossed a significant threshold, signaling mature adoption patterns and the normalization of infrastructure outsourcing as a core business function rather than a peripheral support activity.
Looking ahead, the projected expansion through 2032 underscores a compounding growth dynamic. At a compounded annual growth rate of 6.74 percent, the market is positioned to traverse into materially higher revenue tiers over the forecast window. This trajectory is not merely a function of incremental spend; it reflects deepening enterprise commitments to integrated outsourcing models that bundle network operations, managed hosting, infrastructure management, and security oversight into cohesive delivery frameworks. For procurement leaders and C-suite strategists, such sustained expansion signals that the outsourcing landscape will remain highly active, competitively intense, and continuously reshaped by technological and regulatory forces.
Architectural Shifts Redefining Service Consumption
The composition of outsourced IT infrastructure has fundamentally restructured itself. What was once a spectrum dominated by standalone data center leases and routine help desk engagements has matured into a portfolio of sophisticated, interlocked service lines. Enterprises increasingly view outsourcing not as a series of discrete transactions but as an operational architecture that must deliver scalability, visibility, and risk mitigation simultaneously.
Managed hosting and data center services continue to anchor the market, reflecting enduring demand for reliable, geographically diversified compute environments. Yet the fastest-growing areas of investment are emerging where infrastructure services intersect with security postures, cloud orchestration, and AI-enabled monitoring. Network outsourcing remains essential for maintaining global connectivity and complex routing environments, while managed security services have become inseparable from infrastructure contracts as organizations confront the reality that uptime without protection carries unacceptable business risk. End-user support and help desk functions have also transformed; rather than being treated as reactive cost centers, they are being integrated into proactive service models that leverage automation, predictive diagnostics, and omnichannel engagement.
This structural rebalancing matters for strategy because it directly influences vendor evaluation criteria, contract architecture, and service-level expectations. Organizations that continue to evaluate outsourcing proposals through a narrow cost-per-ticket or per-server lens risk overlooking the value layers that now define market leadership: integrated threat detection, compliance assurance, hybrid environment orchestration, and AI-augmented operational intelligence.
Worldwide IT Infrastructure Outsourcing Service Market
Competitive Dynamics Among Enterprise-Scale Providers
The provider landscape is populated by global firms with distinct geographic footprints, delivery models, and strategic positioning. Market concentration, as measured by the combined share of leading participants, remains moderate, indicating a competitive field with room for differentiation and consolidation. This dispersion is significant for decision-makers because it implies that procurement leverage, specialized capability pairing, and partnership structuring can materially influence outcomes.
Several multinational integrators and technology consultancies anchor the upper tier of the market. Each brings a differentiated mix of managed services, cloud operations, hybrid infrastructure support, and cybersecurity integration. Providers headquartered in North America and Europe maintain strong enterprise relationships and compliance-oriented delivery frameworks, while firms based in India and other high-scalability regions contribute scale, depth in infrastructure operations, and expanding capabilities in digital transformation and automation. Japan-based organizations extend global reach through established enterprise relationships and group synergies that span infrastructure, cloud management, and end-to-end IT operations.
What distinguishes competitive positioning in this environment is rarely a single offering. Instead, differentiation emerges from how providers combine data center management, network and infrastructure management, hybrid cloud capabilities, security integration, and industry-specific solutioning. The ability to operate across multiple service domains while maintaining rigorous controls, geographic flexibility, and contractual transparency has become a decisive factor in vendor selection. Organizations evaluating partners must therefore assess portfolios holistically, prioritizing providers whose delivery models align with specific risk tolerances, compliance regimes, and operational ambitions.
Regulatory Pressure and Compliance as Operational Gatekeepers
The outsourcing environment is increasingly defined by regulatory expectations that transform compliance from an administrative afterthought into an operational gatekeeper. Cybersecurity now stands alongside infrastructure services as one of the most frequently outsourced functions, reflecting board-level recognition that external expertise is essential for maintaining resilient security postures across complex, distributed environments. This shift is amplified by mandatory standards and frameworks that span data protection, transaction integrity, and operational transparency.
Providers and their clients are navigating an expanding matrix of compliance requirements. Data privacy and security obligations tied to GDPR, HIPAA, PCI DSS, and SOX continue to shape contracting practices, service design, and audit expectations. In parallel, certification and governance regimes such as SOC 2, ISO 27001, and emerging AI governance standards are becoming baseline expectations for organizations seeking to de-risk third-party relationships. Continuous vendor risk assessment, documented control environments, and transparent audit trails are no longer optional enhancements; they are prerequisites for long-term outsourcing engagements.
Cross-border dynamics add further complexity. Recent regulatory instruments, including stringent controls on transactions involving bulk sensitive personal data, impose heightened cybersecurity obligations and record-keeping requirements on international service arrangements. As a result, enterprises must weigh not only cost and capability but also jurisdictional exposure, data residency considerations, and the regulatory readiness of prospective partners. For procurement teams, compliance literacy has become a core competency, and vendor assessments must include rigorous review of security architectures, incident response processes, and governance maturity.
Labor Economics, Geographic Strategy, and the Push Toward Intelligent Delivery
The economics of outsourcing delivery are undergoing a meaningful recalibration. Rising labor costs in traditional outsourcing hubs have begun to reshape location strategies and operating models. Providers are responding with a combination of nearshoring, automation, and intelligent service design. This evolution is not simply a cost-response measure; it reflects a broader rethinking of how infrastructure services are delivered, monitored, and optimized.
AI-enabled management and automation are increasingly embedded into delivery frameworks. Predictive maintenance, automated incident triage, policy-driven orchestration, and agentic workflow integration are transitioning from experimental initiatives to operational realities. Recent strategic moves by major providers illustrate this momentum, including acquisitions and partnerships designed to embed advanced AI capabilities into business-process and infrastructure delivery. These developments signal that competitive differentiation will increasingly depend on how effectively providers blend human expertise with automated intelligence to reduce latency, improve accuracy, and scale service delivery without proportionally escalating cost structures.
For enterprises, this dynamic creates both opportunity and caution. Automation can unlock efficiency, but it also raises questions about service quality assurance, exception handling, and the strategic role of in-house teams. Organizations must define where intelligent automation adds genuine value and where human oversight remains essential, particularly in environments with stringent uptime requirements or sensitive operational contexts.
Strategic Imperatives for Enterprise Decision-Makers in 2026
As the market expands and its architecture grows more complex, strategic decision-making must move beyond transactional procurement. Several imperatives stand out for organizations planning their infrastructure outsourcing strategies over the coming years.
- Evaluate providers against an integrated capability baseline that includes hybrid infrastructure management, security integration, compliance readiness, and cloud orchestration rather than isolated service checklists.
- Treat regulatory alignment as a primary selection criterion, ensuring that partners can demonstrate control maturity, audit transparency, and the ability to adapt to evolving cross-border data and cybersecurity requirements.
- Structure contracts to incentivize outcomes, not only cost containment. Service-level frameworks should reflect integrated monitoring, proactive threat response, and continuous improvement expectations.
- Incorporate AI-augmented delivery and automation into sourcing evaluations, assessing how providers use intelligent tools to improve reliability, reduce response times, and manage scale efficiently.
- Balance global scale with geographic flexibility. Where labor economics, data residency, and latency concerns intersect, nearshoring and multi-region delivery models may offer more resilient operating postures than single-hub dependency.
Why Comprehensive Intelligence Matters Now
The Worldwide IT Infrastructure Outsourcing Service Market is at an inflection point where growth, technology convergence, and regulatory pressure intersect. In such an environment, partial visibility can lead to suboptimal vendor selection, misaligned contract structures, and unanticipated compliance exposure. Executive teams require market intelligence that connects historical performance, forward-looking projections, service-model evolution, and competitive dynamics into a coherent strategic framework.
This research report delivers exactly that synthesis. It provides a structured foundation for evaluating market direction, understanding the forces reshaping service demand, and identifying the criteria that will separate reliable partners from commoditized providers. By integrating rigorous market sizing, segmentation architecture, competitive profiling, and industry-context dynamics, the analysis supports more disciplined planning across procurement, IT leadership, risk management, and enterprise strategy functions.
To access the complete segment breakdowns, detailed competitive profiles, methodology depth, and forward-looking scenario analysis that support these insights, readers should consult the full report. The complete dataset and proprietary intelligence are essential for organizations seeking to convert market awareness into actionable, differentiated strategy.
For detailed analysis of this topic, please visit the official page: Worldwide IT Infrastructure Outsourcing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global 5G-Advanced Chip Market Poised to Hit $41.5B by 2032 at 40.45% CAGR
By pmarketresearch, 2026-09-16
Navigating the 5G-Advanced Chip Revolution: Strategic Intelligence for 2026 Enterprise Decisions
The global semiconductor landscape is undergoing a tectonic shift, driven by the transition from initial 5G deployment to the sophisticated capabilities of 5G-Advanced. As enterprises across telecommunications, automotive, industrial manufacturing, and consumer technology sectors evaluate their roadmaps for the latter half of the decade, the hardware foundation supporting these networks has become a critical variable in strategic planning. PW Consulting's latest Worldwide 5G-Advanced Chip Market report offers a comprehensive lens into this transformation, providing decision-makers with the data density required to navigate a market defined by rapid escalation and intense technological competition.
For stakeholders operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for capital allocation, supply chain resilience, and product portfolio optimization. The market has moved from nascent experimentation to high-volume commercialization, creating a complex environment where timing and technological alignment determine competitive advantage. This introduction outlines the strategic value embedded within our latest research, highlighting the market dynamics, competitive currents, and technical specifications that will define success in the coming years.
Market Trajectory and Macroeconomic Scale
The velocity of growth in the 5G-Advanced chip sector is unprecedented. Our analysis tracks the market evolution from a historical baseline through a forecast period extending to 2032. The data reveals a steep adoption curve that underscores the accelerating integration of advanced wireless capabilities into diverse hardware ecosystems. Starting from a foundational period, the market crossed significant thresholds in the early 2020s, with revenue figures climbing sharply as infrastructure and devices began aligning with evolving 3GPP standards.
Worldwide 5G Processor Market
By 2025, the market had reached substantial scale, reflecting the culmination of years of research and development into commercially viable products. Looking forward to 2026, the projected revenue continues to expand at a pace that demands attention from investors and corporate strategists alike. The compound annual growth rate (CAGR) observed over the forecast period indicates a sustained surge, driven by the proliferation of high-performance applications that require more than legacy connectivity. This growth is not linear; it is compounded by the expanding addressable market as 5G-Advanced features move from premium segments to broader industrial and consumer use cases.
The forecast horizon through 2032 suggests that the peak of this investment cycle is still ahead. Organizations that analyze these trends now can position themselves to capture value before the market matures and competition intensifies further. The sheer magnitude of the revenue projections emphasizes that 5G-Advanced is not a niche enhancement but a foundational shift in how connectivity is engineered and monetized.
Segmentation Dynamics: Types, Applications, and Regions
A granular understanding of where value is being created is essential for targeted strategy. The market is diversified across chip types, application verticals, and geographic regions, each with distinct growth drivers and technical requirements. Our report dissects these segments to reveal the underlying forces shaping demand.
In terms of chip architecture, the market is dominated by baseband processing capabilities, which form the core of signal handling and protocol management. However, the ecosystem is equally dependent on radio frequency (RF) transceivers and front-end modules, as well as power management solutions that ensure efficiency in high-performance deployments. The balance between these components reflects the broader engineering challenges of 5G-Advanced, where bandwidth, latency, and energy consumption must be optimized simultaneously.
On the application side, mobile devices and wearables remain a primary consumption channel, leveraging advanced modems to deliver enhanced user experiences. Yet, the industrial sector is emerging as a powerful growth engine. Industrial IoT and robotics applications are increasingly reliant on robust, low-latency connections that 5G-Advanced chips enable, facilitating automation and real-time data analytics at the edge. Automotive and vehicle-to-everything (V2X) communications represent another critical vector, where safety and connectivity intersect to redefine transportation infrastructure. Fixed wireless access continues to play a role in bridging connectivity gaps, supported by chipsets designed for robust network performance.
Geographically, the market distribution highlights the concentration of manufacturing and deployment capabilities. Asia Pacific stands out as a significant hub, reflecting the region's dense manufacturing base and rapid technology adoption. North America and Europe also contribute substantial shares, driven by infrastructure investment and enterprise innovation. Emerging regions are beginning to integrate into this global supply chain, adding layers of complexity and opportunity for companies with international operational footprints.
The Competitive Arena: Leaders and Innovators
The competitive landscape of the 5G-Advanced chip market is characterized by a mix of established giants and specialized innovators, each pursuing distinct strategies to capture market share. Market concentration metrics indicate that a small number of players control a significant portion of the revenue, underscoring the high barriers to entry and the capital intensity of advanced semiconductor development. The top three players account for a dominant share, while the top five extend their influence further, shaping the standards and supply dynamics of the industry.
Qualcomm Technologies, Inc., based in San Diego, remains a pivotal force with its lineup of 5G-Advanced modem-RF systems. Their platforms, including the Snapdragon X85 and X80, support 3GPP Release 18 features across smartphones, fixed wireless access, automotive, and infrastructure segments. In March 2026, Qualcomm announced the Qualcomm X105 5G Modem-RF, described as the world's first 3GPP Release 19-ready modem. This launch integrates enhanced 5G-Advanced performance with AI capabilities, with sampling to customers underway and commercial devices anticipated in the second half of 2026. Such moves signal a continuous iteration cycle where leadership is maintained through rapid product evolution.
MediaTek Inc., headquartered in Hsinchu, Taiwan, offers a broad portfolio of 5G-Advanced solutions. Their M90 modem and T930 flagship platform for fixed wireless access and customer premises equipment support Release 18 standards. MediaTek has also emphasized MIMO enhancements, with 8Rx/3Tx configurations delivering significant spectrum efficiency gains. In March 2026, the company showcased the world's first 5G-Advanced CPE device with Wi-Fi 8 powered by the T930 chipset, highlighting improvements in uplink performance and AI-driven quality of service engines. Additionally, MediaTek introduced new 5G-Advanced telematics chipsets, expanding their reach into automotive applications.
Samsung Electronics Co., Ltd., in Suwon, South Korea, operates with a dual role in modem and smartphone integration. Their Exynos processors and 5G-Advanced chipsets leverage advances in GAA transistor technology and high-bandwidth memory to support high-performance wireless applications. This vertical integration allows Samsung to optimize performance across the device stack, a strategic advantage in the mobile and infrastructure sectors.
Broadcom Inc., located in San Jose, California, focuses on infrastructure-grade solutions. Their BroadPeak 5nm Massive MIMO SoC platform is designed for 5G-Advanced and 6G-ready infrastructure, incorporating RF and converter technology with FPGA interoperability for wideband radios. In February 2026, Broadcom completed interoperability testing of Agilex 7 FPGAs with the BroadPeak SoC platform at 32.44Gbps JESD204C, enabling scalable beamforming and AI-assisted signal processing. These collaborations highlight the importance of open architectures in scaling network capabilities.
Other notable players include GCT Semiconductor Holding Inc., which announced first commercial shipments of its 5G chipset in January 2026 for applications including air-to-ground networks, marking a milestone in niche deployment areas. Sequans Communications, based in Paris, is developing 5G NR eRedCap chipsets with platforms like Monarch 3 and Calliope 3, supporting the transition to 5G-Advanced IoT with low-energy designs. Huawei Technologies Co., Ltd., in Shenzhen, supplies 5G-Advanced chipsets and infrastructure solutions with demonstrated applications in robotics and healthcare. Intel Corporation, in Santa Clara, offers infrastructure-focused chipsets and network processors supporting edge computing and base station solutions. Together, these companies illustrate the breadth of innovation driving the market.
Industry Dynamics and Technological Catalysts
Beyond company actions, the market is shaped by broader industry dynamics including standardization, regulatory frameworks, and manufacturing infrastructure. The 3GPP Release 18 specifications define the core features of 5G-Advanced, introducing enhancements in advanced downlink and uplink MIMO, AI/ML data-driven designs, energy-efficient networks, evolved duplexing, RedCap evolution, and expanded positioning. These specifications form the technical backbone that chipsets must support, creating a standardized baseline for interoperability and performance.
The Global System for Mobile Communications Association (GSA) tracks the ecosystem's readiness, noting that as of May 2025, five modems supported 5G-Advanced features with 75 devices hardware-compatible with Release 18, primarily using Qualcomm Snapdragon platforms. Increased device launches are expected from late 2025 onward via Snapdragon X85 adoption, indicating a pipeline of products ready to absorb advanced chip capabilities.
Regulatory and investment environments also play a crucial role. The U.S. CHIPS Act has driven substantial semiconductor supply chain investments, including advanced packaging and GaN-on-SiC fabs for 5G/6G, radars, and satellite technologies. TSMC's Arizona facilities are producing advanced nodes such as 4nm, 3nm, and 2nm, supporting high-volume manufacturing of chips for 5G/6G smartphones and related applications. These infrastructure developments reduce supply bottlenecks and enable the production of the complex chips required for next-generation networks.
Worldwide 5G-Advanced Chip Market
Additionally, material science trends influence component selection. GaN RF chips account for over half of RF chips in telecom equipment and are projected to reach up to 90% market share due to requirements for high-frequency mmWave 5G-Advanced signal amplification. This shift impacts procurement strategies and supply chain planning for organizations involved in RF front-end design.
Strategic Imperatives for 2026 and Beyond
For enterprises operating in 2026, the insights contained in this report translate into actionable intelligence across several dimensions. Procurement teams must evaluate supplier capabilities against the backdrop of rapid product cycles and evolving standards. Understanding which chip types and architectures align with specific application requirements can optimize performance and cost. Supply chain managers need to assess the geographic distribution of manufacturing and the impact of government incentives on availability and lead times.
Product strategists should consider how 5G-Advanced features can be leveraged to differentiate offerings in competitive markets. The convergence of AI integration with modem technology, as seen in recent launches, opens new possibilities for intelligent connectivity and network optimization. Meanwhile, the growth in industrial IoT and automotive segments suggests opportunities for cross-industry collaboration and new business models.
Investors and analysts can use the market size projections and segmentation data to inform capital allocation and valuation models. The high CAGR and expanding revenue base indicate a sector with significant upside, but also one where competitive positioning and technological execution will determine long-term winners. The concentration of market share among top players suggests that partnerships, licensing, and ecosystem access may be as important as raw manufacturing capacity.
Risk management is another critical area. The reliance on specific standards, materials, and manufacturing nodes introduces vulnerabilities that must be mitigated through diversification and scenario planning. Regulatory changes and geopolitical factors can influence supply chain flows and market access, requiring continuous monitoring and adaptive strategies.
Accessing Comprehensive Intelligence
This overview provides a snapshot of the strategic landscape surrounding the Worldwide 5G-Advanced Chip Market. However, the full depth of analysis required for precise decision-making is contained within the complete report. Detailed segmentation data, historical trends, forecast models, and company profiles offer the granularity needed to validate hypotheses and build robust strategies.
PW Consulting's research is designed to serve as a foundational tool for executives, planners, and technical leaders who need to navigate the complexities of this high-growth market. The report integrates quantitative data with qualitative insights, covering the interplay of technology, competition, and regulation that defines the industry.
For organizations seeking to secure their position in the 5G-Advanced era, access to comprehensive market intelligence is not optional. We invite stakeholders to explore the full report for detailed figures, regional breakdowns, application-specific forecasts, and in-depth competitive analysis. Engaging with this intelligence now will ensure that your organization is prepared to capitalize on the opportunities of 2026 and beyond, with a clear view of where the market is heading and how to reach it.
Visit our research portal to access the complete Worldwide 5G-Advanced Chip Market report and equip your team with the insights needed to lead in this dynamic landscape.
For detailed analysis of this topic, please visit the official page: Worldwide 5G-Advanced Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com