

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Battery Software Market Hits $1,127.29M in 2025, Projected 18.24% CAGR to $3,642.24M by 2032

Navigating the Battery Manufacturing Software Boom: Strategic Imperatives for 2026 and Beyond
The global battery manufacturing software market is undergoing a transformation that mirrors the electrification of the automotive industry itself. No longer a back-office utility, manufacturing software has become the central nervous system of gigafactory operations, influencing everything from cell yield rates to regulatory compliance. According to our latest research, the worldwide market for battery manufacturing software is projected to expand from an estimated 1,127.29 million USD in 2025 to 3,642.24 million USD by 2032. This trajectory represents a compound annual growth rate of 18.24 percent over the forecast period.
Such figures are not merely indicators of market expansion. They signal a structural shift in how battery producers approach scalability, quality assurance, and operational intelligence. As capital intensity rises and regulatory scrutiny tightens, software platforms that once supported discrete manufacturing processes are being reimagined as integrated digital threads. For executives planning their 2026 investment roadmaps, understanding the architecture, competitive dynamics, and external pressures shaping this market is no longer optional. It is a prerequisite for sustainable growth.
Our comprehensive Worldwide Battery Manufacturing Software Market report is designed to provide the analytical rigor and actionable granularity required to navigate this inflection point. What follows is a strategic overview of the forces driving this market, the competitive landscape defining it, and the practical dimensions our study unpacks for industry leaders.
Market Trajectory and the Case for Strategic Investment
The historical trajectory of the battery manufacturing software market reflects the broader acceleration of electrification. Between 2020 and 2025, the market expanded consistently each year, growing from 510.45 million USD to the aforementioned 1,127.29 million USD. This doubling of market value over a five-year period underscores how quickly software has moved from a supplementary expenditure to a core operational necessity.
Looking ahead, the forecast period from 2026 through 2032 indicates that this momentum will not decelerate. The market is expected to surpass 1,367.57 million USD in 2026 and continue climbing steadily to 1,606.81 million USD in 2027, 1,875.33 million USD in 2028, 2,182.17 million USD in 2029, and 2,669.49 million USD in 2030. By the close of the forecast window in 2032, revenue is projected to reach 3,642.24 million USD. An 18.24 percent CAGR across this horizon suggests that software adoption will remain tightly coupled with production capacity expansion, technological maturation, and the evolving demands of downstream customers.
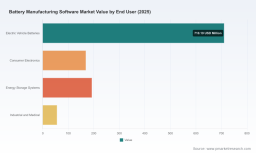
Importantly, these projections are not homogeneous across all solution types or end-user segments. The composition of market value reflects distinct adoption curves for manufacturing execution systems, simulation and design platforms, quality management tools, asset performance management suites, and data analytics and AI offerings. Similarly, the demand profile varies meaningfully across application domains such as electric vehicle batteries, consumer electronics, energy storage systems, and industrial and medical batteries. Our report dissects these structural nuances in detail, enabling decision-makers to align software procurement with their specific operational priorities rather than relying on aggregate market narratives.
External Pressures Redefining Software Requirements
Market growth is being accelerated by a confluence of regulatory, economic, and technical forces that are simultaneously raising the stakes for manufacturing software vendors and end-users. One of the most consequential developments is the emergence of the EU battery passport framework. By 2027, mandatory requirements for carbon footprint declaration and quality component disclosure will apply to large segments of the battery industry. This regulatory shift is not simply a compliance exercise. It is driving a fundamental need for enhanced traceability, data sovereignty, and interoperable data architectures within manufacturing software environments.
Parallel to regulatory evolution, cost structures in battery production are creating new incentives for digitalization. In a baseline 40 GWh per annum lithium-ion battery cell production plant, labor accounts for approximately 6.9 percent of total costs. Research indicates that digitalization solutions encompassing predictive quality, automated traceability, and workflow optimization can reduce required staffing and overall production costs by up to 0.8 percent per use case. While these percentages may appear incremental in isolation, their cumulative impact across multiple production lines and operational domains can materially improve margins in an industry where cost-per-kWh remains a central competitive battleground.
Energy efficiency represents another critical lever. Energy tracking and optimization use cases in battery manufacturing digitalization hold the potential for a 9.5 percent reduction in energy consumption. The electrode production stage, in particular, stands to benefit most from integrated scrap reduction and energy efficiency initiatives. As energy prices remain volatile and sustainability commitments tighten, software platforms capable of delivering granular energy visibility and actionable optimization insights are gaining strategic prominence.
Cybersecurity is equally reshaping vendor selection criteria. Standards such as ISO 21434 and IEC 62443 are increasingly referenced in battery-related systems procurement. Recommendations for end-to-end encryption, including AES-256 and TLS 1.3, alongside secure update mechanisms in connected manufacturing environments, are becoming baseline expectations rather than premium differentiators. In this context, software platforms must demonstrate not only operational functionality but also resilient security architectures that align with evolving compliance mandates.
Geopolitical dynamics add further complexity. US domestic battery manufacturing output grew 359 percent in inflation-adjusted terms from 2020 to 2024, supported by policy actions encouraging onshoring of supply chain elements. This surge amplifies the importance of software integration for traceability, quality assurance, and regulatory reporting, particularly for manufacturers seeking to align with domestic content requirements and localized production incentives.
Competitive Landscape: Differentiated Platforms and Strategic Positioning
The competitive landscape in battery manufacturing software is characterized by a mix of established industrial automation players, specialized software vendors, and emerging analytics-focused firms. Market concentration data indicates that the top three players account for 34.2 percent of the market, while the top five represent 48.15 percent. This distribution reflects a market that is substantial enough to attract broad participation yet fragmented enough to allow differentiated value propositions to thrive.
GE Vernova continues to leverage its Proficy Smart Factory MES software to support diverse battery production processes within a single manufacturing platform. Its offering emphasizes end-to-end production visibility, quality control, traceability, and scalability for gigafactories while aiming to reduce operational technology costs and maintenance burdens. Siemens, meanwhile, integrates battery manufacturing execution systems, quality management systems, and process planning tools into its broader digital thread and smart manufacturing portfolio. Its approach is oriented toward standardization and optimization across battery production workflows.
Rockwell Automation delivers end-to-end MES solutions tailored specifically for EV lithium-ion battery producers. Its focus on integrated automation and manufacturing execution positions it as a relevant partner for organizations prioritizing tightly coupled control and execution architectures. Honeywell has made notable moves in this space, including its June 2024 launch of the Battery Manufacturing Excellence Platform, an AI-powered solution designed to optimize gigafactory operations, improve battery cell yields, reduce material waste, and compress production ramp-up cycles. Public disclosures around this launch highlighted a potential 60 percent reduction in startup material scrap, underscoring the growing emphasis on AI-driven process optimization.
Voltaiq offers an enterprise battery intelligence software platform that extends data analytics and insights from research and development through to giga-scale production. Its value proposition centers on helping manufacturers detect and correct battery issues using existing data streams, thereby improving quality, safety, and efficiency. Energsoft serves a different segment by providing subscription-based predictive battery analytics software aimed at medium-sized companies. Its model focuses on automating data export, storage, and analysis to boost manufacturing yield and streamline workflows in battery production environments.
camLine, operating under the Elisa IndustrIQ umbrella, supplies MES, manufacturing operations management, and AI-powered solutions with a specific emphasis on efficiency, quality control, and end-to-end traceability for battery manufacturing processes. ABB contributes through its Manufacturing Operations Management software, which integrates secure data services, predictive analytics, and collaboration capabilities to deliver end-to-end visibility, including dedicated support for smart production in battery manufacturing. Panasonic Connect expanded the competitive field with its October 2024 launch of Syncora, an end-to-end manufacturing execution system designed to accelerate the digital transformation of EV battery manufacturing. Finally, PDF Solutions provides Exensio Battery, a modular solution set that addresses critical challenges in battery manufacturing through advanced analytics applicable to both semiconductor and battery processes.
Together, these players illustrate the breadth of approaches available to manufacturers. The strategic question is not simply which vendor offers the most features, but which platform architecture best aligns with a company's production scale, data maturity, regional compliance requirements, and integration constraints. Our report evaluates these competitive dynamics with a structured lens, allowing readers to assess fit beyond marketing narratives.
What the Report Covers: Operational Intelligence for Decision-Makers
The Worldwide Battery Manufacturing Software Market study is structured to serve as both a strategic compass and a practical reference for procurement, operations, and technology leadership. Rather than relying on surface-level aggregations, the report provides a detailed exploration of market architecture, adoption patterns, and the operational contexts in which software solutions deliver measurable value.
The analysis begins with a rigorous framing of market size and growth trajectories, contextualized across historical performance and forward-looking projections. It then examines segmentation structures that matter for enterprise planning, including solution type categories and end-user applications. By isolating the distinct demand drivers behind manufacturing execution systems, simulation and design software, quality management systems, asset performance management, and data analytics and AI platforms, the report helps readers understand where investment is concentrating and why.
Worldwide Battery Manufacturing Software Market
A substantial portion of the study is dedicated to competitive profiling. Each of the key companies is assessed for its product strategy, integration approach, target customer profile, and recent market moves. This includes not only incumbents with broad industrial automation portfolios but also specialized vendors whose solutions address niche but increasingly important requirements such as predictive analytics, battery intelligence, and modular process optimization. Recent product launches and strategic announcements are contextualized within broader market trends, enabling readers to distinguish between incremental updates and genuinely transformative offerings.
The report also integrates an assessment of external market dynamics, including regulatory developments, cost structure considerations, energy optimization potential, cybersecurity expectations, and regional manufacturing policy shifts. These factors are examined not as isolated observations but as interconnected forces that shape software selection criteria, implementation timelines, and total cost of ownership. By mapping these dynamics to practical procurement and deployment considerations, the study equips leaders to anticipate compliance requirements, align software capabilities with operational KPIs, and build internal business cases that withstand executive and board-level scrutiny.
Importantly, the report avoids treating the market as a monolith. Where relevant, it highlights the structural differences that emerge across regions, solution types, and end-user applications without overemphasizing any single segment in isolation. This balanced approach ensures that readers can extract insights applicable to a range of strategic scenarios, whether they are scaling gigafactory operations, optimizing existing production lines, or evaluating entry into new battery market segments.
Strategic Recommendations for 2026 Planning
As organizations move into 2026, several strategic priorities should guide battery manufacturing software decisions. First, traceability and data sovereignty must be treated as foundational requirements rather than afterthoughts. With regulatory frameworks such as the EU battery passport approaching, manufacturers should evaluate whether their software platforms can support the granularity, auditability, and data governance necessary for compliance. Solutions that lack robust traceability frameworks may require costly retrofits or integration work later.
Second, AI-enabled optimization should be assessed against measurable operational outcomes. The market is seeing a growing number of platforms that promise yield improvement, scrap reduction, and faster ramp-up cycles. However, the value of these capabilities depends on data quality, integration depth, and change management. Procurement teams should seek evidence of performance in comparable production environments and establish clear baseline metrics before committing to large-scale deployments.
Third, cybersecurity and secure data exchange must be embedded into vendor evaluation criteria from the outset. As manufacturing environments become more connected, the attack surface expands. Software platforms that support recognized security standards and provide secure update mechanisms, encryption, and access controls will reduce long-term risk and simplify compliance reporting.
Fourth, total cost of ownership should be evaluated across labor, energy, and material efficiency dimensions. The potential for digitalization to reduce staffing requirements, lower energy consumption, and minimize scrap represents a multi-dimensional value proposition. Organizations that model these benefits holistically are better positioned to justify investments and prioritize use cases with the highest return potential.
Finally, alignment with regional manufacturing incentives and supply chain strategies is essential. In markets where domestic production is being actively supported through policy mechanisms, software platforms that facilitate traceability, compliance reporting, and integration with localized production workflows can provide strategic advantages beyond their operational functionality.
Accessing the Full Intelligence
The battery manufacturing software market is expanding at a pace that rewards organizations capable of making informed, timely decisions. The aggregate growth trajectory is compelling, but the real strategic value lies in understanding the segmentation dynamics, competitive differentiators, regulatory pressures, and operational use cases that will determine success in specific deployment contexts.
Our Worldwide Battery Manufacturing Software Market report provides the depth, structure, and analytical discipline required to navigate this complexity. It is intended for leaders who need more than headline figures. It offers a comprehensive view of how the market is evolving, who is shaping it, and what practical considerations should inform software strategy in 2026 and beyond.
Battery Design And Manufacturing Software Market
For detailed segmentation breakdowns, competitive assessments, regional analyses, and the full set of market projections, we invite you to explore the complete report. The full intelligence is available through our official research portal, where you can access the complete dataset, methodology documentation, and supporting exhibit materials designed to support executive planning, procurement strategy, and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Battery Manufacturing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com