

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Orchard Sprayer Market Hits $631M in 2025, Projects $1B by 2032 at 6.8% CAGR

Navigating the Green Shift: Strategic Intelligence for the Worldwide Electrical Orchard Sprayer Market (2026–2032)
The agricultural machinery sector is currently undergoing a profound transformation, driven by the dual imperatives of labor scarcity and environmental sustainability. Within this landscape, the Worldwide Electrical Orchard Sprayer Market stands out as a critical frontier for innovation and capital allocation. As we move into 2026, the transition from traditional diesel-powered equipment to electric and autonomous solutions is no longer a conceptual trend but a measurable shift in procurement strategies across major growing regions. For stakeholders in agribusiness, equipment manufacturing, and investment, understanding the trajectory of this market is essential for long-term resilience and growth.
Our latest comprehensive study, spanning historical analysis from 2020 through base year 2025 and forecasting out to 2032, provides a rigorous examination of this sector. This article serves as a strategic overview, highlighting the macro-economic forces, technological disruptions, and competitive dynamics that define the landscape. While specific quantitative breakdowns are reserved for the full detailed report, the trajectory indicates a robust expansion phase underpinned by technological maturity and regulatory pressure.
Market Trajectory and Growth Dynamics
The global market for electrical orchard sprayers has demonstrated consistent resilience and upward momentum over the past half-decade. Reflecting on the historical period from 2020 to 2025, the industry navigated supply chain challenges while accelerating adoption rates in premium crop segments. The market valuation witnessed a significant climb, moving from approximately $452.18 million in 2020 to an estimated $631.24 million by the base year 2025. This historical performance sets a solid foundation for the forecast period extending from 2026 to 2032.
Projecting forward, the market is poised to breach significant psychological and financial thresholds. Forecasts suggest a steady compound annual growth rate (CAGR) of 6.8%, indicating sustained demand rather than a temporary spike. By 2032, the market revenue is anticipated to approach the $1 billion million mark, reflecting the deep integration of electric technologies into standard orchard management practices. This growth is not merely a function of unit sales but represents a fundamental shift in how orchard operations are engineered, focusing on precision, autonomy, and emission reduction.
Several macro drivers are converging to support this trajectory. First, the global push toward decarbonization in agriculture is prompting governments and large-scale growers to prioritize electric machinery to meet sustainability certifications. Second, the diminishing availability of skilled labor in key horticultural regions is accelerating the adoption of autonomous spraying solutions that can operate with minimal human intervention. Third, the long-term operational cost benefits of electric systems, despite higher upfront capital expenditure, are becoming increasingly attractive as energy prices stabilize and battery technology improves.
Technological Architecture and Product Segmentation
The market is primarily bifurcated by power source and operational technology, each offering distinct value propositions to the end user. The dominant segment currently relies on battery-powered systems, which have benefited from advancements in lithium-ion energy density and cycle life. These systems offer the advantage of zero local emissions and reduced noise pollution, critical for orchards located near residential zones or sensitive ecosystems. Concurrently, a growing niche exists for hybrid electric solutions, which combine the endurance of internal combustion engines with the precision and low-emission benefits of electric drive systems, catering to operations where charging infrastructure remains limited.
Beyond power sources, the functional differentiation lies in the automation level. The industry is moving from simple electric propulsion to integrated autonomous systems. Modern electric sprayers are increasingly equipped with AI-driven weed detection, GPS/LiDAR navigation, and remote monitoring capabilities. This shift transforms the sprayer from a passive tool into an active data collection node within the farm's digital ecosystem. The ability to perform spot-spraying based on real-time weed detection significantly reduces chemical usage, which aligns with both cost-saving objectives and stringent environmental regulations regarding pesticide runoff.
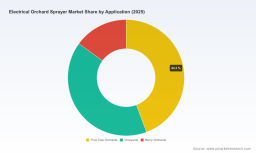
Application areas remain concentrated in high-value specialty crops. Fruit tree orchards and vineyards represent the core demand drivers due to the high economic value of the produce and the necessity for precise chemical application to protect yield quality. Berry orchards also contribute to demand, though at a different scale, often driven by specific disease control requirements that benefit from low-volume, high-precision electric application methods. The versatility of electric platforms allows manufacturers to tailor solutions across these verticals, creating a diversified product portfolio that mitigates sector-specific risks.
Competitive Landscape and Strategic Consolidation
The competitive environment in the electrical orchard sprayer market is characterized by a mix of established agricultural machinery giants and specialized innovators. Market concentration metrics indicate a moderately fragmented landscape, though consolidation activity is intensifying. The top three players hold approximately 32.4% of the market share, while the top five account for roughly 48.75%. This structure suggests that while niche players can thrive through specialization, scale advantages are becoming increasingly important for global distribution and service support.
John Deere, particularly through its integration with GUSS Automation, represents a significant force in this space. The strategic acquisition completed in August 2025 marks a pivotal moment, integrating autonomous electric herbicide sprayer technology directly into one of the world's largest machinery portfolios. Their Electric GUSS unit, featuring Kreisel batteries for full-shift operation and AI weed detection, exemplifies the industry's direction toward autonomy and material efficiency. This move signals a broader strategy to capture value not just in hardware sales but in precision agriculture software and service ecosystems.
In Europe, companies like Nobili S.p.A. in Italy and MDE Machinebouw bv in the Netherlands are focusing on specialized electric architectures. Nobili's approach with dual electric motors for pumps and fan groups targets zero-emission operations in specialty crops, appealing to European markets with strict environmental compliance. MDE focuses on mounted pneumatic electric sprayers with varied capacities, catering to precision requirements in fruit tree applications. Similarly, TRS Sprayers & Equipment in New Zealand is pushing the envelope with the EON1 model, designed to pair with electric tractors for full orchard electrification, highlighting a systems-level approach to orchard energy management.
Worldwide Electrical Orchard Sprayer Market
Hol Spraying Systems (HSS) complements this landscape with towed orchard sprayers that blend hydraulic and electric features, offering flexibility for low-volume or precision spraying needs. More recently, updates from players like KUHN in April 2025 regarding revised tank sizes and simplified operation features indicate that even broader machinery manufacturers are refining their offerings to match the precision and usability demands of electric-compatible workflows. These developments underscore a competitive race to balance battery endurance, spray precision, and operator ease of use.
Operational Context and Regulatory Influences
Adoption of these technologies is heavily influenced by the regulatory and operational context in which they are deployed. Safety standards are becoming more rigorous, particularly concerning autonomous operation in environments where workers and machinery coexist. Advanced systems now incorporate safety protocols that automatically pause spraying when individuals are detected in proximity, aligning with operator safety and precision application standards. This feature is becoming a baseline expectation rather than a premium differentiator in mature markets.
Material availability and energy storage technology also play critical roles. The performance of electric autonomous orchard sprayers is contingent on battery technology advancements. For instance, certain high-capacity battery packs enable continuous operation for extended shifts, which is crucial for large-scale commercial orchards where downtime equates to significant revenue loss. The integration of such energy systems directly impacts the total cost of ownership calculations that growers perform when switching from diesel to electric fleets.
Furthermore, the ability of electric sprayers to support reductions in chemical usage through spot-spraying technologies is a powerful value proposition. Depending on weed pressure, these technologies can achieve substantial material savings, which resonates with both economic goals and sustainability mandates. This dual benefit is accelerating the payback period for electric equipment investments, making them more viable for mid-sized operations that previously found the capital cost prohibitive.
Strategic Implications for 2026 Decision-Makers
For executives and strategists navigating the 2026 landscape, the implications of this market evolution are multifaceted. Procurement strategies must now account for total lifecycle costs, including energy infrastructure requirements at orchard sites. Investing in electric sprayers often necessitates parallel investments in charging stations and grid capacity, which must be factored into capital planning. Companies that delay this transition risk higher operational costs and potential regulatory non-compliance as regions tighten emission standards for agricultural machinery.
From a product development perspective, the convergence of autonomy and electrification suggests that future competitive advantage will lie in software integration and data analytics, not just hardware durability. Manufacturers and service providers need to focus on building ecosystems that allow seamless monitoring and management of multiple units. The ability to remotely monitor operational status and chemical usage data is becoming a key requirement for enterprise-level orchard managers who operate across multiple locations.
Self-Propelled Sprayer Market
Investment capital should also be aware of the regional variations in adoption speeds. While specific market share percentages vary by geography, mature markets with high labor costs and stringent environmental rules are likely to lead in adoption rates. Emerging markets may follow a different trajectory, potentially leveraging hybrid solutions as a bridge technology before fully committing to battery-electric infrastructure. Understanding these nuances requires detailed regional intelligence that goes beyond global aggregates.
Supply chain resilience is another critical consideration. The reliance on specific battery technologies and electronic components introduces new dependency risks distinct from traditional mechanical supply chains. Diversifying suppliers and securing long-term contracts for critical energy components will be essential for manufacturers aiming to maintain production stability during the growth phase projected through 2032.
Conclusion: Accessing Deep-Dive Intelligence
The Worldwide Electrical Orchard Sprayer Market is at an inflection point where technology, regulation, and economics align to drive sustained growth. The data suggests a clear path toward a $1 billion market valuation by the early 2030s, supported by a healthy CAGR and widespread technological adoption. However, capturing value in this environment requires more than just recognizing the trend; it demands granular insight into segmentation, competitive moves, and regional dynamics.
While this overview highlights the strategic contours of the market, the full depth of our research offers the specific data points necessary for precise modeling and decision-making. Our complete report details the exact revenue splits across types and applications, regional performance metrics, and detailed profiles of every key player mentioned herein and their recent strategic developments. For stakeholders ready to commit to data-driven strategies in 2026, accessing this comprehensive intelligence is the next logical step.
To explore the full segmentation analysis, including detailed breakdowns by region, type, and application, as well as the complete competitive landscape and regulatory forecasts, we invite you to review the full Worldwide Electrical Orchard Sprayer Market research report. Equip your organization with the precise intelligence needed to navigate the electric shift in orchard management.
For detailed analysis of this topic, please visit the official page: Worldwide Electrical Orchard Sprayer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com