

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide IT Market Hits $5.7B in 2025, Projected to Reach $9.93B by 2032 at 8.25% CAGR

Strategic Intelligence for the Next Wave: Navigating the Worldwide Information Technology Market in 2026
The global information technology landscape is undergoing a structural transformation that demands more than incremental budgeting or reactive procurement. As organizations move deeper into an AI-augmented, hyperconnected operating environment, the capacity to distinguish durable growth from temporary hype has become a critical strategic competency. PW Consulting’s latest Worldwide Information Technology Market research study provides that distinguishing lens, synthesizing historical performance, forward-looking projections, and competitive intelligence into a single decision-ready framework. For leaders planning capital allocation, capability building, and market positioning throughout 2026 and beyond, this research offers the operational clarity required to act with precision rather than speculation.
The study opens with a clear macroeconomic baseline: the worldwide IT market has expanded from an estimated 3.92 trillion USD in 2020 to approximately 5.70 trillion USD in 2025, reflecting sustained enterprise digitization, cloud migration, and the emergence of generative AI as a core operational driver. Looking ahead, the forecast period through 2032 projects continued expansion at a measured compound annual growth rate of 8.25 percent, with the market trajectory climbing toward nearly 10 trillion USD by the final projection year. These figures are not abstract indicators; they frame the scale of investment, capability development, and competitive positioning that enterprise leaders must now plan for. The revenue is tracked in USD millions, providing consistent comparability across time horizons, and the growth profile suggests that IT spending will remain a central pillar of corporate strategy rather than a discretionary cost center.
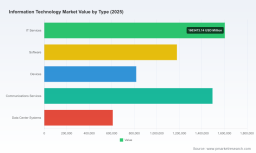
Before executives attempt to translate these top-line trajectories into portfolio decisions, it is essential to understand where momentum is concentrated and how it is flowing through the ecosystem. The research deliberately segments the market across type, application, and geographic dimensions, allowing decision-makers to see how capital and demand are distributed across the value chain without overwhelming them with raw spreadsheets. Rather than treating the IT market as a monolith, the analysis reveals the underlying balance between IT services, software, devices, communications services, and data center systems, each carrying distinct margin profiles, adoption cycles, and competitive dynamics. The same logic applies to end-use verticals, where enterprise deployments, consumer adoption, government and public sector programs, and small and medium business digitization present different buying behaviors, procurement cycles, and resilience factors.
This segmentation foundation matters because 2026 is shaping up as a year of divergence. Recent industry signals indicate that spending on servers, storage, and network equipment is accelerating sharply as service providers expand data center infrastructure to accommodate AI workloads and cloud-native architectures. At the same time, semiconductor revenue is projected to climb to levels not seen in decades, with memory markets experiencing particularly pronounced expansion. These shifts are not isolated technical trends; they represent structural changes in how IT capacity is built, where value is captured, and which vendors are positioned to influence enterprise buying behavior. In parallel, trade exhibitions and analyst forecasts have emphasized robotics enabled by physical AI, digital health innovation, and advanced mobility as reinforcing themes within the broader IT ecosystem, while strategic trends for the year increasingly center on domain-specific language models and AI-powered connectivity across business functions.
Equally important, macro and regulatory conditions are reshaping the operating environment. Tariff policies and geopolitical tensions continue to introduce supply chain uncertainty for IT hardware and semiconductor components, prompting organizations to invest in resilient sourcing strategies and cloud-based visibility tools. AI-driven investment across telecom, fiber, and data centers is also accelerating infrastructure development, making the TMT sector’s physical and digital layers more interdependent than ever. In that context, the strategic question for senior leaders is no longer whether IT will remain a growth engine, but how to allocate resources in a market where innovation cycles, regulatory exposure, and supply-side volatility intersect.
What the Research Delivers: Operational Content for 2026 Decision-Making
PW Consulting’s Worldwide Information Technology Market study is designed to move directly from market structure to actionable planning. The report assembles a comprehensive historical record spanning 2020 through the base year of 2025, then extends forward across a multi-year forecast period through 2032. This dual lens allows organizations to test strategic assumptions against both proven performance patterns and expected transitions in demand. Historical data illuminates how the market absorbed shocks, scaled cloud and services growth, and rebalanced around shifting enterprise priorities. The forecast component, meanwhile, translates those patterns into forward indicators that support budget planning, capacity modeling, and investment prioritization.
Segmentation Analysis That Supports Portfolio Strategy
One of the most valuable components of the research is its segmentation architecture. By disaggregating the market into type, application, and regional dimensions, the study enables leaders to examine how growth is distributed across the IT ecosystem rather than relying on a single aggregate figure. This approach supports more precise questions: Where is incremental spending likely to appear? Which segments are expanding on the back of structural infrastructure demand, and which are being reshaped by software-led transformation or services migration? How does demand differ between large enterprise buyers and smaller commercial entities? Because the report maintains a consistent unit framework in USD millions throughout, readers can compare relative scale without losing sight of absolute investment levels.
The analysis is intentionally built to support segmentation-informed strategy. For technology vendors, this means clearer insight into which product and service categories are most relevant to near-term growth narratives. For enterprise buyers, it means better visibility into where cost, speed, and capability trade-offs are likely to emerge. For investors and advisors, it means a more defensible basis for assessing which parts of the market are consolidating around durable demand and which are subject to faster disruption or substitution.
Competitive Intelligence Grounded in Company Profiles
A market of this size is shaped not only by end-user demand but also by the strategies of a concentrated set of leading firms. The report integrates detailed profiles of core participants across the IT ecosystem, capturing their headquarters, primary capabilities, and strategic positioning. These include organizations spanning cloud platforms, productivity suites, AI tooling, operating systems, semiconductor and data center infrastructure, enterprise databases, business applications, hybrid cloud, IT services, digital transformation consulting, and application development. Each profile is structured to help readers understand not just what a company offers today, but how it is positioned relative to the demand shifts that the forecast anticipates.
Worldwide Information Technology Market
The competitive picture is especially relevant given the market’s concentration profile. The top three firms account for roughly 14.82 percent of overall market share, while the top five firms account for approximately 21.35 percent. That level of concentration does not imply a static landscape; rather, it signals where competitive pressure, ecosystem influence, and partnership leverage are likely to concentrate in 2026. Companies outside the top tier still play essential roles in implementation, services delivery, and regional execution, but large platform players continue to shape pricing expectations, integration norms, and enterprise adoption patterns across cloud, software, and AI-enabled services.
To complement these corporate profiles, the study integrates recent developments that illustrate how market participants are reacting to structural change. Industry output from late 2025 and early 2026 highlights a strong spending environment, with worldwide IT investment projected to grow significantly in 2025 and maintain positive momentum into 2026, driven by AI infrastructure, cloud services, and device refresh cycles. Simultaneously, semiconductor revenue forecasts point to one of the strongest growth intervals in recent history, reinforcing the importance of hardware and data center capacity in the broader IT economy. Analyst commentary and industry events further underscore domain-specific AI, robotics, digital health, and advanced mobility as themes that are becoming embedded in mainstream IT planning rather than remaining peripheral innovation stories.
Why This Research Matters for 2026 Strategy
For executives and strategy teams, the value of this research lies in its ability to connect market scale with operational decision-making. The data does more than confirm that IT continues to grow; it defines the magnitude of that growth, the timeframe over which it is expected to unfold, and the degree of concentration within the competitive field. That combination helps organizations answer a set of core strategic questions: How much capacity should we plan for? Which demand pools should we prioritize? Where do we face the greatest exposure to supply chain or tariff-related disruption? How should we position ourselves relative to dominant platforms and service providers?
The practical applications are broad. A CIO planning a multi-year technology roadmap can use the macro trajectory and segmentation structure to validate investment phasing and align procurement with anticipated demand shifts. A product leader can use the type-based segmentation to identify where service, software, or infrastructure demand is likely to be strongest, and adjust roadmap focus accordingly. A corporate development team can use the competitive profiles and concentration data to assess partnership, acquisition, and ecosystem entry opportunities with a realistic sense of market power distribution. A risk and operations leader can use the latest industry dynamics to anticipate supplier-side volatility and adjust sourcing, inventory, or cloud dependency strategies.
Because the report is built around both history and forecast, it also supports scenario planning. Decision-makers can examine how sensitive their plans are to different adoption speeds, how exposure to specific segments may shift over time, and where the difference between headline growth and segment-level realities is most pronounced. That capacity is especially important in a market where AI infrastructure, data center expansion, and advanced connectivity are reshaping spending priorities faster than traditional budgeting cycles can accommodate.
How the Study Turns Market Complexity into Executive Clarity
PW Consulting’s approach emphasizes clarity without oversimplification. The study preserves the granularity needed for serious planning while organizing the information so that leadership teams can move quickly from market context to internal implications. Historical revenue trends demonstrate how the market has scaled over the last several years; the forward forecast establishes a structured view of expected momentum through the end of the decade and into the early 2030s; segmentation data allows readers to separate broad growth from segment-specific dynamics; and competitive profiles translate market structure into strategic awareness.
This is not a static market description. It is a working base for strategic action in 2026, when IT spending behavior is being reshaped by AI-led infrastructure demand, cloud expansion, hardware refresh cycles, and a more uncertain geopolitical and supply chain environment. Leaders who rely on aggregate narratives alone risk misjudging where growth is concentrated, where costs will move, and where competitive advantage can be built. The research is designed to reduce that risk by providing a structured, evidence-based view of the market as it is today and as it is expected to evolve.
IT Services Market
The full depth of this analysis is available in the complete Worldwide Information Technology Market report, where the underlying segment detail, regional context, company intelligence, and forecast logic are presented in full. For organizations that need to move from high-level awareness to committed investment decisions, the complete study offers the granular intelligence necessary to align strategy with market reality and to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Information Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com