

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Global Mine Shaft Elevator Market Hits $1.05B in 2025, Booms to $1.50B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Mine Shaft Elevator Market
The global mining industry stands at a critical inflection point where operational safety, capital efficiency, and technological modernization converge. For executives making capital allocation and procurement decisions in 2026, understanding the trajectory of vertical transport systems underground is no longer optional. It is a strategic imperative. Our latest Worldwide Mine Shaft Elevator Market research consolidates hard data, competitive dynamics, and regulatory shifts into a single decision-making framework. This introduction outlines the strategic value embedded in the full report, demonstrating how the analysis connects macroeconomic trajectories with actionable intelligence for boardrooms, engineering directors, and procurement leaders.
The central thesis of this study is straightforward: the market for mine shaft elevators and hoisting systems is expanding steadily while undergoing simultaneous transformation in technology, regulation, and competitive intensity. Companies that treat these systems as mere infrastructure purchases risk underinvesting in reliability and compliance. Those that integrate long-range market intelligence into their planning will secure better vendor partnerships, anticipate regulatory costs, and align capital projects with the most resilient technology segments.
Macro Market Signals and What They Mean for 2026 Planning
The firm foundation of this research is a rigorous historical reconstruction and forward-looking forecast. Drawing on a consolidated base year of 2025 and a historical window spanning 2020 through 2025, the study projects growth through 2032. The global market reached approximately USD 1,049.82 million in 2025, reflecting a recovery from an anomalous dip observed in 2024, when revenue briefly contracted to USD 963.1 million after peaking near USD 970.36 million in 2023. The overall compound annual growth rate across the forecast horizon rests at 5.25 percent, signaling a dependable expansion path rather than a speculative boom. By 2026, the market is projected to climb to roughly USD 1,142.69 million, and sustained growth is expected to carry the figure toward USD 1,502.0 million by 2032.
This growth trajectory is not merely a number on a spreadsheet. It reflects a structural reordering of mining logistics: deeper shafts, increased reliance on continuous and automated extraction, and a backlog of modernization projects that had been deferred during periods of commodity price volatility. For 2026 decision-makers, the message is clear. The demand floor is rising, and procurement windows are compressing. Equipment lead times, integration complexity, and lifecycle costs must be evaluated within a market that is scaling predictably rather than experiencing erratic spikes.
Equally important is market concentration. The analysis indicates that the top three competitors control approximately 42.5 percent of market revenue, while the top five account for roughly 61.2 percent. This concentration suggests that a handful of established providers hold meaningful leverage in pricing, technology roadmaps, and service contract structures. Yet it also implies that niche players and regional specialists retain viable openings, particularly in specialized shaft geometries, localized service ecosystems, and project-based delivery models. The full report dissects this competitive balance without reducing it to oversimplified rankings, enabling leaders to gauge where consolidation pressure is strongest and where differentiation remains achievable.
Competitive Landscape: Who Shapes the Market and How
Any strategic assessment of this market must grapple with the fact that a limited group of globally capable firms dominates the high-value segments of hoist design, engineering, and lifecycle service. Our report profiles the companies that are actively shaping standards, delivery methods, and technology transitions. Rather than presenting generic corporate descriptions, the study maps each player against the specific capabilities that matter in mine shaft applications: shaft geometry constraints, carrying capacity requirements, automation readiness, safety compliance, and service responsiveness across remote operational sites.
ABB remains a central reference point for hoist system integration. With more than a century of experience and over 1,000 installations worldwide, the company provides complete hoist solutions covering mechanical and electrical components as well as shaft equipment. Its positioning is especially relevant for organizations seeking integrated systems rather than component-level procurement. In late 2024, ABB formalized a collaboration with EcoHoist to build a scale demonstrator of vertical bucket elevator technology for mine shafts. The initiative targets reductions in capital cost and construction time, signaling a broader industry appetite for modular and potentially lower-cost vertical transport architectures. For 2026 strategists, this matters because it hints at future procurement pathways that could alter total cost models for new shafts and major refurbishments.
Worldwide Mine Shaft Elevator Market
SIEMAG TECBERG continues to function as a core supplier of shaft hoisting systems and associated equipment, delivering full mechanical and electrical solutions for production and service hoists. Its recent delivery footprint reinforces the point that large-scale international projects remain a primary demand driver. In May 2025, the company executed a cold start-up for the supply of five shaft hoisting systems serving two mines operated by India-based MOIL Limited. This kind of multi-system delivery underscores how project pipelines in key mining territories sustain revenue stability even as individual commodity cycles fluctuate. The full report situates such developments within regional demand patterns and project financing environments, allowing readers to distinguish between one-off wins and evidence of durable market engagement.
Alimak Group operates from a slightly different vantage, specializing in rack-and-pinion industrial elevators and construction hoists tailored to mining environments. Its portfolio spans permanent and temporary vertical access solutions used in mine shafts, smelters, processing plants, and underground operations. For organizations managing hybrid access requirements or prioritizing flexibility in shaft design, Alimak's capabilities represent a distinct value proposition relative to conventional drum or friction hoist suppliers.
Century Elevators addresses a practical constraint that many operators face: narrow shaftways. The company distributes and provides permanent mining elevators with controls and drives optimized for mine safety regulations and high-speed vertical transport in constrained geometries. In markets where shaft dimensions are dictated by legacy infrastructure or geological limitations, the ability to fit efficient transport systems into narrow openings becomes a decisive operational advantage.
KONE Corporation brings a complementary angle through customizable elevator solutions with energy-efficient designs suitable for underground mining environments, backed by extensive testing capabilities in deep mine shafts. While often associated with civilian vertical transport, KONE's underground-oriented engineering and testing infrastructure give it credibility in settings where reliability and energy performance intersect.
These profiles are not presented as isolated snapshots. The report examines how such companies compete on integration depth, service coverage, innovation timelines, and project execution. It also maps recent developments against long-term strategic positioning so that readers can evaluate whether observed collaborations, deliveries, or product demonstrations indicate incremental improvement or genuine portfolio shifts.
Segment Dynamics Without Over-Simplification
One of the deliberate strengths of this study is that it avoids the temptation to reduce a complex market to a small number of simplistic percentage splits. Instead, the report organizes segment analysis around engineering and operational logic. Hoist types differ not just in name but in mechanical behavior, maintenance profiles, and suitability for specific shaft configurations and load requirements. Friction-based systems, drum hoists, and multi-rope configurations each present distinct tradeoffs in terms of installation complexity, rope and brake management, speed envelopes, and service life. The report connects these technical distinctions to procurement considerations, so buyers can compare options based on total cost of ownership rather than sticker price alone.
Application context matters just as much. Metal mining operations, coal mining, and non-metal or industrial mineral extraction place different demands on vertical transport. The report analyzes how shaft depth, payload profiles, 교대 frequency, and regulatory exposure vary across these application domains and how those differences influence system selection, redundancy planning, and inspection regimes. Importantly, it ties those application dynamics to component-level realities. Steel wire ropes, for example, remain core components in mine shaft hoisting systems and are subject to regular nondestructive testing and visual examinations to monitor diameter loss, broken wires, and strength reduction. This is not a peripheral maintenance detail; it is a safety-critical input that affects inspection scheduling, rope replacement planning, and downtime forecasting. The report integrates such component realities into segment discussion so that planning is grounded in operational substance.
Regulatory and Safety Dynamics as Strategic Variables
Regulatory frameworks are not background noise in this market; they are decisive forces shaping procurement specifications, inspection cycles, service contracts, and retrofit timelines. In the United States, MSHA provides Mine Hoist and Elevator Inspection Program Training that covers inspection of mine hoist and elevators, the impact of the mine environment on components, and mechanical escape facilities. This type of training framework signals how seriously regulators treat the operational and human factors of vertical transport. It also implies that vendors and operators alike must maintain competency in inspection methodology, not merely equipment installation.
The regulatory environment is also tightening in specific technical areas. U.S. regulations require that hoists used to transport persons be equipped with overspeed, overwind, and automatic stop controls, along with brakes capable of stopping the fully loaded device. These requirements translate directly into design specifications and verification burdens for manufacturers and integrators. In December 2024, MSHA finalized updates to safety standards for electric motor-driven mine equipment, incorporating ANSI voluntary consensus standards that became effective in January 2025. For 2026 planning, this is especially relevant because compliance expectations can shift procurement lead times and influence whether a project chooses new equipment, retrofitted systems, or refurbished assets with updated control architectures.
The full report embeds these regulatory developments within the broader market dynamics section, showing how safety mandates interact with technology adoption, inspection costs, and competitive positioning. For executives overseeing compliance, risk, or capital planning, the value lies in understanding not just what the rules say but how enforcement patterns and standard revisions reshape commercial behavior across the industry.
Practical Utility: What the Report Delivers for Decision-Makers
This study is built for execution, not just intelligence consumption. It is structured to support several core workstreams that matter in 2026. First, it provides a market sizing and growth baseline that can anchor demand forecasts, capacity planning, and investment timing. Second, it presents competitive profiles and recent project activity in a format that helps procurement and engineering teams benchmark vendor capabilities and assess stable relationships versus opportunistic bids. Third, it links technology types and application contexts to operational realities, allowing readers to map system choices to shaft constraints, payload needs, and maintenance expectations. Fourth, it incorporates regulatory developments as dynamic variables, not static footnotes, so that compliance considerations are evaluated alongside cost and performance.
For companies planning new shafts, major hoist replacements, or phased modernization programs, the report can support three practical tasks: comparing total lifecycle value across hoist types, anticipating where service coverage and spare parts logistics will matter most, and timing investments to align with both regulatory cycles and regional demand momentum. For suppliers and investors, the same base of analysis can inform positioning decisions, partnership strategies, and identification of underserved segments with credible demand signals.
Crucially, the report does not stop at high-level narrative. It brings together historical performance, forward projections, segmentation logic, competitive profiles, recent developments, and regulatory context in a coordinated structure. That design reduces the risk of making decisions based on partial information. Instead of assembling scattered sources, leaders can work from a unified analytical frame that connects market size, competitive concentration, and operational requirements.
Why the Full Report Matters Now
The worldwide mine shaft elevator market is large enough to attract strategic attention and dynamic enough to reward careful analysis. USD 1,049.82 million in 2025 base revenue, a 5.25 percent CAGR through 2032, and a forecast exceeding USD 1.5 billion by the end of the period all point to a market with durable expansion. At the same time, the competitive set is concentrated, regulatory expectations are evolving, and technology pathways are being tested through demonstrator projects and specialized delivery programs. This combination means that intuition alone is insufficient for 2026 planning.
What this introduction has provided is a credible preview of the analytical depth and practical relevance available in the complete study. It has shown how market growth, competitive positioning, segment logic, and safety regulation are woven together into a decision-ready framework. What it has not done, by design, is expose the granular regional and application-level breakdowns, company-specific metric comparisons, and exact segmentation values that empower more precise planning. Those detailed calculations, benchmark tables, and scenario-ready figures are reserved for the full report, where they can be used without dilution and applied directly to procurement, investment, and risk-management workflows.
For executives and analysts who need to move beyond trend commentary into actionable strategy, the complete Worldwide Mine Shaft Elevator Market research offers the structure and specificity required to make confident decisions in 2026 and beyond.
Elevators Market
For detailed analysis of this topic, please visit the official page: Worldwide Mine Shaft Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Blown Castor Oil Market to Reach $206.59M by 2032 with 5.6% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Blown Castor Oil Market
As global manufacturing ecosystems undergo rapid transformation, decision-makers across coatings, adhesives, lubricants, and industrial chemical sectors face a critical imperative: align procurement and product development strategies with evolving material dynamics. PW Consulting’s latest Worldwide Blown Castor Oil Market research study delivers precisely the kind of structured, forward-looking intelligence required to navigate this landscape with confidence. Designed for executives, procurement leaders, R&D directors, and investment analysts, the report bridges historical performance, current market realities, and a disciplined multi-year forecast to position your organization ahead of structural shifts rather than reacting to them.
The blown castor oil segment is not merely a commodity derivative market; it is a functionally specialized value chain where viscosity control, oxidation stability, and solvent resistance dictate end-use performance across high-stakes applications. Understanding where demand is consolidating, how regional supply networks are rebalancing, and which operational levers will define competitive advantage in 2026 requires more than headline figures. It demands a rigorous breakdown of market architecture, cost dynamics, and strategic positioning. This research provides that depth, while intentionally reserving granular segmentation detail for the complete publication so that strategic teams can evaluate the full intelligence matrix before committing to capital or sourcing decisions.
Macro Trajectory and the Strategic Signal for 2026
The historical record establishes a market that has demonstrated resilience through cyclical volatility while maintaining a clear upward trajectory. Between 2020 and 2025, total market revenue expanded from 108.45 million USD to 141.08 million USD, reflecting a compound annual growth rate of 5.6 percent across the forecast horizon. This macro path is not linear; it carries the imprint of agricultural supply cycles, regional manufacturing recalibration, and downstream demand elasticity across coatings, lubricants, inks, and sealant formulations. For leadership teams planning 2026 operating budgets and capacity allocation, the critical insight is that growth is structurally anchored but sensitive to input pricing and formulation substitution trends. Strategic procurement and product roadmaps must therefore be built around scenario-aware assumptions rather than fixed-volume expectations.
Worldwide Blown Castor Oil Market
Looking forward, the forecast window extends through 2032, offering a multi-year planning frame that captures medium-term capacity adjustments, regional demand maturation, and the unfolding impact of raw material price movements on derivative economics. Organizations that integrate this temporal perspective into their strategic planning will be better positioned to time inventory commitments, evaluate supplier diversification, and prioritize R&D investments where application performance requirements are tightening. The full publication unpacks these forward pathways with a level of segmentation granularity that enables precise market-entry and portfolio-allocation decisions; the executive summary presented here is designed to establish the strategic rationale and direct readers toward the complete dataset.
What the Report Delivers: Operational Content Built for Decision-Making
PW Consulting’s market study is structured to move beyond descriptive market sizing and into actionable intelligence. The publication maps the blown castor oil ecosystem across multiple analytical dimensions, giving strategy and operations teams a unified reference point for sourcing, forecasting, and competitive benchmarking. Core content includes:
- Market sizing and trajectory analysis covering historical performance, current baseline positioning, and a disciplined forecast extending across the coming growth cycle, with explicit attention to demand momentum and structural inflection points.
- Segmentation architecture that dissects the market by viscosity grade and by application category, enabling readers to evaluate where performance specifications, regulatory requirements, and formulation preferences are steering demand concentration.
- Regional demand and supply mapping that identifies where consumption is heaviest, where manufacturing footprints are consolidating, and how trade flows are adapting to cost differentials and logistics realities.
- Raw material cost dynamics and supply chain sensitivity analysis that connects agricultural commodity cycles, origin availability, and downstream buying behavior to derivative pricing patterns, giving procurement teams early-warning context for budget planning.
- Competitive landscape profiling with company-level context on integrated manufacturers, specialty exporters, and regional producers, including their functional positioning across resins, greases, coatings, inks, adhesives, and plasticizer systems.
- Strategic implications and decision frameworks that translate market structure into practical guidance for sourcing strategy, capacity planning, product differentiation, and risk mitigation.
This structure is purpose-built for cross-functional use. Procurement leaders can align purchasing strategies with cost-cycle visibility; R&D and formulation teams can identify performance-driven demand pockets; and corporate strategy groups can assess where incremental investment or market participation is most defensible. The complete study preserves full segmentation breakdowns and detailed regional-application interplay so that decision-makers can test assumptions against the full evidence base rather than relying on high-level aggregates.
Competitive Landscape: Positioning in a Concentrated Ecosystem
The blown castor oil market displays meaningful concentration among established manufacturers, with strategic positioning heavily influenced by integration depth, derivative capability, and geographic proximity to both raw material origins and end-use industrial clusters. Industry concentration metrics underscore the importance of understanding not only who the leading players are, but how their product architectures and market access strategies shape procurement options and competitive pressure. The report profiles a set of core enterprises whose activities define the current supply landscape:
- Jayant Agro-Organics Ltd. operates as a leading integrated manufacturer and exporter, with blown castor oil positioned across plasticizer applications in paints, sealants, printing inks, and adhesives. Its scale and integration give it a strong reference point in the global supply chain.
- Girnar Industries produces polymerized blown castor oil formulations used in resins, adhesives, heat-set inks, sealant systems, and oil- or solvent-resistant plasticizer applications, emphasizing functional customization for industrial end-users.
- Vandeputte Group manufactures oxidized blown oils, including oxidized castor oil, for use in greases, lubricants, adhesives, coatings, and plasticizer applications in inks and surface coatings, reinforcing a specialty chemical orientation across European and international markets.
- Nikunj Chemicals focuses on manufacturing and export of blown castor oil for broad industrial applications, contributing to the competitive breadth of the supply base.
- Adya Oils & Chemicals specializes in castor oil derivatives with customized blown castor oil offerings tailored to industrial and formulation-specific requirements.
- CanCastor serves as a global supplier, emphasizing the functional value of blown castor oil in industrial applications and supporting procurement with standardized documentation such as COA, TDS, and MSDS materials.
- Castor International operates as a specialist in sourcing, marketing, and sales of castor oil and derivatives, offering oxidized castor oil for chemical industry uses and bridging global supply with downstream demand.
- Tongliao TongHua Castor Chemical Co., Ltd. produces castor oil products including blown castor oil alongside other derivative grades, expanding regional manufacturing depth and derivative optionality.
- Thai Castor Oil Industries Co., Ltd. stands as a major castor oil producer with derivative capabilities that support global supply of blown castor oil, reflecting the strategic importance of Asia-Pacific production infrastructure.
- Gokul Overseas / Gokul Agro Group contributes to the export-oriented supply of castor oil and derivatives, including blown castor oil, reinforcing the competitive density of the international trade network.
This landscape matters for 2026 strategy because supplier optionality, technical differentiation, and documentation readiness increasingly determine procurement resilience. Organizations evaluating supplier consolidation, dual-sourcing strategies, or regional qualification pathways will find the report’s company context and structural assessment essential for separating routine supply relationships from strategically significant partnerships.
Raw Material Dynamics and the Cost Environment Shaping 2026
Any credible market strategy for blown castor oil must account for the raw material environment in which it is produced and priced. Castor oil pricing is intimately tied to agricultural cycles, crop yields, and downstream demand pacing, and recent market signals show a pricing environment that is adjusting rather than stabilizing in a straight line. In the United States, castor oil prices reached 1,724 USD/MT in September 2025 before easing, reflecting the interplay between ample origin supply and softer downstream buying. Month-on-month relief continued into early 2026, with U.S. prices declining approximately 4 percent in January 2026 as supply conditions remained supportive and buying caution persisted.
Looking into the first quarter of 2026, price indications have been observed across key reference markets: the United States around 1,643 USD/MT, China near 1,780 USD/MT, and Germany in the vicinity of 1,718 USD/MT. These discrepancies matter because regional cost differentials influence export competitiveness, inland formulation economics, and the relative attractiveness of alternative sourcing routes. At the same time, Indian market pricing has exhibited its own dynamic, with a noted decline in Q1 2026 pricing on an FOB basis as domestic conditions adjusted to broader trade and demand patterns. This level of cost nuance is critical for procurement teams evaluating landed-cost exposure and for product managers assessing whether formulation substitution or specification tightening is economically justified in the near term.
The broader supply chain context reinforces why these pricing movements cannot be interpreted in isolation. Castor oil supply remains sensitive to agricultural commodity cycles and global crop yields, which directly affects production costs for derivatives such as blown castor oil. For strategic planners, this means that forecasting and sourcing decisions must incorporate a supply-side risk lens, not merely a demand-side growth narrative. The full study embeds these dynamics within the segmentation and regional analysis so that cost, concentration, and application pressure can be evaluated together rather than as disconnected inputs.
Why This Research Is Strategically Essential for 2026 Decisions
In a market where growth is positive but sensitive, where concentration creates both pricing leverage and supplier risk, and where raw material cost cycles can alter the attractiveness of specific formulation pathways, strategic advantage belongs to teams that can see the market with precision. PW Consulting’s Worldwide Blown Castor Oil Market research provides that precision by merging historical validation, current demand architecture, competitive mapping, and multi-year forecasting into a single decision-ready framework.
The report is designed to support several high-value use cases:
- Sourcing and procurement strategy that balances cost exposure, supplier qualification, and regional availability against a structured view of market concentration and application demand.
- Portfolio and product planning that identifies which viscosity grades and application categories are most relevant to near-term demand, enabling R&D and commercial teams to prioritize development resources.
- Market entry and expansion evaluation that helps corporate development and regional strategy teams assess where incremental participation is most defensible, taking into account demand geography and competitive density.
- Risk management and scenario planning that connects raw material price behavior, agricultural supply sensitivity, and downstream buying patterns to budgeting and inventory decisions.
High-level aggregates establish direction, but the strategic value of this study lies in the depth that follows: how segmentation splits articulate with regional consumption, how concentration metrics inform supplier dependence, and how application-level performance requirements translate into durable demand pockets. Those details are fully presented in the complete publication, where executive teams can review the full intelligence architecture before making sourcing commitments, capacity decisions, or investment allocations.
Castor Oil Modified Polyol Market
From Insight to Action: Accessing the Complete Intelligence
The Worldwide Blown Castor Oil Market report is built for leaders who need more than directional commentary. It offers a disciplined, evidence-based view of where the market has been, how it is currently structured, and what the forward trajectory implies for 2026 and beyond. The macro growth path, competitive concentration, raw material cost dynamics, and application viscosity framework together define a landscape in which clarity translates directly into better procurement timing, stronger supplier strategy, and more targeted product development.
For organizations that require the complete segmentation detail, regional-application interplay, and full competitive context to support high-stakes decisions, the full study is available through PW Consulting’s market research portal. The publication preserves the granular data and analytical breakdowns necessary to validate assumptions, compare sourcing alternatives, and build internal strategy narratives with confidence. Readers interested in obtaining the complete dataset and detailed market maps should access the full report through the official study page to ensure they are working from the current, comprehensive version of the analysis.
Strategic advantage in blown castor oil is not simply a matter of tracking growth; it is a matter of interpreting structure, cost behavior, and competitive positioning with rigor. This research provides that rigor, and the most consequential decisions will be made by teams that take the next step toward the complete intelligence set.
For detailed analysis of this topic, please visit the official page: Worldwide Blown Castor Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Satellite Internet Hits $7,042M in 2026, 11.22% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Connected Seas: Strategic Intelligence for the Marine Satellite Internet Market
The maritime connectivity landscape has reached an inflection point. As vessels transition from discretionary broadband to mission-critical digital infrastructure, the Worldwide Marine Satellite Internet System Market is reshaping how shipping companies, defense agencies, cruise operators, and offshore energy firms plan their procurement, network architecture, and long-term capital allocation. This market research publication is designed not as a retrospective ledger but as a forward-looking strategic instrument. For executives making multi-year fleet decisions in 2026, the intelligence contained within this study provides the analytical rigor needed to separate temporary technology hype from durable competitive advantage.
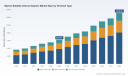
The sector has demonstrated remarkable momentum over the past half-decade. Between 2020 and 2025, global revenue climbed from approximately 3.7 billion USD to over 6.2 billion USD, reflecting both the maturation of high-throughput satellite ecosystems and the accelerating digitization of maritime operations. Looking toward 2032, the market trajectory points toward sustained expansion, with a compound annual growth rate of 11.22 percent. By the end of the forecast window, cumulative revenues will approach 13 billion USD, signaling that satellite internet is no longer a niche maritime add-on but a foundational layer of global maritime logistics. This growth is not merely a function of unit sales; it is being driven by a structural shift in how vessels are operated, maintained, and monetized at sea.
The Architecture of the Analysis
Any market study worth its weight must move beyond headline figures and into the operational mechanics of the industry. This report is structured to serve as a decision-support platform for procurement directors, network architects, fleet managers, and investment committees. The analysis covers terminal type evolution, end-user demand patterns, regional deployment dynamics, and the competitive maneuvers reshaping market concentration. Readers will find granular assessments of how VSAT terminals continue to anchor enterprise-grade reliability while LEO compact terminals and MSS terminals carve out specialized roles in crew welfare, safety communications, and rapid-deployment scenarios. The end-user breakdown examines how merchant shipping, cruise and leisure vessels, government and defense platforms, and offshore energy operators each impose distinct bandwidth profiles, latency tolerances, and redundancy requirements.
Beyond segmentation, the publication delivers actionable operational content. It maps the power consumption realities of maritime terminals, discusses the integration challenges of hybrid GEO and LEO architectures, and evaluates how regulatory developments across the United States, Europe, and Asia are influencing spectrum access, licensing frameworks, and lawful interception expectations. The report also addresses cybersecurity imperatives for fleets transitioning to always-on satellite connectivity, alongside the operational trade-offs between managed service models and self-operated terminal deployments. Each section is designed to translate market intelligence into procurement strategy, vendor evaluation criteria, and fleet-wide connectivity roadmaps.
Competitive Landscape: Who Shapes the Market
Market concentration remains a defining feature of the marine satellite internet ecosystem. The top three players capture a meaningful share of global revenue, while the top five collectively control the majority of high-value managed connectivity contracts. This concentration does not imply stagnation; rather, it reflects the high barriers to entry associated with orbital spectrum rights, terminal certification, global ground infrastructure, and long-term fleet service agreements. Yet the competitive field is increasingly dynamic, with incumbent GEO and hybrid service providers adapting to the low-latency promise of LEO networks while new entrants leverage phased-array terminals and unlimited data models to disrupt traditional pricing structures.
Viasat, operating through its Inmarsat Maritime division, has advanced a bonded multi-orbit strategy that pairs GEO high-throughput capabilities with LEO augmentation. The recent unveiling of the next phase of its NexusWave service, supported by a new VS60 maritime terminal engineered in partnership with Intellian and leveraging ViaSat-3 satellite capacity, illustrates how incumbents are investing in terminal hardware to unlock enterprise networking, video streaming, and mission-critical operations for commercial shipping, cruise, and offshore fleets. SpaceX Starlink Maritime has pursued a different trajectory, emphasizing high-speed, low-latency LEO connectivity through flat-panel phased-array terminals and unlimited data plans designed for crew welfare, operational connectivity, and vessel management across global routes. This approach has resonated strongly with operators seeking predictable bandwidth economics and rapid terminal deployment.
Iridium Communications continues to anchor the market in global LEO narrowband and broadband services, with Iridium Certus providing data, voice, and hybrid connectivity solutions tailored to vessels that require pole-to-pole coverage and reliable backup communications. Its recent selection by a major shipping line for hybridized fleet operations alongside Starlink underscores a broader industry pattern: operators are increasingly layering complementary networks rather than relying on a single provider. Marlink has built its position around managed hybrid satellite networks that integrate GEO VSAT, Starlink, and OneWeb LEO resources, with an emphasis on smart digital solutions, cybersecurity, and high-availability connectivity for commercial shipping and cruise lines. Speedcast brings deep expertise in VSAT and managed satellite communication services for maritime, offshore, and energy sectors, prioritizing reliability, network optimization, and large-fleet integration.
Equipment manufacturing remains a critical enabler. Intellian Technologies supplies high-performance maritime VSAT antennas and terminals, including systems designed for Viasat NexusWave and OneWeb-compatible architectures, spanning yachts to large commercial vessels. KVH Industries continues to deploy mini-VSAT broadband terminals and airtime services, with TracPhone systems engineered for global HTS coverage across yachts, commercial vessels, and crew connectivity applications. On the satellite operator side, Intelsat offers FlexMaritime and other GEO and hybrid VSAT solutions supporting enterprise networking and operational data across global shipping routes, while the Eutelsat Group, integrating OneWeb LEO capacity, delivers resilient high-throughput connectivity for vessels operating in remote areas. Hughes Network Systems, under EchoStar, has expanded its footprint with ruggedized transportable LEO terminals certified for Comms-on-the-Pause service and compatible with the Eutelsat OneWeb network, enabling rapid broadband deployment in mobility scenarios including maritime support.
The service ecosystem is further diversified by providers such as NSSLGlobal, Satcom Global, IEC Telecom, and AST Networks, each contributing specialized combinations of VSAT, L-band, Iridium, Inmarsat, and hybrid LEO offerings with regional expertise, fleet management tooling, and IoT-focused solutions. The competitive dynamics are not merely a roster of vendors; they reflect a strategic contest over managed service models, terminal standardization, multi-orbit bonding, and the ability to deliver predictable performance across harsh maritime environments.
Market Dynamics: Forces Reshaping Procurement and Deployment
Several structural forces are converging to redefine how marine satellite internet systems are evaluated and purchased in 2026. First, the terminal power envelope is becoming a more prominent operational consideration. Maritime VSAT and LEO terminals typically consume between 60 and 150 watts, with high-speed performance kits requiring elevated power budgets compared to traditional GEO systems. This reality has direct implications for vessel power management, installation design, and the economics of broadband operations on smaller or energy-constrained platforms. Second, safety and regulatory mandates are reinforcing demand for robust, certifiable connectivity. Iridium Certus GMDSS provides the only truly global maritime distress and safety system, encompassing distress alerts, safety voice, Maritime Safety Information, LRIT, and SSAS services, making it a non-negotiable element for operators prioritizing regulatory compliance and crew safety.
Third, spectrum policy is entering a period of active modernization. The FCC is advancing spectrum policy that includes auctions in the Upper C-Band and AWS-3 bands, alongside modernization of satellite regulations intended to support growing LEO and space operations. In parallel, the EU Open Internet Regulation and the proposed Digital Networks Act maintain net neutrality principles while addressing spectrum harmonization and satellite integration for digital sovereignty. These regulatory trajectories influence not only terminal certification and service availability but also the strategic calculus of operators seeking to operate seamlessly across jurisdictions. Governments are also asserting digital sovereignty through licensing, taxation, and lawful interception requirements for LEO satellite services that cross national borders, adding a layer of compliance complexity to global fleet deployments.
Fourth, the industry is navigating a phase of accelerated terminal and service evolution. The introduction of ruggedized transportable LEO terminals, new bonded connectivity services, and hybrid fleet configurations signals that the market is moving from single-orbit dependency to multi-orbit orchestration. Operators are increasingly designing networks that combine the throughput and latency advantages of LEO with the coverage reliability and service maturity of GEO, while maintaining safety-grade fallback. This hybridization trend is reshaping vendor evaluation criteria, as procurement teams now weigh not only bandwidth cost but also integration complexity, service continuity, cybersecurity posture, and regional support coverage.
Worldwide Marine Satellite Internet System Market
Why This Study Matters for 2026 Decision-Making
For organizations planning fleet upgrades, terminal standardization, or connectivity partnerships in 2026, the strategic value of this research lies in its ability to convert market complexity into actionable clarity. The report does not simply report what happened between 2020 and 2025; it maps the conditions that will determine which investments deliver durable advantage through 2032. Decision-makers will find structured analysis of how terminal types are evolving in response to bandwidth, latency, power, and safety requirements. End-user segments are examined through the lens of operational priorities, revealing why merchant shipping, cruise and leisure, government and defense, and offshore energy operators each demand distinct connectivity architectures. Regional dynamics are assessed in terms of deployment density, regulatory environments, and competitive intensity, without oversimplifying the heterogeneity of local market conditions.
Equally important, the study provides a framework for interpreting vendor strategies and market concentration trends. Understanding how leading providers are positioning multi-orbit services, managed hybrid networks, and next-generation terminals allows procurement leaders to anticipate pricing shifts, service bundling patterns, and potential consolidation risks. The competitive profiles and recent developments captured in this research highlight where innovation is materializing, which partnerships are gaining operational traction, and how terminal hardware is becoming a strategic differentiator rather than a commodity accessory.
Broadband Satellite Services Market
The report also addresses the operational realities that often fall outside high-level market summaries. It examines the implications of terminal power consumption for vessel integration, the role of safety-grade services in shaping baseline procurement requirements, and the regulatory landscape that influences spectrum access and cross-border service continuity. Cybersecurity considerations are treated as integral to connectivity strategy rather than as an afterthought, reflecting the reality that always-on maritime broadband expands both operational capability and attack surface. By weaving these dimensions together, the study equips readers to evaluate total cost of ownership, service resilience, and long-term scalability with greater confidence.
What You Will Gain by Going Deeper
This overview is intentionally designed as a strategic preview. It demonstrates the analytical depth, market context, and decision-oriented framing that the full report delivers, while leaving the precise segmentation values, regional revenue distributions, end-user percentages, and terminal-level financial breakdowns for the complete publication. Those details matter because they convert directional insight into procurement-ready intelligence. They allow organizations to benchmark fleet expenditure patterns, compare regional deployment economics, and align terminal selections with specific operational profiles rather than generic market averages.
The full study also expands the competitive analysis into a structured evaluation of service models, terminal compatibility, orbital strategy, and regional support coverage. It provides the context needed to assess where bonded multi-orbit architectures are delivering measurable performance gains, where LEO-only solutions are appropriate, and where GEO fallback remains essential for safety, redundancy, or regulatory compliance. For investment committees and strategic planners, the forecast period through 2032 offers a basis for modeling recurring connectivity spend, terminal refresh cycles, and the reallocation of operational budgets toward digital services.
Next Steps for Strategic Leaders
The Worldwide Marine Satellite Internet System Market is expanding at a pace that rewards disciplined analysis. Organizations that treat connectivity as a strategic utility rather than a tactical expense will be better positioned to manage fleet performance, crew welfare, compliance obligations, and operational resilience. This research publication is built to support that shift. It provides the market context, competitive intelligence, and segmentation logic required to make informed 2026 decisions with an eye toward the 2032 horizon.
To access the complete segmentation data, regional revenue distribution, end-user breakdowns, and the full competitive profiles accompanying this forecast, visit the source page for the Worldwide Marine Satellite Internet System Market research. The detailed tables, terminal-level analysis, and operator-level scenario discussions are available there, enabling procurement, network, and strategy teams to translate market momentum into concrete fleet and service decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Marine Satellite Internet System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cyclopentylamine Market Hits $112.45M in 2025, Poised for 4.95% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Global Cyclopentylamine Market: Navigating Growth and Complexity in 2026
The global chemical landscape is undergoing a period of measured expansion, and within this broader ecosystem, cyclopentylamine has emerged as a compound of significant strategic interest for stakeholders across pharmaceutical, agrochemical, and specialty manufacturing sectors. As organizations refine their procurement strategies, capacity planning, and competitive positioning for the 2026–2032 horizon, access to rigorously validated market intelligence is no longer a differentiator—it is a prerequisite for resilient decision-making. This article introduces PW Consulting’s latest independent assessment of the Worldwide Cyclopentylamine Market, outlining the structural dynamics, value chain sensitivities, and competitive forces that will shape industry trajectories in the coming years. The following analysis is designed to provide executives, procurement leaders, and R&D strategists with a clear lens into the market’s directional momentum, while emphasizing the depth of operational and commercial intelligence required to navigate its nuances.
Macroeconomic Trajectory and Value Chain Momentum
Cyclopentylamine’s commercial footprint has demonstrated a pattern of structural resilience, underpinned by steady demand across high-margin specialty applications and a production ecosystem that continues to optimize cost efficiency. Historical data spanning 2020 through 2025 reflects a market that has navigated supply volatility, feedstock pricing fluctuations, and shifting regulatory expectations with disciplined adaptation. From a baseline of approximately 88.42 million USD in 2020, the market advanced through a period of recalibration, reaching an estimated 111.79 million USD by 2024 and stabilizing near 112.45 million USD in 2025. This trajectory underscores a market that has successfully absorbed external pressures while maintaining foundational demand streams.
Worldwide Cyclopentylamine Market
Looking forward, the forecast window through 2032 projects a compound annual growth rate of 4.95 percent, with nominal revenue expanding from an estimated 117.1 million USD in 2026 toward a terminal valuation approaching 157.7 million USD by the end of the decade. This growth profile reflects a combination of steady volume expansion, incremental adoption in downstream formulation cycles, and the continued substitution of lower-purity alternatives in applications where consistency and regulatory compliance are non-negotiable. Importantly, the expansion is not uniform; it is shaped by regional production capacity adjustments, feedstock availability, and the strategic priorities of end-user industries that treat cyclopentylamine as a critical building block rather than a commodity input.
Feedstock dynamics have played an increasingly visible role in shaping production economics. Cyclopentanone, a primary upstream precursor in reductive amination pathways, has experienced noticeable price movements tied to regional oversupply conditions and broader aromatics market trends. In the final quarter of 2024, pricing in China registered a decline of roughly four percent, driven by softer demand and abundant supply. Throughout 2025, similar stabilizing to downward pressures were observed across Asian, European, and North American markets, reflecting lower benzene-derived feedstock costs and comfortable inventory positions. These upstream conditions have created a favorable cost environment for producers who maintain efficient conversion yields and disciplined operational footprints, while simultaneously placing pressure on less optimized capacity to compete on margin.
Demand Architecture and Application Drivers
The commercial relevance of cyclopentylamine is anchored in its versatility as a chemical intermediate, with demand distributed across several high-value end-use streams. Pharmaceutical intermediates represent the dominant application channel, where the compound serves as a functional building block in synthesis pathways that demand stringent purity standards, batch-to-batch reproducibility, and regulatory-grade documentation. In this context, cyclopentylamine is valued not merely for its chemical reactivity but for its role in enabling efficient downstream processing and reducing variability in active ingredient development.
Agrochemical formulations constitute the second major demand pillar, where cyclopentylamine supports the development and production of specialty crop protection compounds and intermediate formulations. As agricultural input manufacturers continue to optimize performance-to-volume ratios and adapt to evolving regional registration frameworks, the compound’s role in enabling targeted molecular architectures has reinforced its position within this segment. Beyond these core channels, cyclopentylamine also finds application in rubber processing chemicals, where it contributes to formulation stability and processing performance, alongside a smaller but steady demand stream across miscellaneous industrial and specialty chemical applications.
Purity specifications remain a decisive commercial variable. The market exhibits a pronounced preference for high-purity grades, which command stronger positioning in research, pharmaceutical, and regulated specialty applications. Lower-purity variants maintain a presence in segments where cost sensitivity and performance requirements allow for broader tolerance thresholds. Understanding the interrelationship between purity segmentation, downstream quality expectations, and pricing architecture is essential for organizations that seek to align procurement strategies with end-product value propositions. Rather than treating purity as a binary specification, market participants increasingly view it as a strategic lever that influences regulatory clearance timelines, customer acceptance cycles, and long-term margin sustainability.
Regulatory Environment and Operational Compliance
Regulatory and environmental frameworks continue to exert meaningful influence on how cyclopentylamine is produced, distributed, and integrated into downstream products. In the European Union, the compound falls under REACH regulatory oversight, with exposure control requirements shaped by its potential impact on aquatic environments and the expectation of long-term ecological stewardship. These obligations extend beyond compliance documentation; they influence logistics planning, storage protocols, waste handling, and cross-border distribution strategies, particularly for manufacturers and distributors operating across multiple jurisdictions.
In North America, cyclopentylamine is managed under established US EPA and FDA guidelines relevant to chemical manufacturing, safety practices, and its use as an intermediate in pharmaceutical and agrochemical applications. While the regulatory posture is largely operational and quality-focused rather than restrictive, the expectation of traceability, documentation rigor, and process control remains elevated. Organizations that proactively align their operational procedures with these expectations are better positioned to reduce certification lead times, mitigate supply chain friction, and maintain uninterrupted market access across regions with differing compliance cultures.
For global buyers and suppliers alike, regulatory alignment is increasingly a competitive consideration. The cost of non-compliance is not limited to fines or operational interruptions; it extends to customer qualification delays, loss of preferred supplier status, and increased complexity in multi-region distribution. As such, regulatory readiness has become an integral component of market strategy, influencing everything from sourcing decisions to partnership structures and geographic expansion priorities.
Competitive Landscape and Strategic Positioning
The cyclopentylamine market is characterized by a moderately concentrated supply base, with a handful of established players accounting for a meaningful share of global distribution and production capacity. The CR3 concentration level sits at approximately 42.5 percent, while the CR5 share extends to 58.85 percent, indicating a competitive field that balances scale advantages with the presence of specialized regional and application-focused suppliers. This structure creates a market environment where scale, technical service capability, and regulatory agility all contribute to commercial differentiation.
Among the core participants, Sigma-Aldrich, operating under Merck KGaA in Darmstadt, Germany, continues to represent a prominent reference point for high-purity cyclopentylamine supply. Its positioning as a reagent and building-block provider for research, pharmaceutical, and specialty chemical applications gives it a strong foothold in segments where traceability, documentation, and batch consistency are paramount. Biosynth Ltd, based in the United Kingdom, complements this landscape by offering cyclopentylamine for both R&D and production-scale requirements, with capabilities that include hazardous material handling and global distribution networks. This dual-focus model enables the company to serve customers across the development-to-commercialization continuum.
From the Asian production base, TNJ Chemical has established itself as a manufacturer and supplier of cyclopentylamine positioned around pharmaceutical intermediate applications, with an emphasis on bulk production capacity. Its scale-oriented approach reflects broader trends in regional manufacturing ecosystems that prioritize volume responsiveness and cost efficiency. Volant-Chem Corp, also based in China, operates as a manufacturer of fine chemicals including cyclopentylamine, with ISO 9001 certification and a focus on sulfonyl and amine derivatives. This specialization reinforces its relevance for customers seeking integrated access to related chemical families and process-aligned supply relationships. Broadpharm, headquartered in San Diego, California, serves as a US-based supplier for chemical and pharmaceutical research applications, catering to domestic buyers who prioritize localized service, rapid fulfillment, and alignment with North American compliance expectations.
The competitive dynamics of this market extend beyond product availability. Suppliers differentiate through technical support, regulatory documentation quality, lead-time reliability, and the ability to accommodate custom purity or packaging requirements. In a market where downstream customers increasingly treat intermediate sourcing as a strategic partnership rather than a transactional purchase, these capabilities can determine long-term supplier retention and market share evolution.
What This Market Study Delivers
PW Consulting’s Worldwide Cyclopentylamine Market study is structured to provide decision-makers with an integrated, operationally relevant view of market behavior, competitive forces, and forward-looking risk factors. The analysis is designed not as a high-level summary but as a working intelligence asset that supports procurement planning, investment evaluation, and strategic scenario modeling. The report’s architecture reflects the needs of organizations that must balance commercial ambition with operational discipline.
At its core, the study offers a comprehensive market sizing framework covering historical performance and forecast trajectories across the full analysis window. It places particular emphasis on translating macro-level growth signals into actionable context, allowing readers to assess how demand composition, pricing dynamics, and regional supply conditions interact over time. The analysis also examines how upstream feedstock conditions influence production economics, providing a structured view of cost-side sensitivities that can affect margin planning and sourcing strategy.
In addition to market-wide assessment, the study delivers a detailed competitive landscape review that maps the positioning, operational focus, and commercial strengths of leading suppliers. This includes an evaluation of how scale, geographic presence, application specialization, and compliance readiness shape competitive advantage. The report also addresses the regulatory environment across key markets, highlighting exposure control expectations, documentation standards, and the operational implications of cross-border chemical handling requirements.
To ensure practical utility, the study incorporates scenario-sensitive analysis that helps stakeholders evaluate how shifts in feedstock pricing, regulatory interpretation, and demand composition could alter market outcomes over the forecast period. This forward-looking component is particularly valuable for organizations that must plan for multiple contingencies, including changes in regional cost structures, new compliance obligations, or shifts in downstream formulation priorities. Readers seeking complete market sizing tables, full segmentation breakdowns, and supplier-level strategic profiles will find the full report structured to support detailed internal review and executive decision-making.
Translating Insight into 2026 Decision-Making
For organizations operating in or adjacent to the cyclopentylamine value chain, 2026 represents a pivotal moment to translate intelligence into action. The convergence of stable-to-favorable feedstock conditions, steady demand growth in pharmaceutical and agrochemical applications, and a competitive field that rewards reliability and compliance readiness creates an environment where strategic positioning can be reinforced through disciplined planning. Procurement teams can use market-level insight to evaluate supplier diversification, negotiate terms with a clearer understanding of cost-side dynamics, and reduce exposure to regional supply disruptions. R&D and formulation leaders can align purity selection and sourcing pathways with downstream performance requirements, ensuring that material choices support both regulatory timelines and product differentiation objectives.
For manufacturers and distributors, the forecast period offers an opportunity to assess capacity utilization, evaluate regional expansion trade-offs, and strengthen service capabilities that distinguish their offerings in a moderately concentrated market. Understanding how purity preferences, application demand, and regulatory expectations interact allows companies to refine their product portfolios and customer engagement models with greater precision. For investors and strategic planners, the market’s growth trajectory and competitive structure provide a foundation for evaluating where incremental investment, partnership formation, or vertical integration could generate sustained value.
Accessing the Full Intelligence Framework
The cyclopentylamine market is evolving within a broader chemical ecosystem that rewards precision, preparedness, and strategic foresight. While the directional signals are clear, the detailed mechanics that determine commercial success—segment-level demand behavior, regional pricing sensitivities, supplier capability comparisons, and regulatory impact pathways—require a more granular analytical lens. PW Consulting’s complete Worldwide Cyclopentylamine Market study delivers that depth, providing the full dataset, segmentation detail, competitive benchmarking, and scenario analysis needed to support confident, evidence-based decisions.
Cyclopentanone Market
Stakeholders who require comprehensive market sizing, full segmentation breakdowns, and supplier-level strategic profiles are encouraged to access the complete report through our official research portal. THERE, decision-makers can obtain the complete intelligence framework necessary to align procurement, production, and growth strategies with the realities of a market poised for steady expansion through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Cyclopentylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Suspension Bridge Apparatus Market to Hit $74.44M by 2032, 6.01% CAGR from $49.5M in 2025
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Engineering Lab Sector: Inside the Worldwide Suspension Bridge Apparatus Market 2026-2032
The global engineering education and testing sector is entering a transformative phase defined by digitization, enhanced safety protocols, and sustained infrastructure investment. At the center of this shift lies the Worldwide Suspension Bridge Apparatus Market, a niche yet critical segment supporting civil and mechanical engineering laboratories worldwide. PW Consulting's latest comprehensive study offers a definitive roadmap for stakeholders navigating this evolving landscape through 2032.
This article serves as a strategic briefing on the findings contained within the full report. It is designed to equip executives, procurement leaders, and investment analysts with the contextual understanding necessary to make informed decisions in 2026. While we highlight the macroeconomic trajectories and competitive dynamics here, the precise segmentation data and granular forecasts are reserved for subscribers who require actionable intelligence to secure their market position.
Market Trajectory and Growth Dynamics
The suspension bridge apparatus sector has demonstrated resilience and steady expansion over the past half-decade. Drawing from historical data spanning 2020 to 2025, the market has shown a consistent upward trend in revenue generation, reflecting the heightened emphasis on practical engineering training and structural testing capabilities. The transition from 2025 into the forecast period indicates a continuation of this momentum, driven by renewed focus on infrastructure durability and the modernization of laboratory equipment.
Our analysis projects the market valuation to reach significant milestones by the end of the forecast period in 2032. The compound annual growth rate (CAGR) observed during the historical window sets a baseline for expectations, while forward-looking indicators suggest sustained growth fueled by both replacement cycles and new laboratory installations. Understanding the velocity of this growth is essential for capacity planning and R&D allocation.
Key drivers influencing this trajectory include:
- Increasing global infrastructure investments that necessitate rigorous testing protocols in academic and industrial settings.
- A shifting preference toward durable materials and advanced monitoring tools within structural mechanics.
- The integration of digital data acquisition systems into traditional mechanical apparatuses, enhancing the value proposition of modern units.
However, growth is not uniform across all vectors. The interplay between raw material costs, specifically high-carbon steel wire rods used in cable components, and the purchasing power of educational institutions creates a complex pricing environment. Our full report dissects these cost pressures and their impact on margin stability for manufacturers and suppliers.
Worldwide FRP Bridge Market
Product Innovation and Technological Shifts
The definition of a suspension bridge apparatus is evolving. Historically, these units were purely mechanical setups designed to demonstrate load distribution and cable tension. Today, the market is witnessing a convergence of hardware and software. Leading solutions now incorporate digital data acquisition kits and software-integrated analysis modules, allowing for real-time visualization of stress factors and parabolic cable behavior.
This technological shift is reshaping demand. While traditional manual bench-top apparatuses remain relevant for foundational training, there is a marked inclination toward systems that offer connectivity and advanced analytics. The ability to compare experimental data against cable theory through software interfaces adds a layer of sophistication that appeals to higher-tier research centers and university labs seeking to maintain accreditation standards.
Manufacturers are responding by modularizing their offerings. Equipment that mounts on standard structures platforms with optional data acquisition capabilities allows institutions to scale their investment based on budget and curriculum requirements. This flexibility is becoming a key differentiator in a crowded marketplace.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established European manufacturers and agile regional suppliers. Concentration metrics indicate a moderately fragmented environment, where top players hold significant share but regional competitors maintain strong footholds through localized pricing and service networks. Understanding the specific positioning of these entities is crucial for identifying partnership opportunities or potential acquisition targets.
Several core companies define the current competitive baseline:
- TecQuipment (United Kingdom): Recognized for their Next Generation Structures range, specifically the Simple Suspension Bridge experiment modules. Their focus on compatibility with data acquisition systems positions them as a premium provider for advanced educational study.
- PA Hilton (United Kingdom): Offers robust structural ranges featuring rigid decks and twin steel cables. Their emphasis on visual demonstration and load cell measurement caters to institutions prioritizing clear pedagogical outcomes.
- Edibon (Spain): Provides units designed for strength of materials and mechanics labs, utilizing lightweight alloy beams and parallel main cables to simulate dynamics of forces and stresses effectively.
- Infinit Technologies (Saudi Arabia): Supplies apparatuses that focus on various load cases with integrated force gauges, serving the specific needs of technical training in the Middle East region.
- Indian Manufacturers (Edutek, Shambhavi Impex, Swarg Systems, Ambros India, Elshaddai Engineering): A cluster of suppliers based in India offers cost-effective solutions for mechanical and civil engineering labs. These players compete heavily on price and customization, such as roller conversion options and specific cable dimensions, making them vital for budget-conscious procurement strategies.
Strategic maneuvering in this landscape often involves balancing the premium quality and software integration offered by Western manufacturers against the value and customization provided by Asian suppliers. The full report provides a detailed competitive benchmarking analysis that goes beyond product features to examine market share distribution and regional penetration strategies.
Regulatory and Raw Material Influences
External factors play a disproportionate role in the stability and pricing of suspension bridge apparatuses. The reliance on high-carbon steel wire rod as a primary raw material links the cost of laboratory equipment to the broader volatility of the global steel wire rope market. With the broader steel wire rope sector valued in the billions, fluctuations in supply chain dynamics can ripple down to affect component pricing for apparatus manufacturers.
Furthermore, regulatory frameworks are tightening. Recent presentations at the 2024 International Cable Supported Bridge Operators Conference highlighted new AASHTO Guidelines for Risk-Based Inspection and Strength Evaluation of Suspension Bridge Main Cable Systems. While these guidelines target operational bridges, they influence the educational standards required for engineers entering the workforce. Laboratories must ensure their apparatuses can simulate conditions relevant to these updated safety and evaluation protocols, driving demand for more sophisticated testing units.
Additionally, the macro trend of increasing global infrastructure investments continues to validate the need for structural mechanics education. As governments and private entities pour capital into durable infrastructure, the pipeline for civil engineers equipped with practical knowledge of suspension dynamics remains robust. This creates a long-term demand anchor for the apparatus market, insulating it somewhat from short-term economic dips in other sectors.
Strategic Value of the Full Report
The insights summarized above represent only the surface level of the intelligence available in the PW Consulting Worldwide Suspension Bridge Apparatus Market report. For decision-makers in 2026, the difference between reactive planning and proactive strategy lies in the depth of data access.
Worldwide Suspension Bridge Apparatus Market
Subscribers to the full study gain access to:
- Granular Revenue Forecasts: Detailed year-by-year projections through 2032 that allow for precise budget allocation and inventory planning.
- Segment-Specific Growth Rates: Uncovered insights into which product categories and end-user segments are outperforming the market average, enabling targeted marketing and product development.
- Regional Market Shares: Exact valuation splits across key geographies, helping exporters identify high-potential markets and importers assess local competition.
- Competitive 심층 Analysis: Beyond company profiles, the report includes strategic group mapping and potential disruptor analysis.
- Risk Assessment: A dedicated section on raw material volatility and regulatory changes, providing mitigation strategies for supply chain managers.
In an environment where engineering labs are increasingly evaluated on their technical capabilities and safety compliance, relying on general market trends is insufficient. The specific data points contained in this report enable stakeholders to quantify opportunities, validate investment theses, and negotiate from a position of knowledge.
Conclusion
The Worldwide Suspension Bridge Apparatus Market stands at a pivotal intersection of educational demand, technological integration, and infrastructure-driven necessity. The growth trajectory observed from 2020 through 2025 sets a strong foundation for the forecast period ending in 2032. However, capturing value in this market requires more than acknowledging growth; it requires understanding the nuanced drivers behind product preference, regional demand shifts, and the competitive tactics of key players.
PW Consulting's comprehensive study is designed to be the definitive resource for navigating these complexities. By leveraging the detailed findings within the full report, industry leaders can align their strategies with the actual market mechanics rather than assumptions. We invite you to access the complete intelligence package to ensure your 2026 decisions are backed by the most accurate and actionable data available.
For detailed analysis of this topic, please visit the official page: Worldwide Suspension Bridge Apparatus Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Deicing Salt Market Hits $2.7B in 2025, Rises to $3.45B by 2032 at 3.55% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Deicing Salt Market: A 2026 Outlook
Market Trajectory and Macroeconomic Context
The global deicing salt industry is entering a phase of measured but steady expansion, driven by recurring winter maintenance demands, infrastructure aging, and evolving regulatory frameworks across key geographies. According to the latest comprehensive assessment, the worldwide market reached approximately 2.7 billion USD in 2025, reflecting a consistent upward trajectory from the 2.27 billion USD recorded in 2020. Over the historical baseline period, revenue growth has been characterized by incremental volume gains, supply chain recalibration, and periodic cost pressures linked to energy markets and packaging logistics. Looking ahead, the forecast window through 2032 projects a cumulative valuation approaching 3.45 billion USD, supported by a compound annual growth rate of 3.55 percent.
This growth profile is neither explosive nor stagnant. It reflects an industry that has matured past the volatility of early-cycle commodity swings and now operates within a more predictable demand envelope. Municipal budgets, transportation authorities, and commercial facility managers continue to treat deicing salt as a non-negotiable operational input, even as they increasingly weigh environmental compliance, corrosion mitigation, and total lifecycle costs against unit pricing. For executive teams navigating procurement strategy, capacity planning, and geographic diversification in 2026, the macro trajectory provides a reliable foundation for medium-term forecasting. The exact valuation inflection points, regional contribution shifts, and application-specific demand curves are mapped in granular detail within the full report, enabling precise scenario modeling rather than reliance on broad industry heuristics.
Structural Drivers and Supply-Side Dynamics
Several interconnected forces are shaping the operational landscape for deicing salt producers and distributors. On the raw material side, underground mining operations have experienced meaningful cost escalation, with production expenses rising in the 8 to 12 percent range during 2024 due to higher energy consumption in subterranean extraction and hauling processes. Simultaneously, salt evaporation facilities in North America operated against natural gas price environments averaging around 3.50 USD per MMBtu in the fourth quarter of 2024, influencing the economics of solar and solution-based production pathways. These input cost dynamics are not uniform across all production methods, and they create divergent margin profiles depending on whether operators rely on deep-shaft mining, conventional solar evaporation, or blended chemical formulations.
On the regulatory front, compliance considerations are increasingly influencing product selection and procurement specifications. Environmental directives in Europe continue to limit chloride discharge from deicing applications into sensitive waterways, prompting municipalities and contractors to prioritize low-chloride alternatives in designated zones. In North America, environmental agencies have reinforced recommendations favoring magnesium chloride blends over pure sodium chloride to reduce infrastructure corrosion and ecological impact. Packaging and logistics costs have also been affected by trade policy adjustments, with certain container tariffs adding a measurable premium to imported packaged goods during 2024. These overlapping pressures are pushing buyers toward value-engineered specifications, blended formulations, and supplier partnerships that can demonstrate consistent quality, environmental documentation, and reliable winter-season delivery.
Competitive Landscape and Enterprise Positioning
The industry remains moderately fragmented, yet it is anchored by a cohort of scaled producers with integrated mining assets, evaporation facilities, and established distribution networks. Concentration metrics indicate that the top three participants collectively account for roughly 22.45 percent of total market revenue, while the top five extend their combined share to approximately 31.8 percent. This structure suggests that while large incumbents hold meaningful influence over pricing benchmarks, logistics standards, and product specifications, there remains sufficient room for regional specialists, niche blenders, and logistics-focused intermediaries to capture differentiated value.
Among the leading enterprises, Cargill stands out as the world's largest producer of deicing salt, supplying rock salt, solar salt, and treated products from mines and evaporation facilities across North America, Europe, and Asia, with a strong focus on both road and airport deicing applications. Morton Salt operates as a major supplier of rock salt and magnesium chloride-based products, drawing from underground mines in the United States and Canada and offering both bulk and packaged options tailored to highway maintenance programs. K+S has built a leading European position through rock salt production from mines in Germany and Poland, exporting to more than 100 countries and emphasizing anti-caking treated variants for broad operational compatibility. Compass Minerals manages the Goderich mine in Canada, recognized as North America's largest salt producer, and supplies treated rock salt alongside liquid brines to U.S. and Canadian markets. China National Salt Industry Corporation operates as a state-owned giant with massive coastal capacity, producing solar-evaporated salt for domestic deicing demand and export. Ineos Enterprises supplies rock salt from United Kingdom mines for winter road maintenance across Europe, including direct provisioning to national highways agencies. Cheetham Salt contributes Australian solar salt production for colder-region applications and exports into Asia-Pacific markets, while Sudsalz GmbH provides German rock salt from multiple underground sites to Central European customers.
Recent corporate activity underscores how incumbents are responding to the demand for capacity, product differentiation, and sustainability credentials. In late 2024, one major producer announced an expansion of deicing salt production at a Saskatchewan facility to align with North American demand expectations. Another key player introduced a treated deicing salt formulation with enhanced corrosion inhibition designed to protect infrastructure assets while maintaining deicing performance. A European operator meanwhile secured updated environmental certification for sustainable production practices at its German mining operations, signaling the growing importance of documented sustainability compliance in public-sector procurement. These moves illustrate a broader strategic theme: leaders are investing not only in volume but also in specification maturity, environmental documentation, and regional supply assurance.
Worldwide Deicing Salt Market
Segmentation Dynamics and Application Realities
The market's structure reveals clear hierarchy across product types, use cases, and geographic footprints. Rock salt continues to dominate the product mix, reflecting its cost efficiency, widespread availability, and long-standing acceptance among maintenance agencies. Magnesium chloride blends occupy a strategically important secondary position, gaining traction where corrosion concerns, temperature extremes, or environmental sensitivity make pure sodium chloride less desirable. A smaller but notable share of demand flows through alternative and specialty formulations that address specific operational requirements, including pre-wetting additives, treated variants, and liquid brine programs.
In terms of application, roadway and highway maintenance remains the dominant demand center, consistent with the scale of public infrastructure networks and the recurring need for winter roadway safety. Commercial and residential usage forms a substantial secondary segment, shaped by property management contracts, retail facility operations, and localized weather patterns. Industrial and utility facilities represent a more specialized demand pool, where deicing protocols are often integrated into broader asset-protection and operational continuity plans. Regional demand distribution is heavily influenced by climate exposure, municipal budgeting cycles, and transportation network density, with established northern markets sustaining consistent baseline consumption while certain emerging colder-region corridors show incremental uptake.
Ice Melter Market
Because segmentation outcomes are continually reshaped by weather variability, procurement specification changes, and local regulatory guidance, aggregate splits only tell part of the story. The full report decomposes these dynamics into actionable detail, highlighting where volume concentrations persist, where specification migration is underway, and how different product types interface with specific application requirements across regions.
Forward Outlook and Strategic Decision Levers for 2026
For organizations making procurement, pricing, and capacity decisions in 2026, the deicing salt market presents a set of clear strategic levers. First, cost management must account for the reality that energy-intensive extraction and evaporation pathways are exposed to volatile input pricing, while logistics and packaging components remain sensitive to trade policy and container availability. Second, specification strategy is increasingly decisive: buyers are evaluating blended formulations, treated products, and corrosion-mitigating options not simply as premium upgrades but as risk-management tools that can reduce long-term infrastructure maintenance exposure. Third, regional supply assurance is gaining importance as public agencies and large commercial operators prioritize reliable winter-season delivery, documented quality consistency, and environmental compliance records over narrow unit-price competition.
Growth over the forecast period will likely be shaped by incremental public-sector budget normalization, sustained investment in transportation network upkeep, and gradual specification shifts toward blends and treated variants in environmentally sensitive or corrosion-prone contexts. At the same time, regulatory continuity around chloride discharge, ongoing environmental recommendations favoring lower-impact formulations, and packaging cost pressures will continue to influence procurement behavior. Companies that can integrate production flexibility, specification documentation, and reliable distribution logistics will be best positioned to capture share in a market that rewards operational dependability as much as price competitiveness.
The complete Worldwide Deicing Salt Market research report translates these macro themes into detailed market sizing, segment trajectories, regional breakdowns, competitive profiling, and forward scenario analysis. It provides the structured intelligence needed to evaluate where demand is most durable, how product mix evolution may affect sourcing strategy, and which competitive moves are reshaping supply expectations across key geographies. For decision-makers requiring a precise basis for planning in 2026 and beyond, the full study offers the depth necessary to move beyond general market narratives and into executable, data-grounded strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Deicing Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Industrial Wiping Cloth Market to Reach $6.4 Billion by 2032 Growing at 5.15% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Industrial Wiping Cloth Sector: Navigating Growth Through 2032
The global landscape for industrial wiping solutions is undergoing a structural transformation, driven by the convergence of manufacturing expansion, evolving sustainability mandates, and the increasing technical demands of modern production environments. For strategic planners, procurement leaders, and market entry teams operating in 2026, understanding the trajectory of this sector requires more than headline revenue figures. It demands a rigorous examination of material science shifts, supply chain regionalization, application-specific performance requirements, and the competitive dynamics that will dictate margin structures over the next seven years. Our newly released Worldwide Industrial Wiping Cloth Market research study provides an exhaustive, data-grounded blueprint designed to equip decision-makers with the precision intelligence required to allocate capital, optimize sourcing strategies, and position portfolios ahead of market inflection points.
This article serves as a strategic overview of the market's current architecture and the analytical framework embedded within the full report. It highlights the macroeconomic trajectory, the structural forces reshaping supply and demand, the competitive archetypes defining the industry, and the practical analytical modules that enterprise teams can immediately deploy to stress-test operational assumptions. Readers seeking granular regional valuations, detailed sub-segment penetration rates, company-level capacity assessments, and scenario-modeled forecasts will find those deliverables comprehensively housed within the complete study, accessible through our research portal.
Microfiber Cleaning Cloths Market
Market Architecture and Long-Term Growth Trajectory
The global industrial wiping cloth market has demonstrated consistent expansion across the historical evaluation window, advancing from approximately 3.51 billion USD in 2020 to an estimated 4.52 billion USD by 2025. This upward trajectory reflects steady industrial activity, sustained maintenance and repair operations, and the ongoing replacement of legacy cleaning protocols with higher-performance, application-specific wiping media. The momentum carries into the forecast horizon, with the market projected to reach approximately 4.81 billion USD in 2026 and continue its expansion toward a projected valuation exceeding 6.4 billion USD by the close of 2032.
At the core of this projection sits a compound annual growth rate of 5.15 percent, a pace that underscores durable demand while also signaling meaningful variation across product architectures, end-use verticals, and geographic supply ecosystems. A growth rate at this level typically indicates that volume expansion is being supplemented by value migration toward engineered materials, specialized absorbency profiles, and compliance-driven formulations. For enterprises evaluating capacity investments, distribution partnerships, or product development roadmaps, this trajectory suggests that broad-based commodity positioning will increasingly struggle to preserve margin integrity against competitors leveraging material differentiation and application engineering.
The historical record from 2020 through 2025 also reveals the market's resilience through periods of supply chain disruption and shifting industrial output patterns. Rather than experiencing structural contraction, the sector adapted through material substitution, localized sourcing adjustments, and the accelerated adoption of nonwoven and microfiber alternatives where traditional woven or cotton-based formats faced cost or availability constraints. These adaptive behaviors have permanently altered procurement expectations, pushing industrial buyers to prioritize consistency, contamination control, and lifecycle cost over lowest unit price.
Segmentation Dynamics and Strategic Implications
The market's internal structure is defined by distinct product architectures, application requirements, and regional supply-demand balances. Understanding how these layers interact is essential for any organization attempting to forecast capacity needs, design premium product lines, or enter new distribution channels. Our study maps these layers in detail, but even at the strategic level, several structural patterns merit executive attention.
Product Architecture Evolution
Industrial wiping formats span non-woven constructions, woven and knitted cloth architectures, and microfiber-based solutions, each serving different performance thresholds, absorption profiles, and end-use tolerances. The non-woven category has gained substantial operational relevance due to its manufacturability, consistency, and adaptability to engineered treatments such as controlled linting, chemical resistance, and specialized absorbency. Woven and knitted cloths continue to occupy important niches where tensile durability and reusability are critical, particularly in environments where wiping media must withstand repeated mechanical stress. Microfiber formats, meanwhile, have expanded in applications demanding particulate capture, fine surface preparation, and controlled contamination management, especially in precision manufacturing and sensitive equipment maintenance.
From a strategic vantage point, the material mix is not simply a product preference question. It is a reflection of how industrial buyers weigh total cost of use, process contamination risk, disposal or laundering logistics, and regulatory compliance. Product architectures that can demonstrate verifiable performance consistency, reduced downstream contamination, and alignment with sustainability cascades are gaining purchasing preference in competitive procurement environments.
Application-Driven Demand Patterns
Industrial wiping consumption is dispersed across multiple high-activity verticals, with demand shaped by output volumes, cleanliness standards, and maintenance intensity. Automotive and aerospace operations require wiping media capable of handling lubricants, solvents, and precision surface preparation without introducing particulate or fiber contamination. General industrial manufacturing represents a broad-demand base where absorbency, durability, and bulk availability drive purchasing decisions. Electronics and semiconductors push the performance envelope further, requiring ultra-low-lint, controlled-environment-compatible formats that support stringent cleanliness protocols. Healthcare and life sciences impose their own compliance and contamination-control requirements, while food and beverage processing environments demand materials compatible with sanitary workflows and regulatory expectations.
The strategic implication is that a single product strategy cannot efficiently serve these application clusters. Instead, successful operators are aligning product specifications, packaging formats, and quality assurance protocols to the distinct risk and performance profiles of each vertical. Procurement organizations, in turn, are moving from transactional purchasing toward application-engineered sourcing, where the cost of failure, rework, or compliance deviation is factored into material selection.
Geographic Distribution of Demand and Supply
Regional market architecture reflects differences in industrial density, manufacturing specialization, procurement maturity, and logistics infrastructure. The global demand footprint is distributed across major production zones and consumption hubs, with North America, Europe, and Asia Pacific representing substantial share of activity, while Latin America and the Middle East and Africa contribute incremental but strategically important growth corridors. Regional divergence is not merely a matter of volume; it influences supplier proximity strategies, freight cost exposure, lead-time expectations, and the competitiveness of localized versus imported wiping solutions.
For enterprises planning network expansion, distribution partnerships, or sourcing diversification, regional analysis must go beyond aggregate consumption estimates. The meaningful questions involve where capacity is located relative to end-use clusters, how regulatory and sustainability expectations vary by market, and which applications are most sensitive to supply continuity. The full study provides structured regional assessments that enable these judgments without relying on broad generalizations.
Competitive Landscape and Strategic Positioning
The industrial wiping cloth sector is characterized by a mix of established manufacturers, specialized material engineers, regional distributors, and service-oriented rental and replacement models. Competitive intensity is shaped not only by pricing, but by product reliability, application expertise, supply reliability, and the ability to support compliance-driven procurement requirements. Market concentration metrics indicate a moderately fragmented structure, meaning that while leading participants command meaningful presence, a broad field of regional and niche operators continues to compete on specialization, service models, and customer intimacy.
Competitive Archetypes
Several company profiles illustrate the strategic diversity within the sector. Some participants compete as regional manufacturing and wholesale distribution leaders, building durable advantage through localized supply chains, broad rag and cloth assortments, and strong relationships across automotive, industrial, janitorial, and food service channels. Others position around engineered cleaning wipes designed for critical manufacturing environments and controlled operations, where consistency, cleanliness, and performance repeatability are non-negotiable. Additional players emphasize durability and absorbency for manufacturing, automotive, and general maintenance applications, while long-established manufacturers leverage multi-decade distribution networks and sanitized cloth expertise to serve industrial users with dependable bulk supplies and microfiber options.
A further competitive dimension includes manufacturers focused on nonwoven fabrics and heavy-duty applications, where product design targets grease handling, waste reduction, and operational efficiency. There are also suppliers whose wiping products integrate into broader spill-control and safety portfolios, aligning wiping performance with workplace hazard management. On the service side, certain European providers emphasize rental wipers and absorption mats with scheduled pickup and replacement, giving industrial customers access to consistent supply without bearing the full burden of inventory management and disposal logistics. These varied models demonstrate that competitive advantage in this market is not monolithic; it can emerge from material engineering, service design, regional scale, or application-specific trust.
Strategic Implications of Fragmentation and Consolidation Pressure
With a moderately fragmented market structure, larger players often compete by broadening product ranges, strengthening quality assurance, and deepening customer-facing support, while smaller operators survive by specializing in niche applications, regional logistics, or cost-efficient material flows. Over time, sustainability requirements, compliance complexity, and the growing demand for engineered formats may exert consolidation pressure, particularly where scale enhances quality control, R&D capability, and supply reliability. Conversely, fragmentation may persist where application specificity and localized service deliver more value than centralized volume production.
For buyers, this environment rewards supplier evaluation frameworks that weigh not just unit economics but also defect rates, contamination risk, replenishment reliability, and technical support. For suppliers, the path to durable positioning increasingly depends on demonstrating measurable performance value and building resilient, transparent supply relationships.
Industry Dynamics Shaping the 2026–2032 Horizon
The forward trajectory of industrial wiping solutions is influenced by several interlocking dynamics that extend beyond simple volume growth. These forces are reshaping product design priorities, procurement behavior, and competitive differentiation.
Material Science and Formulation Innovation
Industrial wiping media are commonly manufactured from a range of input materials including cotton rags, polyester-based constructions, nonwoven fabrics such as spunlace, airlay, and meltblown polypropylene, and recycled textile streams. The strategic significance of this material diversity lies in how each input affects absorbency, lint generation, chemical compatibility, rework risk, and end-of-life handling. As manufacturing processes become more precise and sensitive, the performance expectations for wiping media rise accordingly, encouraging innovation in fiber selection, web formation, and treatment technologies.
Innovation is also being accelerated by industry gatherings and technical exchange forums where material developers, manufacturers, and end-users discuss advances in wipes materials, formulations, sustainability, and manufacturing technologies. These conversations are not merely promotional; they reflect real pressure on suppliers to improve consistency, reduce waste, and adapt products to stricter operational environments.
Sustainability, Circularity, and Procurement Expectations
Sustainability considerations are becoming integral to industrial wiping procurement rather than peripheral concerns. Recycled fabrics derived from post-consumer clothing are frequently cascaded into lower-value applications such as wiping cloths in manufacturing and custodial work, an approach that aligns with broader circular economy objectives while also offering cost and resource efficiency advantages. This cascading model creates both opportunities and challenges: it can lower input cost volatility and support ESG narratives, but it also requires careful quality control to ensure that material consistency and performance reliability are not compromised.
As corporate sustainability commitments deepen, buyers are increasingly attentive to lifecycle impact, material traceability, and the alignment of wiping products with broader waste-reduction and resource-efficiency goals. Suppliers that can document responsible sourcing, product durability, and appropriate end-of-life pathways are better positioned to participate in competitively evaluated procurement processes.
Regulatory Attention and Standards-Driven Quality Expectations
Industrial wipers and wipes are subject to ongoing scrutiny related to sustainability, advanced formulations, manufacturing technologies, and application-specific performance expectations. This scrutiny is reinforced through dedicated industry conferences and technical discourse that keep regulatory, compliance, and quality considerations in active focus. While wiping products may not always face the same regulatory intensity as direct-contact hygiene goods, their role in contamination control, chemical handling, and workplace safety ensures that quality standards, documentation, and process control remain strategically important.
For high-value applications in electronics, aerospace, and controlled manufacturing environments, compliance-adjacent expectations can materially influence purchasing decisions. Even where formal regulatory exposure is limited, customer audit requirements and internal quality systems often raise the effective bar for material consistency and documentation.
Worldwide Industrial Wiping Cloth Market
Macro Demand Support from Industrial Activity
Demand for industrial wiping solutions is supported by growth in manufacturing, automotive, metalworking, and maintenance sectors that require absorbent and durable cleaning materials. These sectors generate recurring consumption through routine maintenance, line changeovers, equipment servicing, spill management, and process cleanliness requirements. As industrial output expands and operating standards tighten, the demand for reliable wiping media becomes more structural rather than cyclical. This dynamic provides a foundational reason for the sector's long-term growth profile, but it also means that competitive success will depend on aligning product offerings with the specific operational rhythms and cleanliness demands of each vertical.
What the Worldwide Industrial Wiping Cloth Market Report Delivers
Our research study is designed to convert broad industry context into actionable strategic intelligence. It brings together historical performance data, forward projections, segmentation analysis, competitive profiling, and market dynamic assessment in a structured format that supports planning across multiple functional domains. The report is built for teams that need to make defensible decisions about product development, sourcing, capacity planning, market entry, and competitive positioning.
Core Analytical Modules
The study includes:
- Macro market sizing and growth projections extending from the base year through the forecast horizon, providing a consistent reference frame for revenue planning and investment appraisal.
- Detailed product-type analysis that examines the structural role of nonwoven, woven and knitted, and microfiber formats, including their performance positioning and commercial significance.
- Application-based assessment covering automotive and aerospace, general industrial manufacturing, electronics and semiconductors, healthcare and life sciences, and food and beverage processing, with focus on the distinct demand drivers and performance requirements within each vertical.
- Regional market evaluation that maps demand distribution and supply context across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, enabling geographic prioritization and sourcing strategy calibration.
- Competitive landscape profiling for key participants, including company capabilities, market orientation, and strategic positioning across manufacturing, distribution, engineered-wipe development, and rental or service-oriented models.
- Industry dynamics analysis covering materials, sustainability and circular economy practices, regulatory and standards-related expectations, and macro demand drivers linked to manufacturing, automotive, metalworking, and maintenance activity.
- Recent industry event and innovation context, including major trade shows and technical conferences shaping product development and market dialogue around wipes materials, formulations, sustainability, and manufacturing technologies.
Decision-Use Cases
The report is intended to support a range of high-value decisions, including:
- Evaluating whether to expand, consolidate, or reposition wiping product portfolios in response to material innovation and application-specific demand shifts.
- Assessing supplier selection criteria beyond unit price, particularly where contamination control, consistency, and compliance expectations influence total cost of ownership.
- Identifying regional opportunities where demand growth, industrial density, or supply gaps create favorable conditions for distribution expansion or local manufacturing.
- Understanding how sustainability expectations and recycled-material cascading may affect input sourcing, product positioning, and customer acceptance.
- Benchmarking competitive exposure by examining how different players compete on engineering, service, scale, specialization, and application trust.
- Informing capacity and inventory planning by integrating historical trend patterns with forward growth projections and segment-specific momentum.
Why This Study Matters for 2026 Decision-Making
The 2026 decision environment is defined by heightened attention to supply resilience, material performance, cost control, and sustainability alignment. In this context, industrial wiping cloths are not merely consumable inputs; they are process enablers whose selection can influence cleanliness outcomes, operational efficiency, compliance exposure, and downstream risk. Executives who treat wiping procurement and product strategy as purely tactical may miss the strategic implications of material migration, application engineering, and competitive specialization.
This study provides the evidentiary foundation needed to make more precise judgments. It links market size and growth rate to the structural factors that actually drive value migration, including product architecture, vertical-specific requirements, regional supply context, and competitive differentiation. By combining quantitative trajectory data with qualitative analysis of industry dynamics and company strategies, the report enables readers to test assumptions, prioritize initiatives, and anticipate where performance and compliance expectations will intensify.
The study also recognizes that detailed numbers matter, but only when interpreted within the right strategic frame. Aggregate growth is useful for headline planning; segment-specific insights are essential for portfolio architecture; regional breakdowns are critical for sourcing and distribution design; and competitive profiles are necessary for positioning and negotiation strategy. The full report integrates these layers into a coherent decision-support system rather than a static data table.
Accessing the Full Intelligence Package
Organizations that require detailed sub-segment analysis, regional revenue context, company-level competitive assessment, and forecast frameworks for planning cycles will find the complete study structured to support that depth. The full report is available through our research platform, where teams can access the comprehensive dataset, analytical commentary, and strategic frameworks needed for detailed internal review.
For strategy, procurement, operations, and commercial teams preparing for the 2026–2032 period, the Worldwide Industrial Wiping Cloth Market study offers a disciplined, evidence-based pathway to better-informed decisions. In a market where material performance, sustainability expectations, and application-specific requirements increasingly determine competitive outcomes, the ability to ground strategy in rigorous market intelligence is not optional. It is a core capability for sustainable growth.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Wiping Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Copper Hollow Conductors Market to Reach $403.9M by 2032, CAGR 5.49%
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Copper Hollow Conductors Market Through 2032
The copper hollow conductor sector is navigating a period of structural expansion shaped by electrical infrastructure modernization, medical equipment upgrading, and advanced thermal management requirements. Our latest Worldwide Copper Hollow Conductors Market study is designed to translate this evolving landscape into executable strategy for executives who need to allocate capital, plan capacity, and sharpen competitive positioning through 2032.
The report combines historical reconstruction, demand forecasting, and competitive profiling into a single decision framework. It is built for leaders who require more than top-line figures, offering a structured view of where capacity is expanding, where pricing power is shifting, and how leading manufacturers are differentiating in a moderately concentrated market.
Global Market Trajectory and 2026 Decision Context
The worldwide market for copper hollow conductors is estimated at approximately 277.65 million USD in 2025, reflecting sustained demand momentum after the 2020 to 2025 historical window. Over that period, the market grew from 212.45 million USD in 2020 to 277.65 million USD in 2025, with year-to-year movement shaped by project timing, regional capacity adjustments, and demand variability across industrial and high-technology end-use sectors.
Looking ahead, the market is projected to move from 288.24 million USD in 2026 toward 403.9 million USD by 2032, supported by a forecast CAGR of 5.49 percent. This growth path is not uniform across years or segments, and the report explains where growth is likely to be more resilient versus where it may be more sensitive to capital spending cycles, procurement timing, and raw material volatility.
For 2026 planning teams, the value of the study lies in disentangling short-term price noise from underlying demand structure. The market outlook is placed against a backdrop of pronounced copper price variability, including periods of elevated pricing that have tested margins and procurement strategies. The report shows how demand patterns across key end-use categories continue to shape order books and capacity utilization even as input costs fluctuate.
What the Study Covers and How It Supports Execution
This research is structured as a practical reference for strategy, sales, procurement, and operations teams. Instead of presenting abstract trends, it links market sizing to the operational realities that determine competitive outcomes. The study breaks the market into logical segments and analyzes demand behavior, product preferences, and regional development patterns without relying on oversimplified snapshots.
Key areas included in the report are:
- Market sizing for the historical period from 2020 through 2025 and forecasts across the 2026 to 2032 window
- Segment-level analysis by product form, including rectangular hollow conductors, square hollow conductors, and circular and other profiles
- Application-level analysis spanning power generation and transmission, medical imaging for MRI systems, industrial induction heating, and high-energy physics research
- Regional analysis covering Asia Pacific, Europe, North America, and the Rest of the World
- Competitive assessment of leading manufacturers, including headquarters location, product capabilities, and strategic focus areas
- Recent corporate developments, product emphasis updates, and industry initiatives that signal changing priorities
- Contextual analysis of market concentration, cost dynamics, and procurement considerations relevant to sourcing and pricing decisions
A central strength of the study is its focus on how segment dynamics interact. For example, demand for precision hollow conductors in specialized magnetic and thermal applications does not behave the same way as demand from broader electrical and industrial procurement channels. The report examines these differences qualitatively and quantitatively, helping readers understand which applications are likely to be more recession-resilient, which are tied to project cycles, and which are expanding due to technological upgrade activity.
Segment Structure and Demand Drivers
The market is organized around product geometry, application requirements, and regional demand conditions. These dimensions matter because they influence tooling requirements, manufacturing complexity, lead times, and end-customer expectations. Rectangular and square hollow conductors, for instance, are closely associated with specific coil and cooling configurations, while circular and other profiles serve different mechanical and electrical design needs.
The report also examines application demand in detail. Power generation and transmission continues to be a central demand area, reflecting the importance of conductors in electrical systems where performance, reliability, and thermal management are critical. Medical imaging, especially MRI applications, represents another high-value demand stream where precision and consistency can be decisive in supplier selection. Industrial induction heating adds further volume, driven by manufacturing process needs and energy-intensive production environments. High-energy physics research, while smaller in overall scale, contributes to demand for highly specialized conductor formats with stringent specification requirements.
Rather than presenting these categories as static silos, the report explores how they compete for capacity, how procurement priorities differ among end-users, and how manufacturers balance customization against volume efficiency. This perspective is particularly important for companies evaluating whether to invest in flexible production capabilities or to focus on standardized high-volume formats.
Competitive Landscape and Manufacturer Positioning
The competitive environment is moderately concentrated, with the top three companies accounting for approximately 42.5 percent of market revenue and the top five reaching around 58.2 percent. That concentration pattern indicates that scale, relationships, and product specialization still provide meaningful advantages, even though regional manufacturing footprints and customization capabilities create opportunities for a broader set of suppliers.
The study profiles the principal companies shaping the market and evaluates their strategic positioning. Luvata, headquartered in Pori, Finland, is recognized for custom-made copper hollow conductors for high magnetic field applications, including MRI scanners, electric vehicle stator direct cooling, power generators, and induction furnaces. Its offering emphasizes a wide range of tooling options across shapes and sizes, which supports shorter lead times for specialized orders.
KME, based in Germany, operates as a major European manufacturer of copper and copper alloy products, including bars, profiles, and hollow conductors for industrial and electrical applications. Its multi-plant footprint across Europe, Asia, and the USA gives it a broad production and distribution base capable of serving demanding customer requirements in multiple markets.
Proterial Metals, Ltd., formerly Hitachi Metals and headquartered in Japan, produces copper bar, rod, formed bars, and hollow conductors using tough pitch copper C1100. Its product set supports magnetic field coils for generators, particle accelerators, rectifiers, and heating furnaces, aligning it with applications that require reliable electromagnetic and thermal performance.
cunova, also based in Germany, is a leading producer of copper bars and sections, including solid and hollow sections manufactured with modern machinery for industrial applications. Its focus on section quality and production precision positions it in a segment where tolerance control and consistent output are important differentiators.
Fabmann, based in China, manufactures high-quality custom copper and copper alloy hollow conductors with complex to standard profile shapes, tight tolerances, and internally cooled channels. In addition to hollow conductor products, it offers edge wound and form wound coils, broadening its relevance in applications that require integrated component solutions.
Oriental Copper, headquartered in Thailand, produces copper hollow conductors through extrusion and drawing processes, delivering shiny smooth surfaces suitable for further machining and different cross-sections. Its process emphasis supports downstream manufacturing needs where surface finish and form consistency matter.
Extube, based in India, manufactures hollow conductors from high-conductivity oxygen-free copper with electrical conductivity of at least 100 percent IACS for demanding applications. This focus on material purity and conductivity targets end-use cases where performance margins are narrow and specification adherence is critical.
S&W Wire Co., operating in the United States, offers seamless high-purity hollow conductor tubing for electrical applications requiring water-cooled conductors and high thermal conductivity. Its product emphasis reflects the needs of systems where cooling, purity, and structural integrity must be managed together.
Channel Metal, also known as Zhangjiagang Channel Int'l Co., Ltd. and based in China, supplies customized hollow copper conductor tubes, including microwave hollow conductors in straight lengths, coils, and spools for magnet and electric industries. Its offering illustrates how customized formats continue to matter across specialty markets.
Steel Hollow Section Market
The report evaluates these companies not just as a roster of competitors, but as examples of different strategic plays. Some compete through customization and short lead times, others through material specification, while others rely on geographic reach, integrated coil supply, or process expertise. Understanding these positioning differences helps buyers and competitors anticipate where pricing pressure will emerge and where service value can support margin defense.
Recent Developments and Strategic Signals
Recent industry activity reinforces the importance of operational innovation and application-specific focus. In May 2025, KME published results from its BMBF research project KUPFERDIGITAL 2 on data collection along the production chain for copper and copper alloy connectors. This initiative highlights a broader industry push toward better data, traceability, and chain-wide process visibility, which can influence procurement confidence and manufacturing efficiency over time.
In March 2024, Luvata emphasized high-quality hollow conductors specifically for induction furnaces, underscoring the importance of shape and size options for demanding thermal and electrical performance. Moves like these matter because they show where suppliers are investing attention and where application-specific engineering is becoming a competitive advantage rather than a supplementary service.
These updates are placed in context within the report, allowing readers to interpret corporate announcements not as isolated events but as indicators of shifting product emphasis, market targeting, and operational priorities.
Raw Material Volatility and Market Dynamics
One of the most important decision challenges in this market is managing input cost variability while maintaining supply reliability. Copper prices reached record levels above 14,500 USD per metric tonne in January 2026 before moderating, with COMEX cash spot levels moving in the range of roughly 5.87 to 5.92 USD per pound by late April 2026. That kind of movement has direct implications for quotation strategies, inventory planning, and customer negotiations.
Looking at forward expectations, J.P. Morgan has forecast LME copper prices in the range of 11,600 to 13,500 USD per tonne across 2026 quarters, reflecting the influence of supply-demand dynamics on the pricing outlook. At the same time, IEA analysis has noted that despite record copper prices in early 2026, treatment and refining charges for smelters fell to all-time lows, placing pressure on the midstream sector. This combination of high headline prices and squeezed downstream economics is highly relevant for hollow conductor producers and their customers, because cost structures do not always move in lockstep with spot quotes.
The report also addresses the broader demand environment. Global copper markets experienced meaningful volatility as prices rose through 2025 into 2026, driven by electrification, AI-related data center activity, and power infrastructure demand. For copper hollow conductors, these forces matter indirectly and directly: electrification and power infrastructure affect demand for electrical components, while broader copper market conditions influence procurement confidence, project timing, and supplier negotiation dynamics.
By integrating these material dynamics with demand forecasts and competitive analysis, the study helps decision-makers separate cyclical price turbulence from structural opportunity. That distinction is essential for capacity planning, long-term contracting, and investment prioritization.
Strategic Value for 2026 and Beyond
This report is designed for organizations that need a rigorous, market-wide view without losing sight of operational detail. It supports several key decisions, including where to expand or consolidate product offerings, how to benchmark against leading competitors, which geographic markets deserve closer attention, and how to respond to raw material cycles without compromising service quality.
It is equally useful for buyers and suppliers. Procurement teams can use the analysis to evaluate where customization, purity, lead time, or regional availability creates real value. Manufacturers and investors can use it to assess demand durability across applications, identify where concentration creates pricing or capacity constraints, and recognize which competitive capabilities are becoming more important as the market matures.
Because the research is built around both historical evidence and a 2026 to 2032 outlook, it provides a basis for planning that is anchored in actual market movement rather than guesswork. The forecast period is long enough to be strategically useful, but the report also pays close attention to the near-term signals that shape 2026 decisions.
Conclusion: Why This Study Matters Now
The Worldwide Copper Hollow Conductors Market is entering a phase in which growth potential, competition, and input cost volatility all require more sophisticated planning than in prior years. The convergence of electrification trends, specialized medical and industrial demand, and a moderately concentrated supplier base means that competitive advantage will increasingly depend on product precision, manufacturing flexibility, regional reach, and informed procurement strategy.
Worldwide Copper Hollow Conductors Market
This study offers a comprehensive but actionable view of that environment. It gives executives the context needed to interpret market movement, evaluate competitors, and make better-informed decisions about product focus, sourcing, and growth timing. Its strength lies in combining market-level data with a practical understanding of how manufacturers and end-users actually compete and buy.
For a full assessment of segment dynamics, regional demand patterns, application-level growth coverage, and detailed competitive intelligence, the complete report provides the deeper data and analysis needed to support high-stakes strategy decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Copper Hollow Conductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide IR Carbon Sulphur Analyzer Market Hits $485.5M in 2025, Projected 4.85% CAGR to $676.36M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Growth Cycle: Inside the Worldwide IR Carbon Sulphur Analyzers Market Research
Decision-makers operating at the intersection of materials science, industrial quality control, and instrument procurement face a growing strategic imperative. As environmental compliance tightens, high-purity material specifications become non-negotiable across metals, ceramics, and battery supply chains, the analytical instruments that quantify carbon and sulfur at trace levels are no longer peripheral lab tools. They are mission-critical gatekeepers of yield, certification, and process stability. Our latest Worldwide IR Carbon Sulphur Analyzers Market research delivers a structured, forward-looking intelligence framework designed specifically for enterprise planning through 2032. Rather than offering static snapshots, the study maps the structural forces, competitive maneuvers, and application-driven demand shifts that will shape purchasing strategies, R&D allocation, and geographic expansion in the coming years.
The overarching trajectory is clear: the global market has matured into a phase of steady, compounding expansion. From a baseline established in the early 2020s, revenue has logged consistent upward movement, crossing the half-billion-dollar threshold as industrial laboratories and production facilities synchronize their analytical capabilities with stricter material specifications. The research anchors this evolution in a rigorous historical-to-forecast architecture, tracing validated market performance across recent years and projecting a stable, mid-single-digit growth rate through the end of the decade. This cadence reflects more than incremental replacement cycles. It signals deepening integration of infrared detection-based combustion analyzers into routine quality workflows, particularly where rapid, repeatable carbon and sulfur quantification directly informs metallurgical grade control, refractory compliance, and mineral processing economics.
What separates this study from conventional sizing exercises is its emphasis on decision-ready architecture. The report does not merely aggregate figures. It decomposes the market into actionable dimensions that align with procurement, product strategy, and regional operations. Readers will find a detailed instrument-type breakdown that contrasts high-frequency induction furnace analyzers with resistance furnace platforms, highlighting the operational trade-offs that purchasing committees and engineering leads weigh when standardizing analytical suites. Application-level analysis isolates the demand engines across steel and metallurgy, mining and minerals, ceramics and glass, aerospace and automotive, and broader industrial laboratory environments, showing how material throughput, certification requirements, and sampling intensity differ by sector. A regional lens completes the picture, revealing how mature industrial hubs and high-growth manufacturing corridors diverge in adoption velocity, service infrastructure, and channel dynamics.
Equally critical is the research’s focus on the physical and consumable architecture that underpins analytical reliability. The study examines how ceramic crucibles, high-purity tungsten and tungsten-tin blend accelerators, and mesh-specific combustion aids form a recurring demand layer that accompanies analyzer installations. These inputs are not ancillary. They determine combustion completeness, detection stability, and consumable procurement cycles across leading instrument ecosystems. By mapping these dependencies alongside the core hardware footprint, the report equips operations leaders with a fuller understanding of total cost of ownership, supply continuity, and service-level expectations.
The competitive landscape analysis is structured to expose strategic positioning rather than simply roster participants. The study profiles a concentrated field of internationally recognized instrument manufacturers, each pursuing distinct value propositions across inorganic and organic matrices. Japanese, German, American, British, Canadian, and Chinese players appear with differentiated portfolio strategies: some emphasize entry-level accessibility and throughput scalability, others push flagship precision for demanding alloy and catalyst workflows, while several have extended platform versatility through dual-furnace architectures or specialized organic-sample configurations. The research also tracks recent product and application developments that illustrate how vendors are aligning with emerging quality-control priorities. Updated documentation emphasizing reliability and improved sample handling, expansions into complementary elemental analyzers, and targeted application messaging around cement raw-material control demonstrate a market where vendors are increasingly bridging instrument performance with specific industrial process needs.
Market structure analysis further illuminates how concentration shapes purchasing leverage, channel relationships, and innovation pacing. With a consolidated share held by a limited set of established vendors, the research examines how incumbency advantages in service networks, application support, and consumable ecosystems intersect with entry points for specialized or region-focused competitors. This concentration dynamic carries direct implications for negotiation strategy, qualification roadmaps, and risk diversification. Procurement leaders can use the findings to evaluate whether standardization around a narrow vendor set delivers service efficiencies, or whether a multi-platform approach better matches the heterogeneity of sample matrices across plants and laboratories.
Combustion Analyzer Market
Beyond sizing and share, the report delivers an operational content suite built for cross-functional use. Market participants, investors, and strategy teams will encounter detailed segmentation narratives, competitive capability comparisons, and scenario-aware forecasts that connect instrument adoption to broader industrial trends. The study traces how detection reliability, heating and filter architectures, and user-centric workflow design influence adoption in environments where moist samples, variable matrices, and high-throughput requirements converge. It also contextualizes how evolving application focus areas such as battery-related material testing, cement process control, and high-purity alloy certification are reshaping demand patterns beyond traditional metallurgical baselines. By linking hardware characteristics, consumable dependencies, and application priorities into a single analytical frame, the research enables teams to translate market movement into concrete sourcing strategies, product planning assumptions, and regional execution priorities.
For enterprise strategists, the practical value of this research lies in its ability to convert macro momentum into allocation intelligence. The stable growth trajectory and application-driven demand diversification indicate that purchasing decisions will increasingly hinge on alignment with specific material workflows, service responsiveness, and consumable supply resilience rather than price alone. The study’s segmentation and competitive modules provide a structured way to evaluate where incremental capacity should be deployed, how vendor relationships should be configured, and which application segments warrant closer monitoring as quality specifications evolve. Because the full report contains granular split-level data, detailed regional and application contributions, and precise competitive benchmarks that are essential for modeling and scenario planning, organizations are encouraged to access the complete study directly on the source webpage. There, procurement, R&D, and business development teams can retrieve the segmented figures, company-level profiles, and forecast tables needed to embed this intelligence into formal decision workflows.
Worldwide IR Carbon Sulphur Analyzers Market
Ultimately, this market research is designed to function as a strategic compass, not a static reference document. The worldwide IR Carbon Sulphur Analyzers market is moving through a period where analytical precision, workflow efficiency, and supply-chain reliability are becoming inseparable from competitive performance in materials-intensive industries. By combining historical validation, structured segmentation, competitive intelligence, and forward-looking scenario framing, the study gives decision-makers a disciplined view of where demand is forming, how vendors are positioning, and what operational dependencies will shape adoption. For teams that require complete segment-level data, detailed regional contributions, and full competitive benchmarks to support budgeting, sourcing, and product strategy, the comprehensive report is available through our official market research portal, where the full intelligence architecture can be reviewed and integrated into enterprise planning processes.
For detailed analysis of this topic, please visit the official page: Worldwide IR Carbon Sulphur Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ZDBC Market to Hit $602.82M by 2032, 5.12% CAGR Through 2032; Asia Pacific Leads
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Rubber Accelerator BZ (ZDBC) Market: Navigating the 2026–2032 Growth Cycle
In the rapidly evolving landscape of specialty chemicals, the rubber accelerator sector remains a critical enabler of manufacturing efficiency, material durability, and regulatory compliance. As industrial demand shifts toward high-performance vulcanization solutions, organizations operating across latex, tire, and industrial rubber supply chains require more than surface-level forecasts. PW Consulting’s latest Worldwide Rubber Accelerator BZ (ZDBC) Market study delivers the analytical rigor necessary to shape sourcing strategies, capacity planning, and competitive positioning through 2032. This overview outlines the report’s strategic foundation, market architecture, competitive dynamics, and operational insights, while preserving the granular intelligence that decision-makers will uncover in the full publication.
Market Trajectory and the 2026 Decision Window
The current market environment reflects a decade of measured but compounding growth, driven by sustained demand from downstream manufacturing and strategic product substitutions in vulcanization chemistry. Our historical analysis captures revenue progression from the early 2020s through the 2025 base year, establishing a clear trajectory that informs near-term procurement and investment decisions. The 2026 forecast period marks a pivotal inflection point, where consolidation patterns, feedstock pricing dynamics, and regional capability maturation begin to reshape procurement benchmarks and margin expectations.
By projecting forward through the end of the decade, the study maps how accelerated adoption of advanced accelerator formulations intersects with shifting production footprints. The compound annual growth rate across the forecast horizon reflects durable end-use demand and the incremental expansion of precision-grade accelerator offerings. Rather than presenting static snapshots, the analysis emphasizes momentum indicators, capacity utilization signals, and pricing elasticity patterns that procurement leaders and strategic planners can translate into operating models. The full report expands on this trajectory with scenario-based adjustments, enabling clients to test sensitivity around feedstock availability, regulatory timelines, and regional demand intensity.
Report Architecture: Translating Data into Operational Decisions
A high-quality market study is valuable only when it converts macro signals into executable intelligence. This publication is structured to support cross-functional teams, from procurement and R&D to sales strategy and corporate development. It begins with a comprehensive market sizing framework that aligns historical performance with forward-looking revenue pathways, then moves into segmentation design that reflects how buyers actually specify accelerator forms, applications, and regional supply arrangements.
Worldwide Rubber Accelerator BZ (ZDBC) Market
The report includes detailed profiling of product forms and application pathways, allowing readers to understand which specifications dominate procurement cycles and where performance-driven substitutions are gaining traction. Instead of presenting isolated tables, the analysis weaves volume and revenue considerations into a unified view of market structure, revealing where concentration is intensifying and where fragmentation creates negotiation opportunities. The study also incorporates a dedicated competitive section that evaluates how leading manufacturers differentiate through form design, certification portfolios, regional service networks, and application-specific technical support.
Decision-makers will find practical tools throughout the document, including supply-side capability maps, procurement sensitivity considerations, and segment-level commentary that highlights where demand is becoming more specification-sensitive. The full version extends this architecture with deeper regional demand breakdowns, application-level revenue distributions, and form-factor comparisons that are essential for detailed sourcing models and commercial forecasting.
Regional and Segmentation Dynamics Without the Noise
Effective strategy requires understanding where value is created and captured across the supply chain. In this market, regional demand patterns are shaped by manufacturing density, downstream rubber consumption, and the localization of specialty chemical production. Asia Pacific continues to represent a substantial share of total market activity, reflecting the scale of regional rubber processing and the proximity of accelerator production assets to end-user clusters. Europe and North America contribute sizable but more specialized demand, often characterized by stricter specification requirements, compliance-driven sourcing, and premium-grade product preferences. Latin America and the Middle East and Africa region account for smaller but strategically relevant volumes, where infrastructure development and selective industrial expansion can create localized demand pockets.
On the product side, form factors matter significantly because they influence handling, dispersion, dosing precision, and compatibility with downstream processing lines. Powder and granular formats remain central to many compounding workflows, while oiled variants and masterbatch offerings address the growing need for pre-dispersed convenience, reduced contamination risk, and improved mixing consistency. The balance among these forms is shifting as manufacturers seek operational efficiencies and as suppliers invest in formulations tailored to specific rubber systems.
Application diversity further shapes purchasing behavior. Latex-based products, automotive tires, industrial rubber goods, footwear, and other end uses each impose different performance requirements and regulatory expectations. Tire production and latex manufacturing remain particularly influential in driving specification standards, especially where cure speed, scorch safety, and emissions-related considerations matter most. The complete report unpacks the revenue contributions by region, form, and application in greater detail, giving clients the comparative baselines they need to validate internal assumptions and refine category strategies.
Rubber Antioxidant Market
Competitive Landscape: Capability, Positioning, and Strategic Differentiation
The competitive field is defined by a blend of established specialty chemical producers, regionally anchored manufacturers, and suppliers focused on application-specific formulations. Western Reserve Chemical stands out for its WESTCO ZDBC offering, which is positioned around fast cures at low temperatures for natural and synthetic rubber and latex compounds, reinforcing its relevance in performance-driven compounding. Akrochem Corporation contributes both standard accelerator offerings and polymeric masterbatch solutions, such as its Akroform ZDBC-75/EPR/P line, extending its reach into EPDM and broader rubber applications where dispersion quality and polymer compatibility are priorities.
Global specialty chemical producers like Lanxess AG reinforce the market’s premium segment by emphasizing high-quality ZDBC solutions for vulcanization, supported by broader technical service and distribution networks. In China, large-scale producers such as China Sunsine Chemical Holdings underscore the importance of capacity scale and integrated supply capabilities in shaping regional pricing and availability. Additional manufacturers, including Taizhou Huangyan Donghai Chemical, Ningbo Actmix Rubber Chemicals, Shandong Stair Chemical & Technology, Willing New Materials Technology, Wellt Chemicals, Dalian Richon Chem, NOCIL Limited, Henan Kailun Chemical, and Shandong Yanggu Huatai Chemical, illustrate the breadth of technical focus across powder, granule, and masterbatch formats, as well as the increasing role of certification, consistency, and application coverage in competitive differentiation.
Recent developments highlight how competitors are actively reshaping market access and product positioning. In early 2026, ChemCeed partnered with PMI to introduce a high-performance rubber accelerator and antioxidant line for the U.S. market, including dithiocarbamate options such as ZDBC. This type of move signals continued interest in bundled performance portfolios and regional market entry strategies. Around the same time, Western Reserve Chemical reinforced its supply credibility through ISO 9001:2015 certification coverage extending into 2028, demonstrating how quality management and process reliability remain differentiators in procurement decisions. The full report provides a more complete competitive assessment, including positioning maps, service model nuances, and implications for sourcing strategy.
Market Drivers, Regulatory Forces, and Structural Risks
ZDBC demand does not evolve in isolation; it reflects a web of feedstock dependencies, compliance pressures, and downstream performance requirements. One of the most important structural inputs is zinc oxide, which serves not only as a key production feedstock but also as an activator in cross-linking during vulcanization. Fluctuations in zinc oxide availability and pricing can therefore influence both manufacturing costs and formulation economics, making feedstock awareness an essential part of strategic planning.
Regulatory considerations are equally influential. In the European Union, ZDBC falls under REACH frameworks governing chemical registration, evaluation, authorization, and restriction. This creates a compliance layer that affects product registration, documentation, and market access, especially for suppliers operating across multiple jurisdictions. At the same time, workplace safety and emissions-related expectations are accelerating the shift toward low-nitrosamine accelerators in tire and latex production. ZDBC’s role within that transition makes it relevant not only as a curing agent but also as part of a broader regulatory-response strategy for manufacturers seeking to align with evolving standards.
These dynamics introduce both opportunity and risk. On the opportunity side, demand for compliant, high-performance accelerators can support premium positioning and long-term supply agreements. On the risk side, regulatory timelines, feedstock variability, and specification tightening can disrupt procurement schedules and margin planning. The report evaluates these forces together, helping readers identify where resilience can be built through supplier diversification, formulation flexibility, and proactive compliance management.
Strategic Takeaways for 2026 and Beyond
For organizations making 2026 sourcing, capacity, and product strategy decisions, the central message is that ZDBC is not a commoditized input with a single buying rule. It is a specification-sensitive material whose value depends on form, application fit, regional compliance context, and supplier reliability. Procurement teams should evaluate not only price but also dispersion performance, masterbatch convenience, certification status, and technical support capability. R&D and production groups should consider how accelerator selection influences cure behavior, process safety, and regulatory alignment. Commercial leaders should track where consolidation, capacity expansion, and product-line launches are likely to alter supply availability and competitive intensity.
The most effective decisions will come from connecting these elements into a single strategic view. That requires market sizing that reflects real procurement patterns, segmentation that mirrors buyer behavior, and competitive analysis that explains how manufacturers create and defend advantage. This study is designed to provide that connective tissue, while leaving the most detailed revenue splits, regional contributions, and form- and application-level distributions for the full report, where they can be used directly in planning models.
Conclusion: Where Deep Intelligence Meets Actionable Strategy
The Worldwide Rubber Accelerator BZ (ZDBC) Market study from PW Consulting is built for leaders who need more than headline growth figures. It offers a disciplined look at how the market is structured, where competitive pressure is intensifying, how regulatory and feedstock realities shape supply, and what decision-makers should prioritize as they move through 2026 and beyond. By integrating historical performance, forward projections, segmentation logic, and competitive context, the report creates a foundation for sourcing strategy, product planning, and commercial execution.
To access the complete regional and application breakdowns, form-factor revenue distributions, concentration analysis, and full competitor profiles, readers are encouraged to explore the full market research on the PW Consulting website. The detailed intelligence within the publication is designed to be directly actionable, giving teams the specificity they need to convert market insight into confident strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Rubber Accelerator BZ (ZDBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com